
 Global Wind Turbine Operations Market | 2026-2036
Global Wind Turbine Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind Turbine Operations Market Outlook
Premium offshore operations is decoupling from commodity onshore maintenance on the basis of vessel requirements, technician certification depth, and remote monitoring infrastructure. Siemens Gamesa Renewable Energy dominates European offshore service with captive vessel fleets and dedicated harbor facilities. Goldwind leverages its domestic scale to anchor low-cost maintenance networks across China's northern wind corridors. Vestas competes through predictive analytics platforms that extend turbine availability guarantees beyond standard OEM terms.
Wind turbine operations encompasses the full lifecycle management of installed wind energy assets, including scheduled maintenance of drivetrain components operating at 1,500-3,000 RPM, blade inspection using rope-access and drone-based methods, and performance optimization through pitch and yaw control adjustments to maximize energy capture per swept area. The service type dimension shows maintenance and monitoring commanding the largest revenue pools while performance optimization represents the fastest-growing category as owners seek to extract additional yield from aging assets. Technology segmentation reveals offshore operations carrying substantially higher margins per megawatt due to jack-up vessel dependencies and harsh-environment component specifications, whereas onshore maintenance has matured into a cost-competitive field with compressed pricing.
The EU Green Deal and F-Gas Regulation are reshaping refrigerant management protocols for turbine transformer cooling systems across member states, while the IEC 61400 series standards govern structural load monitoring and power performance verification that operators must maintain for grid connection compliance. China's GB standards and MIIT directives mandate specific gearbox oil analysis intervals and failure reporting thresholds for utility-scale installations. Stakeholders must weigh the capital requirements of building offshore service vessel fleets against the long-term contract visibility that major utilities now demand for multi-gigawatt portfolios.
Market Dynamics
Offshore wind expansion in the North Sea is compressing maintenance windows and forcing vessel fleet specialization, while aging onshore installations across Northern Europe trigger component replacement cycles that reshape service contract structures.
Growth Catalysts
- EU Green Deal operational mandates:Performance standard tightening across member states accelerates predictive maintenance adoption. Grid connection compliance now requires continuous structural load monitoring under IEC 61400 standards.
- Jack-up vessel specialization:Dedicated offshore service fleets enable year-round turbine access in harsh North Sea conditions. Harbor infrastructure investments in Esbjerg and Cuxhaven support this capability expansion.
- China's northern wind corridors:Utility-scale installation density creates economies of scale for regional maintenance networks. MIIT gearbox oil analysis mandates standardize service intervals across Gansu and Inner Mongolia provinces.
Market Restraints
- Specialized technician scarcity:GWO-certified rope-access specialists and offshore electrical engineers command premium wages. Training pipeline limitations constrain service capacity expansion in Germany and Denmark.
- Jack-up vessel supply concentration:European offshore maintenance depends on a limited fleet of purpose-built vessels. Charter rate volatility directly compresses contractor margins during peak maintenance seasons.
- F-Gas refrigerant phase-down:EU F-Gas Regulation restricts transformer cooling system maintenance protocols. Alternative cooling technology retrofits impose unplanned capital burdens on turbine owners.
Strategic Opportunities
- Floating offshore wind emergence:Pre-commercial projects in Portugal and France require novel dynamic cable maintenance capabilities. Early movers in mooring system inspection secure multi-decade service positions.
- Drone-based blade inspection:Automated damage detection reduces technician deployment costs by eliminating rope-access requirements. Danish operators pioneer integration with existing SCADA monitoring infrastructure.
- India's offshore wind auction pipeline:National targets for Tamil Nadu and Gujarat installations create demand for tropical cyclone-resistant maintenance protocols. Port infrastructure development lags, opening harbor facility investment opportunities.
Industry Challenges
- Legacy drivetrain diagnostic integration:Older turbine models lack sensor density for predictive analytics platforms. Retrofit hardware installation requires extended downtime that conflicts with availability guarantee terms.
- Multi-OEM fleet standardization:Wind farm owners aggregate assets from Vestas, Siemens Gamesa, and Goldwind across single sites. Technician cross-certification requirements fragment workforce deployment efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind Turbine Operations Market |
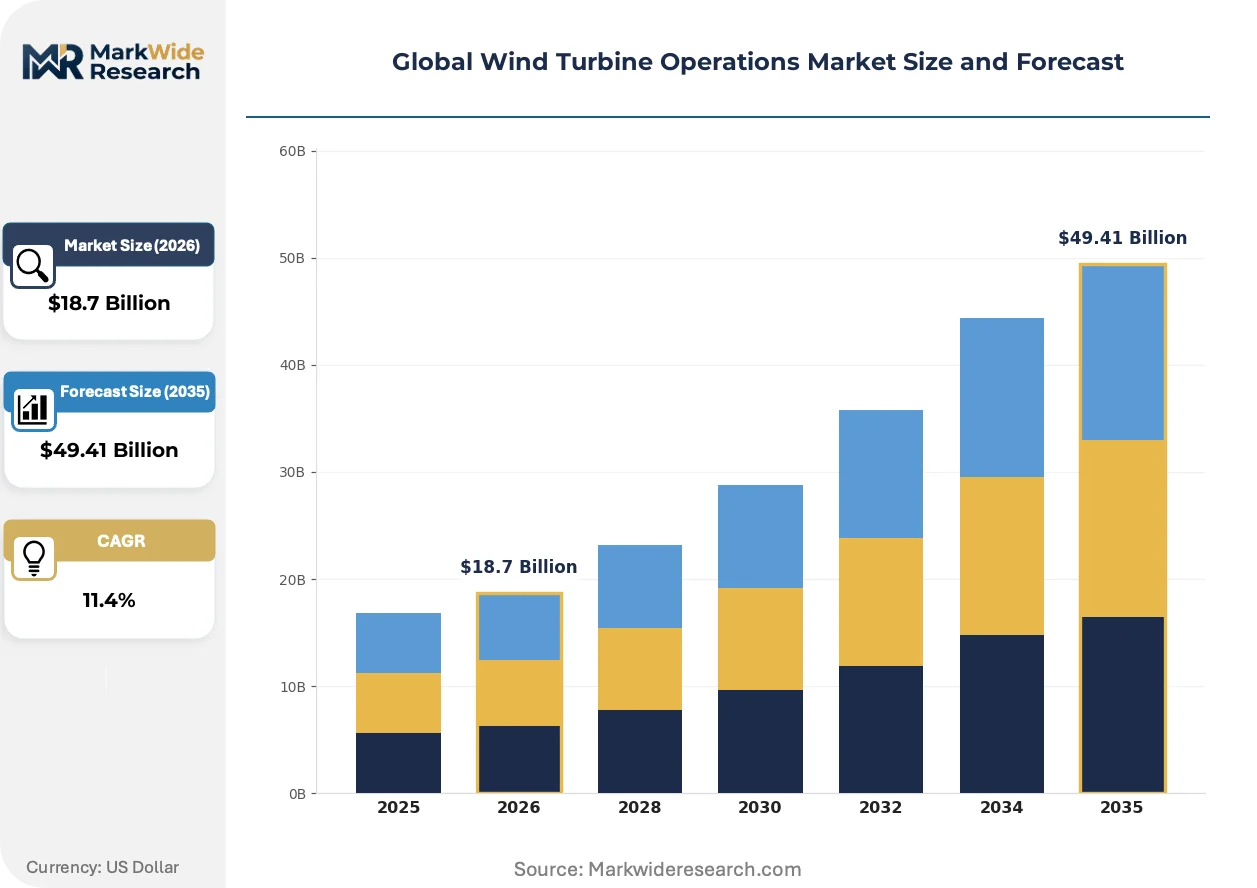
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Performance Optimization, Monitoring Technology: Onshore, Offshore, Hybrid, Advanced Control Systems End User: Utilities, Independent Power Producers, Corporations, Government Agencies Product Type: Horizontal Axis Turbines, Vertical Axis Turbines, Small Scale Turbines, Offshore Platforms |
| Companies Covered | Vestas, Siemens Gamesa Renewable Energy, GE Vernova, Nordex SE, Goldwind, Envision, Mingyang Smart Energy, Windey, Enercon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind Turbine Operations Market Strategic Shifts
Digital twin technology and autonomous inspection systems are compressing maintenance response times while regulatory pressure on refrigerant management forces cooling system redesigns across European installations.
Digital twin platforms are electrifying turbine fleet management by creating real-time virtual replicas of physical assets. Major utilities in the United Kingdom now mandate twin deployment for offshore portfolios exceeding 500 megawatts. This technology is electrifying competitive differentiation among service providers by enabling failure prediction horizons that extend beyond standard OEM warranty periods.
The EU F-Gas Regulation is tightening refrigerant containment requirements for turbine transformer cooling systems. Equipment manufacturers must now certify leak detection systems and transition to lower-GWP alternatives. Offshore installations in the German North Sea face the steepest compliance costs due to salt-air corrosion accelerating seal degradation.
Performance-based service contracts are displacing time-and-materials billing across European wind farm portfolios. Asset owners in Denmark now tie contractor payments to availability guarantees and energy yield improvements. This shift concentrates contract awards among providers with demonstrated predictive analytics capabilities and captive technician workforces.
Global Wind Turbine Operations Market Segmentation
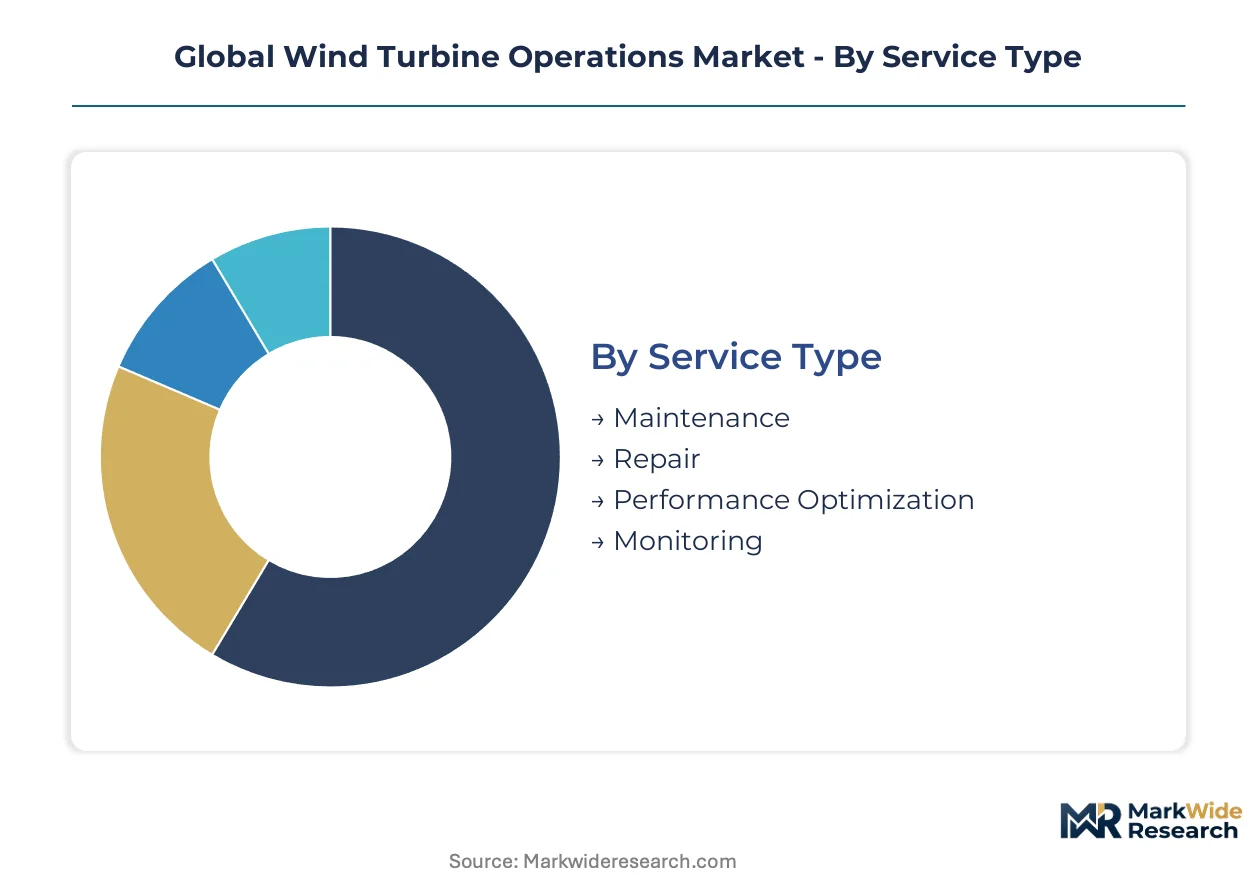
Wind turbine operations segmentation reveals divergent certification requirements across service tiers and technology platforms. OEM service agreements and third-party contractor qualifications fragment competitive positioning across each dimension.
Service Type:
IEC 61400 compliance mandates differentiate scheduled maintenance from predictive monitoring services, with GWO rope-access certification required for blade inspection work.
- Maintenance:Scheduled servicing of drivetrain components operating at 1,500-3,000 RPM demands gearbox oil analysis protocols under China MIIT directives. German operators in the North Sea cluster concentrate demand here due to aging fleet replacement cycles and EU Green Deal availability requirements.
- Performance Optimization:Pitch and yaw control adjustments maximize energy capture per swept area through SCADA-integrated algorithms. Danish utilities lead adoption as they extract additional yield from assets approaching end-of-warranty periods.
- Repair:Component replacement and emergency restoration services require crane logistics and specialized electrical engineering credentials.
- Monitoring:Continuous structural load sensing and power performance verification enable grid connection compliance under IEC standards.
Maintenance sits at the top of the volume ranking, with Performance Optimization climbing the fastest.
Technology:
Cost tier stratification separates vessel-dependent offshore operations from commoditized onshore maintenance networks.
- Offshore:Jack-up vessel access and harsh-environment component specifications carry substantially higher margins per megawatt. Harbor infrastructure investments in Esbjerg and Cuxhaven support year-round North Sea turbine access.
- Onshore:Mature cost-competitive field with compressed pricing and regional technician deployment models. China's northern wind corridors in Gansu and Inner Mongolia anchor volume through utility-scale installation density.
- Hybrid:Combined onshore-offshore service capabilities leverage shared predictive analytics platforms across turbine portfolios.
- Advanced Control Systems:Digital twin integration and autonomous inspection systems compress maintenance response times for large-scale fleets.
Onshore commands the largest revenue base, while Offshore delivers the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between regulated utilities and corporate offtakers with divergent risk appetites.
- Utilities:Multi-gigawatt portfolios demand long-term contract visibility and captive technician workforces. United Kingdom major utilities now mandate digital twin deployment for offshore assets exceeding 500 megawatts.
- Independent Power Producers:Asset aggregation across multiple OEMs fragments service standardization requirements.
- Corporations:Renewable energy procurement targets drive direct ownership with outsourced operations management.
- Government Agencies:Public sector installations in Denmark and Germany prioritize availability guarantees tied to national renewable auction compliance.
Utilities dominate contract value, with Corporations expanding most quickly through direct procurement mandates.
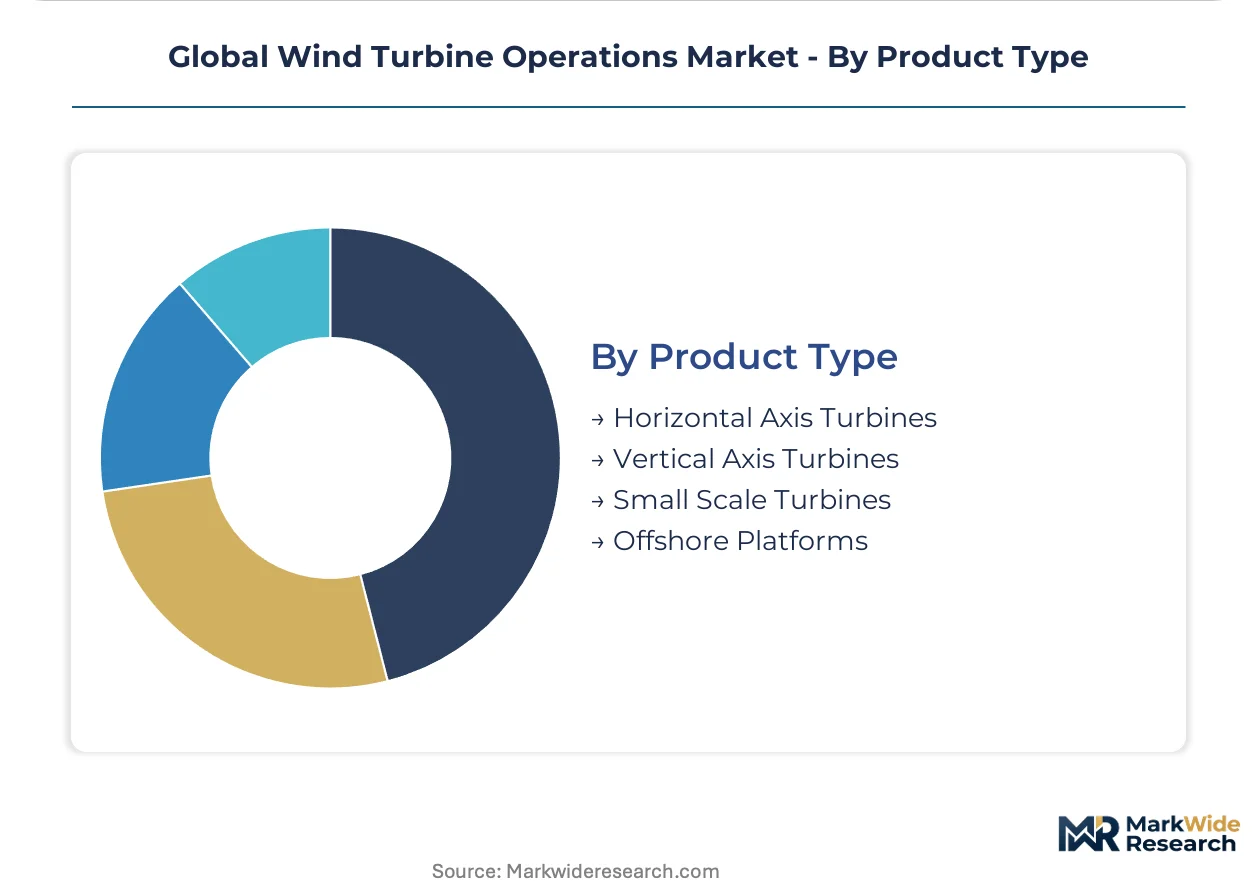
Product Type:
Structural design characteristics dictate maintenance protocol complexity and component replacement lead times.
- Horizontal Axis Turbines:Dominant utility-scale design with established drivetrain diagnostic standards and blade inspection methodologies. Aging European fleets trigger major component replacement cycles.
- Offshore Platforms:Fixed-bottom and floating substructures require dynamic cable maintenance and mooring system inspection capabilities. Pre-commercial projects in Portugal and France demand novel service protocols.
- Vertical Axis Turbines:Alternative mechanical configurations with specialized bearing maintenance requirements.
- Small Scale Turbines:Distributed generation assets with localized technician networks and simplified monitoring systems.
Horizontal Axis Turbines anchor global installed capacity, with Offshore Platforms gaining share fastest through North Sea and Baltic Sea expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's offshore maintenance networks command premium vessel rates, while China's onshore corridors deliver scale economies that reshape technician deployment models across the sector.
Germany
North Sea jack-up vessel specialization concentrates service capacity in Cuxhaven and Bremerhaven harbors. The EU F-Gas Regulation mandates transformer cooling system retrofits across aging Baltic Sea installations. Lower Saxony hosts the densest cluster of drivetrain replacement workshops serving turbines approaching end-of-warranty periods.
United Kingdom
Scottish floating wind pre-commercial projects demand novel dynamic cable maintenance protocols. The UK Energy Act imposes availability guarantee standards for offshore assets exceeding 500 megawatts. Grimsby and Great Yarmouth harbor investments support year-round technician deployment to North Sea arrays.
China
Utility-scale installation density across Gansu and Inner Mongolia provinces anchors regional maintenance network economies. MIIT gearbox oil analysis mandates standardize service intervals for northern wind corridor operators. Xinjiang's turbine clusters drive demand for cold-climate component replacement cycles.
Denmark
Esbjerg harbor infrastructure supports captive vessel fleets serving North Sea offshore arrays. The Danish Energy Agency ties auction compliance to performance-based contractor payment structures. Jutland hosts the highest concentration of GWO-certified rope-access training facilities in Northern Europe.
India
Tamil Nadu and Gujarat offshore auction pipelines create demand for tropical cyclone-resistant maintenance protocols. The Ministry of New and Renewable Energy mandates specific failure reporting thresholds for utility-scale installations. Port infrastructure development in Mundra and Kutch lags installation timelines, opening harbor facility investment gaps.
Global Wind Turbine Operations Market Competitive Environment
Top-tier vendors anchor multi-gigawatt service contracts with captive vessel fleets, while mid-tier specialists compete on regional technician density and predictive analytics platforms. The market structures around three archetypes: OEM-integrated service divisions with harbor infrastructure control, independent contractors with jack-up vessel charter relationships, and technology-focused analytics providers. Consolidation pressures intensify as utilities demand long-term contract visibility. Geographic expansion into floating wind pre-commercial zones and strategic partnerships for drone-based inspection capabilities represent dominant competitive vectors.
Among European-integrated OEMs, Siemens Gamesa Renewable Energy and Vestas occupy positions defined by harbor facility control and predictive platform deployment. Goldwind exemplifies the scale-driven archetype leveraging domestic corridor density to anchor low-cost maintenance networks. These three represent the competitive spectrum from premium offshore specialization to volume-driven onshore standardization.
| Leading Market Players |
|---|
| Vestas |
| Siemens Gamesa Renewable Energy |
| GE Vernova |
| Nordex SE |
| Goldwind |
| Envision |
| Mingyang Smart Energy |
| Windey |
| Enercon |
| Others |
Value Chain & Pricing Dynamics
Specialized steel price indices for offshore-grade alloys cascade through turbine maintenance supply chains into three distinct pricing tiers across European and Asian service markets. Vessel charter rates for jack-up units and GWO-certified technician wages constitute the primary cost escalators that differentiate premium offshore operations from commoditized onshore maintenance networks.
Pricing Analysis
Capacity additions in China's northern wind corridors are reshaping price floors for standardized onshore maintenance services across Asia-Pacific markets. Three-tier pricing structure across premium offshore, standard onshore, and economy retrofit tiers reflects certification depth and vessel dependency. Price differentiation hinges on IEC 61400 compliance grade and captive harbor infrastructure control. Margins are tightening in European offshore segments due to jack-up vessel supply concentration, while China's utility-scale fleet owners demonstrate highest price sensitivity through aggregated procurement mandates.
Supply Chain Analysis
GWO rope-access certification and jack-up vessel operator licensing gate entry into European offshore maintenance supply chains. Manufacturing concentration for specialized drivetrain components rests on Germany, Denmark, and China, with gearbox assemblies and blade materials drawing from these hubs. Rare earth magnet supply for generator maintenance sources from China, while composite blade repair materials hinge on German and Danish chemical producers. Single-source vulnerability concentrates in purpose-built offshore service vessels. Distribution runs through harbor facility networks in Esbjerg, Cuxhaven, and northern Chinese port clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
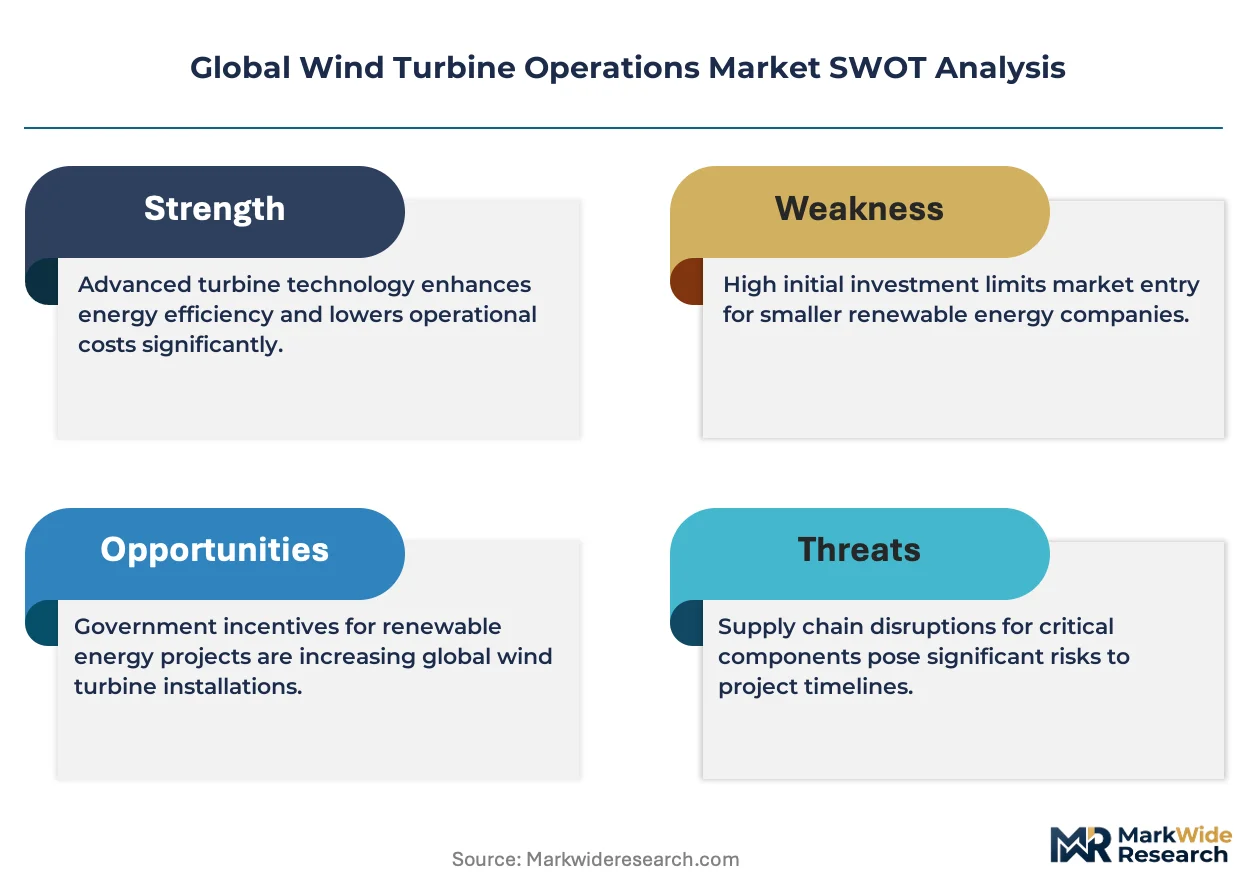
Analyst Recommendations
The Global Wind Turbine Operations Market functions as a stable compounder anchored by irreversible renewable energy capacity expansion and mandatory end-of-warranty maintenance cycles across aging European and Chinese fleets.
For Market Incumbents: Extend predictive analytics platform deployment to capture performance-based contract share as Danish and UK utilities mandate availability guarantees beyond standard OEM terms. Fortify captive vessel fleet positions in North Sea harbors before floating wind pre-commercial projects in Portugal and France mature. Vertical integration into drone-based blade inspection capabilities defends against technology-focused analytics entrants eroding rope-access service margins. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and Denmark opens a window for alternative cooling system retrofit specialists targeting transformer maintenance compliance gaps. India's Tamil Nadu and Gujarat offshore auction pipeline represents the most penetrable geography for tropical cyclone-resistant maintenance protocol development. Drone-based damage detection integration with existing SCADA infrastructure offers the clearest go-to-market angle against entrenched rope-access incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier independent contractors possessing jack-up vessel charter relationships and demonstrated predictive maintenance platforms. Five-to-ten year contract visibility from multi-gigawatt utility portfolios supports long-duration capital deployment. Harbor facility control in floating wind pre-commercial zones signals the critical inflection indicator for early-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Jack-up Vessel Fleet Expansion | Captive harbor access in Cuxhaven and Esbjerg secures year-round North Sea turbine availability. |
| Digital Twin Platform Deployment | UK utilities now mandate virtual asset replicas for offshore portfolios exceeding 500 megawatts. |
| GWO Certification Pipeline Investment | Danish training facility concentration addresses technician scarcity constraining German service capacity. |
| Floating Wind Mooring Capability Development | Pre-commercial projects in Portugal and France demand novel dynamic cable maintenance protocols. |
| Drone-SCADA Integration Partnership | Automated blade inspection eliminates rope-access costs while preserving IEC 61400 compliance standards. |
Study Parameters
Coverage spans Germany, the United Kingdom, China, Denmark, and India, with primary inputs from each market cluster obtained through structured interviews with utility planning officers, independent power producer asset managers, EPC contractors, GWO-certified technician training directors, and offshore vessel fleet operators. Secondary validation draws from IEC 61400 technical committee documentation, EU F-Gas Regulation implementation reports, China MIIT gearbox maintenance directives, and harbor infrastructure investment disclosures. Bottom-up service contract value aggregation triangulates against top-down renewable capacity installation databases.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include service type tier, technology platform, end-user procurement sophistication, and regional regulatory framework cluster. CAGRs derive from installed base growth rates, warranty expiration schedules, and maintenance intensity assumptions per megawatt. Forecast inputs incorporate jack-up vessel supply elasticity, GWO certification pipeline throughput, and F-Gas retrofit compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt commodity price spikes in specialized steel alloys or accelerated floating wind commercialization. Forecasts reflect documented assumptions regarding technician training completion rates and harbor infrastructure commissioning schedules. A model refresh is warranted upon material change in EU Green Deal operational mandate enforcement intensity or China's MIIT gearbox analysis interval revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Wind Turbine Lenses Market