
 Offshore Wind Cable Market | 2026-2036
Offshore Wind Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Wind Cable Market Analysis
A shortage of certified offshore cable installation vessel crews is unwinding project schedules across the supply chain. Prysmian Group leverages its vertical integration from conductor drawing to cable laying to secure long-term utility contracts. JDR Cable Systems specializes in dynamic array cables for floating wind platforms, a segment where technical barriers limit supplier entry. Nexans anchors its position through dedicated R&D centers in Norway and France focused on 66 kV and 132 kV system validation.
Offshore wind cables are high-voltage subsea conductors, typically insulated with cross-linked polyethylene and armored with galvanized steel wire to withstand hydrostatic pressure and seabed abrasion, designed to transmit electricity from turbine arrays to onshore substations. Export cables dominate value capture due to their extended length and higher voltage ratings, while array cables compete on unit cost per megawatt as wind farm densities rise. Installation method selection increasingly favors hybrid burial-lay approaches where seabed geotechnical variability complicates uniform trenching across the North Sea and Baltic basins.
The EU Green Deal, Germany's Bundesamt für Seeschifffahrt und Hydrographie permitting protocols, and the UK's Offshore Petroleum Regulator for Environment and Decommissioning seabed licensing rules collectively shape cable routing, burial depth mandates, and environmental compliance timelines. ISO 13628-5 and IEC 62288 standards govern umbilical and dynamic cable mechanical performance, creating certification bottlenecks that filter out non-specialized manufacturers. Stakeholders must monitor floating platform demonstration projects in Portugal and France, where dynamic cable fatigue testing protocols remain unsettled and will determine which material suppliers qualify for next-generation arrays.
Market Dynamics
The offshore wind cable market faces acute pressure from vessel crew shortages that are compressing installation schedules and forcing utilities to secure manufacturing slots years ahead of deployment. This supply-side bottleneck is restructuring contract negotiations across Northern Europe.
Growth Catalysts
- EU Green Deal targets:Binding renewable energy mandates in Germany, Denmark, and the Netherlands are accelerating maritime spatial planning approvals and cable procurement timelines.
- Floating platform engineering:Turbine capacities exceeding 15 MW per unit are demanding dynamic array cable systems that withstand platform motion and fatigue loads.
- Port infrastructure clusters:Coordinated upgrades at Esbjerg, Rotterdam, and Bremerhaven are reducing logistics friction for heavy cable load-outs.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings compress cable manufacturer margins and complicate long-term fixed-price contracting.
- Installation vessel oligopoly:A concentrated fleet of certified cable-lay ships creates queue bottlenecks that delay project commissioning.
- Seabed licensing fragmentation:Divergent burial depth mandates between Germany's Bundesamt für Seeschifffahrt und Hydrographie and the UK's Offshore Petroleum Regulator for Environment and Decommissioning force redundant route surveys.
Strategic Opportunities
- Floating wind demonstration zones:Portugal and France are hosting pre-commercial arrays where dynamic cable fatigue testing protocols remain unsettled, creating first-mover qualification advantages.
- 66 kV and 132 kV system standardization:Convergence around these voltage levels permits modular manufacturing scale and reduces custom engineering overhead.
- Hybrid burial-lay service models:Geotechnical variability across the North Sea and Baltic basins is opening demand for integrated installation approaches that combine trenching and surface-lay methods.
Industry Challenges
- ISO 13628-5 and IEC 62288 certification timelines:Umbilical and dynamic cable mechanical performance testing creates multi-month bottlenecks that filter out non-specialized manufacturers.
- Cross-linked polyethylene compounding capacity:Insulation material supply constraints limit cable production scaling during procurement surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Wind Cable Market |
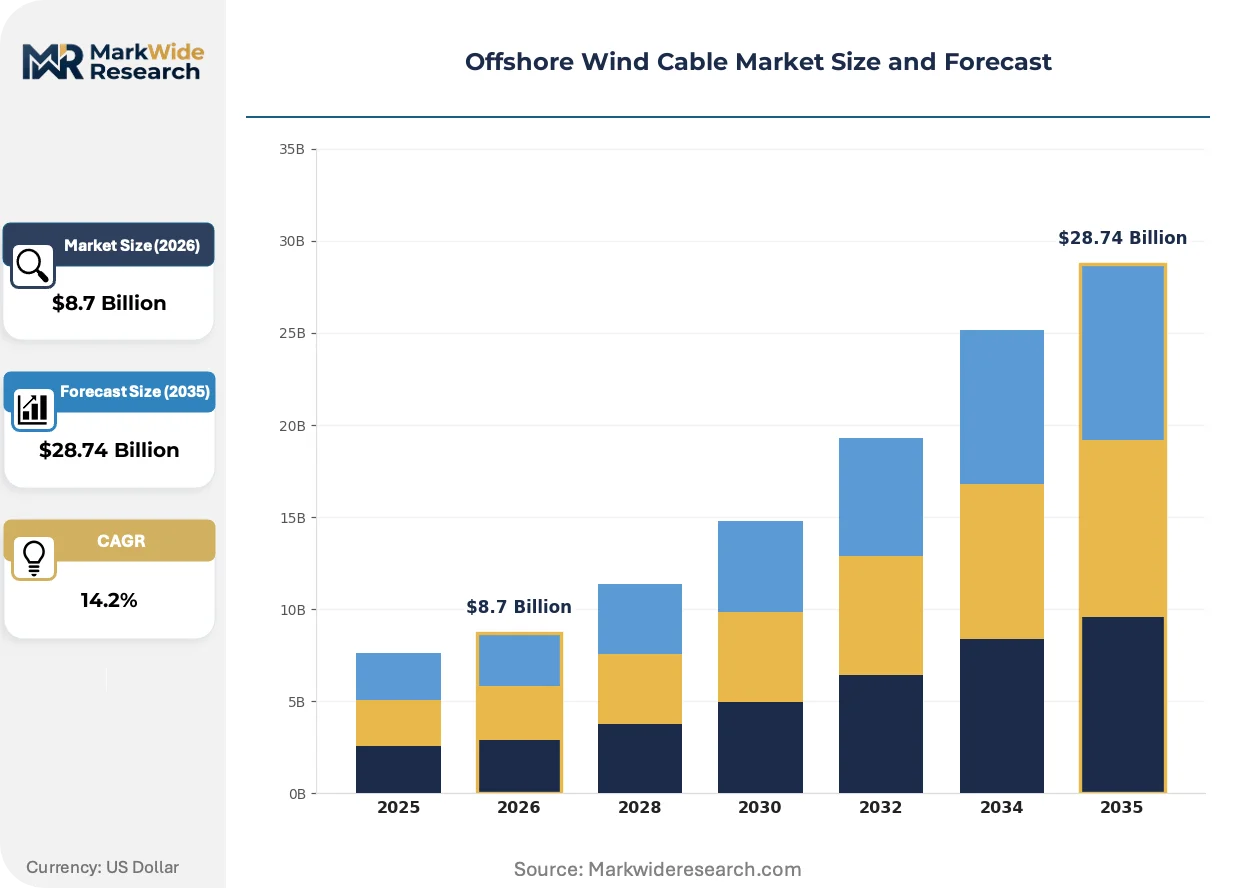
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Export Cable, Array Cable, Installation Cable, Umbilical Cable Material: Copper, Aluminum, Polyethylene, Thermoplastic Elastomer Installation Method: Buried, Laid on Seabed, Directly Embedded, Hybrid End User: Utilities, Independent Power Producers, Government Agencies, Developers |
| Companies Covered | LS Cable & System, Hellenic Cables, Prysmian Group, Furukawa Electric, JDR Cable Systems, Nexans, Sumitomo Electric Industries, ZTT, NKT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Wind Cable Market Emerging Trajectories
High-voltage cable engineering is converging with floating platform mechanics as turbine scale and water depth push installation into unproven territory. Material science and regulatory frameworks are racing to keep pace with these physical demands.
Dynamic cable systems for floating wind platforms are miniaturizing conductor cross-sections while maintaining ampacity through enhanced thermal management. Developers in the Celtic Sea and Gulf of Maine are piloting these compact designs to reduce topside handling weight. The structural consequence is a compression in deck space requirements and lay vessel specifications.
The EU Green Deal's offshore renewable targets are tightening environmental compliance windows for seabed disturbance permits. Germany's maritime spatial planning directives now mandate real-time burial depth monitoring during installation. Array cable suppliers are responding by embedding fiber-optic sensing cores that transmit geotechnical data to shore-based regulators.
Utility procurement departments are consolidating cable contracts into multi-project framework agreements that lock in vessel slots and copper pricing. This behavior shift displaces project-by-project tendering that previously dominated the North Sea corridor. Danish and Dutch transmission system operators are most advanced in this transition, using portfolio-scale bargaining to extract priority manufacturing schedules from suppliers.
Offshore Wind Cable Market Segmentation
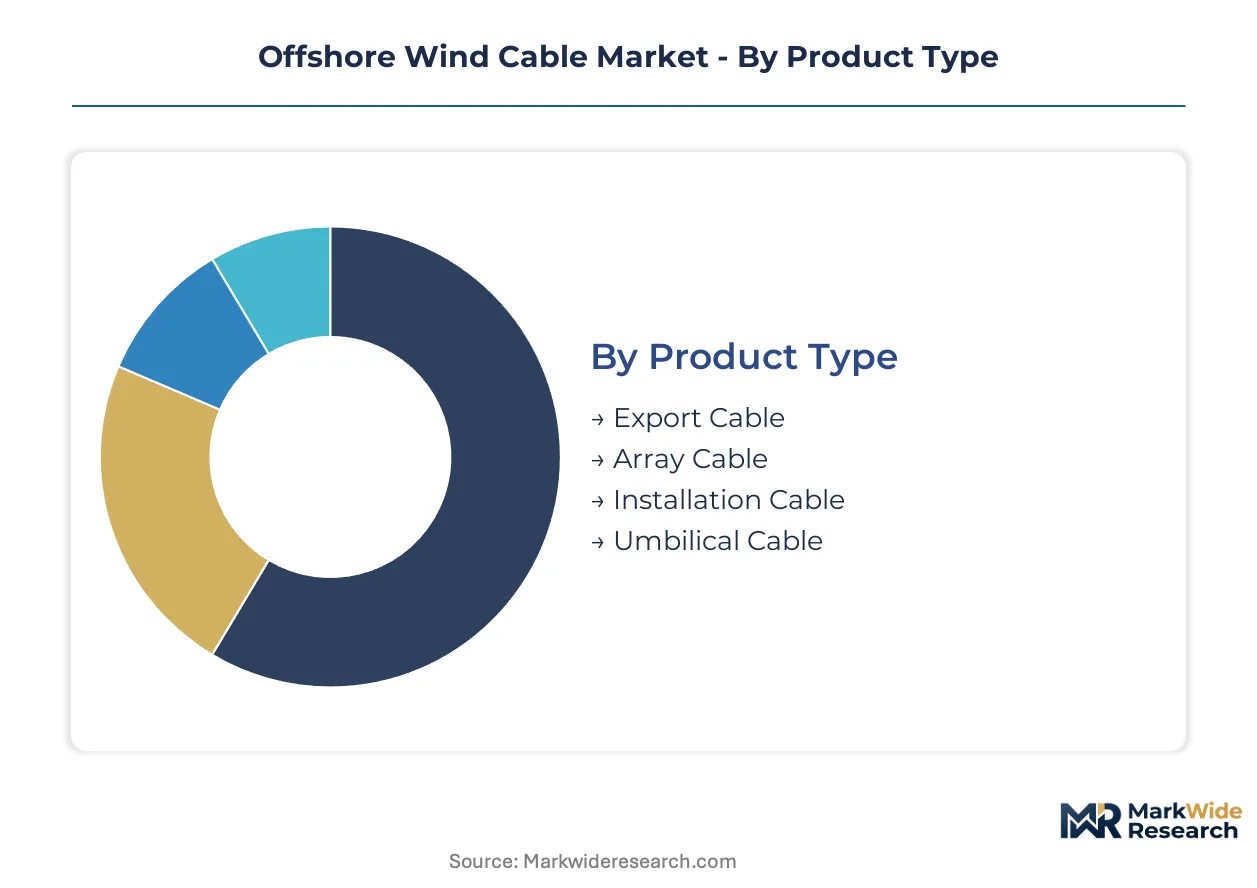
Offshore wind cable procurement decisions hinge on voltage ratings, water depth, and seabed geotechnical conditions. Regulatory burial mandates from Germany's BSH and the UK's OPRED create divergent specification requirements across product categories. Understanding segment boundaries helps utilities align procurement with project-specific compliance and performance thresholds.
Product Type:
Regulatory differentiation in burial depth and voltage rating mandates splits procurement strategies across Northern European markets. Germany's BSH requires deeper trenching for export cables crossing shipping corridors, while Denmark's maritime spatial planning prioritizes array cable density optimization.
- Export Cable:High-voltage conductors rated 66 kV to 220 kV transmit aggregated power from offshore substations to onshore grids across distances exceeding 50 kilometers. Demand concentrates in the North Sea corridor where German and Dutch transmission system operators commission multi-gigawatt clusters. The EU Green Deal's binding targets compress procurement timelines for these high-value assets.
- Array Cable:Medium-voltage inter-turbine links rated 33 kV to 66 kV connect individual units within wind farm footprints. Procurement in Denmark and the Netherlands emphasizes unit cost per megawatt as turbine densities rise and spacing optimization reduces conductor length per installed capacity.
- Installation Cable:Temporary power and control lines support construction-phase logistics and commissioning activities.
- Umbilical Cable:Integrated power, signal, and hydraulic bundles serve floating platform station-keeping and dynamic positioning systems.
Established volume favors Export Cable; emerging adoption favors Umbilical Cable.
Material:
Cost tier differentiation separates commodity conductor metals from specialized insulation compounds. Copper pricing volatility through the London Metal Exchange forces long-term contracting structures that aluminum alternatives partially mitigate.
- Copper:Primary conductor material delivering superior electrical conductivity and fatigue resistance in dynamic bending zones. Norwegian and UK developers specify copper cores for high-reliability export routes where ampacity losses translate directly to revenue leakage.
- Aluminum:Lightweight alternative reducing topside handling requirements and lay vessel deck load constraints. French and Spanish project consortia specify aluminum for array networks where shorter runs diminish conductivity penalty impacts.
- Polyethylene:Cross-linked insulation compound providing dielectric strength and hydrostatic pressure resistance.
- Thermoplastic Elastomer:Flexible jacketing material for dynamic umbilical applications requiring repeated bending cycles.
Copper dominates value capture; aluminum is climbing the fastest in procurement share.
Installation Method:
Application-driven selection depends on seabed substrate mapping and benthic habitat sensitivity assessments. Baltic basin clay sediments favor trenching while North Sea glacial till demands hybrid approaches.
- Buried:Mechanical trenching or jetting achieves target depth below seabed surface for protection against fishing gear and anchor strikes. German BSH permitting mandates this method across designated shipping lanes and cable corridors.
- Laid on Seabed:Surface placement with rock dumping or concrete mattress protection where burial is geotechnically prohibitive. UK OPRED licenses this approach in hard substrate zones of the Celtic Sea.
- Directly Embedded:Post-lay trenching using remotely operated vehicles in sensitive benthic habitats.
- Hybrid:Combined burial and surface-lay techniques adapting to variable geotechnical conditions along single route spans.
Buried methods retain regulatory preference; hybrid approaches are gaining share fastest in complex terrain.
End User:
Customer type determines contracting scale and risk allocation frameworks. Portfolio-scale buyers extract manufacturing priority through multi-project framework agreements.
- Utilities:Vertically integrated transmission system operators in Denmark, Germany, and the Netherlands procure export cables through decade-spanning supply agreements. Energinet and TenneT lock in vessel slots and copper pricing three to five years ahead of installation.
- Independent Power Producers:Project-specific developers bidding into subsidy auctions negotiate array cable supply on a per-farm basis. Copenhagen Infrastructure Partners and Ørsted procurement teams compete for overlapping manufacturing windows.
- Government Agencies:National maritime authorities and spatial planning directorates influence routing and burial specifications.
- Developers:Engineering-procurement-construction contractors package cable supply within turnkey installation contracts.
Utilities command supply priority; Independent Power Producers drive specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities commission export cables at 220 kV for North Sea transmission corridors, while Danish operators prioritize 66 kV array density optimization. Portuguese and French developers pilot dynamic umbilical systems for floating platforms in deeper Atlantic waters.
Germany
Energinet and TenneT procure multi-gigawatt export cable clusters through decade-spanning supply agreements. Germany's Bundesamt für Seeschifffahrt und Hydrographie mandates real-time burial depth monitoring across designated shipping lanes. Port infrastructure at Bremerhaven supports heavy cable load-outs for North Sea installation campaigns.
Denmark
Esbjerg anchors cable manufacturing and logistics for Danish transmission system operators. The country's maritime spatial planning directives prioritize array cable density optimization as turbine spacing tightens. Port upgrades at Esbjerg reduce logistics friction for hybrid burial-lay vessel mobilization.
Netherlands
Rotterdam's port infrastructure cluster coordinates export cable staging for Dutch-German interconnectors. National renewable energy targets compress procurement timelines for 132 kV system validation. The Randstad region concentrates cable engineering talent and subsea testing facilities.
United Kingdom
Scottish and English developers bid array cable contracts into CfD subsidy auctions. The Offshore Petroleum Regulator for Environment and Decommissioning licenses surface-lay methods in hard substrate zones of the Celtic Sea. Aberdeen and Humberside host installation vessel crew training centers.
France
Brittany and Mediterranean demonstration zones host pre-commercial floating wind arrays where dynamic cable fatigue protocols remain unsettled. ANSM and CNIL oversight extends to embedded fiber-optic sensing data transmission. Port infrastructure at Saint-Nazaire adapts for dynamic umbilical handling.
Offshore Wind Cable Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the offshore wind cable market. Tier-one suppliers control conductor drawing through cable laying to secure multi-year utility frameworks. Specialist manufacturers concentrate on dynamic array systems for floating platforms where technical barriers limit entry. Consolidation pressures favor backward integration into cross-linked polyethylene compounding and captive installation vessel fleets.
Among European integrated suppliers, Prysmian Group and Nexans occupy positions spanning export cable manufacturing to installation services. JDR Cable Systems exemplifies the specialist archetype focused on dynamic umbilical systems. Korean and Japanese fabricators including LS Cable & System and Furukawa Electric represent scale-driven challengers expanding beyond domestic offshore wind markets. ZTT anchors Chinese supply capacity for array cable export.
| Leading Market Players |
|---|
| LS Cable & System |
| Hellenic Cables |
| Prysmian Group |
| Furukawa Electric |
| JDR Cable Systems |
| Nexans |
| Sumitomo Electric Industries |
| ZTT |
| NKT |
| Others |
Supply Flow & Price Mechanics
Thirty-six-month manufacturing lead times for 220 kV export cables concentrate pricing power with integrated suppliers controlling conductor drawing through cable laying, while utilities respond with decade-spanning offtake agreements that lock in vessel slots and copper pricing against raw material volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement as Danish and Dutch transmission system operators abandon project-by-project tendering for multi-project framework agreements that secure priority manufacturing schedules. Price differentiation separates premium-tier suppliers with captive installation fleets from standard-tier manufacturers competing on unit cost per megawatt. Cost compression in array cable segments is intensifying as turbine densities rise and spacing optimization reduces conductor length per installed capacity. Independent power producers bidding into subsidy auctions exhibit the highest price sensitivity, while integrated utilities with portfolio-scale bargaining power extract the most favorable terms.
Supply Chain Analysis
Strategic stockpiling of cross-linked polyethylene insulation compounds is displacing just-in-time preferences as procurement surges expose compounding capacity bottlenecks. Manufacturing gravity centers on Germany, Denmark, and the Netherlands where port infrastructure at Esbjerg, Rotterdam, and Bremerhaven supports heavy cable load-outs. The supply chain rests on copper and aluminum conductor metals, galvanized steel wire armoring, and specialized thermoplastic elastomer jacketing materials. Single-source vulnerability concentrates in certified cable-lay vessel fleets where crew shortages create queue bottlenecks. Distribution runs through utility procurement departments and engineering-procurement-construction contractors packaging cable supply within turnkey installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installation vessel crews and dynamic cable fatigue testing capabilities are the binding constraints that determine which suppliers qualify for next-generation floating wind arrays, creating winner-take-most dynamics across the supply chain.
For Market Incumbents: Fortify backward integration into cross-linked polyethylene compounding and captive installation vessel fleets to defend against emerging Korean and Japanese fabricators expanding beyond domestic markets. Prioritize R&D investment in 66 kV and 132 kV system validation to maintain qualification advantages as voltage standardization accelerates. Secure multi-year utility framework agreements before procurement consolidation displaces project-by-project tendering entirely. For New Entrants and Emerging Players: ISO 13628-5 and IEC 62288 certification fast-tracks offer entry pathways into dynamic umbilical systems for floating platforms where technical barriers limit supplier entry and testing protocols remain unsettled. Target pre-commercial demonstration zones in Portugal and France where first-mover qualification advantages persist. Pursue specialist positioning rather than challenging integrated leaders on export cable scale. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capability play because offshore wind cable manufacturing requires irreplicable combinations of subsea engineering talent, port infrastructure access, and regulatory certification relationships that compound over decades. Acquisition targets should display vertical integration from material compounding through installation services. Watch floating platform deployment rates as the inflection indicator for dynamic cable demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Installation Vessel Acquisition | Secures priority crew allocation against EU Green Deal procurement surges. |
| Cross-Linked Polyethylene Compounding Integration | Eliminates insulation material bottlenecks during manufacturing scale-up. |
| 66 kV and 132 kV System Standardization | Reduces custom engineering overhead for modular manufacturing scale. |
| Dynamic Cable Fatigue Testing Protocol Development | Qualifies suppliers for floating wind platforms in Portuguese and French zones. |
| Multi-Project Framework Agreement Structuring | Locks in vessel slots and copper pricing through decade-spanning utility contracts. |
Methodological Framework
The analysis maps export cable, array cable, and dynamic umbilical segments, each validated through utility procurement officers, cable manufacturer engineering directors, installation vessel operators, and maritime regulatory affairs specialists. Primary interview findings triangulate against customs and trade data, Bundesamt für Seeschifffahrt und Hydrographie permitting records, FERC interconnection filings, and project development databases. Bottom-up capacity and demand modeling reconciles with top-down market sizing across voltage rating, material, and installation method dimensions.
Consistency checks validate volume and value outputs against IEA offshore wind deployment projections, EIA transmission investment data, and national renewable energy target trajectories across the analysis window. Segmentation modeling incorporates product type, material composition, installation method, and end-user contracting archetype. CAGRs derive from installed capacity forecasts, turbine scaling curves, and cable intensity per megawatt assumptions. Industry-specific inputs include vessel fleet utilization rates, copper price volatility bands, and burial depth regulatory divergence between Germany's BSH and the UK's OPRED.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal target adherence and floating platform technology maturation; material deviation would warrant model refresh. Revision becomes warranted when installation vessel crew availability or cross-linked polyethylene compounding capacity crosses thresholds that fundamentally alter supply-side constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Dual Rotor Wind Turbine Market