
 Water Source Heat Pump Market | 2026-2036
Water Source Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Water Source Heat Pump Market Analysis
The EU Green Deal is expanding the cost-of-entry calculus for water source heat pump manufacturers by mandating near-zero emission building standards across member states. Trane Technologies leverages its chiller heritage to dominate large-scale commercial installations. Carrier Global Corporation anchors its position through deep contractor relationships and controls distribution channels in North American metropolitan markets. Daikin Industries competes on refrigerant innovation and leads variable-capacity system development for mixed-use buildings.
A water source heat pump extracts thermal energy from groundwater, lakes, or aquifers through a heat exchanger to provide space conditioning, typically achieving coefficient of performance ratings between three and five depending on loop temperature and compressor technology. Ground source installations command the deepest project pipelines due to their year-round temperature stability and compatibility with existing borehole infrastructure. The commercial installation segment sustains the widest margin pools as facility managers prioritize lifecycle cost reduction over first-cost minimization, while district heating networks represent the fastest-growing application as municipalities decarbonize centralized thermal systems.
The EPA regulates refrigerant phase-down timelines under the AIM Act, while the EU F-Gas Regulation constrains hydrofluorocarbon availability and the ISO 13256 standard governs thermal performance testing protocols. These frameworks collectively force manufacturers toward lower-global-warming-potential working fluids and certified efficiency disclosures. Stakeholders must monitor refrigerant chemistry transitions and thermal network interoperability standards as the primary variables determining product viability and project financeability.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing payback period calculations for commercial property owners, forcing capital allocation toward geothermal-ready HVAC infrastructure across member states.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon phase-down schedules are accelerating refrigerant chemistry transitions toward propane and CO2-based systems, expanding addressable markets for low-GWP heat pump architectures.
- District heating network expansion:Municipal decarbonization programs in Denmark, Sweden, and Germany are integrating water source heat pumps as baseload thermal sources for fourth-generation district energy systems.
- Ground source borehole infrastructure:Existing geothermal well fields from abandoned oil and gas operations in Texas, Alberta, and the Netherlands are being repurposed for closed-loop thermal extraction at reduced drilling cost.
Market Restraints
- Copper and rare earth magnet pricing:Compressor motor manufacturing depends on neodymium-iron-boron supply chains concentrated in China, creating input cost volatility that compresses OEM margins.
- Geologic uncertainty:Aquifer thermal capacity and groundwater chemistry vary significantly by site, requiring expensive subsurface characterization that extends project development timelines.
- Natural gas price subsidies:Residential heating fuel incentives in Germany, Poland, and the Netherlands continue to distort lifecycle cost comparisons against electric heat pump alternatives.
Strategic Opportunities
- Industrial waste heat recovery:Data center cooling loops and manufacturing process streams represent untapped thermal sources for hybrid water source heat pump installations.
- US Inflation Reduction Act:Section 48C clean energy manufacturing tax credits are offsetting domestic production facility capital costs for compressor and heat exchanger assembly.
- Retrofit finance bundling:Energy Service Companies in France and Italy are packaging heat pump installation with building envelope upgrades through performance contracting structures.
Industry Challenges
- Refrigerant handling certification:EPA Section 608 technician requirements and EU F-Gas personnel qualification mandates are constraining qualified installer availability.
- Legacy control system integration:BACnet and Modbus protocol translation with 1980s-era building automation systems requires custom engineering that erodes project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Source Heat Pump Market |
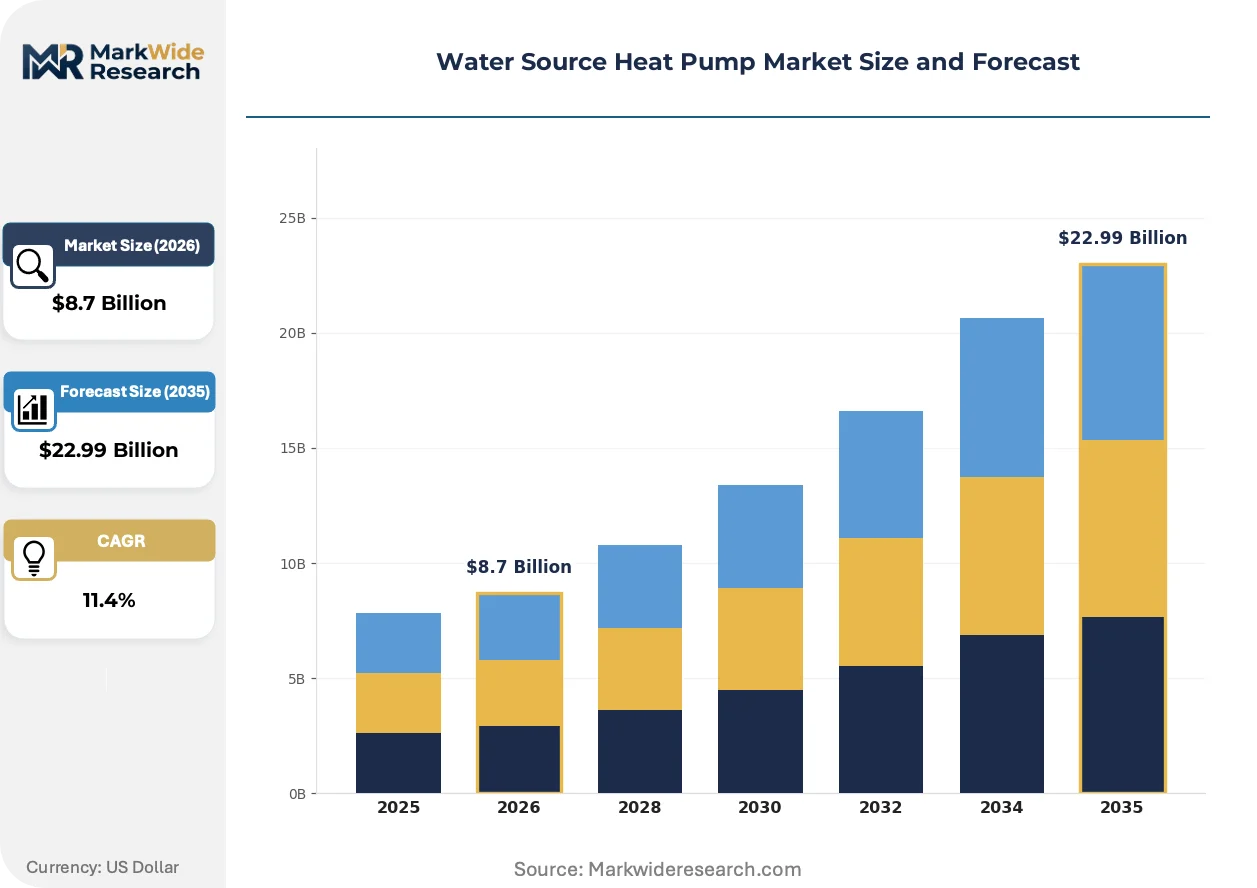
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Source, Surface Water, Aquifer, Hybrid Installation Type: Residential, Commercial, Industrial, District Heating Technology: Open Loop, Closed Loop, Direct Exchange, Passive End User: Homeowners, Building Contractors, Facility Managers, Energy Utilities |
| Companies Covered | Trane Technologies, Carrier Global Corporation, Daikin Industries, Bosch Thermotechnology, Mitsubishi Electric, NIBE Industrier, Johnson Controls, Stiebel Eltron, Rheem Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Source Heat Pump Market Emerging Trajectories
Refrigerant chemistry transitions, thermal network digitization, and procurement model restructuring are converging to redefine competitive advantage in water source heat pump deployment.
Variable-speed scroll compressors using permanent magnet motors are integrating with predictive control algorithms to modulate capacity against real-time thermal load profiles. Large commercial facility operators in Germany and the Netherlands are specifying these systems for mixed-use developments where heating and cooling demands fluctuate asynchronously. This integration is compressing energy consumption differentials between water source and air source alternatives in moderate climate zones.
The EPA's AIM Act refrigerant phase-down timeline is accelerating hydrofluorocarbon quota reductions through 2036, forcing manufacturers to validate alternative working fluids under UL 60335-2-40 safety protocols. Commercial chiller OEMs are responding by expanding R-290 propane and R-744 CO2 product lines for sub-150 kW capacity segments. The regulatory pressure is most acute in California and Washington state, where state-level HFC restrictions precede federal mandates.
Building owners are consolidating mechanical system procurement under single-source performance contracts that bundle design, installation, and 15-year energy savings guarantees. This consolidation is displacing traditional bid-specify-construct models in US K-12 school districts and municipal office portfolios. The shift is most visible in Texas and Florida, where energy savings performance contracting statutes enable off-balance-sheet financing for district-scale geothermal installations.
Water Source Heat Pump Market Segmentation
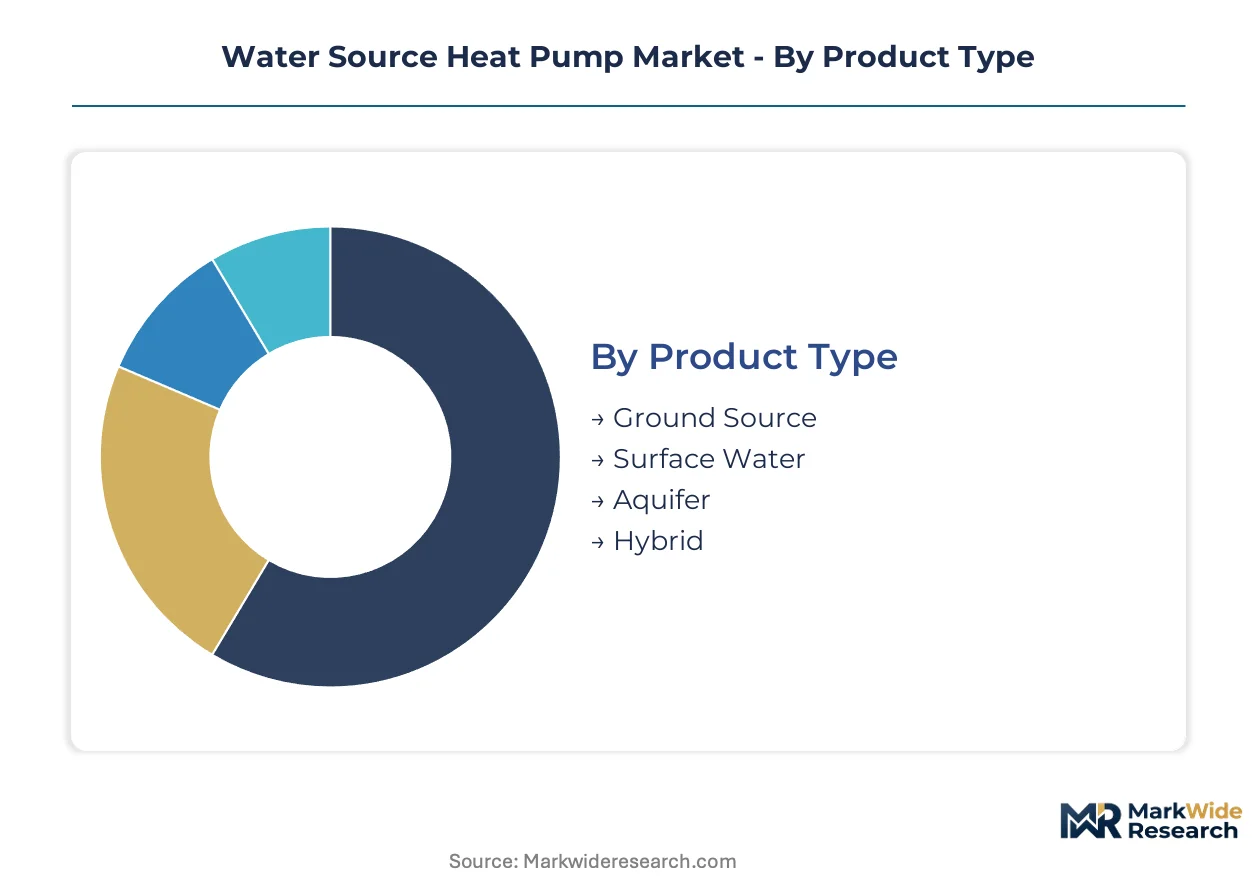
Segmentation in the water source heat pump market reveals how thermal source selection, installation scale, and control architecture determine project economics and regulatory compliance pathways. Product type and installation category together dictate whether systems operate as standalone assets or integrate into broader district energy networks.
Product Type:
Standalone ground source systems dominate retrofit applications, while surface water and hybrid configurations increasingly embed within larger thermal networks serving multiple buildings.
- Ground Source:Closed-loop borehole fields extract stable subsurface temperatures between 10°C and 16°C year-round. Germany and the Netherlands concentrate demand as abandoned oil and gas well infrastructure reduces drilling capital requirements.
- Surface Water:Open-loop configurations draw from lakes, rivers, or cooling ponds through submerged heat exchangers. Denmark and Sweden prioritize these systems for district heating feed-in where thermal discharge regulations favor surface water over groundwater extraction.
- Aquifer:Doublet well systems pump and reinject groundwater to avoid thermal plume contamination. Regulatory permitting complexity limits deployment to geologically characterized sites.
- Hybrid:Combined thermal sources switch between ground, air, and waste heat depending on load and ambient conditions. These systems gain traction in mixed-use developments with asynchronous heating and cooling demands.
Ground source leads volumes today; hybrid configurations are gaining share fastest.
Installation Type:
Cost tier separation between residential single-family systems and commercial multi-tenant installations creates distinct margin structures and procurement channels across the value chain.
- Residential:Single-family and small multi-family units under 50 kW capacity. Natural gas price subsidies in Germany and Poland compress payback calculations and slow electrification transitions.
- Commercial:Office buildings, retail, and hospitality applications where facility managers prioritize lifecycle cost reduction. Energy Service Companies in France and Italy bundle these installations with envelope upgrades through performance contracting.
- Industrial:Process heating and manufacturing facility applications. Data center cooling loops represent emerging thermal source opportunities for waste heat recovery configurations.
- District Heating:Centralized thermal plants serving multiple buildings through piped distribution networks. Municipal decarbonization programs in Denmark, Germany, and Sweden integrate water source heat pumps as baseload sources for fourth-generation systems.
Commercial installations command the widest margins; district heating is climbing the fastest as municipalities phase out fossil thermal plants.
Technology:
Volume concentration in closed-loop systems reflects installer familiarity and regulatory safety certification availability, while direct exchange and passive architectures occupy niche applications with specific geological or thermal load profiles.
- Open Loop:Direct groundwater circulation through heat pump heat exchangers requires aquifer characterization and discharge permitting. Water chemistry variability drives maintenance cost uncertainty.
- Closed Loop:Circulating fluid in sealed piping eliminates groundwater contact and simplifies regulatory approval. This architecture dominates contractor training programs and OEM product standardization.
- Direct Exchange:Refrigerant circulates directly through copper ground loops, eliminating intermediate heat exchanger losses. Copper pricing volatility and refrigerant charge volume restrictions constrain adoption.
- Passive:Gravity-driven or thermosiphon systems without compressors serve low-temperature applications. Limited capacity range restricts deployment to pre-heating or supplementary roles.
Closed loop dominates installed base; direct exchange is expanding most quickly in geothermally favorable regions with stable copper supply contracts.
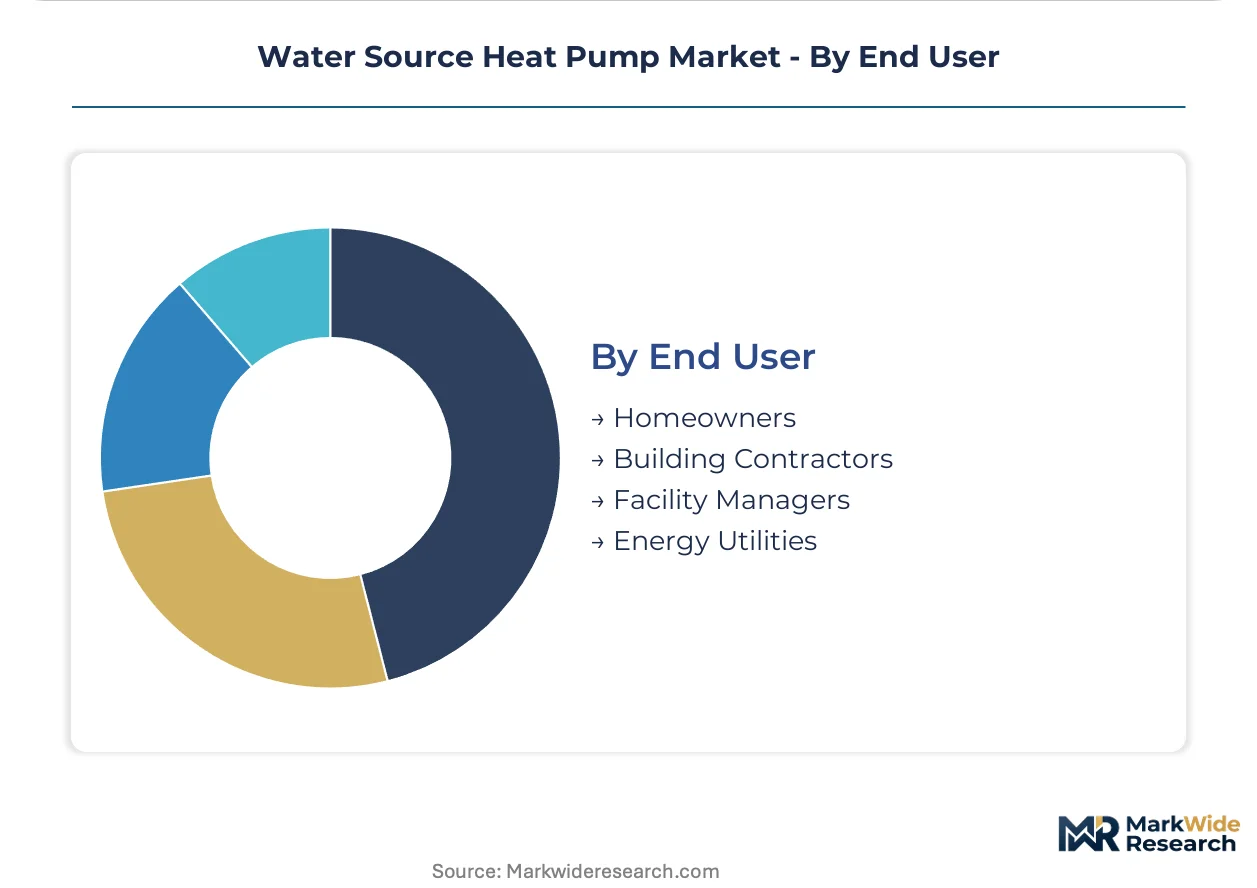
End User:
Customer type determines specification authority, financing mechanism, and service relationship duration, with facility managers and energy utilities increasingly displacing traditional contractor-led procurement.
- Homeowners:Individual purchasers motivated by energy cost reduction and carbon footprint reduction. IRA tax credits in the United States and national subsidy programs in European member states influence purchase timing.
- Building Contractors:New construction developers specifying HVAC systems during design phase. These actors prioritize first-cost minimization over lifecycle optimization, creating margin pressure for premium efficiency tiers.
- Facility Managers:Commercial and institutional portfolio operators with capital planning horizons exceeding ten years. These stakeholders drive demand for predictive maintenance integration and BACnet-compatible control systems.
- Energy Utilities:Municipal and investor-owned thermal network operators procuring megawatt-scale installations. These actors specify interoperability standards for fourth-generation district heating integration.
Facility managers drive commercial segment volumes; energy utilities represent the steepest expansion trajectory as district networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The water source heat pump industry traces its commercial origins to Scandinavian district heating networks and North American oil field repurposing projects, with technology maturation now spreading through German engineering clusters and Chinese manufacturing zones.
Germany
Abandoned oil and gas well infrastructure in Lower Saxony and North Rhine-Westphalia reduces drilling capital for closed-loop geothermal fields. The EU F-Gas Regulation accelerates hydrofluorocarbon phase-downs, pushing OEMs toward propane and CO2 refrigerant architectures. Munich and Stuttgart engineering clusters concentrate system integration expertise for fourth-generation district heating feed-in.
United States
The IRA Section 48C clean energy manufacturing tax credits offset domestic compressor and heat exchanger assembly facility costs. EPA Section 608 technician certification requirements constrain qualified installer availability, creating regional service bottlenecks. Texas repurposes depleted hydrocarbon well fields in the Permian Basin for thermal extraction at reduced capital intensity.
China
Dual carbon goals and building efficiency mandates in the Yangtze River Delta and Pearl River Delta drive electrification of commercial heating infrastructure. The country's national standardization administration governs thermal performance testing protocols for imported and domestic equipment. Beijing-Tianjin-Hebei corridor municipalities integrate water source heat pumps into centralized thermal networks as coal plant phase-outs accelerate.
Sweden
Fourth-generation district heating system expansion in Stockholm and Malmö prioritizes surface water extraction over groundwater to avoid thermal plume contamination. The national environmental protection agency administers discharge permitting for open-loop lake and seawater configurations. Göteborg's harbor district hosts pilot projects pairing data center waste heat recovery with municipal thermal distribution.
Netherlands
Groningen and Limburg provinces repurpose natural gas field infrastructure for geothermal closed-loop deployment, leveraging existing subsurface characterization data. The EU Green Deal's building renovation targets tighten efficiency mandates for commercial property retrofits in Amsterdam and Rotterdam metropolitan zones. Dutch engineering consultancies specialize in aquifer thermal energy storage integration for mixed-use developments.
Water Source Heat Pump Market Vendor Landscape
The competitive structure tilts toward diversified HVAC conglomerates with chiller heritage and deep contractor channel relationships. Market concentration remains moderate, with tier-one players commanding premium pricing in commercial and district heating segments while regional specialists compete on installation proximity and service responsiveness. Three archetypes dominate: integrated climate-control multinationals leveraging refrigerant innovation pipelines; European engineering houses specializing in borehole field design and thermal network integration; and Asian manufacturers scaling variable-capacity production for cost-sensitive markets. Consolidation pressure intensifies through strategic partnerships between OEMs and geothermal drilling contractors, alongside portfolio diversification into predictive maintenance software and energy-as-a-service contracting.
Among diversified climate-control conglomerates, Trane Technologies, Carrier Global Corporation, and Daikin Industries exemplify scale-driven positioning. Trane leverages its chiller engineering lineage to anchor large-scale commercial installation specifications. Carrier maintains contractor network density across North American metropolitan markets. Daikin concentrates variable-capacity system development for mixed-use buildings with asynchronous thermal loads. These three represent the premium-tier vector where refrigerant chemistry transitions and controls integration determine competitive viability.
| Leading Market Players |
|---|
| Trane Technologies |
| Carrier Global Corporation |
| Daikin Industries |
| Bosch Thermotechnology |
| Mitsubishi Electric |
| NIBE Industrier |
| Johnson Controls |
| Stiebel Eltron |
| Rheem Manufacturing |
| Others |
Supply Flow & Price Mechanics
Municipal utility procurement programs in Denmark, Germany, and Sweden anchor volume demand for district-scale water source heat pump installations, enforcing project-based long-term contracting with 15-year performance guarantees as the dominant pricing architecture. This buyer concentration compresses first-cost premiums while elevating lifecycle efficiency specifications as the primary price differentiation axis.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and controls integration depth. Premium tiers command positioning through UL 60335-2-40 safety validation and BACnet-native control architectures, while economy offerings compete on bare-unit transactional pricing for residential retrofits. Cost compression in the standard tier is intensifying because copper and rare earth magnet input volatility erodes OEM margins. Facility managers in commercial portfolios exhibit the lowest price sensitivity, prioritizing predictive maintenance bundling over first-cost minimization; residential homeowners in gas-subsidized markets remain most price-elastic.
Supply Chain Analysis
Dual-sourcing requirements for compressor motors and heat exchangers mandate multi-supplier qualification across China, Japan, and Germany manufacturing bases. Neodymium-iron-boron permanent magnets draw from Chinese rare earth processing concentration, while copper tubing supply rests on Chilean and Peruvian mining output. Single-source vulnerability in rare earth magnet supply chains creates exposure to export restriction risks. Distribution runs through authorized OEM dealer networks and Energy Service Company performance contracting channels, with direct procurement emerging for utility-scale district heating projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU F-Gas Regulation mandates and IRA manufacturing incentives are shifting procurement authority toward specification engineers who prioritize refrigerant chemistry certification and thermal network interoperability over legacy brand loyalty.
For Market Incumbents: Acquire geothermal drilling contractor capabilities to capture borehole field development margins and defend against European engineering houses encroaching on system integration scope. Backward integration into heat exchanger manufacturing in domestic IRA-credit-eligible facilities offsets tariff exposure on Chinese component imports. Prioritize R-290 propane and R-744 CO2 refrigerant platform certification ahead of EPA quota phase-down deadlines. For New Entrants and Emerging Players: Digital-channel specification tools targeting MEP engineers in Texas and Florida school district procurement offices bypass incumbent contractor network lock-in. Industrial waste heat recovery configurations for data center cooling loops represent the most penetrable white-space application, with hybrid system architectures enabling asynchronous load matching that pure ground-source competitors cannot address. Pursue performance contracting partnerships with municipal sustainability offices seeking off-balance-sheet financing structures. For Investors and Strategic Acquirers: Climate-control conglomerates with chiller heritage are the most active acquirers in this space, consolidating predictive maintenance software capabilities and geothermal drilling assets to capture full-project economics. Targets with ISO 13256-certified testing protocols and established F-Gas-compliant refrigerant architectures command premium positioning. Monitor EPA Section 608 technician certification expansion rates as the inflection signal for installer capacity constraints that would throttle volume growth.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R-290 and R-744 validation under UL 60335-2-40 secures EPA compliance ahead of HFC quota reductions. |
| Geothermal Drilling Integration | Capturing borehole field margins in Texas Permian Basin repurposing projects compresses competitor cost structures. |
| Predictive Maintenance Software | BACnet-integrated control algorithms extend service contract duration with facility manager procurement authority. |
| District Heating Network Partnership | Fourth-generation system integration in Stockholm and Copenhagen locks in baseload thermal supply contracts. |
| Domestic Manufacturing Footprint | IRA Section 48C credit capture for compressor assembly offsets Chinese rare earth magnet supply chain risk. |
Methodological Framework
Multiple input streams — OEM product manager interviews, geothermal drilling contractor field assessments, and utility procurement officer consultations — were reconciled against EU F-Gas Regulation implementation timelines and EPA AIM Act refrigerant phase-down schedules. Secondary validation drew from EIA building energy consumption surveys, IEA heat pump deployment tracking, and SEC filings from diversified climate-control conglomerates. Bottom-up project pipeline enumeration across Germany, the United States, and China was cross-checked against top-down market sizing from national building renovation program targets.
Historical installation data was cross-referenced against expert panel input from district heating network operators and MEP engineering specification leads. Segmentation modeling spanned thermal source type, installation scale, and end-user procurement authority across the projection horizon. CAGRs were derived from regression analysis of policy incentive intensity and drilling cost trajectories, with refrigerant chemistry transition timelines and copper price volatility scenarios as key sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for CO2 transcritical systems would alter the outlook if safety code revisions accelerate faster than anticipated. Deviation in EU member state building renovation enforcement rigor or IRA credit allocation continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Global Chiller Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Heat Pipe Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Solar Fan Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Offshore Air Handling Units Market