
 Wind Energy Equipment Logistics Market | 2026-2036
Wind Energy Equipment Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Energy Equipment Logistics Market Analysis
Market Context
China's coastal province manufacturing zones is reconfiguring how nacelles and blade molds reach domestic and export markets. DSV Panalpina A/S leverages its project cargo network across European offshore bases. Deutsche Post DHL Group anchors heavy-lift scheduling through dedicated wind terminals in Northern Europe. A.P. Møller - Mærsk A/S extends vessel-sharing agreements with turbine OEMs for trans-Atlantic blade movements.
Technical Definition and Segment Structure
Wind energy equipment logistics encompasses the specialized transport, lifting, staging, and installation coordination of components exceeding standard dimensional and weight thresholds, where blade lengths surpass 80 meters and nacelle masses exceed 300 metric tons. The discipline integrates marine heavy-lift, road permitting, and port consolidation to synchronize construction timelines for utility-scale wind farms. Turbine and blade segments dominate capital allocation within equipment type categories, driven by escalating rotor diameters and hub heights in offshore configurations. Project cargo and multi-modal approaches capture premium margin pools as developers demand single-contractor accountability across ocean, rail, and road legs.
Regulatory Environment
EU Green Deal implementation through national auction design is mandating local assembly quotas and port investment commitments across Germany, Denmark, and the Netherlands. The International Maritime Organization's carbon intensity regulations and port state controls under EU MRV are reshaping vessel charter terms for turbine transport. Stakeholders must monitor how evolving offshore lease stipulations and customs classifications for temporary importation of installation vessels alter total delivered cost structures.
Market Dynamics
Offshore wind developers in the North Sea are compressing installation windows from months to weeks, forcing logistics providers to synchronize heavy-lift vessel availability with turbine OEM production cycles at unprecedented precision.
Growth Catalysts
- EU Green Deal auction mechanisms:National tender designs in Germany and Denmark now mandate port infrastructure investment commitments, locking in multi-year logistics contracts before construction begins.
- Rotor diameter expansion:Blade lengths exceeding 100 meters require specialized road transport permits and marine heavy-lift coordination, creating premium service tiers for integrated project cargo operators.
- Netherlands port clustering:Rotterdam-Eemshaven corridor consolidation concentrates staging capacity for North Sea lease rounds, attracting turbine pre-assembly investment from OEMs.
Market Restraints
- Heavy-lift vessel scarcity:Purpose-built jack-up installation units face 18-24 month order backlogs at Asian shipyards, constraining deployment capacity for 2027-2028 lease commitments.
- Steel price volatility:Nacelle foundation components and vessel hull construction absorb commodity swings that compress logistics provider margins on fixed-price contracts.
- IMO carbon intensity regulations:EU MRV monitoring and CII rating thresholds are excluding older turbine transport vessels from charter pools serving North Sea projects.
Strategic Opportunities
- US offshore lease expansion:Vineyard Wind and Empire Wind developments along the Atlantic coast require trans-Atlantic blade logistics and dedicated US East Coast marshalling yards.
- Floating foundation logistics:Semi-submersible platform installation creates demand for dynamic positioning heavy-lift vessels and subsea mooring coordination services.
- Repowering wave in Germany:Onshore turbine replacement cycles in Lower Saxony open modular transport and rapid-installation service models for aging fleet upgrades.
Industry Challenges
- Marine coordination complexity:Synchronizing vessel charters with weather windows and turbine production delays demands real-time supply chain visibility tools most operators lack.
- Specialized crane operator certification:EU machinery directive compliance for 1,000-tonne capacity port cranes faces training pipeline gaps in Denmark and the Netherlands.
Report Scope
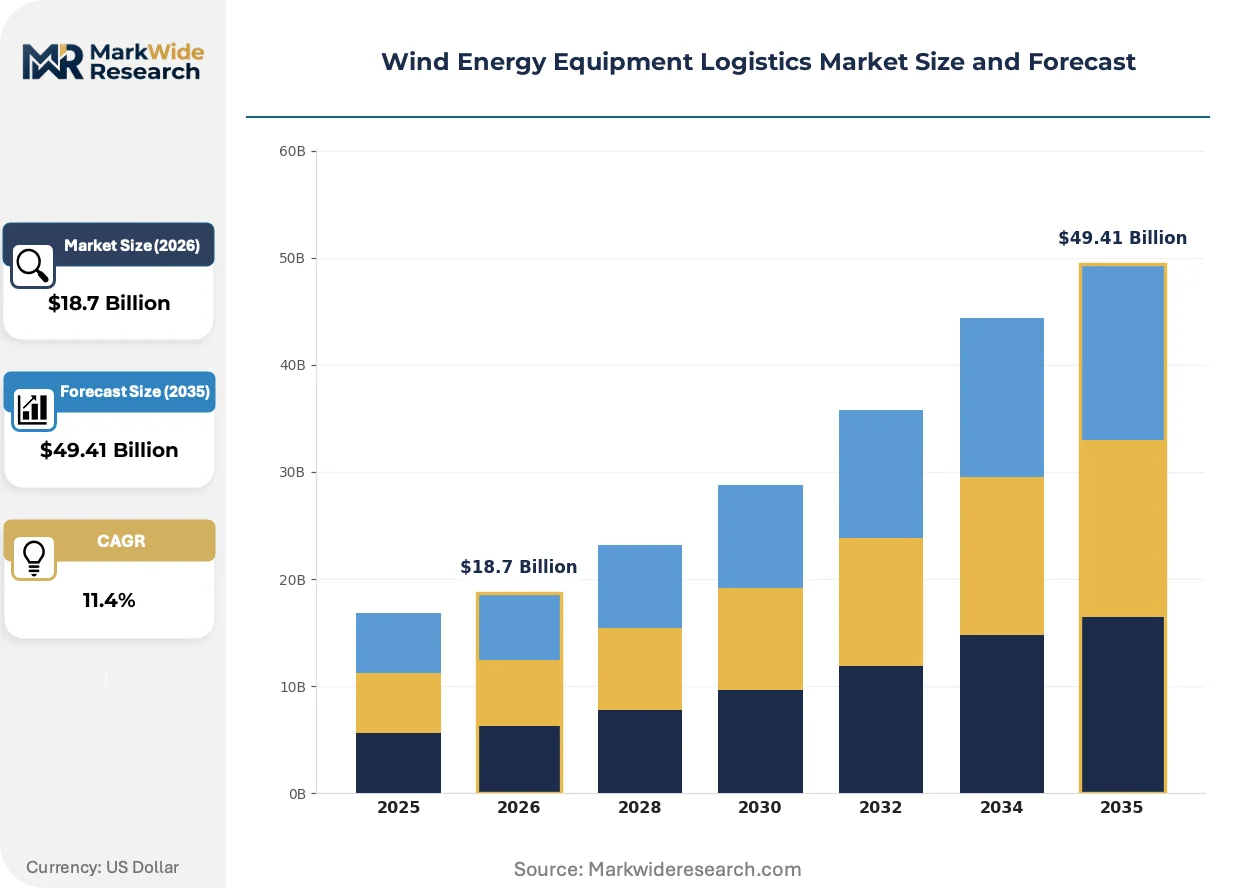
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Energy Equipment Logistics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Installation, Maintenance Equipment Type: Turbines, Blades, Towers, Generators Logistics Approach: Project Cargo, Just-in-Time, Dedicated Fleet, Multi-Modal End User: Developers, EPC Contractors, Utilities, Service Providers |
| Companies Covered | DSV Panalpina A/S, Schenker AG, Deutsche Post DHL Group, CEVA Logistics Inc., Nippon Express Co. Ltd., A.P. Møller - Mærsk A/S, C.H. Robinson Worldwide Inc., Expeditors International of Washington Inc., Federal Express Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Energy Equipment Logistics Market Emerging Trajectories
Digital twin technology and autonomous vessel positioning are compressing the traditional boundaries between marine engineering and port logistics planning in offshore wind construction.
Modular blade transport systems using segmented rail cars and telescopic road trailers are collapsing the distinction between factory gate and port quayside logistics. German turbine OEMs now specify these systems for all rotor deliveries to North Sea marshalling yards. The technology eliminates separate handling stages, compressing total transit time from production facility to installation vessel.
EU Green Deal implementation through national auction design is tightening local content thresholds for turbine assembly in Germany, Denmark, and the Netherlands. Developers must now demonstrate port investment and domestic logistics employment to qualify for subsidy support. Offshore project consortia are responding by signing multi-year terminal lease commitments before final investment decisions.
Integrated single-contractor procurement is displacing fragmented multi-vendor arrangements for turbine installation. Danish and German developers now demand turnkey accountability covering ocean, rail, and road legs from logistics providers. This consolidation concentrates risk with integrated operators while compressing coordination overhead for project sponsors managing North Sea construction schedules.
Wind Energy Equipment Logistics Market Segmentation
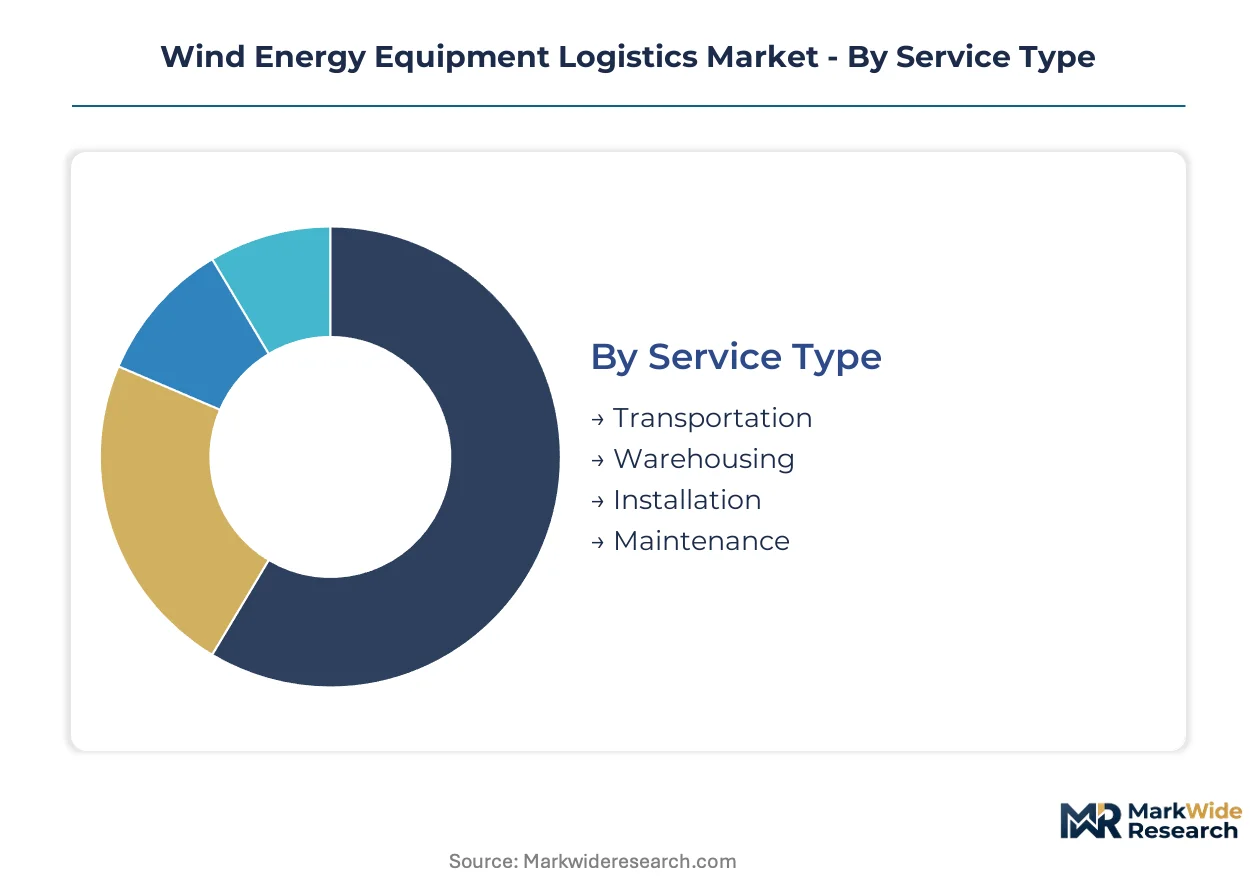
Wind energy equipment logistics demands precise alignment between component dimensions and specialized handling capabilities. Segmentation reveals how service providers structure capabilities around blade length thresholds, nacelle mass categories, and marine lift requirements. Each dimension creates distinct operational constraints that shape contract terms and margin profiles.
Service Type:
Mature transport operations coexist with emerging installation services as offshore scale accelerates.
- Transportation:Oversized road convoys and heavy-lift marine vessels move components exceeding 80-meter blade lengths and 300-tonne nacelle masses. Demand concentrates in Germany and Denmark where port clusters serve North Sea lease areas under EU Green Deal auction requirements.
- Installation:Jack-up vessel coordination and offshore heavy-lift sequencing synchronize turbine placement with weather windows. German and Danish developers now mandate single-contractor accountability across ocean-to-turbine delivery, compressing traditional multi-vendor timelines.
- Warehousing:Staging yards and pre-assembly facilities buffer OEM production cycles against vessel charter schedules.
- Maintenance:Component replacement logistics and spare parts positioning support operational wind fleets.
Transportation retains volume leadership; installation holds the steepest expansion curve.
Equipment Type:
Cost tier differentiation separates commodity tower segments from premium blade logistics requiring specialized handling systems.
- Blades:Rotor components exceeding 100 meters demand telescopic road trailers, segmented rail cars, and purpose-built marine cradles. German turbine OEMs now specify modular transport systems for all deliveries to North Sea marshalling yards, eliminating separate handling stages.
- Turbines:Nacelle assemblies integrating generator, gearbox, and hub components exceed 300 metric tons in offshore configurations. Rotterdam-Eemshaven corridor consolidation attracts pre-assembly investment from OEMs responding to Netherlands port clustering advantages.
- Towers:Steel tubular sections and transition pieces move via standard heavy-lift marine and road transport.
- Generators:Power conversion units require electrical protection protocols during transit and staging.
Blade logistics commands premium pricing tiers; turbine assemblies drive absolute tonnage volumes.
Logistics Approach:
Customer type preferences split between integrated project cargo procurement and fragmented point-to-point arrangements.
- Project Cargo:Single-contractor accountability spans ocean, rail, and road legs with unified risk allocation. Danish developers now demand turnkey coverage for North Sea construction schedules, concentrating risk with integrated operators.
- Multi-Modal:Synchronized mode transfers connect factory gates to installation vessels through dedicated wind terminals in Northern Europe. DSV Panalpina A/S and Deutsche Post DHL Group anchor heavy-lift scheduling across these corridors.
- Just-in-Time:Compressed inventory buffers align component arrival with installation vessel availability.
- Dedicated Fleet:Captive vessel and vehicle assets serve repeat developer relationships with fixed capacity commitments.
Project cargo captures margin premiums; multi-modal approaches scale fastest across developer portfolios.
End User:
Application urgency varies between greenfield developers facing lease commitments and utilities managing operational assets.
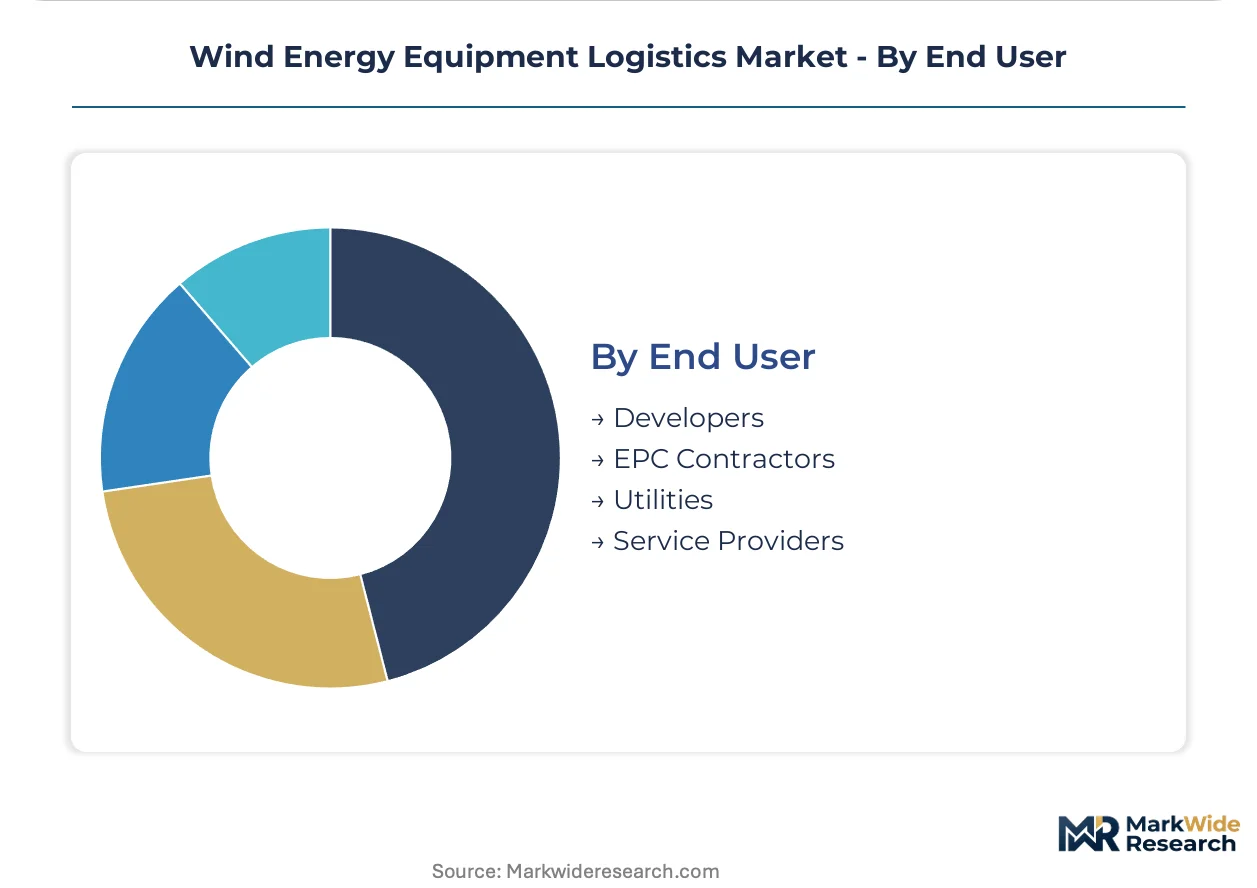
- Developers:Offshore wind farm sponsors procurement logistics through auction-tied contracts with port infrastructure investment mandates. Germany and Denmark now require domestic logistics employment demonstrations for subsidy qualification.
- EPC Contractors:Engineering-procurement-construction firms coordinate subcontractor logistics across turbine supply agreements.
- Utilities:Power generators integrate logistics into long-term service agreements for fleet maintenance.
- Service Providers:Independent operators offer specialized crane, vessel, and transport capacity on spot and term markets.
Developers drive capital expenditure allocation; EPC contractors shape operational procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys modular blade transport systems for factory-to-vessel delivery, while China routes nacelle exports through coastal manufacturing zones. The United States concentrates on Atlantic Coast marshalling yard construction for offshore lease rounds.
Germany
Lower Saxony repowering cycles and North Sea offshore commitments drive demand for rapid-installation logistics services. EU Green Deal auction mechanisms mandate port infrastructure investment and domestic logistics employment for subsidy qualification. The Eemshaven-Rostock corridor consolidates staging capacity where turbine OEMs pre-assemble rotor components.
China
Coastal province manufacturing zones in Jiangsu and Guangdong reconfigure nacelle and blade mold distribution for domestic and export markets. The country's dual carbon goals accelerate offshore wind construction timelines, compressing vessel charter windows. Yangtze River Delta port clusters integrate heavy-lift scheduling with turbine OEM production cycles.
United States
Vineyard Wind and Empire Wind developments along the Atlantic coast require trans-Atlantic blade logistics and dedicated East Coast marshalling yards. FERC offshore lease stipulations and Jones Act vessel requirements shape charter terms for turbine installation. New Bedford and Port of Providence anchor staging investment for Massachusetts and Rhode Island lease areas.
Denmark
Single-contractor procurement mandates across ocean-to-turbine delivery compress traditional multi-vendor timelines for North Sea construction. National auction designs require port infrastructure commitments before final investment decisions. Esbjerg port clustering attracts turbine pre-assembly investment from OEMs responding to logistics integration requirements.
Netherlands
Rotterdam-Eemshaven corridor consolidation concentrates staging capacity for North Sea lease rounds under EU MRV monitoring and CII rating thresholds. The port clustering advantage draws turbine pre-assembly investment from OEMs seeking integrated logistics solutions. Amsterdam IJmuiden expands heavy-lift terminal capacity to capture floating foundation logistics demand.
Wind Energy Equipment Logistics Market Vendor Landscape
Capability concentration sits with specialized project cargo operators; scale advantage sits with integrated logistics networks spanning ocean, rail, and road legs. The market structures around three tiers: global freight forwarders with dedicated wind terminals, regional heavy-lift specialists with captive vessel assets, and port-centric operators controlling marshalling yard capacity. Dominant competitive moves include strategic partnerships for vessel-sharing agreements and backward integration into port terminal operations.
Within the integrated network tier, Deutsche Post DHL Group and DSV Panalpina A/S exemplify operators anchoring heavy-lift scheduling through dedicated wind terminals in Northern Europe. A.P. Møller - Mærsk A/S occupies a position representing marine-heavy-lift scale advantage through vessel-sharing structures with turbine OEMs. These three entities illustrate how logistics providers concentrate risk while compressing coordination overhead for North Sea developers.
| Leading Market Players |
|---|
| DSV Panalpina A/S |
| Schenker AG |
| Deutsche Post DHL Group |
| CEVA Logistics Inc. |
| Nippon Express Co. Ltd. |
| A.P. Møller - Mærsk A/S |
| C.H. Robinson Worldwide Inc. |
| Expeditors International of Washington Inc. |
| Federal Express Corporation |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Eemshaven corridor concentrates heavy-lift vessel charter rates and port terminal fees, compressing margins for logistics providers while amplifying price differentiation between integrated project cargo operators and fragmented point-to-point vendors serving North Sea offshore developers.
Pricing Analysis
Long-term offtake contracts dominate procurement as German and Danish developers lock in multi-year terminal leases before final investment decisions. Pricing stratifies across integrated project cargo premiums, multi-modal standard tiers, and spot-market economy levels for fragmented road transport. Cost compression in the spot tier intensifies because steel price volatility and IMO carbon intensity regulations exclude older vessels from charter pools. EPC contractors exhibit highest price sensitivity due to fixed-price construction contracts, while integrated utilities accept premium pricing for single-contractor accountability.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk as nacelle and blade mold exports face potential customs reclassification. Manufacturing gravity centers on Jiangsu and Guangdong provinces for domestic turbine OEM production, with South Korean and Japanese shipyards supplying purpose-built jack-up installation vessels. The supply chain draws from specialized steel alloys, composite fiber materials, and marine engine systems. Single-source vulnerability concentrates at Asian shipyards facing 18-24 month order backlogs. Distribution runs through Rotterdam-Eemshaven corridor consolidation for North Sea lease rounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution by modular transport technology providers collapsing factory-to-vessel logistics stages, eroding traditional handling revenue pools.
For Market Incumbents: Pre-empt vessel-sharing agreement erosion by securing captive heavy-lift capacity at Rotterdam and Esbjerg terminals. Backward integration into port terminal operations locks in marshalling yard control before EU Green Deal auction commitments solidify competitor positions. Threat from autonomous vessel positioning technology demands real-time supply chain visibility platform investment as a defensive lever.
For New Entrants and Emerging Players: Floating foundation logistics for semi-submersible platform installation represents the most penetrable entry point, with Amsterdam IJmuiden expanding heavy-lift terminal capacity to capture this demand. US Atlantic Coast marshalling yard construction for Vineyard Wind and Empire Wind developments offers second-mover advantage absent entrenched European operators. Go-to-market angle: dynamic positioning heavy-lift vessel charter brokerage bridging Asian shipyard output and US offshore lease timelines.
For Investors and Strategic Acquirers: Regional heavy-lift specialists with captive jack-up vessel assets and established port terminal relationships offer acquisition profiles aligned with long-term offshore wind infrastructure buildout. Viability rests on 5-10 year visibility into North Sea lease commitment pipelines and EU MRV regulatory trajectory. Signal to watch: turbine OEM pre-assembly investment location decisions relative to port clustering advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Vessel-Sharing Agreement Expansion | Maersk's turbine OEM partnerships demonstrate how marine capacity pooling compresses trans-Atlantic blade movement costs. |
| Port Terminal Backward Integration | DSV Panalpina's dedicated wind terminals in Northern Europe anchor heavy-lift scheduling control against fragmented competitors. |
| Modular Transport Technology Deployment | German OEM specifications for telescopic road trailers eliminate handling stages and compress factory-to-vessel transit windows. |
| Floating Foundation Logistics Capability | Dynamic positioning vessel chartering captures semi-submersible platform installation demand outside traditional jack-up markets. |
| Digital Twin Platform Investment | Real-time supply chain visibility tools address marine coordination complexity gaps most operators currently exhibit. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with offshore wind developers, EPC contractor logistics directors, heavy-lift vessel charter brokers, port terminal operators, and turbine OEM supply chain managers. Secondary validation drew from EU MRV vessel monitoring data, FERC offshore lease filings, IEA renewable energy project databases, and national auction mechanism documentation in Germany and Denmark. Bottom-up component demand modeling and top-down infrastructure investment flow analysis were triangulated to calibrate market sizing.
Calibration against historical vessel charter rate movements and port capacity utilization patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, equipment category, logistics approach, and end-user archetype, with regional regulatory framework clusters as an additional wind-specific dimension. CAGRs were derived from lease commitment pipeline analysis and OEM production cycle synchronization requirements, incorporating blade length expansion trajectories and nacelle mass escalation curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in steel commodity prices, offshore wind auction clearing prices, or marine fuel cost indices would shift the trajectory. Forecasts reflect documented assumptions regarding vessel delivery schedules from Asian shipyards and EU Green Deal implementation pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market