
 Boat Wind Turbine Market | 2026-2036
Boat Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Wind Turbine Market Insights
DNV GL's type-approval certification for marine wind turbines is bifurcating the competitive landscape into qualified suppliers and aspirants. Siemens Gamesa Renewable Energy leverages its offshore wind heritage to anchor credibility in vessel-integrated systems. Goldwind Science & Technology competes through cost-engineered horizontal-axis units optimized for salt-air corrosion resistance. Vestas Wind Systems sustains technology leadership via modular blade designs that reduce deck footprint on commercial vessels.
A boat wind turbine converts kinetic wind energy into electrical power through rotor-driven generators mounted on maritime platforms, typically producing 100W to 5kW for auxiliary loads or battery charging via permanent-magnet synchronous generators with marine-grade coatings. Horizontal axis configurations dominate current installations due to higher aerodynamic efficiency at vessel cruising speeds, while hybrid models combining wind and solar capture are gaining traction among research vessels requiring uninterrupted off-grid power. The 500W to 1kW power rating segment occupies the thickest margin pool, balancing sufficient output for electronics and lighting against manageable structural loads on mid-sized commercial craft.
The International Maritime Organization's Energy Efficiency Existing Ship Index and the EU's Monitoring, Reporting and Verification framework are tightening emissions accountability, directly stimulating retrofit demand for auxiliary wind power across European-flagged fleets. The US Coast Guard's electrical system standards for inspected vessels shape product safety requirements, while China's GB/T wind turbine standards under SAMR oversight govern export certification for Asian manufacturers. Stakeholders must monitor how pending MARPOL amendments treat wind-assisted propulsion in carbon intensity calculations, as this classification will determine whether boat turbines qualify for compliance credits or remain discretionary efficiency investments.
Market Dynamics
The International Maritime Organization's Energy Efficiency Existing Ship Index is forcing commercial vessel operators to install auxiliary renewable power systems, creating retrofit demand that outpaces new-build specifications and concentrating supplier attention on salt-air corrosion resistance and compact deck footprints.
Growth Catalysts
- EU Green Deal maritime decarbonization mandates:The EU Green Deal's binding emissions reduction targets for European-registered fleets are accelerating type-approval certification for onboard wind energy systems as compliance pathways harden.
- Diesel-electric hybridization:Commercial operators on long-haul routes are expanding wind turbine deployment to supplement conventional propulsion and reduce bunker fuel consumption during steady-state cruising.
- North Sea and Baltic port clustering:Shipyards and turbine specialists concentrate around Hamburg, Copenhagen, and Rotterdam, creating integrated supply chains that lower installation costs and technical risk for regional fleet operators.
Market Restraints
- Permanent-magnet generator cost volatility:Rare-earth element price swings for neodymium and dysprosium directly impact permanent-magnet synchronous generator economics, compressing margins on sub-1kW units.
- Deck load structural limitations:Mid-sized commercial craft face payload constraints that restrict turbine mass and rotor diameter, capping power output below vessel auxiliary demand thresholds.
- MARPOL amendment uncertainty:Pending carbon intensity calculation methodologies for wind-assisted propulsion create compliance credit ambiguity, delaying capital commitment from risk-averse fleet managers.
Strategic Opportunities
- Research vessel hybridization:Scientific fleets requiring uninterrupted off-grid power represent an emerging application segment for wind-solar hybrid configurations with battery integration.
- US Coast Guard electrical standards alignment:Compliance with USCG inspected vessel safety requirements opens access to American-flagged commercial and government maritime contracts.
- Horizontal-vertical axis convergence:Technology pairing of horizontal-axis efficiency at cruising speeds with vertical-axis low-wind performance is creating modular retrofit kits for variable route profiles.
Industry Challenges
- DNV GL type-approval timeline compression:Marine certification cycles for turbine structural integrity and electrical safety extend 18-24 months, delaying revenue recognition for qualified suppliers and aspirants alike.
- Marine-grade coating application skill scarcity:Specialized corrosion protection for salt-air environments requires trained applicators concentrated in Northern European shipyards, creating installation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Wind Turbine Market |
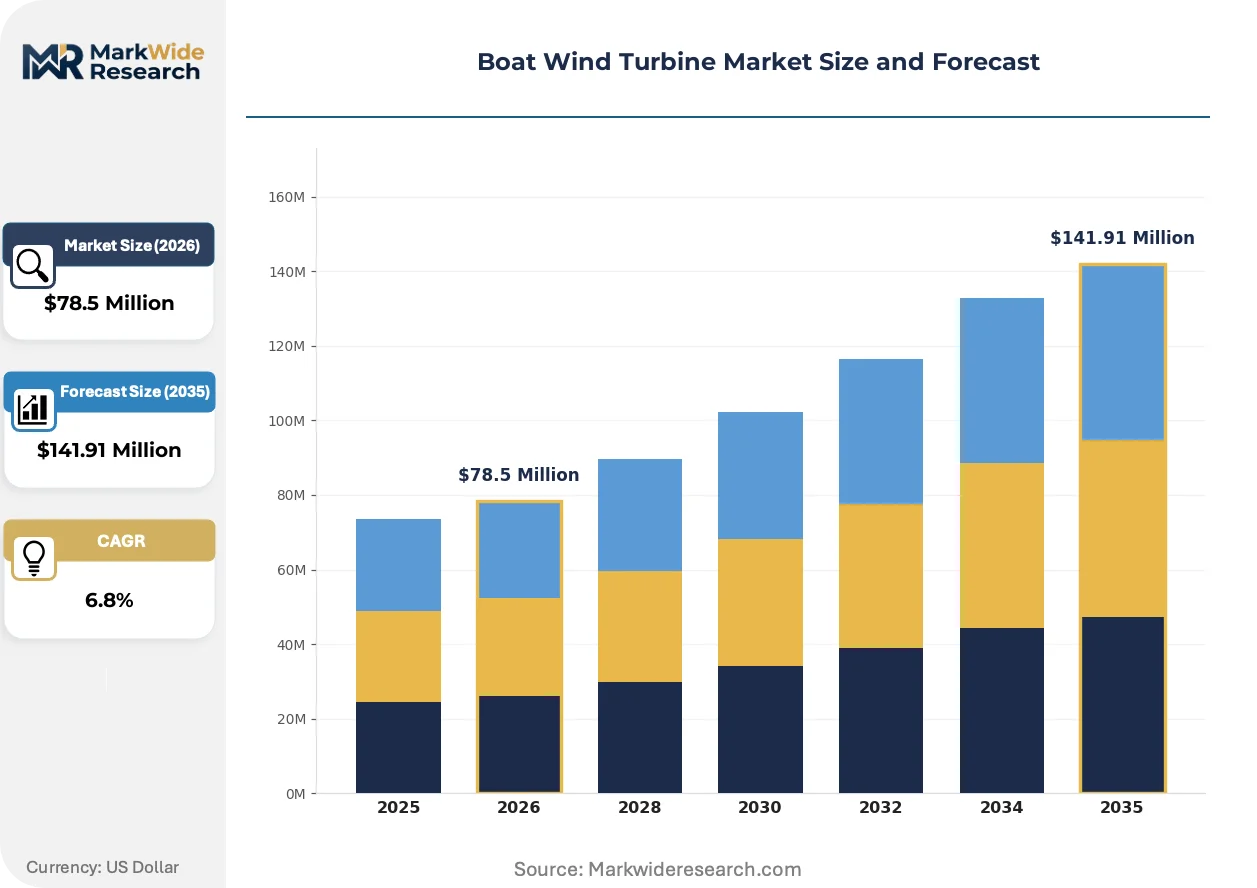
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $141.91 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Axis, Horizontal Axis, Hybrid Model, Portable Application: Recreational Boats, Commercial Vessels, Research Vessels, Sailing Yachts Power Rating: Up to 100W, 100W to 500W, 500W to 1kW, Above 1kW Installation: Deck Mount, Mast Mount, Hull Integrated, Temporary |
| Companies Covered | Siemens Gamesa Renewable Energy, Vestas Wind Systems, GE Vernova, Goldwind Science & Technology, Mingyang Smart Energy, Nordex SE, ENERCON GmbH, Envision Energy, Senvion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Wind Turbine Market Trends and Innovations
Permanent-magnet generator architecture is actively compressing unit dimensions while maintaining output density, enabling deployment on vessel classes previously excluded by deck footprint constraints. Three interconnected developments are reshaping product roadmaps and procurement patterns.
Permanent-magnet synchronous generator technology is miniaturizing through advanced magnetic circuit design and high-temperature superconductor research. Research vessels and offshore support craft are adopting these compact units for auxiliary load management. The structural consequence is a compression of minimum viable vessel size for turbine economics, expanding addressable fleet population.
REACH regulation substance restrictions on marine coatings are forcing reformulation of blade and housing protection systems. Manufacturers must eliminate legacy chromate-based primers and migrate to compliant zinc-rich and ceramic alternatives. European-flagged fleets face the most immediate compliance deadlines, driving preference for pre-certified coating packages.
Retrofit procurement is consolidating around turnkey installation contracts bundling turbine supply, structural engineering, and electrical integration. Shipowners are displacing component sourcing in favor of single-vessel responsibility models. This pattern is most visible in German and Danish commercial fleets where yard downtime costs dominate total ownership calculations.
Boat Wind Turbine Market Segmentation
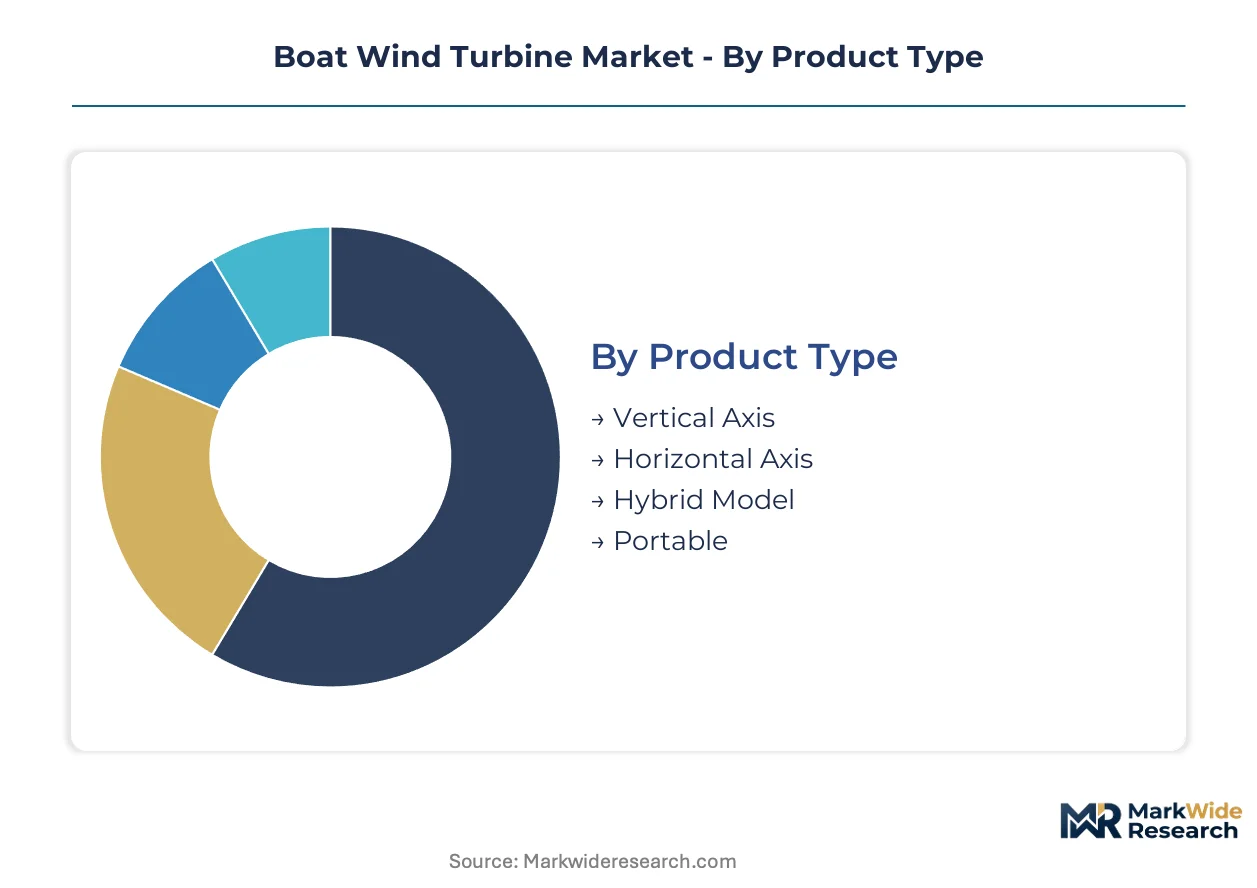
Segmentation in the boat wind turbine market determines installation feasibility, regulatory pathway, and total cost of ownership across vessel classes. Procurement patterns diverge sharply between retrofit operators seeking minimal deck modification and new-build specifiers integrating turbines into hybrid propulsion architectures.
Product Type:
Channel flow splits between marine distributors stocking standardized horizontal-axis units and shipyard-direct procurement of certified vertical-axis and hybrid systems for commercial fleets.
- Horizontal Axis:Rotor blades rotate around a horizontal shaft perpendicular to wind direction, delivering higher aerodynamic efficiency at vessel cruising speeds. German and Danish commercial operators on North Sea routes specify these for diesel-electric hybridization, though DNV GL certification cycles extend 18-24 months. Mast-mounted configurations dominate this segment.
- Vertical Axis:Darrieus or Savonius designs capture wind from any direction without yaw mechanisms, reducing mechanical complexity for recreational users. Demand concentrates in Baltic ports where variable wind patterns and smaller craft predominate; lower efficiency caps adoption on cargo vessels.
- Hybrid Model:Wind-solar combinations serve research vessels requiring uninterrupted off-grid power through battery integration.
- Portable:Clamp-on or suction-mounted units target transient power needs on charter fleets and small craft.
Horizontal axis dominates installed base. Hybrid models are where expansion concentrates.
Application:
Cost tiering separates premium-certified systems for commercial compliance from economy-grade recreational equipment sold through marine retail channels.
- Commercial Vessels:Cargo ships, tankers, and fishing fleets install turbines as auxiliary power for electronics, lighting, and battery charging to reduce bunker fuel consumption. EU Green Deal mandates are accelerating type-approval procurement for European-registered fleets, with Hamburg and Rotterdam shipyards bundling turnkey installations.
- Research Vessels:Scientific fleets require continuous power for sensor arrays and communication equipment during extended off-grid operations. Wind-solar hybrid configurations with permanent-magnet synchronous generators are gaining preference for payload efficiency.
- Recreational Boats:Weekend cruisers and coastal fishers purchase sub-500W units through marine chandleries for battery maintenance and small electronics.
- Sailing Yachts:Long-distance cruisers value redundancy for autopilot and navigation systems on ocean passages.
Commercial vessels dominate installed base. Research vessels are where expansion concentrates.
Power Rating:
Volume concentration sits in the 500W to 1kW band where output sufficiency meets manageable structural loads, while sub-100W units serve price-sensitive recreational entry points.
- 500W to 1kW:Balances auxiliary load coverage for mid-sized commercial craft against deck load constraints. This band captures the thickest margin pool as operators seek sufficient output for electronics and lighting without exceeding payload limits on vessels under 500 gross tons.
- Above 1kW:Large cargo vessels and offshore support craft deploy these units for substantial battery charging and hybrid propulsion support. Rare-earth magnet cost volatility for permanent-magnet generators compresses margins, limiting supplier participation.
- 100W to 500W:Coastal commercial craft and larger recreational boats specify these for modest auxiliary loads.
- Up to 100W:Battery trickle charging for moored vessels and emergency backup applications.
500W to 1kW dominates installed base. Above 1kW is where expansion concentrates.
Installation:
Maturity gradients separate established deck-mount retrofits from emerging hull-integrated designs requiring naval architecture collaboration.
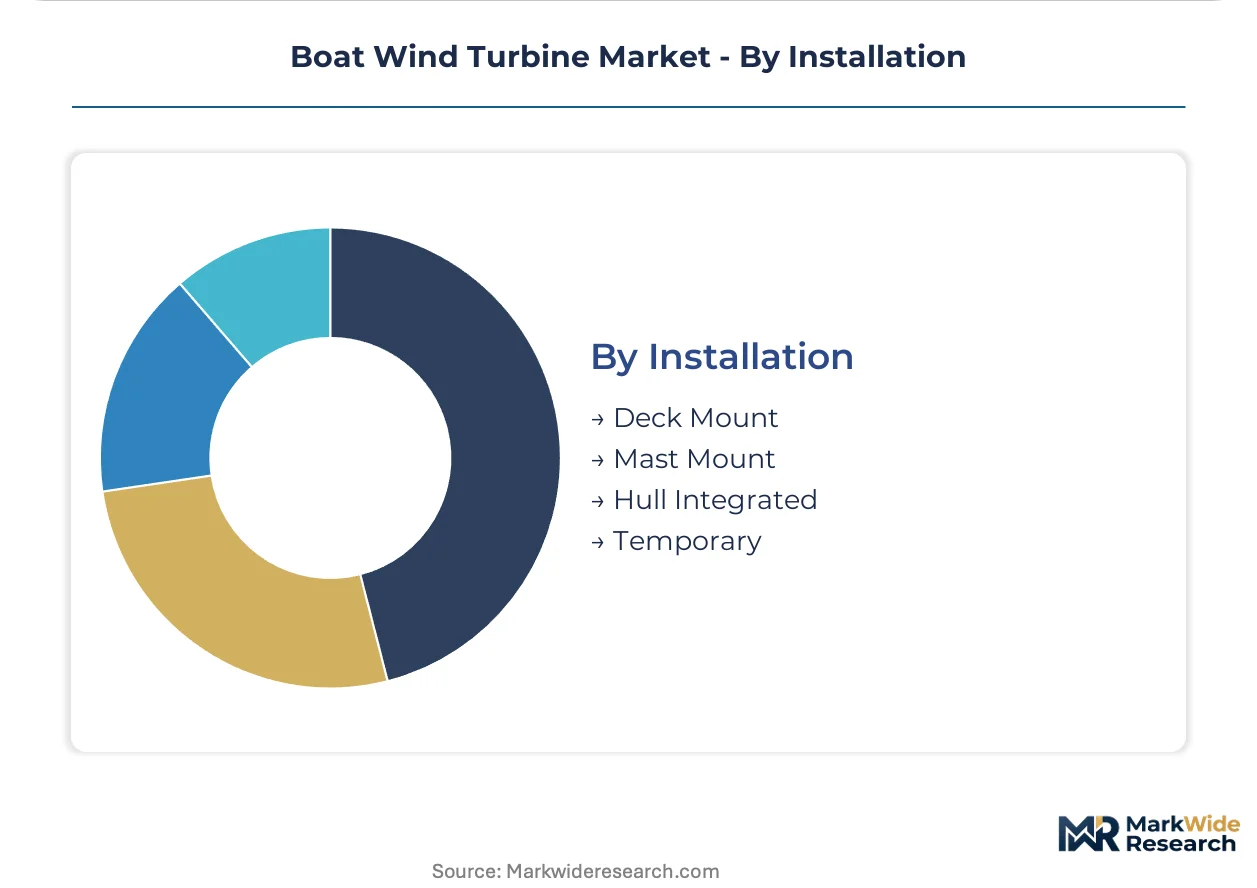
- Deck Mount:Bolted platforms on cargo hatches or aft decks enable retrofit without structural modification. German and Danish fleets favor this approach for minimal yard downtime, though rotor diameter faces payload constraints.
- Mast Mount:Elevated positioning captures cleaner airflow above superstructure turbulence. Sailing yachts and research vessels specify these configurations, requiring analysis of mast stress and guy-wire loads.
- Hull Integrated:Flush or semi-flush turbine housings built into vessel superstructure during new construction. Shipyards in Hamburg and Copenhagen are developing standardized interfaces for this emerging approach.
- Temporary:Suction or clamp systems for seasonal use and charter fleet flexibility.
Deck mount dominates installed base. Hull integrated is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's binding maritime decarbonization targets are reshaping procurement patterns across coastal economies. National regulators are translating bloc-wide emissions mandates into vessel-specific compliance pathways, concentrating installation demand near established marine engineering clusters.
Germany
Hamburg and Bremerhaven shipyards are bundling turnkey turbine installations for North Sea commercial fleets. The Federal Maritime and Hydrographic Agency enforces DNV GL-aligned certification for auxiliary renewable power systems. Kiel's marine engineering ecosystem anchors salt-air corrosion research and permanent-magnet generator testing facilities serving Baltic and North Sea operators.
Denmark
Copenhagen-Malmö cross-border port infrastructure supports integrated supply chains for diesel-electric hybridization projects. The Danish Maritime Authority fast-tracks type-approval for EU Green Deal compliance pathways. Esbjerg's offshore wind heritage cluster is pivoting expertise toward vessel-integrated systems for North Sea cargo routes.
Netherlands
Rotterdam's port authority mandates auxiliary renewable power for terminal-assigned fleets under municipal emissions protocols. The Human Environment and Transport Inspectorate coordinates with DNV GL on marine turbine safety standards. Delft's naval architecture programs are prototyping hull-integrated turbine housings for new-build specifications.
United Kingdom
Aberdeen and Hull maritime service bases are retrofitting offshore support craft with hybrid wind-solar configurations. The Maritime and Coastguard Agency enforces electrical system standards that shape product safety requirements for British-flagged vessels. Southampton's shipyard networks are developing modular deck-mount kits for fishing fleet compliance upgrades.
China
Shanghai and Guangzhou shipyards are certifying export-bound turbines under SAMR-overseen GB/T standards for Asian manufacturer compliance. The Ministry of Industry and Information Technology coordinates dual carbon goals with maritime equipment export incentives. Qingdao's marine engineering corridor is scaling permanent-magnet synchronous generator production for cost-engineered horizontal-axis units.
Boat Wind Turbine Market Competitive Landscape
Player mix skews toward diversified renewable energy conglomerates with offshore wind heritage. The supplier base concentrates around Northern European engineering centers and Chinese manufacturing corridors. Three archetypes dominate: certification-heavy marine specialists, cost-optimized volume fabricators, and hybrid technology integrators. Competitive moves center on DNV GL type-approval acquisition and turnkey installation contract consolidation.
Among diversified renewable conglomerates, Siemens Gamesa Renewable Energy and Vestas Wind Systems occupy positions leveraging offshore wind credibility for vessel-integrated credibility. Goldwind Science & Technology exemplifies the cost-engineered archetype with horizontal-axis units optimized for salt-air environments. These three anchors illustrate how certification timelines and manufacturing geography are bifurcating qualified suppliers from aspirants in marine-specific procurement.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| GE Vernova |
| Goldwind Science & Technology |
| Mingyang Smart Energy |
| Nordex SE |
| ENERCON GmbH |
| Envision Energy |
| Senvion |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month DNV GL certification cycles compress supplier margins and concentrate pricing power among pre-qualified incumbents while forcing aspirants to absorb extended inventory carrying costs before revenue recognition. This lead-time structure anchors premium tiering to certification status rather than manufacturing scale alone.
Pricing Analysis
Certification level creates the primary spread between premium DNV GL-approved systems and economy-grade recreational units lacking marine-grade validation. Three-tier pricing structure across premium certified, standard compliant, and economy recreational levels reflects differential after-sales bundling and installation support. Pricing pressure stems from rare-earth magnet cost volatility in permanent-magnet generators, compressing margins on sub-1kW units. Commercial fleet operators exhibit lowest price sensitivity due to EU Green Deal compliance mandates, while recreational buyers in Baltic ports drive hard negotiation on portable clamp-on configurations.
Supply Chain Analysis
Germany and Denmark anchor marine-grade coating application and permanent-magnet generator testing facilities serving North Sea and Baltic operators. China feeds cost-engineered horizontal-axis turbine production from Shanghai and Guangzhou shipyards under SAMR-overseen GB/T standards. Rare-earth element sourcing for neodymium and dysprosium draws from concentrated mining jurisdictions, creating single-source vulnerability for permanent-magnet synchronous generator supply. Distribution runs through Hamburg, Copenhagen, and Rotterdam shipyard-direct channels bundling turnkey installation contracts rather than component retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boat wind turbine market sits as a high-growth regulatory disruption driven by EU Green Deal maritime decarbonization mandates forcing auxiliary renewable power installation across European-flagged fleets.
For Market Incumbents: Shield installed base relationships by accelerating hull-integrated system development with Hamburg and Copenhagen shipyards before aspirants clear DNV GL certification. Deepen backward integration into permanent-magnet generator supply to offset rare-earth price volatility compressing sub-1kW margins. Prioritize turnkey installation contract consolidation to displace component sourcing patterns among risk-averse fleet managers. For New Entrants and Emerging Players: DNV GL fast-track certification for research vessel wind-solar hybrid configurations opens immediate white-space access before commercial fleet procurement hardens around incumbent relationships. Target US Coast Guard electrical standards alignment for American-flagged government and commercial contracts where marine-certified supplier scarcity persists. Lead with modular deck-mount retrofit kits minimizing yard downtime for mid-sized Baltic commercial craft. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because IMO Energy Efficiency Existing Ship Index tightening and pending MARPOL amendments will progressively mandate auxiliary renewable power across global fleets. Acquisition candidates with DNV GL type-approval and established Northern European shipyard relationships command defensive positioning. Monitor MARPOL carbon intensity calculation methodology finalization as the signal determining whether wind-assisted propulsion qualifies for compliance credits or remains discretionary.| Strategic Initiative | Industry Significance |
|---|---|
| DNV GL Type-Approval Acceleration | Compresses 18-24 month certification cycles to capture EU Green Deal compliance window. |
| Permanent-Magnet Generator Backward Integration | Captive neodymium-dysprosium supply hedges rare-earth cost volatility in sub-1kW units. |
| Hull-Integrated System Development | Delft naval architecture collaboration prototypes new-build turbine housing interfaces. |
| US Coast Guard Standards Alignment | Opens American-flagged commercial and government maritime contract access. |
| Turnkey Installation Contract Consolidation | Hamburg and Rotterdam bundling displaces component sourcing for fleet operators. |
Research Methodology
A standing panel of shipyard procurement directors, fleet operations managers, marine certification engineers, and permanent-magnet generator R&D leads provided ongoing calibration across primary interview cycles. Secondary validation drew from DNV GL certification registries, EU MRV emissions databases, SAMR GB/T standard filings, and Hamburg-Bremerhaven port authority procurement records. Bottom-up vessel-class demand modeling triangulated against top-down regulatory mandate impact assessment.
Consistency checks against IEA maritime energy transition benchmarks and EEA shipping emissions inventories validated volume and value outputs across the analysis window. Segmentation modeling incorporated product type, application class, power rating tier, and installation configuration dimensions. CAGRs derived from regression analysis of historical retrofit penetration rates and new-build specification trends, with permanent-magnet generator cost curves and EU Green Deal enforcement timelines as key industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and stable rare-earth supply; material deviation in MARPOL amendment treatment of wind-assisted propulsion would warrant model refresh. Recalibration cycles align with material shifts in IMO regulatory frameworks and permanent-magnet generator input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market