
 Global Marine Wind Turbine Market | 2026-2036
Global Marine Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Wind Turbine Market Intelligence
Performance specification for deep-water applications is decoupling from the cost-optimization focus of near-shore turbine models. European manufacturers like Siemens Gamesa Renewable Energy lead in developing high-capacity, direct-drive turbines for harsh offshore environments. Vestas competes on a similar technological front, emphasizing reliability and service life. In contrast, Goldwind leverages its scale to dominate the rapidly expanding Chinese domestic market with cost-effective solutions.
A marine wind turbine is an apparatus designed to convert wind's kinetic energy into electrical power in offshore settings, often featuring rotor diameters exceeding 200 meters and power ratings above 12 MW. Its primary purpose is large-scale energy generation for grid supply. While fixed-bottom foundations constitute the majority of current installations, the floating turbine segment represents the fastest-growing category, enabling development in deeper waters. Utility companies remain the principal end-users, procuring turbines for extensive offshore wind farm projects.
Regulatory frameworks such as the EU's CE marking and China's GB standards mandate specific safety and performance criteria for turbines. Environmental assessments, guided by bodies like the US EPA, govern site selection and operational permits, directly impacting project timelines. The key decision for manufacturers now revolves around allocating capital between maturing fixed-bottom supply chains and pioneering next-generation floating platform technologies.
Market Dynamics
The primary structural force is the technological divergence between cost-optimized near-shore turbines and performance-driven deep-water models. This split is driven by utility companies' pursuit of massive, grid-scale power generation from harsh offshore environments, demanding larger and more resilient turbine platforms.
Growth Catalysts
- National Energy Policies:Frameworks like the EU Green Deal and China's dual carbon goals establish binding targets that accelerate the deployment of large-scale offshore wind projects.
- Utility Demand Concentration:Utility companies are commissioning extensive wind farms in high-potential zones like the North Sea and off China's coast to meet grid-scale energy needs.
- Floating Turbine Technology:Innovations in floating platforms unlock access to deep-water sites with stronger wind resources, expanding the geographic scope for development beyond near-shore areas.
Market Restraints
- High Capital Intensity:The substantial upfront investment required for deep-water foundations, subsea cables, and grid integration infrastructure presents a significant financial barrier for new projects.
- Specialized Component Bottlenecks:Supply chains for critical components, such as multi-megawatt nacelles and blades exceeding 100 meters, are highly concentrated and face production capacity constraints.
- Lengthy Permitting Cycles:Environmental assessments governed by bodies like the US Environmental Protection Agency (EPA) involve complex, multi-year approval processes that can delay project timelines.
Strategic Opportunities
- New Geographic Markets:Significant potential exists in developing offshore wind capacity in underpenetrated regions, including the US East Coast, Taiwan, and South Korea, beyond the established European and Chinese markets.
- Green Hydrogen Integration:Co-locating offshore wind farms with electrolyzer facilities offers a direct pathway to produce green hydrogen at scale, creating a new offtake market for renewable power.
- Digital Twin and AI Analytics:Deploying advanced predictive maintenance platforms using AI and digital twins can optimize turbine performance, reduce O&M costs, and extend the operational lifespan of assets.
Industry Challenges
- Specialized Labor Scarcity:A shortage of qualified technicians and engineers with expertise in offshore installation, commissioning, and maintenance hinders the sector's ability to scale operations rapidly.
- Port Infrastructure Deficiencies:Many existing ports lack the quay strength, laydown area, and heavy-lift crane capacity required to handle the assembly and load-out of next-generation 15+ MW turbines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Wind Turbine Market |
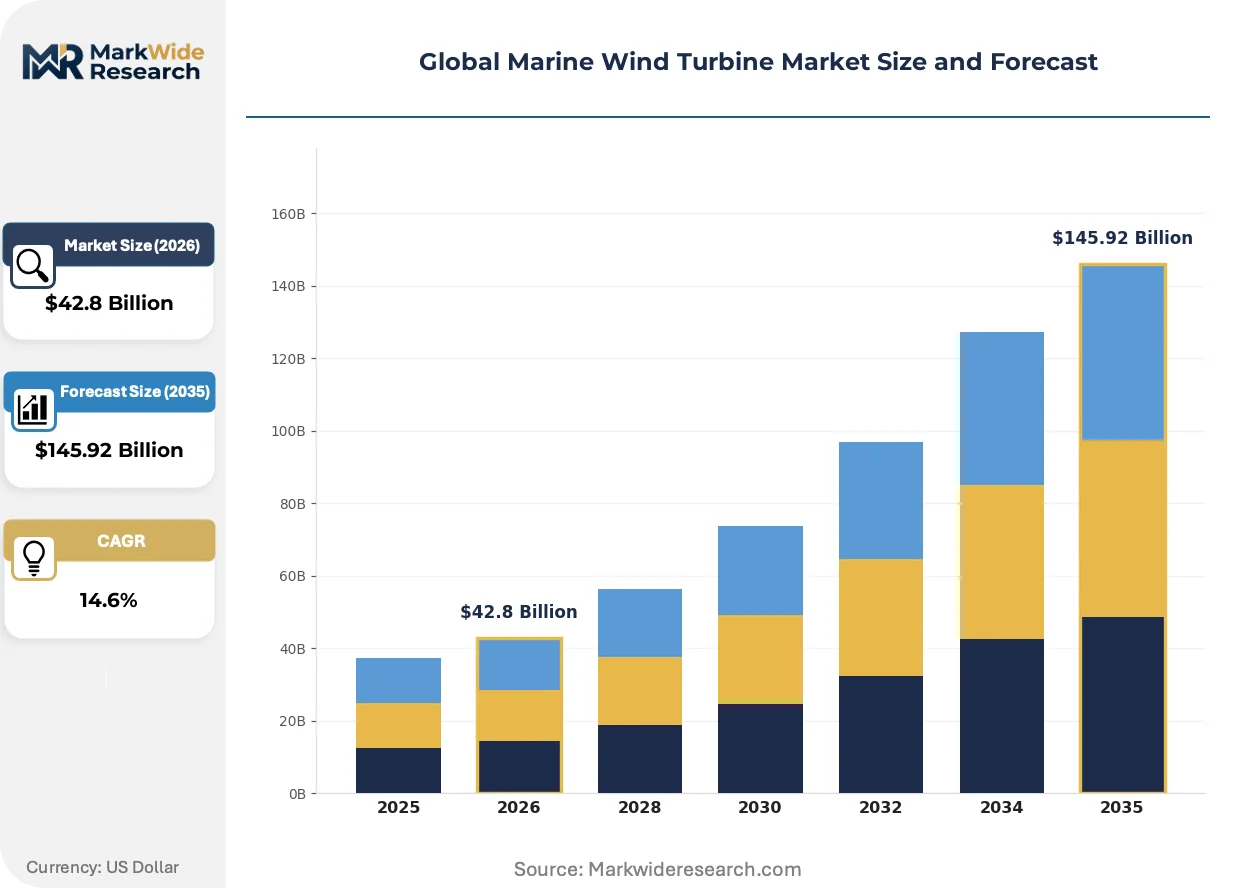
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $145.92 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Bottom, Floating, Semi-Submersible, Spar Buoy Technology: Direct Drive, Gearbox Drive, Hydraulic, Magnetic Bearing Application: Energy Generation, Grid Integration, Off-Grid Power, Hybrid Systems End User: Utility Companies, Renewable Energy Developers, Maritime Operators, Research Institutes |
| Companies Covered | SANY Group, Dongfang Electric, Mingyang Smart Energy, Suzlon Energy, Goldwind, Siemens Gamesa Renewable Energy, Envision Energy, GE Wind Energy, Vestas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Wind Turbine Market Strategic Shifts & Innovations
Technological upscaling is the defining theme, as turbine designs push physical and material limits to maximize energy capture. This evolution is closely tied to regulatory frameworks that mandate higher performance and safety standards for accessing key offshore markets. These forces together are reshaping product specifications.
Direct-drive generator technology improves turbine reliability by removing the gearbox, a common point of failure in harsh offshore conditions. Utility operators are specifying these systems for most new deep-water projects to minimize costly maintenance interventions. This technological preference is consolidating direct-drive as the dominant architecture for high-capacity turbines destined for remote offshore wind farms.
The EU's CE marking framework imposes rigorous design, safety, and manufacturing criteria on all wind turbines sold within the European market. This regulation requires extensive documentation and third-party verification, adding complexity and cost to the supply chain. The fixed-bottom turbine segment is most affected, as component suppliers must ensure full compliance to participate in North Sea projects.
A notable change in energy offtake involves the rise of Corporate Power Purchase Agreements (PPAs) for offshore wind. This model allows large corporations to contract directly with developers for long-term renewable energy supply, diversifying the customer base beyond utilities. This pattern is particularly strong in Europe, where corporate sustainability mandates are directly influencing energy procurement decisions.
Global Marine Wind Turbine Market Segmentation
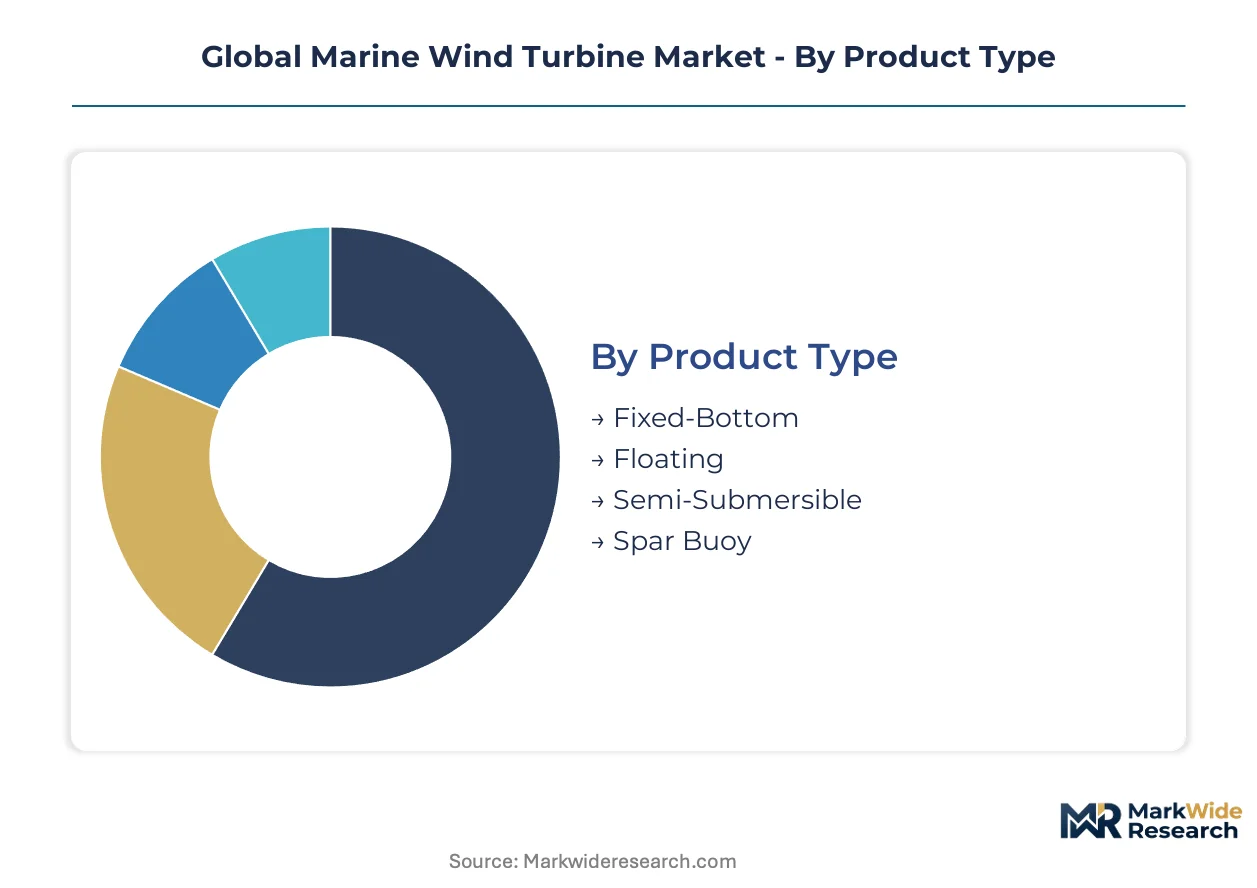
Understanding the market segmentation for marine wind turbines reveals how diverse technical requirements and operational environments shape product development and end-user adoption. This analysis highlights the distinct characteristics that differentiate offerings across the global landscape.
Product Type:
The choice of product type for marine wind turbines is primarily driven by water depth and seabed conditions, influencing installation complexity and overall project cost.
- Fixed-Bottom:These turbines are anchored directly to the seabed, offering a mature technology solution for shallow to intermediate waters. Demand from utility companies concentrates in the North Sea region and China's coastal provinces due to established infrastructure and favorable bathymetry.
- Floating:Supporting turbines in deep-water locations, floating platforms unlock access to stronger, more consistent wind resources beyond continental shelves. This segment represents the fastest-growing category, with significant project development underway off the US East Coast and in Taiwan.
- Semi-Submersible:This foundation type utilizes multiple columns and pontoons for stability, making it suitable for intermediate to deep-water depths where fixed-bottom solutions become uneconomical.
- Spar Buoy:Characterized by a large, ballasted cylindrical structure with a deep draft, spar buoys provide stability in very deep offshore locations, minimizing motion from waves.
Fixed-Bottom leads on scale; Floating leads on momentum.
Technology:
Performance requirements and long-term operational reliability dictate the selection of specific turbine drive technologies in offshore environments.
- Direct Drive:This technology eliminates the need for a gearbox, directly connecting the rotor to the generator, which significantly improves reliability and reduces maintenance interventions in harsh offshore conditions. European manufacturers like Siemens Gamesa Renewable Energy prioritize direct drive for high-capacity deep-water models.
- Gearbox Drive:Employing a gearbox to increase generator speed, this traditional design offers a well-established manufacturing base and often presents a lower initial capital expenditure. Cost-optimized near-shore projects in various global regions frequently specify gearbox-driven turbines.
- Hydraulic:These systems use hydraulic fluid to transfer power from the rotor to the generator, offering flexibility in turbine design and potentially smoother power output.
- Magnetic Bearing:Utilizing magnetic forces to suspend and rotate components, this advanced technology minimizes mechanical friction and wear, promising enhanced durability and efficiency for future turbine generations.
Direct Drive systems are consolidating their market position, while Magnetic Bearing technologies offer long-term innovation potential.
Application:
The strategic objective for offshore wind projects determines the primary application focus, from large-scale power production to localized energy solutions.
- Energy Generation:This represents the core application for marine wind turbines, focusing on the large-scale production of electricity for national power grids. Utility companies in Germany and the United Kingdom are commissioning extensive wind farms for this purpose.
- Grid Integration:This application involves the complex process of connecting offshore wind farms to onshore electricity grids, managing power flow, and ensuring grid stability. National grid operators in Denmark and the Netherlands invest heavily in robust grid integration solutions.
- Off-Grid Power:Marine wind turbines can provide isolated power supply to remote offshore installations, such as oil and gas platforms or research stations, reducing reliance on diesel generators.
- Hybrid Systems:This application integrates offshore wind power with other renewable energy sources or energy storage solutions, creating more stable and dispatchable power systems.
Energy Generation remains the dominant application, with Grid Integration solutions becoming increasingly critical for system stability.
End User:
Investment capacity and project scope fundamentally shape the engagement of different end-user groups in the marine wind turbine market.
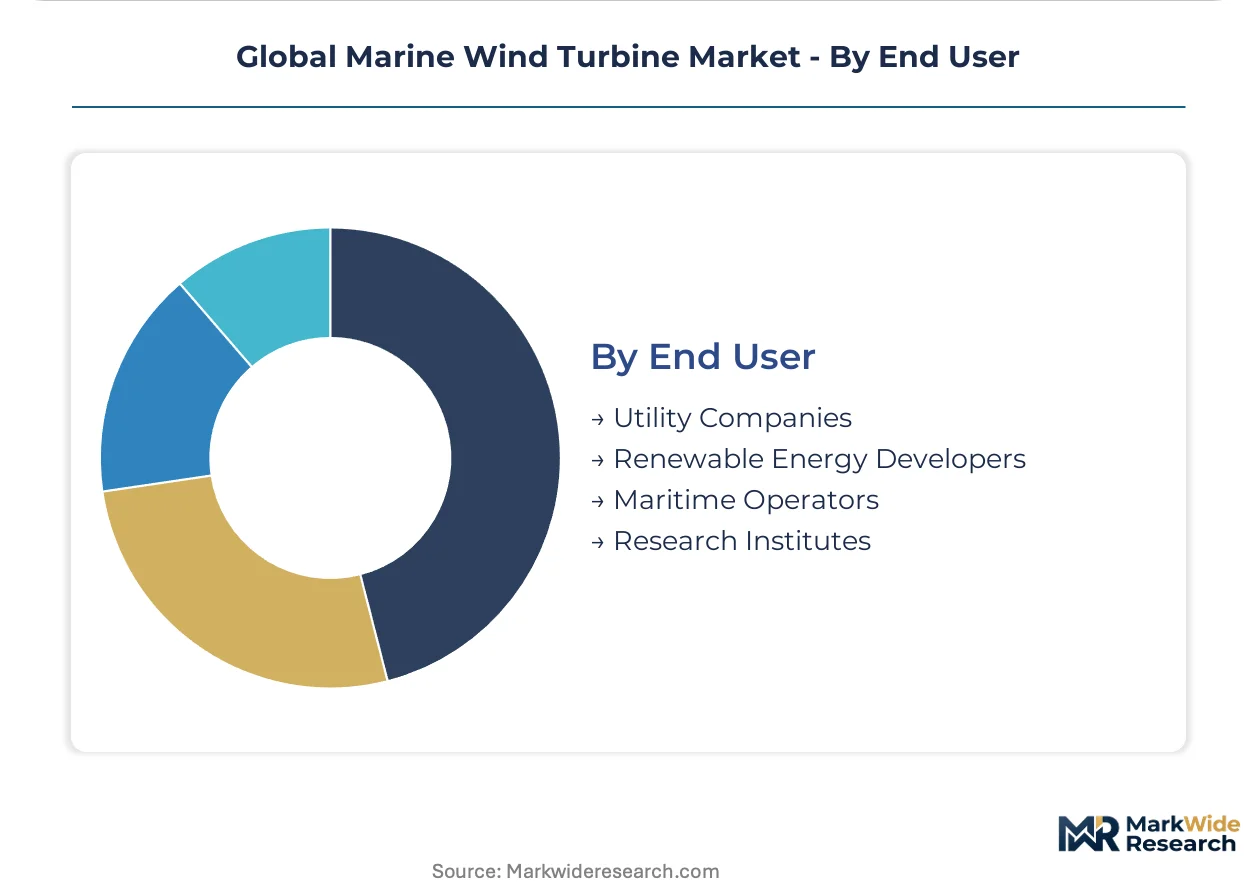
- Utility Companies:These entities are the principal procurers of marine wind turbines, commissioning massive offshore wind farm projects to meet national energy targets and consumer demand. European utilities like Ørsted and RWE are major players in this segment.
- Renewable Energy Developers:Specialists in the planning, financing, and construction of renewable energy projects, these developers often partner with utilities or secure Corporate Power Purchase Agreements (PPAs). Independent power producers in Taiwan and South Korea represent a growing segment.
- Maritime Operators:This group includes companies operating offshore platforms, vessels, or aquaculture farms that may utilize smaller-scale marine wind turbines for localized power needs.
- Research Institutes:Academic and governmental research bodies focus on advancing turbine technology, conducting environmental impact assessments, and optimizing operational performance for the industry.
Utility Companies drive the majority of project demand, while Renewable Energy Developers expand project pipelines in new regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized engineering talent required for offshore wind projects anchors significant development across key global geographies. These regions benefit from established maritime infrastructure and binding energy targets, driving substantial investment in large-scale marine wind turbine installations.
China
China's coastal provinces exhibit a strong demand for marine wind turbines, driven by ambitious national energy generation goals. The dual carbon goals mandate extensive deployment of renewable energy sources, including offshore wind. Key industrial clusters along the southeastern coast, such as Jiangsu and Guangdong, are actively commissioning large-scale offshore wind farms to power industrial growth.
United Kingdom
The United Kingdom's North Sea region remains a focal point for marine wind turbine deployment, with utility companies pursuing massive grid-scale power generation projects. Policy frameworks influenced by the EU Green Deal and subsequent national targets accelerate project timelines. East Coast ports like Hull and Grimsby serve as critical hubs for turbine assembly and maintenance operations, supporting extensive offshore wind farm development.
Germany
Germany concentrates its marine wind turbine demand in the North Sea and Baltic Sea, aiming for significant contributions to national energy supply. The EU Green Deal establishes stringent targets for renewable energy capacity, directly influencing offshore wind farm construction. Manufacturing and logistics centers in northern Germany, including Wilhelmshaven and Emden, facilitate the integration of high-capacity turbines into the grid.
United States
The United States East Coast presents a significant opportunity for marine wind turbine development, particularly for floating platforms in deeper waters. The Inflation Reduction Act (IRA) provides substantial incentives for renewable energy projects, encouraging investment in offshore wind. New York and Massachusetts are establishing port infrastructure and supply chain hubs to support extensive offshore wind farm construction.
Taiwan
Taiwan is rapidly developing its offshore wind capacity, driven by national energy security goals and a shift towards renewable sources. Local regulatory frameworks support independent power producers and utility companies in commissioning large-scale projects. Development zones off the west coast, particularly in the Changhua region, are becoming key sites for both fixed-bottom and floating turbine installations.
Global Marine Wind Turbine Market Key Industry Players
Top-tier vendors anchor the global marine wind turbine market, while a diverse array of regional specialists and emerging technology providers compete for market share. The market structure exhibits a clear hierarchy, with established players dominating high-value segments. Global technology innovators and cost-effective regional scale players represent two distinct strategic archetypes. Capacity expansion and strategic partnerships remain dominant competitive moves across the industry.
On the premium-tier vector, Siemens Gamesa Renewable Energy and Vestas exemplify European leadership in high-capacity, direct-drive turbines for harsh offshore environments. These companies prioritize reliability and service life in their deep-water models. In contrast, Goldwind, a Chinese-based manufacturer, occupies a position as a cost-effective solution provider, leveraging its scale to dominate the rapidly expanding Chinese domestic market.
| Leading Market Players |
|---|
| SANY Group |
| Dongfang Electric |
| Mingyang Smart Energy |
| Suzlon Energy |
| Goldwind |
| Siemens Gamesa Renewable Energy |
| Envision Energy |
| GE Wind Energy |
| Vestas |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and China's dual carbon goals gate qualified supply and premium-tier pricing access for marine wind turbines. These mandates necessitate stringent performance and environmental criteria, shaping market entry and product valuation.
Pricing Analysis
The market primarily operates on a bundled service model, integrating turbine supply with long-term O&M contracts for utility companies. Project-based pricing dominates, with differentiation stemming from turbine capacity, adherence to CE marking standards, and manufacturer brand reputation. Pricing pressure intensifies on gearbox-driven models due to cost-effective solutions from Chinese manufacturers like Goldwind. Utility companies prioritize long-term reliability over initial cost, making them less price-sensitive than independent renewable energy developers.
Supply Chain Analysis
Specialized labor scarcity in manufacturing hubs like Germany and China impacts marine wind turbine supply chain efficiency. Production concentrates heavily in China, Germany, and the United Kingdom, drawing from global raw material inputs. Critical dependencies include multi-megawatt nacelles and blades exceeding 100 meters, creating specialized component bottlenecks. The distribution model primarily involves direct sales from manufacturers to utility companies and renewable energy developers, often through EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine wind turbine market presents a margin-expansion story, driven by the shift towards high-capacity direct-drive systems for deep-water applications. This premium-tier focus allows for higher value capture per installation, optimizing project economics.
For Market Incumbents:Hedge against market share erosion from cost-effective regional players by accelerating R&D into next-generation floating platform technologies. Secure long-term supply agreements for critical components, mitigating specialized component bottlenecks. Siemens Gamesa and Vestas can reinforce their premium positioning through continuous innovation in direct-drive reliability and CE marking compliance. This strategy defends against Goldwind's scale advantage in the rapidly expanding Chinese domestic market.
For New Entrants and Emerging Players:The Inflation Reduction Act (IRA) in the United States opens a window for new entrants in offshore wind development. Focus on the floating turbine segment, particularly off the US East Coast and in Taiwan, where established fixed-bottom supply chains are less entrenched. Partner with local renewable energy developers to offer project-specific solutions, capitalizing on green hydrogen integration opportunities. This strategy allows for market penetration outside dominant European and Chinese coastal zones.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized component manufacturers with proven track records in high-capacity turbine elements. The long-term viability of the marine wind market appears robust over the next 5-10 years, driven by global energy transition mandates. Target floating platform technology developers or grid integration specialists for strategic acquisitions. A key signal to watch is the stability and consistency of national energy policies supporting offshore wind deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Floating Platform R&D | Unlocks deep-water sites and expands development potential beyond continental shelves. |
| Secure Long-Term Component Supply | Mitigates specialized component bottlenecks for multi-megawatt nacelles and blades. |
| Pursue Green Hydrogen Integration | Creates new offtake markets for offshore wind power, enhancing project economics. |
| Expand into US East Coast Market | Capitalizes on the Inflation Reduction Act incentives and new demand zones. |
| Develop AI-Driven Predictive Maintenance | Optimizes turbine performance and reduces costly operational expenses over asset life. |
Research Approach
Multiple input streams — primary interviews, secondary research, and proprietary databases — were reconciled for this analysis. Industry stakeholders, including utility planning officers, turbine R&D directors, and port infrastructure managers, provided qualitative insights. Secondary validation utilized IEA reports, national energy agency data, and corporate annual reports. This approach integrated both bottom-up market sizing and top-down validation to ensure data accuracy.
Historical data was cross-referenced with expert panel input to construct the forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional deployment type. Compound annual growth rates were derived from projected wind farm capacity additions and anticipated regulatory policy shifts. This comprehensive approach ensured robust market projections over the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of geopolitical instability or significant technological breakthroughs. These forecasts reflect underlying assumptions regarding market dynamics and regulatory consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Thailand Wind Energy Market