
 China Wind Turbine Rotor Blade Market | 2026-2036
China Wind Turbine Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
China Wind Turbine Rotor Blade Market Outlook
Offshore utility-scale deployment is repositioning blade procurement priorities across China's wind supply chain. Goldwind leverages its integrated turbine-blade platform to capture coastal project awards. Lianyungang Zhongfu Lianzhong Composites Group anchors its position through fiberglass-carbon hybrid material expertise. Tianshun Wind Energy sustains manufacturing scale across Jiangsu and Guangdong production bases.
China wind turbine rotor blades are aerodynamic structures typically spanning 80 to 120 meters in length, fabricated from glass fiber reinforced epoxy composites via vacuum infusion or prepreg layup processes, designed to convert kinetic wind energy into rotational mechanical force for electricity generation. Horizontal axis configurations dominate installed capacity given their compatibility with megawatt-scale drivetrains. Vacuum infusion manufacturing is displacing hand layup across extra-large blade categories due to resin consistency and labor efficiency gains. Composite blade types command margin concentration as carbon fiber loading rises above 15 percent in 100-meter-plus designs.
MIIT blade certification rules and GB structural load standards shape product qualification timelines and factory audit intensity for domestic suppliers. NMPA-style equipment safety protocols and provincial grid connection codes further filter market access for non-compliant producers. Stakeholders must monitor carbon fiber supply agreements and resin price volatility as blade lengths extend past current transport infrastructure limits.
Market Dynamics
Offshore wind farm developers are consolidating procurement around 15MW-plus turbine platforms, compressing supplier qualification timelines while MIIT blade certification rules tighten structural load testing protocols.
Growth Catalysts
- Dual carbon policy mandate:China's national carbon neutrality targets bind provincial governments to accelerate offshore wind auctions in Jiangsu and Guangdong coastal zones.
- Carbon fiber hybridization:Load-bearing spar cap designs above 100 meters incorporate 15-percent-plus carbon fiber content, reducing blade mass while extending capture area.
- GB standards alignment:Factory audit intensity under GB structural integrity protocols filters subscale competitors, concentrating volume among certified domestic manufacturers.
Market Restraints
- Resin price volatility:Epoxy feedstock costs fluctuate with petrochemical supply, squeezing margin on vacuum-infused extra-large blade categories.
- Carbon fiber import dependency:Domestic carbon fiber capacity lags 100-meter-plus blade demand, exposing supply risk to aerospace-priority allocation from Japanese and European producers.
- Transport infrastructure limits:Road and port clearances constrain blade lengths beyond 120 meters, capping onshore deployment options without specialized logistics investment.
Strategic Opportunities
- Fujian offshore zone development:Untapped deep-water sites beyond Guangdong and Jiangsu offer first-mover positioning for blade suppliers with floating platform compatibility.
- Recyclable thermoplastic resins:Thermoplastic composite systems enable end-of-life blade shredding and reprocessing, aligning with MEE circular economy directives.
- Direct blade-shipping partnerships:Dedicated port-side finishing facilities bypass inland transport bottlenecks, cutting logistics cost for coastal project developers.
Industry Challenges
- Aerodynamicist talent scarcity:Computational fluid dynamics specialists with offshore wind experience command premium compensation, constraining R&D team scaling.
- MIIT certification timeline compression:Accelerated project schedules force parallel testing and production ramp-up, elevating recall risk if prototype validation fails.
- Legacy blade retrofit incompatibility:8-10MW turbine blade stocks face stranded asset risk as 15MW platforms dominate new procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Wind Turbine Rotor Blade Market |
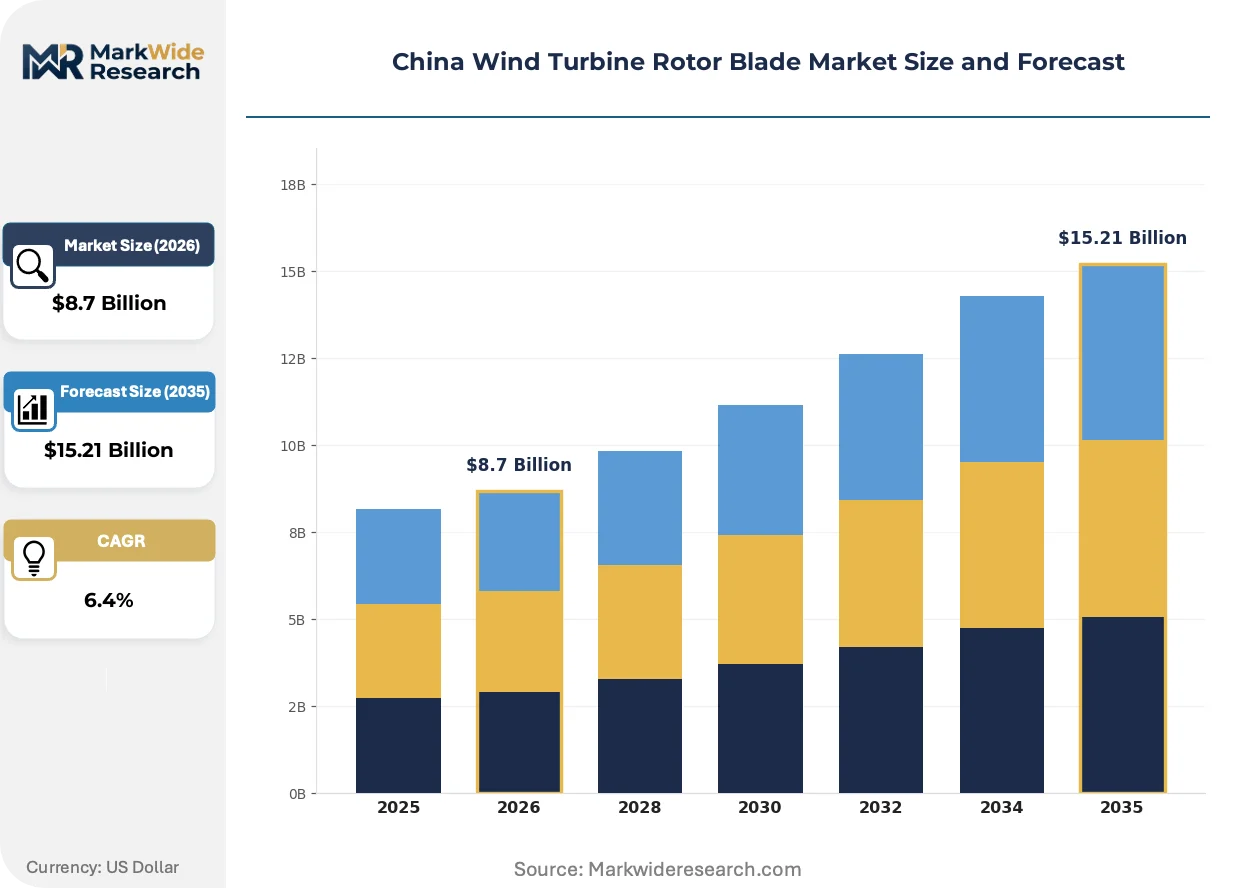
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Blade Type: Horizontal Axis, Vertical Axis, Composite, Steel Manufacturing Process: Injection Molding, Hand Layup, Vacuum Infusion, Prepreg Layup Application Area: Onshore, Offshore, Hybrid, Utility Scale Length Category: Small, Medium, Large, Extra Large |
| Companies Covered | Tianshun Wind Energy (Suzhou), Goldwind, Lianyungang Zhongfu Lianzhong Composites Group, Mingyang Smart Energy, Envision, Sinoma Wind Power Blade, LM Wind Power (GE Renewable Energy), Dongfang Electric Corporation, Zhuzhou Times New Material Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Wind Turbine Rotor Blade Market Strategic Shifts
Material science breakthroughs and regulatory stringency are rewriting blade design specifications and manufacturing protocols across China's wind supply base.
Glass-carbon hybrid spar cap construction is converging with automated fiber placement systems to cut layup labor hours by half while maintaining torsional stiffness. Goldwind and domestic tier-one suppliers deploy these lines for 110-meter-plus offshore blades. The convergence is compressing cost curves for next-generation turbine platforms.
MIIT blade certification rules now mandate full-scale static and fatigue testing before serial production approval, extending qualification timelines by four to six months. Factory audit protocols under GB standards inspect resin mixing consistency and fiber volume fraction compliance. Suppliers in Jiangsu and Guangdong are consolidating testing partnerships with Shanghai-based certification bodies to accelerate turnaround.
Developer procurement now bundles blade supply with twenty-year service agreements covering inspection, repair, and tip extension retrofits. Coastal wind farm operators in Guangdong negotiate these packages directly with integrated turbine-blade platforms, displacing standalone blade vendor relationships. The shift is most pronounced in state-backed offshore concessions where lifecycle cost guarantees determine award outcomes.
China Wind Turbine Rotor Blade Market Segmentation
Blade specification diversity in China reflects the tension between coastal offshore megaprojects demanding 100-meter-plus units and inland onshore farms constrained by transport corridors. Procurement patterns diverge sharply across these dimensions, with MIIT certification timelines and GB structural standards filtering supplier participation differently in each category.
Blade Type:
Supply concentration tilts toward configurations compatible with 15MW-plus drivetrain platforms now dominating Jiangsu and Guangdong offshore auctions.
- Horizontal Axis:Aerodynamic designs with three blades mounted perpendicular to wind flow dominate installed capacity. Jiangsu coastal developers specify these exclusively for 12-15MW turbine platforms, with GB structural load standards mandating full-scale fatigue testing before serial production approval.
- Composite:Glass fiber reinforced epoxy construction with carbon fiber spar cap hybridization above 15 percent loading for 100-meter-plus designs. Guangdong offshore zones drive procurement as developers optimize swept area against mass constraints.
- Vertical Axis:Darrieus and Savonius configurations occupy niche distributed generation applications in remote western provinces where grid connection costs exceed turbine sophistication premiums.
- Steel:Metal blade construction persists in small-scale retrofits and training installations where capital constraints override efficiency optimization.
Horizontal axis configurations absorb the bulk of installed capacity; composite blade types are expanding most quickly.
Manufacturing Process:
Cost tier stratification separates automated high-volume lines from labor-intensive methods now relegated to replacement blade production.
- Vacuum Infusion:Resin transfer under vacuum pressure ensures consistent fiber volume fraction across 80-120 meter blade molds. Jiangsu manufacturers deploy these lines for offshore serial production, with MIIT factory audits inspecting resin mixing consistency as a GB compliance checkpoint.
- Prepreg Layup:Pre-impregnated carbon fiber sheets enable precise spar cap placement in 110-meter-plus designs. Guangdong-based suppliers favor this method for floating platform compatibility projects where torsional stiffness tolerances tighten.
- Hand Layup:Manual fiber placement persists in small blade categories and emergency replacement production where tooling investment cannot be amortized.
- Injection Molding:Thermoplastic resin systems enable rapid cycling for sub-50 meter blades in distributed wind applications aligned with MEE circular economy directives.
Vacuum infusion commands the majority of offshore volume; prepreg layup gains share fastest in extra-large categories.
Application Area:
Customer type differentiation separates state-backed offshore concessions from provincial SOE onshore portfolios with diverging service agreement structures.
- Offshore:Deep-water installations beyond 50 kilometers from Guangdong and Fujian coastlines specify 100-meter-plus blades with 25-year corrosion protection. Developers bundle twenty-year service agreements covering inspection and tip extension retrofits.
- Utility Scale:Centralized procurement by state grid affiliates concentrates volume in 8-15MW platforms across northern plains provinces where wind resource consistency supports capacity factor optimization.
- Onshore:Distributed projects in central and western provinces face 120-meter transport infrastructure limits, capping blade length without specialized logistics investment.
- Hybrid:Wind-solar co-location designs in Gobi corridor zones require blade aerodynamic tuning to minimize wake interference with downstream PV arrays.
Utility scale deployments anchor current procurement volumes; offshore applications show the steepest expansion trajectory.
Length Category:
Margin concentration tracks carbon fiber loading intensity, with 100-meter-plus designs capturing premium pricing against transport-constrained smaller segments.
- Extra Large:Blades exceeding 100 meters incorporate 15-percent-plus carbon fiber spar cap content. Fujian deep-water developers specify these for floating platform compatibility where tip clearance and swept area determine annual energy production.
- Large:80-100 meter glass-epoxy designs serve Jiangsu intertidal zone projects with fixed-bottom foundations and established port-side logistics infrastructure.
- Medium:50-80 meter blades dominate northern plains onshore repowering where existing tower infrastructure constrains rotor diameter expansion.
- Small:Sub-50 meter units supply distributed generation and agricultural hybrid installations in remote western counties beyond grid extension priorities.
Large blades currently dominate manufacturing throughput; extra large categories are climbing the fastest as 15MW platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal provinces dominate blade fabrication capacity while inland transport corridors constrain finished goods distribution to interior wind zones. Provincial energy bureaus coordinate factory licensing with port access to minimize logistics friction for extra-large units.
Jiangsu
Intertidal offshore zones drive demand for 80-100 meter glass-epoxy blades with fixed-bottom foundation compatibility. MIIT factory audits inspect resin mixing consistency at Nantong and Yancheng production bases. State grid affiliates consolidate procurement through Yangkou Port logistics clusters where blade finishing facilities bypass inland road constraints.
Guangdong
Deep-water floating platform projects specify 100-meter-plus carbon fiber hybrid designs with 25-year corrosion protection. Provincial offshore wind auction rules under the dual carbon mandate bind developers to twenty-year service agreements. Zhuhai and Yangjiang port zones anchor dedicated blade-shipping partnerships that cut coastal logistics costs.
Fujian
Untapped deep-water sites beyond Guangdong and Jiangsu offer first-mover positioning for suppliers with floating platform expertise. Fujian Energy Bureau zoning approvals prioritize 15MW-plus turbine compatibility in Xiamen and Fuzhou coastal concessions. Local SOE developers negotiate direct blade supply contracts with integrated turbine platforms.
Shandong
Northern plains repowering projects face 120-meter transport infrastructure limits that cap blade length without specialized logistics investment. Shandong provincial grid codes filter non-compliant producers through GB structural load standard enforcement. Weihai and Yantai manufacturing bases serve Bohai Bay offshore zones with vacuum infusion lines.
Hebei
Wind-solar co-location designs in the Zhangjiakou renewable energy demonstration zone require blade aerodynamic tuning to minimize wake interference. Hebei Development and Reform Commission procurement guidelines favor domestic certified suppliers under MIIT blade certification timelines. Baoding industrial clusters host testing partnerships with Beijing-based certification bodies.
China Wind Turbine Rotor Blade Market Competitive Environment
Top-tier vendors anchor integrated turbine-blade platforms, while mid-scale fabricators compete on material specialization and regional port access. Factory audit intensity under GB standards filters subscale competitors, concentrating volume among certified domestic manufacturers. Three archetypes dominate: state-linked turbine OEMs with captive blade operations, independent composite specialists with carbon fiber hybrid expertise, and port-proximate fabricators with dedicated coastal logistics. Competitive moves center on backward integration into carbon fiber supply agreements and testing partnership consolidation with Shanghai-based certification bodies.
Among integrated turbine-blade platforms, Goldwind exemplifies the state-linked OEM archetype with coastal project award concentration. Lianyungang Zhongfu Lianzhong Composites Group occupies a position within the independent composite specialist tier, its name signaling Lianyungang port proximity and hybrid material focus. Tianshun Wind Energy represents the scale-driven fabricator archetype, with Suzhou-based operations spanning Jiangsu and Guangdong production bases. These three anchors illustrate how supplier qualification timelines compress around 15MW-plus platform procurement.
| Leading Market Players |
|---|
| Tianshun Wind Energy (Suzhou) |
| Goldwind |
| Lianyungang Zhongfu Lianzhong Composites Group |
| Mingyang Smart Energy |
| Envision |
| Sinoma Wind Power Blade |
| LM Wind Power (GE Renewable Energy) |
| Dongfang Electric Corporation |
| Zhuzhou Times New Material Technology |
| Others |
Value Chain & Pricing Dynamics
15MW-plus turbine procurement mandates from Jiangsu and Guangdong offshore developers are compressing supplier qualification timelines, forcing blade fabricators to absorb carbon fiber premium costs while MIIT certification rules extend factory audit cycles. This demand-side pressure concentrates pricing power among certified domestic manufacturers with integrated testing partnerships.
Pricing Analysis
Expedited delivery premiums now separate certified Jiangsu and Guangdong producers from uncertified competitors facing six-month qualification delays. Pricing stratifies across MIIT-certified premium tier, GB-compliant standard tier, and uncertified economy tier based on factory audit completion and carbon fiber spar cap loading. Cost compression in standard-tier vacuum-infused blades intensifies as epoxy resin feedstock volatility squeezes margin. State-backed offshore developers show lowest price sensitivity given twenty-year service agreement bundling; inland onshore repowering projects exhibit highest sensitivity to per-blade unit costs.
Supply Chain Analysis
Dual-sourcing requirements from Goldwind and Mingyang Smart Energy mandate multi-supplier qualification for carbon fiber spar cap and epoxy resin inputs. Supply concentrates in China for glass fiber and vacuum infusion equipment, Japan and Europe for aerospace-grade carbon fiber, and South Korea for specialty epoxy formulations. Raw material dependencies center on petrochemical-derived epoxy resins, PAN-based carbon fiber tows, and boron-free E-glass rovings. Single-source vulnerability in carbon fiber supply exposes blade fabricators to aerospace-priority allocation from Toray and SGL. Distribution runs through port-side finishing facilities at Yangkou, Zhuhai, and Yangjiang that bypass 120-meter inland transport limits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over carbon fiber supply agreements and Shanghai-based certification partnerships determines award access. Players are pursuing backward integration into resin mixing and spar cap preform production to compress lead times.
For Market Incumbents: Acquire carbon fiber supply agreements with Japanese and European producers before aerospace allocation tightens. Consolidate testing partnerships with Shanghai-based certification bodies to compress MIIT approval timelines. Defend position against emerging port-proximate fabricators by locking twenty-year service agreements with Guangdong and Fujian state-backed developers. For New Entrants and Emerging Players: The 80-100 meter glass-epoxy price-point gap between premium carbon-hybrid designs and economy steel-reinforced alternatives offers entry leverage. Target Shandong and Hebei onshore repowering projects where transport infrastructure caps blade length and certification requirements filter slower. Pursue direct blade-shipping partnerships with Bohai Bay and Zhangjiakou port developers as the go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors independent composite specialists with carbon fiber hybrid expertise and existing GB certification. Long-term viability hinges on positioning ahead of 15MW platform standardization and floating offshore proliferation. Watch carbon fiber import quota announcements from SAMR as the inflection indicator for supply cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Supply Agreement | Secures aerospace-grade tow allocation from Toray and SGL against MIIT certification timelines. |
| Port-Side Finishing Facility | Bypasses 120-meter inland transport limits at Yangkou and Zhuhai logistics clusters. |
| GB Standards Certification Investment | Filters subscale competitors through factory audit intensity under structural load protocols. |
| Twenty-Year Service Agreement Bundling | Locks lifecycle cost guarantees with Guangdong state-backed offshore concessions. |
| Thermoplastic Resin R&D Partnership | Aligns with MEE circular economy directives for end-of-life blade recyclability. |
Study Parameters
MIIT blade certification databases, GB standards technical committees, and provincial energy bureau auction records formed the secondary backbone. Primary interviews with turbine OEM procurement directors, composite plant managers, carbon fiber supply specialists, and Shanghai certification body auditors combined with secondary validation. Bottom-up and top-down triangulation cross-checked blade shipment volumes against offshore auction capacity announcements.
Bottom-up modeling built from individual blade fabrication line throughput, carbon fiber loading specifications, and port logistics cost structures. Segmentation dimensions included blade length category, manufacturing process type, application area, and regional grid code compliance. CAGRs derived from trend extrapolation of 15MW platform procurement trajectories and dual carbon policy auction schedules across the projection horizon. Forecast inputs incorporated epoxy resin price indices and carbon fiber import volume data.
Underlying measurement precision varies by segment; offshore and extra-large blade categories carry tighter precision than distributed onshore applications due to consolidated procurement transparency. Forecasts reflect assumptions around MIIT certification timeline stability and carbon fiber supply continuity. Deviation in SAMR carbon fiber import quotas or GB standards revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Wind Power Bolts Market