
 Electricity Transmission Infrastructure Market | 2026-2036
Electricity Transmission Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Electricity Transmission Infrastructure Market Foresight
Utility procurement is decoupling from traditional bundled EPC contracts as independent power producers and industrial offtakers enter direct transmission access negotiations. GE Vernova leverages its turbine-to-grid integration portfolio to anchor long-term service agreements with hybrid renewable developers. Siemens Energy AG competes on HVDC converter station technology leadership, particularly for subsea interconnector projects. Prysmian Group dominates submarine cable manufacturing, sustaining margin pools through vertical integration into specialized insulation compounds.
Electricity transmission infrastructure encompasses high-voltage conductors, transformers, switchgear, and control systems engineered to transport bulk power across distances exceeding 300 kilometers at voltages from 110 kV to 800 kV. Underground cables using cross-linked polyethylene insulation now penetrate dense urban corridors where right-of-way constraints eliminate overhead options. AC transmission equipment retains the largest installed base, though HVDC systems represent the fastest-growing technology segment as offshore wind integration demands low-loss submarine links. Smart grid technology deployments concentrate around substation automation and wide-area monitoring, where margin pools shift from hardware sales toward software-defined asset management platforms.
The US Federal Energy Regulatory Commission Order 2023 and EU F-Gas Regulation jointly shape equipment procurement by mandating SF6-free switchgear transitions and streamlining interconnection queue reform. China's National Energy Administration enforces GB standards for ultra-high voltage conductor ratings, creating de facto export specifications for suppliers targeting Belt and Road projects. India's Central Electricity Authority technical standards for renewable energy evacuation further fragment certification requirements across procurement jurisdictions. Stakeholders must monitor regulatory divergence on grid-forming inverter standards as asynchronous renewable penetration redefines stability criteria for transmission planners.
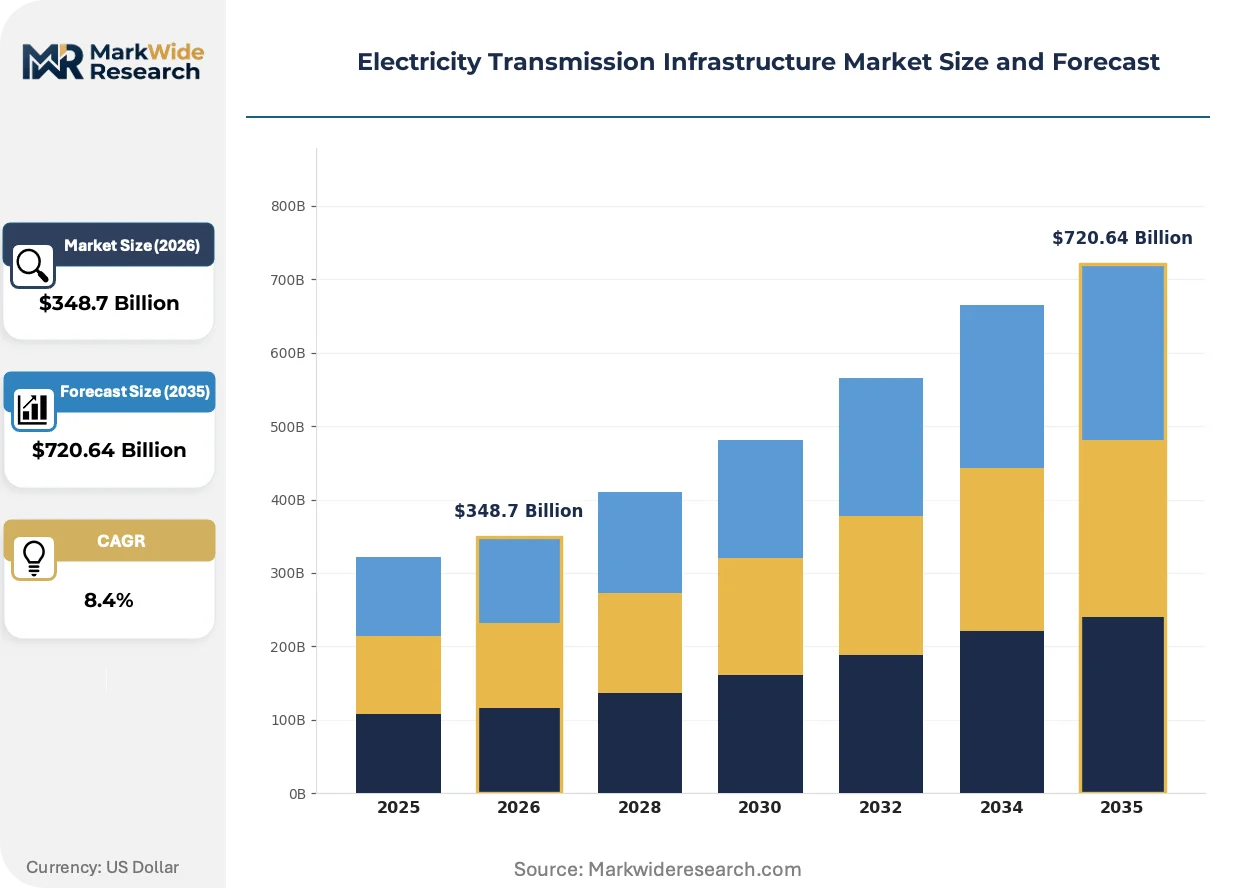
Market Dynamics
HVDC converter technology is concentrating procurement decisions among a narrowing pool of system integrators capable of delivering submarine interconnector projects, fundamentally restructuring how transmission assets are financed and operated across continental distances.
Growth Catalysts
- US Inflation Reduction Act grid modernization mandates:Federal tax credits and loan guarantees accelerate HVDC corridor approvals, pulling forward capital deployment timelines for cross-regional transmission builds.
- Offshore wind evacuation requirements:Utility-scale floating wind farms in the North Sea and Atlantic coastlines demand low-loss submarine cable networks, creating dedicated procurement streams for specialized manufacturers.
- Cross-linked polyethylene insulation advances:XLPE cable systems now achieve 525 kV ratings, enabling underground urban corridors where overhead right-of-way constraints previously blocked expansion.
Market Restraints
- Copper and aluminum price volatility:Conductor raw materials constitute 35-45% of cable system costs, exposing project economics to commodity exchange fluctuations without effective hedging instruments.
- SF6 switchgear phase-out timelines:EU F-Gas Regulation mandates fluorinated gas elimination by 2030, forcing premature asset retirement before alternative insulation technologies achieve scale.
- Specialized vessel bottlenecks:Submarine cable installation requires purpose-built fleet capacity concentrated among three European marine contractors, creating queue congestion for interconnector projects.
Strategic Opportunities
- India renewable energy evacuation infrastructure:Central Electricity Authority standards for solar and wind integration create certification-aligned procurement pools for compliant equipment suppliers.
- Grid-forming inverter convergence with HVDC:Synchronous condenser functionality embedded within converter stations enables black-start capability for islanded renewable zones.
- Software-defined asset management platforms:Predictive maintenance subscriptions monetize operational data from transformer monitoring systems, shifting revenue from hardware sales to recurring service contracts.
Industry Challenges
- High-voltage cable splicing technician scarcity:Specialized jointing expertise for 400 kV+ XLPE systems requires apprenticeship programs exceeding 18 months, constraining installation velocity for urban underground projects.
- Interconnection queue reform implementation:FERC Order 2023 streamlines study processes but creates transitional friction as regional transmission organizations reconfigure backlog management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electricity Transmission Infrastructure Market |
| Market Size in 2026 | $348.7 Billion |
| Market Size in 2035 | $720.64 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Overhead Lines, Underground Cables, High Voltage Direct Current, Substations Technology: AC Transmission, DC Transmission, Smart Grid Technology, Synchronous Condenser End User: Utilities, Independent Power Producers, Industrial Plants, Government Entities Installation: New Construction, Upgrades, Maintenance, Rehabilitation |
| Companies Covered | GE Vernova, Nexans S.A., ABB Ltd., Sumitomo Electric Industries, Ltd., Prysmian Group, Hitachi Energy Ltd., Schneider Electric SE, TBEA Co., Ltd., Siemens Energy AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electricity Transmission Infrastructure Market Shifts & Advancements
Silicon carbide power electronics are compressing converter station footprints while enabling higher switching frequencies, fundamentally altering the spatial economics of HVDC terminal placement in dense industrial zones.
Gas-insulated switchgear using vacuum interruption and clean air insulation is expanding into 145 kV and 245 kV ratings previously dominated by SF6-dependent designs. German transmission system operators now specify SF6-free alternatives for urban substation rebuilds. This technology compression is forcing incumbent manufacturers to retool production lines ahead of regulatory deadlines.
The EU F-Gas Regulation ban on fluorinated greenhouse gases in electrical equipment triggers accelerated R&D spending on alternative insulation media. Industrial consequence includes shortened product certification cycles as notified bodies adapt testing protocols for novel dielectric gases. Substation equipment procurement in Germany, France, and the Netherlands now prioritizes SF6-free bids, reshaping competitive scoring criteria.
Industrial offtakers are negotiating direct transmission access agreements independent of utility intermediation, disrupting traditional bundled EPC contracting structures. This channel disintermediation concentrates in data center and hydrogen electrolyzer projects with predictable load profiles. The United States exhibits the most visible behavioral shift, with PJM interconnection filings from non-utility applicants rising sharply.
Electricity Transmission Infrastructure Market Segmentation
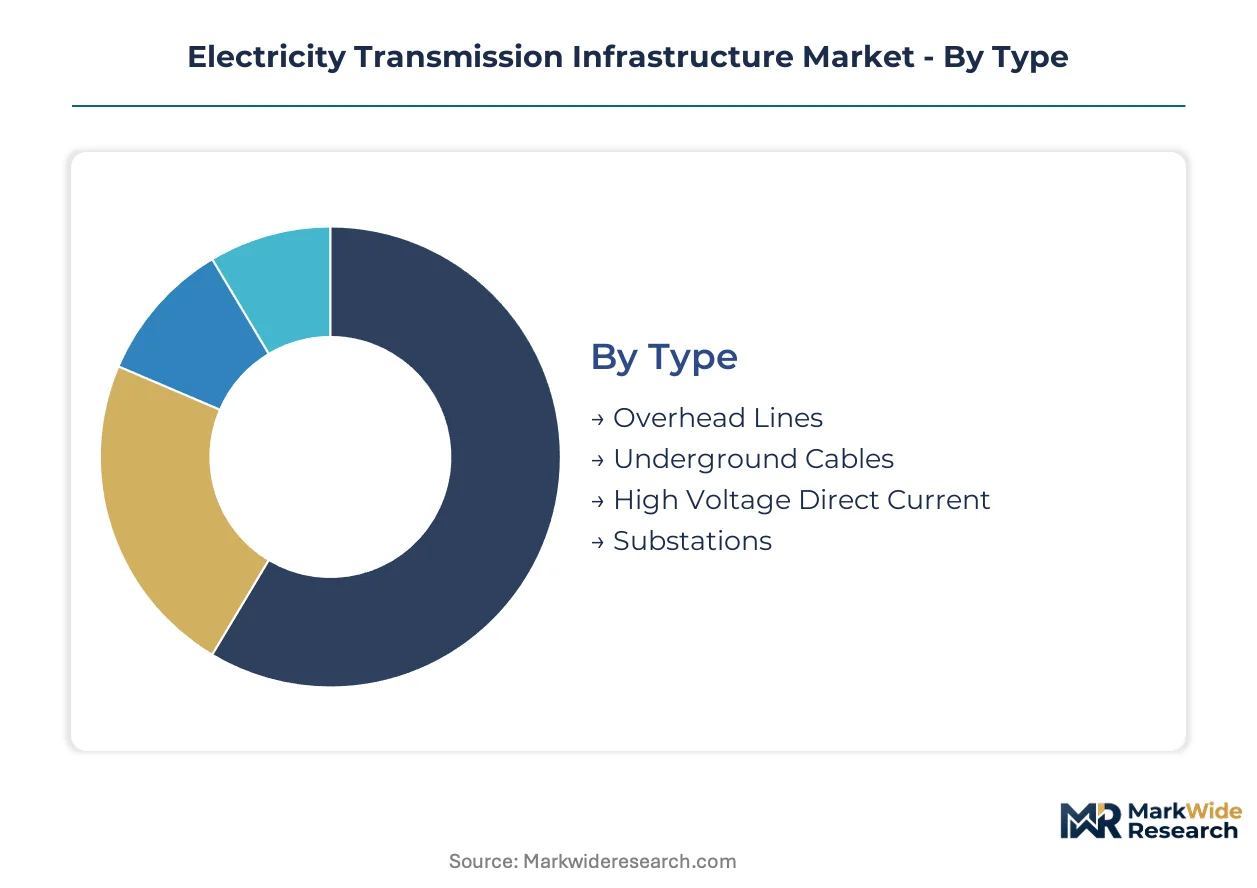
Segmentation reveals how procurement authority is fragmenting across traditional utilities and new market entrants. Equipment specifications diverge sharply between legacy grid reinforcement and offshore wind integration projects. Understanding these splits enables targeted positioning for HVDC converter stations versus conventional AC infrastructure.
Type:
Capital intensity and right-of-way availability drive buyer selection between overhead and buried solutions.
- Overhead Lines:Steel lattice towers and aluminum conductor steel reinforced cables dominate long-distance bulk power corridors above 300 kilometers. Demand concentrates in China's western provinces and the US Great Plains where land availability eliminates underground cost premiums. State Grid Corporation of China deploys ultra-high voltage overhead corridors exceeding 800 kV for coal and renewable evacuation from interior generation bases.
- Underground Cables:Cross-linked polyethylene insulated systems penetrate dense urban corridors and environmentally restricted zones. Germany's SuedLink project and London's new tunnel networks demonstrate 525 kV XLPE viability for metropolitan reinforcement. Right-of-way constraints in Japan's Kanto region and the Netherlands' Randstad megalopolis accelerate procurement.
- High Voltage Direct Current:Converter stations enable asynchronous grid interconnection and submarine power transmission with losses below 3% per 1000 kilometers. North Sea offshore wind evacuation and US-Canada cross-border links anchor current deployment pipelines.
- Substations:Gas-insulated and air-insulated switchgear assemblies transform voltage levels and provide system protection. Urban densification in India and Southeast Asian megacities drives compact GIS adoption.
Overhead lines lead on scale; underground cables lead on momentum.
Technology:
Grid stability requirements and renewable penetration rates determine technology adoption sequencing.
- AC Transmission:Conventional alternating current infrastructure retains the largest installed base with mature transformer and circuit breaker ecosystems. Developing economies in Africa and Southeast Asia extend AC networks for initial electrification coverage.
- DC Transmission:Line-commutated and voltage-source converters enable point-to-point bulk transfer without reactive power constraints. Submarine interconnectors between Norway and Germany, plus planned Spain-France Pyrenees links, anchor European procurement.
- Smart Grid Technology:Phasor measurement units, digital substation automation, and wide-area monitoring systems enable real-time grid visibility. PJM Interconnection and National Grid UK deploy synchronized measurement networks for stability management.
- Synchronous Condenser:Rotating machines and grid-forming inverters provide reactive power support and inertia in weak grids. Australia's renewable zones and Ireland's isolated system incorporate condensers for frequency stability.
AC transmission leads on scale; DC transmission leads on momentum.
End User:
Financing capacity and regulatory standing shape procurement authority and contract structures.
- Utilities:Vertically integrated and transmission-only utilities maintain dominant procurement volume for integrated resource planning. TenneT, National Grid, and State Grid execute multi-year capital programs with sovereign-backed financing.
- Independent Power Producers:Merchant generators and renewable developers negotiate direct transmission access agreements outside traditional utility intermediation. US offshore wind leaseholders and Middle East solar IPPs drive merchant HVDC procurement.
- Industrial Plants:Aluminum smelters, data centers, and hydrogen electrolyzers seek dedicated high-voltage connections for predictable load profiles. Nordic aluminum producers and Dutch hydrogen clusters negotiate bilateral transmission deals.
- Government Entities:National transmission planners and multilateral development banks finance strategic interconnection and rural electrification. African Development Bank and Asian Infrastructure Investment Bank anchor cross-border project finance.
Utilities lead on scale; independent power producers lead on momentum.
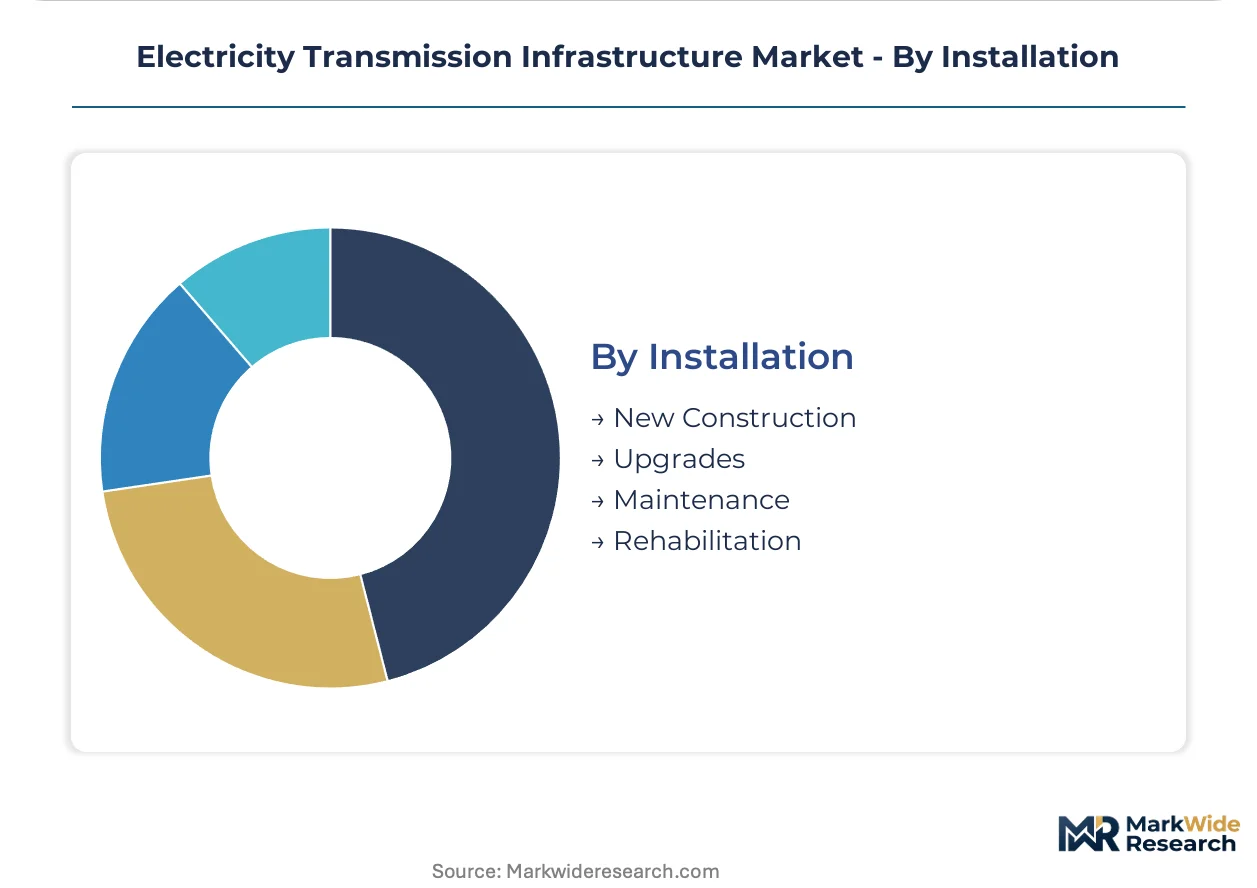
Installation:
Asset age profiles and regulatory deadlines determine work type distribution across project pipelines.
- New Construction:Greenfield transmission corridors and substations serve load growth and generation interconnection. China's 14th Five-Year Plan and US IRA-funded HVDC corridors anchor greenfield investment.
- Upgrades:Capacity expansion through conductor replacement, tower reinforcement, and transformer augmentation extends asset life. European TSOs upgrade 1960s-era corridors for higher thermal ratings.
- Maintenance:Scheduled inspection, vegetation management, and component replacement preserve system reliability. North American utilities deploy helicopter and drone-based line inspection programs.
- Rehabilitation:Comprehensive reconstruction of aged infrastructure addresses structural degradation and obsolescence. UK's Victorian-era London underground cable networks and US Rust Belt substations require systematic replacement.
New construction leads on scale; upgrades lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys ultra-high voltage corridors at scale while Germany prioritizes subsea interconnectors for offshore wind integration. Both markets illustrate how geography and generation mix reshape transmission priorities.
United States
FERC Order 2023 streamlines interconnection queue reform while IRA tax credits accelerate HVDC corridor financing. Texas and Great Plains states anchor greenfield overhead construction for renewable evacuation. PJM Interconnection filings from non-utility applicants reshape procurement authority.
Germany
SuedLink and NordLink projects demonstrate 525 kV XLPE viability for metropolitan and subsea applications. EU F-Gas Regulation mandates SF6-free switchgear transitions by 2030, forcing equipment replacement timelines. TenneT procures converter stations for North Sea offshore wind clusters.
China
State Grid Corporation executes 800 kV ultra-high voltage corridors from western generation bases to coastal load centers. National Energy Administration GB standards create export specifications for Belt and Road suppliers. Xinjiang and Inner Mongolia anchor coal and renewable evacuation infrastructure.
India
Central Electricity Authority technical standards for renewable evacuation create certification-aligned procurement pools. Gujarat and Rajasthan solar zones drive greenfield transmission investment. Green Energy Corridors program targets interstate renewable transfer capacity.
United Kingdom
National Grid deploys synchronized measurement networks for stability management across isolated island systems. Victorian-era London underground cable networks require systematic rehabilitation. North Sea offshore wind interconnectors anchor submarine cable demand.
Electricity Transmission Infrastructure Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across converter stations, cable systems, and switchgear assemblies. Market structure concentrates procurement authority among system integrators capable of delivering submarine interconnector projects. Strategic archetypes span turbine-to-grid integrators, HVDC technology leaders, and specialized cable manufacturers. Competitive moves center on long-term service agreements and vertical control over insulation compound supply.
Within the diversified industrial tier, GE Vernova and Siemens Energy AG occupy positions spanning generation-to-grid integration, while Prysmian Group exemplifies specialized cable manufacturing with captive supply chain control. Hitachi Energy Ltd. and ABB Ltd. represent Japanese and Swiss-Swedish technology anchors respectively. Nexans S.A. and Sumitomo Electric Industries, Ltd. sit within the submarine and high-voltage cable specialist segment alongside Prysmian.
| Leading Market Players |
|---|
| GE Vernova |
| Nexans S.A. |
| ABB Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Prysmian Group |
| Hitachi Energy Ltd. |
| Schneider Electric SE |
| TBEA Co., Ltd. |
| Siemens Energy AG |
| Others |
Supply & Pricing Matrix
High-voltage cable splicing technician scarcity in Germany and Japan widens pricing spreads between premium-certified and standard-grade installation contracts, as labor-cost differentials compound material premiums for 400 kV+ XLPE systems.
Pricing Analysis
Capacity additions in China are reshaping price floors for aluminum conductor steel reinforced cables, compressing margins for European and North American manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified submarine cable systems from domestic-grade overhead conductors and unbranded commodity wire. Pricing pressure stems from volatile copper and aluminum exchange rates that expose project economics without hedging coverage. Independent power producers exhibit acute price sensitivity due to merchant financing constraints, while sovereign-backed utilities absorb premiums for guaranteed delivery timelines.
Supply Chain Analysis
Workforce availability constraints in Italy, South Korea, and Norway limit expansion velocity for specialized XLPE insulation compound production and HVDC converter station assembly. Manufacturing draws from concentrated rare earth processing in China for permanent magnet components, high-purity copper cathodes from Chile and Peru, and specialty steel for lattice towers from India and Japan. Single-source vulnerability runs through European marine cable-laying vessel operators, where three contractors control interconnector installation capacity. Distribution runs through EPC prime contractors who bundle equipment procurement with construction services, though direct manufacturer-offtaker negotiations are fragmenting this channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electricity transmission infrastructure market functions as a stable compounder, with grid modernization mandates under the US IRA and EU Green Deal providing durable demand visibility across decade-long capital cycles.
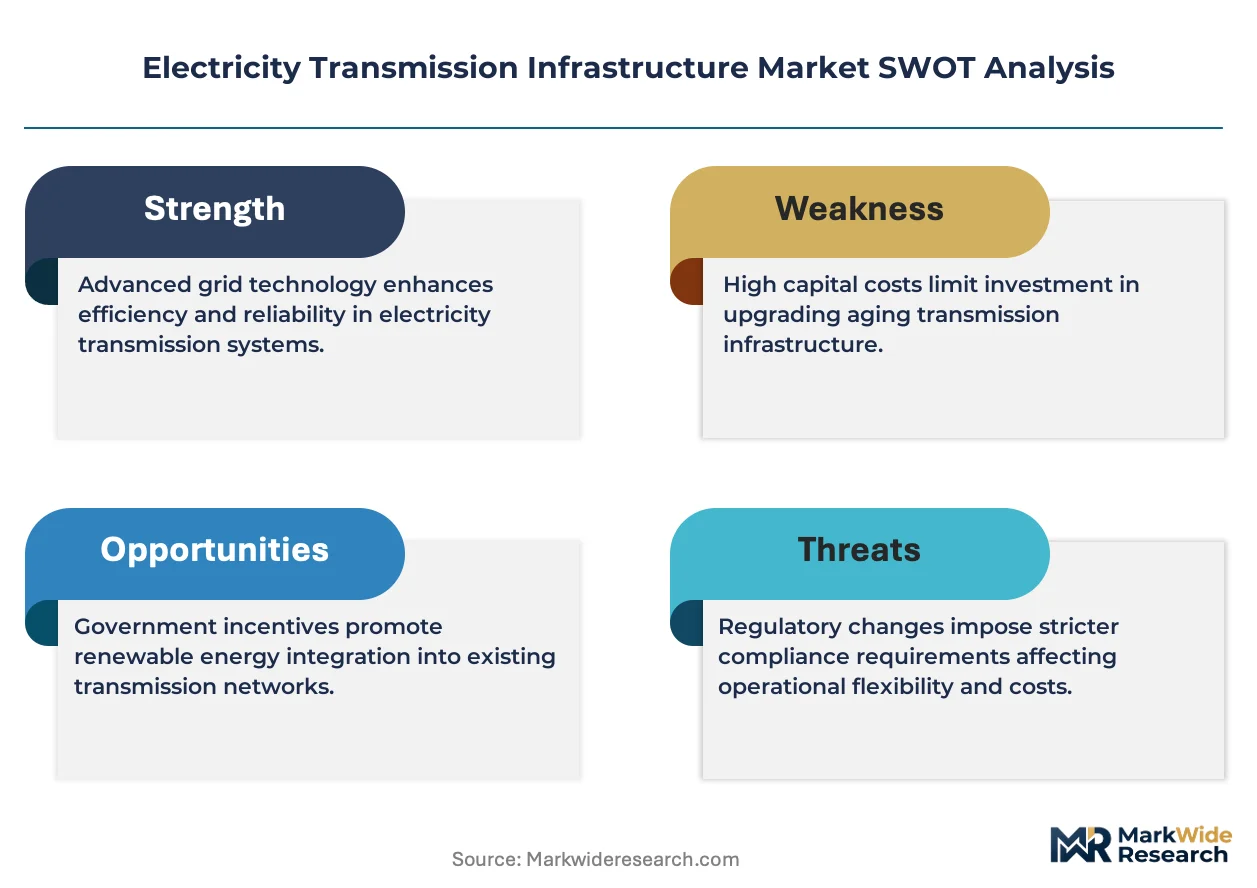
For Market Incumbents: Deploy long-term service agreements as the anchor lever to capture recurring revenue from transformer monitoring and predictive maintenance platforms. Consolidate position through backward integration into specialized insulation compound supply, countering margin pressure from raw material volatility. Acquire grid-forming inverter capabilities to address synchronous condenser substitution threats in islanded renewable zones. For New Entrants and Emerging Players: Enter via India's renewable energy evacuation infrastructure, where Central Electricity Authority certification requirements create procurement pools for compliant equipment suppliers lacking established relationships. Target submarine cable jointing services as the most penetrable niche, given 18-month apprenticeship bottlenecks constraining incumbent installation velocity. Pursue direct contracting with data center developers seeking unbundled transmission access outside utility intermediation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap cable manufacturers with captive XLPE compound production but limited converter station integration capabilities. Five-to-ten-year viability hinges on exposure to offshore wind procurement pipelines rather than legacy AC overhead replacement cycles. Monitor FERC interconnection queue reform implementation velocity as the signal for merchant HVDC demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Switchgear Transition | EU F-Gas Regulation mandates accelerate R&D spending on vacuum interruption and clean air insulation technologies ahead of 2030 deadlines. |
| Submarine Cable Capacity Expansion | Prysmian and Nexans vertical integration into specialized insulation compounds sustains margin pools for North Sea offshore wind interconnectors. |
| HVDC Converter Station Localization | Siemens Energy and Hitachi Energy anchor technology leadership for subsea projects, concentrating procurement among system integrators. |
| Grid-Forming Inverter Convergence | Embedded synchronous condenser functionality enables black-start capability, redefining stability criteria for transmission planners in Australia and Ireland. |
| Software-Defined Asset Management | GE Vernova monetizes operational data through predictive maintenance subscriptions, shifting revenue from hardware sales to recurring service contracts. |
Research Methodology
Multiple input streams — structured interviews with utility planning officers and IPP project developers, regulatory filing analysis, and project development database tracking — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged EPC contractors, grid operators, and aftermarket service heads across China, Germany, India, and the United States. Secondary validation drew from FERC interconnection filings, EIA transmission infrastructure data, IEA grid investment reports, and State Grid Corporation capital expenditure disclosures. Bottom-up equipment procurement tracking and top-down macroeconomic scenario modeling were triangulated to anchor volume forecasts.
Data-stream reconciliation across the projection horizon applied multi-dimensional segmentation modeling by voltage tier, installation type, and end-user financing structure. The analytical framework incorporated technology substitution curves for HVDC versus AC systems, regulatory deadline phasing for SF6 phase-out, and commodity price sensitivity bands for conductor materials. CAGRs were derived from installed base replacement cycles, greenfield corridor approval timelines, and renewable energy evacuation capacity buildout trajectories specific to offshore wind and utility-scale solar zones.
Inputs from transmission system operator procurement announcements and national energy administration capital plans were available through the study window; gaps in merchant project financing commitment levels introduce uncertainty bands around independent power producer demand segments. Forecasts reflect assumptions regarding interconnection queue reform implementation, HVDC converter station delivery schedules, and marine vessel availability for submarine cable installation. Material deviation in named triggers — regulatory deadline delays, commodity price spikes, or specialized labor availability constraints — warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Energy Cable Market