
 Heavy Duty Gas Turbine Market | 2026-2036
Heavy Duty Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Gas Turbine Market Intelligence
Advanced class and H-class turbine specifications is redrawing procurement priorities across the heavy duty gas turbine landscape. GE Vernova leverages its HA-class technology leadership to anchor large utility contracts in North America and the Middle East. Siemens Energy differentiates through hydrogen-ready turbine architectures that extend product lifecycle relevance. Mitsubishi Heavy Industries dominates the Asia-Pacific installation base with manufacturing scale and localized service networks.
A heavy duty gas turbine is a stationary internal combustion engine that converts natural gas or liquid fuel into mechanical energy through continuous combustion at temperatures exceeding 1,400 degrees Celsius, driving an electrical generator for grid-scale power supply. Frame type turbines occupy the dominant share of installed capacity due to their efficiency ratings above 62 percent in combined cycle configuration. Combined cycle applications represent the fastest-growing segment as utilities prioritize fuel efficiency and carbon intensity reduction over simple cycle peaking units. Power generation end users command the largest revenue pool, though oil and gas sector demand for mechanical drive applications sustains a specialized secondary market.
EPA emission standards under the Clean Air Act, FERC Order 2222 grid interconnection rules, and EU ETS carbon pricing mechanisms collectively shape turbine technology roadmaps and market access conditions across operating jurisdictions. Compliance with these frameworks requires continuous combustion optimization, selective catalytic retrofit integration, and hydrogen fuel blending capability certification. Stakeholders must monitor hydrogen infrastructure buildout timelines and carbon border adjustment implementations to align capital deployment with evolving fuel and emissions economics.
Market Dynamics
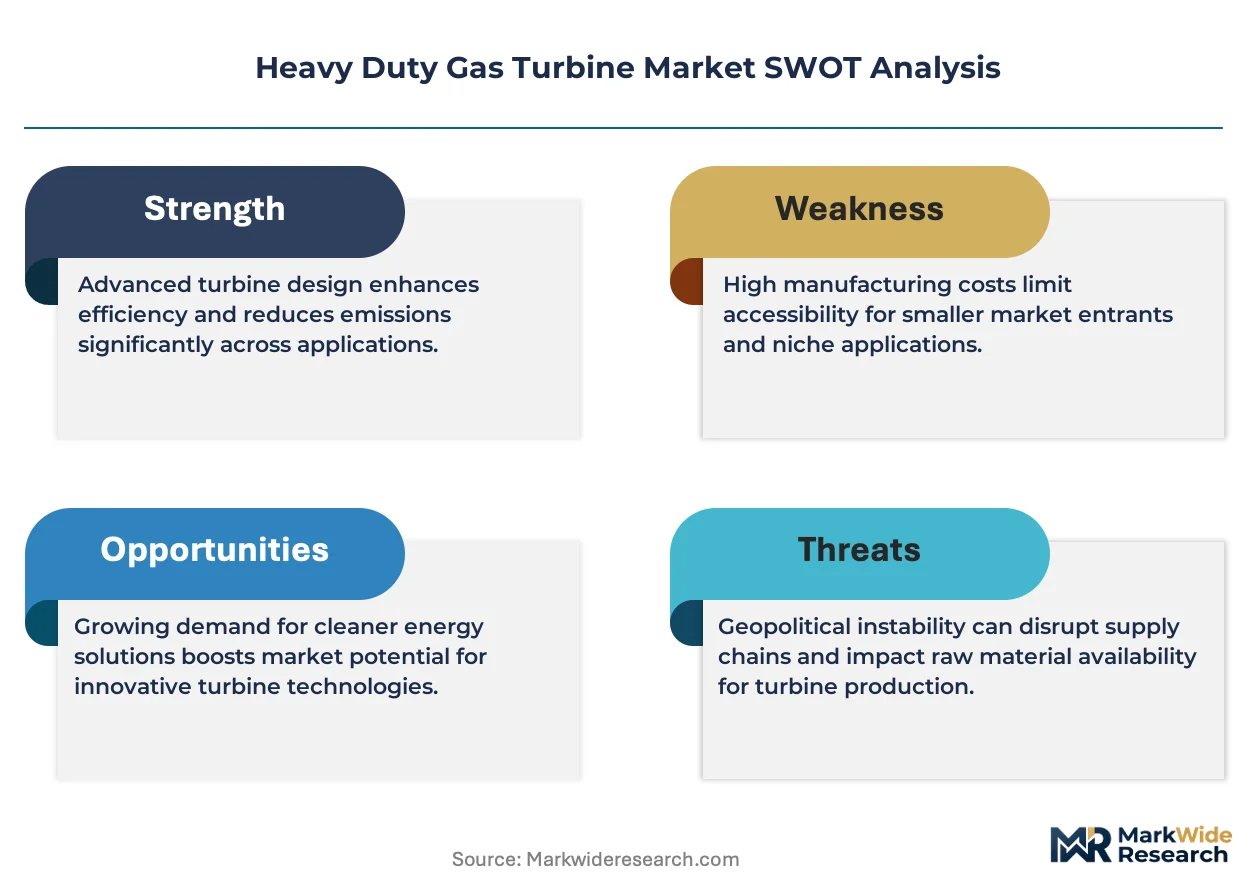
The transition from coal baseload to gas-fired flexible capacity is restructuring procurement priorities across the heavy duty gas turbine sector. Combined cycle configurations now dominate utility planning as grid operators balance renewable intermittency with dispatchable power requirements.
Growth Catalysts
- EPA Carbon Standards:The Clean Air Act emission limits are forcing coal plant retirements and accelerating combined cycle turbine deployments across US power generation utilities.
- Hydrogen Fuel Pathways:Hydrogen-ready turbine architectures are extending equipment lifecycle relevance as utilities prepare for decarbonized fuel blends.
- Saudi Arabia:The kingdom's gas-to-power expansion programs are driving frame-type turbine orders for grid-scale capacity additions.
Market Restraints
- Superalloy Supply Concentration:Specialized nickel-based turbine blade materials concentrate among limited specialty metals suppliers, creating input cost volatility and lead time risk.
- Natural Gas Price Exposure:Fuel cost fluctuations compress operating margins for independent power producers in deregulated markets.
- Long Development Cycles:New turbine platform certification requires multi-year testing protocols that delay technology refresh timelines.
Strategic Opportunities
- India:The country's grid expansion programs present underpenetrated demand for efficient combined cycle capacity to support industrial load growth.
- Carbon Capture Retrofit:Post-combustion capture integration creates equipment upgrade cycles for existing installed bases.
- Digital Twin Convergence:Physics-based modeling with operational data analytics is enabling predictive maintenance service contracts.
Industry Challenges
- Combustion Engineering Talent:Specialized expertise in high-temperature flame dynamics remains scarce as experienced workforce cohorts retire.
- Grid Code Compliance:Evolving FERC interconnection standards require continuous control system modifications for frequency response capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Gas Turbine Market |
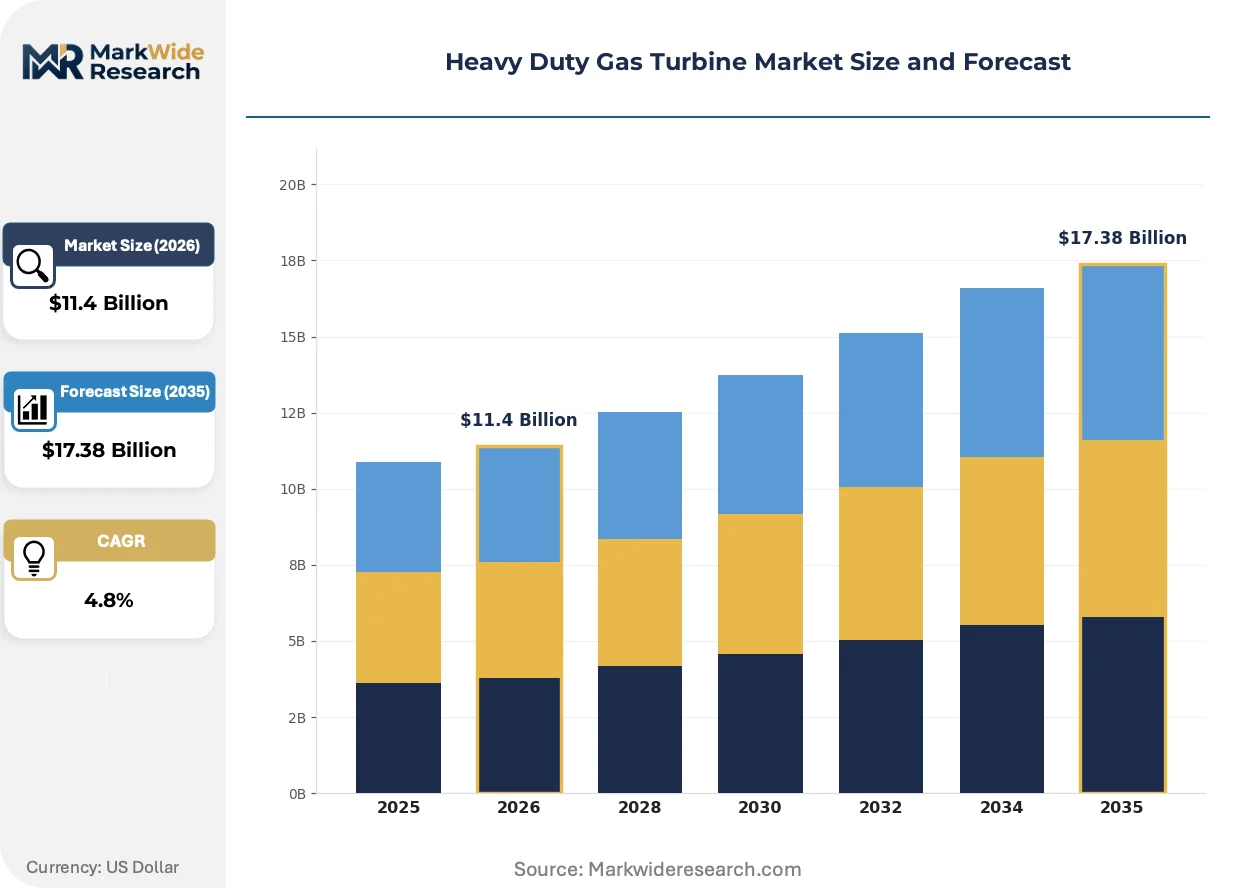
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Type, Aero-derivative, Simple Cycle, Combined Cycle End User: Power Generation, Oil & Gas, Manufacturing, Marine Technology: Closed Cycle, Open Cycle, Hybrid System, Emission Control Application: Load Dispatch, Base Load, Peak Load, Hybrid Power |
| Companies Covered | Baker Hughes, Ansaldo Energia, GE Vernova, Bharat Heavy Electricals, Doosan Enerbility, Siemens Energy, Wärtsilä, Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Gas Turbine Market Strategic Shifts & Innovations
Equipment specifications are pivoting toward fuel flexibility and thermal efficiency as utilities navigate decarbonization pathways. Technology roadmaps now prioritize hydrogen combustion compatibility alongside traditional natural gas performance.
Advanced air cooling systems and thermal barrier coatings are displacing traditional steam-cooled architectures in H-class turbine designs. US utilities deploying these systems achieve firing temperatures above 1,600 degrees Celsius while reducing maintenance intervals. The shift is compressing demand for legacy F-class simple cycle peaking units.
The EU F-Gas Regulation is restricting fluorinated greenhouse gas use in turbine leak detection and fire suppression systems. Equipment manufacturers must certify alternative detection technologies and inert gas fire protection for CE marking compliance. Combined cycle installations in Germany and Italy face accelerated retrofit timelines.
Long-term service agreements are fragmenting into modular performance contracts with unbundled maintenance options. Independent power producers in Texas and California now procure spare parts and field services through competitive tender rather than OEM-captive arrangements. This behavior shift is most pronounced in merchant generation fleets with private equity ownership structures.
Heavy Duty Gas Turbine Market Segmentation
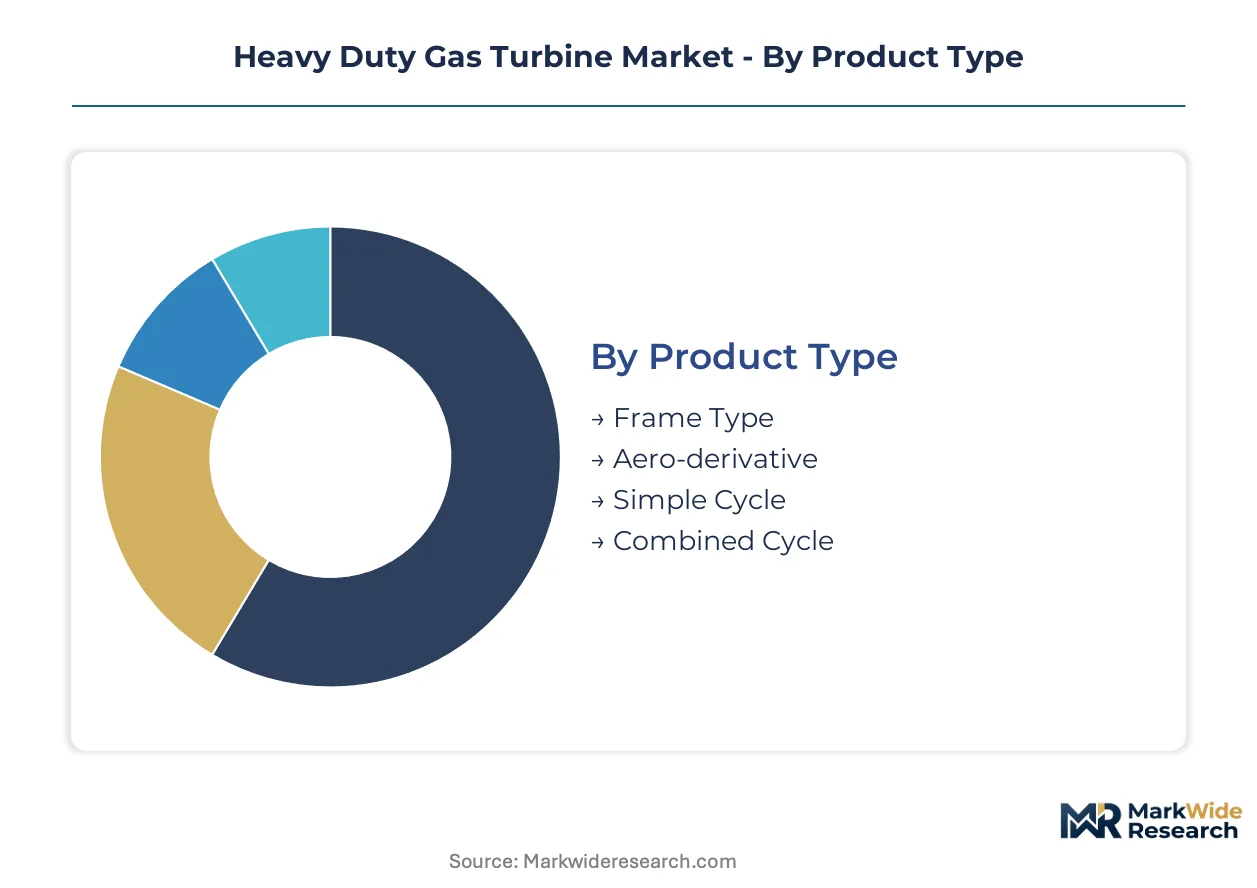
Segmentation in the heavy duty gas turbine market reveals distinct margin pools tied to thermal efficiency ratings and fuel flexibility specifications. Procurement patterns diverge sharply between utilities prioritizing baseload capacity and industrial operators seeking mechanical drive applications.
Product Type:
Margin concentration follows thermal efficiency ratings and installation scale, with combined cycle configurations commanding premium pricing over simple cycle alternatives.
- Frame Type:These heavy-duty stationary turbines achieve firing temperatures exceeding 1,400 degrees Celsius through continuous combustion architecture. US power generation utilities anchor procurement volumes here as EPA emission standards force coal plant retirements and anchor combined cycle deployments.
- Combined Cycle:Configurations integrate gas turbines with heat recovery steam generators to push thermal efficiency above 62 percent. Saudi Arabia's gas-to-power expansion programs concentrate demand for these systems as the kingdom diversifies from oil-fired generation.
- Aero-derivative:Aviation-derived turbine designs offer rapid start capability for grid balancing applications.
- Simple Cycle:Single-stage configurations serve peaking and emergency backup roles with lower capital intensity.
The dominant share belongs to Frame Type, while Combined Cycle is closing the gap fastest.
End User:
Application context determines technology specifications, with grid-connected utilities driving volume and oilfield operators sustaining specialized mechanical drive demand.
- Power Generation:Grid-scale utilities deploy turbines for baseload, intermediate, and peaking duty cycles depending on renewable penetration levels. China's provincial grid operators anchor regional procurement as the country balances solar and wind intermittency with dispatchable gas capacity.
- Oil & Gas:Upstream and midstream operations utilize mechanical drive turbines for gas compression and pumping stations. Saudi Aramco's domestic gas processing expansion sustains specialized demand for high-availability units in harsh environment configurations.
- Manufacturing:Industrial cogeneration applications combine power generation with process heat recovery.
- Marine:Naval and commercial vessel propulsion systems require compact, high-power-density turbine packages.
Power Generation captures the largest revenue pool, though Oil & Gas maintains the most resilient replacement cycle visibility.
Technology:
Technology selection hinges on emissions compliance requirements and hydrogen fuel readiness timelines across operating jurisdictions.
- Emission Control:Selective catalytic reduction systems and dry low-NOx combustors enable compliance with EPA Clean Air Act limits and EU ETS carbon pricing mechanisms. German utilities face accelerated retrofit timelines under the EU F-Gas Regulation restricting fluorinated greenhouse gases in leak detection systems.
- Hybrid System:Configurations blending gas turbine output with battery storage or renewable generation optimize capacity factors. Texas independent power producers pilot these architectures to capture price volatility in deregulated ERCOT markets.
- Open Cycle:Standard combustion configurations without heat recovery serve peaking and emergency applications.
- Closed Cycle:Recirculating working fluid systems enable alternative working media for specialized industrial processes.
Emission Control systems anchor current upgrade spending, while Hybrid System configurations are expanding most quickly.
Application:
Grid integration requirements and renewable penetration rates determine which duty cycle specifications utilities prioritize in procurement.
- Base Load:Continuous operation configurations maximize capacity factors and fuel efficiency metrics. India's state electricity boards concentrate procurement here as the country expands grid infrastructure to support industrial load growth targets.
- Peak Load:Rapid-start units provide dispatchable capacity during demand spikes and renewable generation shortfalls. California grid operators anchor demand as the state manages evening ramp requirements from solar duck curve effects.
- Load Dispatch:Flexible operation modes enable real-time response to grid operator signals.
- Hybrid Power:Integrated renewable-gas turbine systems optimize carbon intensity and reliability.
Base Load retains the dominant installed base, though Peak Load applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nickel-based superalloy supply chains concentrate among limited specialty metals suppliers, creating input cost volatility that shapes regional manufacturing footprints. Turbine OEMs locate final assembly and testing facilities proximate to major utility procurement markets while sourcing precision castings from established metallurgical clusters.
United States
EPA carbon emission standards under the Clean Air Act and FERC Order 2222 grid interconnection rules are accelerating combined cycle deployments across ERCOT, PJM, and CAISO territories. Texas independent power producers anchor procurement volumes as merchant generators replace aging coal baseload with flexible gas-fired capacity. GE Vernova maintains manufacturing and testing infrastructure in Greenville, South Carolina to support utility-scale turbine deliveries.
Saudi Arabia
The kingdom's gas-to-power expansion programs and domestic gas processing infrastructure buildout are driving frame-type turbine orders for grid-scale capacity additions. Saudi Aramco's Master Gas System expansion and power sector privatization initiatives concentrate demand in the Eastern Province industrial corridor. Localized service networks support high-availability requirements for harsh environment configurations.
China
Provincial grid operators are balancing solar and wind intermittency with dispatchable gas capacity additions across the Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT industrial policy and national dual carbon goals shape technology roadmaps favoring high-efficiency combined cycle configurations. State Grid Corporation procurement concentrates in coastal provinces with established LNG import terminal infrastructure.
Germany
EU ETS carbon pricing mechanisms and the EU F-Gas Regulation restricting fluorinated greenhouse gases are accelerating retrofit timelines for leak detection and fire suppression systems. German utilities face compressed certification schedules for hydrogen-ready turbine architectures under national hydrogen strategy implementation. Industrial cogeneration demand in the Ruhr Valley and Bavarian chemical clusters sustains specialized mechanical drive applications.
India
State electricity boards and central generation utilities are expanding grid infrastructure to support industrial load growth targets across Maharashtra, Gujarat, and Tamil Nadu manufacturing corridors. CEA grid codes and national renewable integration mandates prioritize flexible combined cycle capacity over baseload coal alternatives. NTPC and state gencos anchor procurement volumes for 800 MW-class ultra-supercritical gas turbine projects.
Heavy Duty Gas Turbine Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the heavy duty gas turbine sector. The market structure consolidates around integrated industrial conglomerates with captive power generation expertise and specialized energy equipment divisions. Three archetypes dominate competitive positioning: full-spectrum OEMs with in-house combustion engineering capabilities, regional champions leveraging manufacturing scale and localized service networks, and diversified industrial groups with cross-sector technology transfer advantages. Dominant competitive moves include hydrogen-ready platform development and long-term service agreement restructuring toward modular performance contracts.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries, Siemens Energy, and GE Vernova occupy positions spanning technology leadership and geographic coverage breadth. These firms exemplify the integrated OEM archetype through combined cycle system integration capabilities and established utility relationships. Kawasaki Heavy Industries and Doosan Enerbility represent regional manufacturing specialists with concentrated Asia-Pacific installation bases. Baker Hughes and Wärtsilä anchor mechanical drive and distributed power applications distinct from utility-scale procurement patterns.
| Leading Market Players |
|---|
| Baker Hughes |
| Ansaldo Energia |
| GE Vernova |
| Bharat Heavy Electricals |
| Doosan Enerbility |
| Siemens Energy |
| Wärtsilä |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries |
| Others |
Cost & Logistics Intelligence
Long-term service agreements lock in both superalloy component access and maintenance price visibility for US power generation utilities navigating EPA compliance timelines. These multi-year contracts tether turbine OEMs to specialized nickel-based blade suppliers while insulating independent power producers from spot market volatility in critical input materials.
Pricing Analysis
EPA Clean Air Act emission standards dictate the pricing tier structure across the heavy duty gas turbine landscape. Three-tier pricing structure across premium, standard, and economy levels separates H-class hydrogen-ready configurations from F-class retrofits and simple cycle peaking units. Cost compression in the standard tier is intensifying because merchant generators in Texas and California now unbundle maintenance from OEM-captive arrangements. Independent power producers with private equity ownership structures exhibit the highest price sensitivity, while Saudi Aramco and State Grid Corporation procurement teams prioritize availability guarantees over unit economics.
Supply Chain Analysis
Specialized nickel-based superalloy foundries in the United States, Germany, and Japan anchor precision casting capacity for turbine blade manufacturing. These facilities draw from cobalt, rhenium, and tantalum feedstocks concentrated among limited specialty metals traders. Single-source vulnerability in high-temperature alloy supply creates lead time risk during utility fleet expansion cycles. Distribution runs through OEM-integrated service networks and third-party aftermarket parts specialists serving merchant generation fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy duty gas turbine sector faces technology disruption as hydrogen-ready architectures and carbon capture retrofits redefine equipment lifecycle economics. FERC Order 2222 grid interconnection rules and EU hydrogen strategy implementation timelines compress the window for incumbent technology lock-in.
For Market Incumbents: Consolidate hydrogen combustion engineering capabilities through targeted recruitment and combustion test facility investment. GE Vernova, Siemens Energy, and Mitsubishi Heavy Industries must anchor HA-class and H-class technology leadership before Chinese provincial grid operators finalize procurement specifications. Backward integration into superalloy recycling capabilities reduces exposure to specialty metals price volatility from limited supplier bases. For New Entrants and Emerging Players: Aftermarket digital twin and predictive maintenance services represent the most penetrable white-space where incumbent OEMs under-serve independent power producers. Texas and California merchant generation fleets with private equity ownership structures prioritize unbundled spare parts procurement and competitive field service tendering. A direct-to-plant-engineer sales model bypasses traditional utility procurement committees and captures modular performance contract demand. For Investors and Strategic Acquirers: Regional service specialists with localized manufacturing scale and established utility relationships in Asia-Pacific growth corridors offer the strongest acquisition target profile. Long-term viability over the next decade hinges on hydrogen fuel blending certification timelines and carbon border adjustment implementation across operating jurisdictions. The signal to monitor is Saudi Aramco domestic gas processing expansion award announcements, which concentrate frame-type turbine demand and validate technology roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Platform Development | Extends equipment lifecycle relevance as EU hydrogen strategy mandates fuel blending timelines. |
| Superalloy Recycling Investment | Reduces input cost volatility from concentrated specialty metals suppliers in Germany and Japan. |
| Digital Twin Service Launch | Captures predictive maintenance revenue from Texas independent power producers unbundling OEM contracts. |
| Carbon Capture Retrofit Partnership | Creates equipment upgrade cycles for existing installed bases under EPA emission standards. |
| India Manufacturing Footprint Expansion | Positions for state electricity board procurement as CEA grid codes prioritize flexible gas capacity. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads; and secondary validation through EIA capacity data, FERC interconnection filings, IEA technology roadmaps, and project development databases. The research combined bottom-up unit deployment tracking with top-down market sizing across thermal efficiency tiers and fuel flexibility specifications.
Across the analysis window, the forecast framework modeled volume and value trajectories by product type, end user, technology, and application duty cycle. CAGRs were derived from utility capital expenditure pipelines, coal plant retirement schedules, and hydrogen infrastructure buildout assumptions. Key inputs included Saudi Aramco gas-to-power expansion timelines, China MIIT industrial policy directives, and India CEA grid code implementation progress.
Material uncertainties — superalloy supply disruption, natural gas price volatility, and hydrogen certification timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and utility procurement behavior shifts. Practitioners should keep alternative scenarios live as EU carbon border adjustment mechanisms and FERC interconnection standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Cogeneration Equipment Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Process Air Heater Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Magnetic Bearing Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Romania Power EPC Market
Power Equipment
Thailand Power Market
Power Equipment
US Power EPC Market
Power Equipment
Global Power System Simulator Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
United Kingdom Power EPC Market