
 Global Wind LIDAR Market | 2026-2036
Global Wind LIDAR Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind LIDAR Market Outlook
Project finance structures for offshore wind developments are reshaping how LIDAR suppliers compete for long-term service contracts. Vaisala leverages its meteorological heritage to anchor utility-scale validation programs across Northern European waters. Movelaser competes on manufacturing scale, sustaining cost advantages in nacelle-mounted systems for Chinese turbine OEMs. ZX Lidars specializes in floating-platform deployments, occupying a technical niche as deep-water projects proliferate beyond fixed-foundation limits.
Wind LIDAR denotes light detection and ranging systems that emit laser pulses or continuous-wave beams to measure wind speed, direction, and turbulence at altitudes from ground level to 300 meters, with Doppler shift analysis enabling real-time atmospheric profiling for energy yield optimization. Doppler Wind LIDAR dominates utility-scale deployment where turbine manufacturers require hub-height wind characterization for power curve verification. Pulsed Laser configurations capture the fastest-growing share in offshore applications, as longer-range detection supports floating platform positioning and wake-steering algorithms. Scanning LIDAR commands premium positioning in research and aviation safety segments where three-dimensional wind field mapping justifies higher unit economics.
The International Electrotechnical Commission's IEC 61400-12-1 standard governs power performance verification using remote sensing, compelling turbine manufacturers to specify certified LIDAR units for warranty compliance. China's National Energy Administration mandates LIDAR integration in new wind base developments, while the EU F-Gas Regulation pressures manufacturers to eliminate sulfur hexafluoride from auxiliary systems. Stakeholders must monitor how floating offshore certification protocols evolve, as type-approval requirements for motion-compensated platforms will determine which technology suppliers secure preferred vendor status in emerging deep-water markets.
Market Dynamics
IEC 61400-12-1 certification mandates are compressing vendor qualification timelines while floating offshore projects demand motion-compensated LIDAR architectures that fixed-platform suppliers cannot retrofit.
Growth Catalysts
- China's wind base mandates:The National Energy Administration requires LIDAR integration in new state-backed developments, locking in procurement volumes for nacelle-mounted and ground-based systems.
- Floating offshore proliferation:Deep-water projects beyond fixed-foundation limits in the North Sea and Celtic Sea are creating specialized demand for platform-stabilized wind measurement.
- Wake-steering algorithm deployment:Turbine OEMs are embedding scanning LIDAR into control systems to optimize array efficiency through real-time wake detection and yaw adjustment.
Market Restraints
- Optical component supply concentration:Precision laser sources and photodetector arrays depend on a limited set of East Asian foundries, creating single-source vulnerability for Doppler system manufacturers.
- EU F-Gas Regulation compliance costs:The phase-out of sulfur hexafluoride in auxiliary cooling and insulation systems forces redesign of existing product architectures without immediate cost recovery mechanisms.
- Interferometric LIDAR range limitations:Continuous-wave systems face physical constraints in offshore environments where 300-meter+ measurement horizons are required for floating platform positioning.
Strategic Opportunities
- Brazil's offshore licensing rounds:The Búzios and Mero field adjacencies are driving pre-development wind resource campaigns where floating LIDAR can anchor early-mover positioning.
- Aviation safety integration:Airport wind shear detection systems represent an adjacent vertical where scanning LIDAR three-dimensional mapping commands premium unit economics.
- Digital twin convergence:Pairing real-time LIDAR feeds with computational fluid dynamics models enables predictive turbine loading that extends operational life.
Industry Challenges
- Motion-compensation engineering talent scarcity:The intersection of optical physics, marine dynamics, and real-time signal processing requires specialized skill sets concentrated in Nordic maritime research clusters.
- IEC type-approval timeline compression:Certification protocols for floating platforms remain under development, forcing suppliers to engineer against moving regulatory targets without guaranteed approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind LIDAR Market |
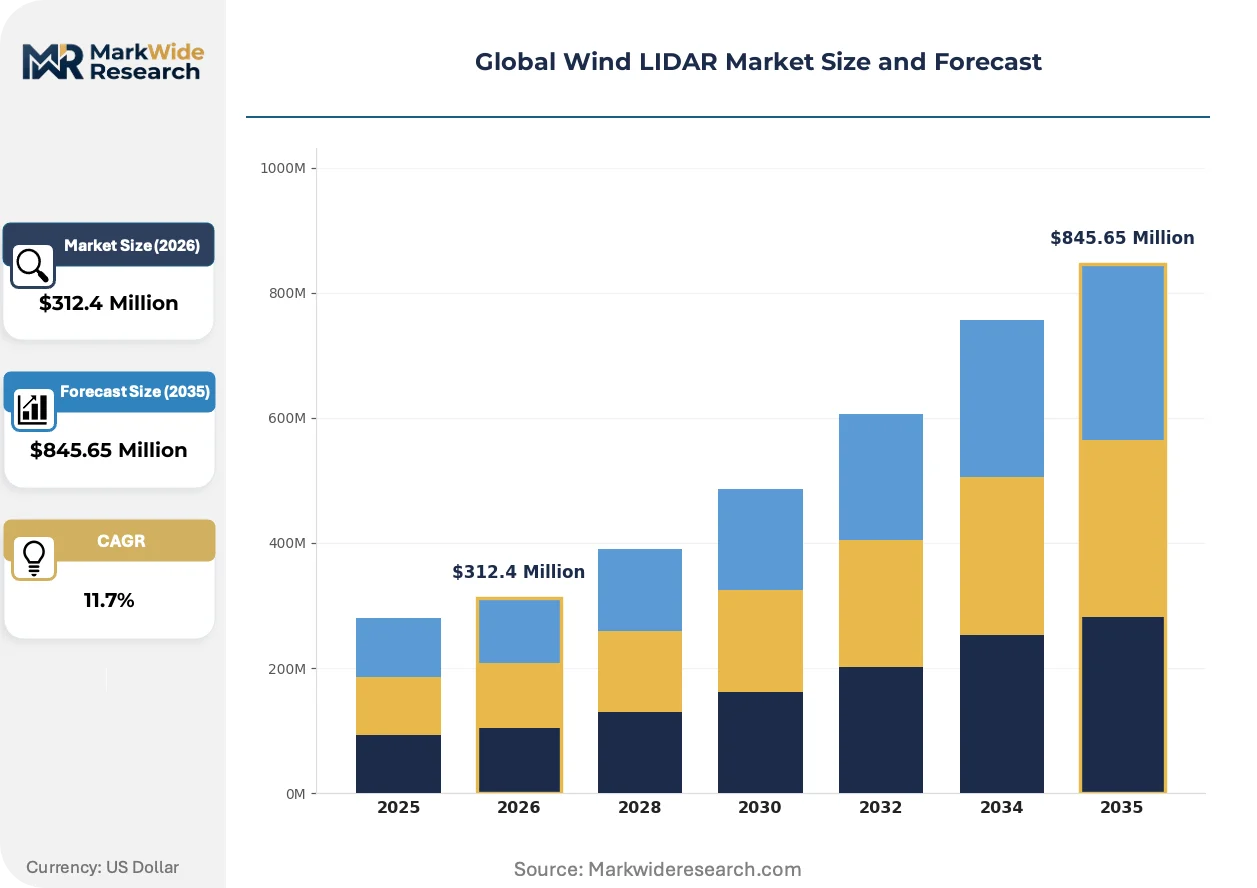
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Continuous Wave, Pulsed Laser, Doppler Wind LIDAR, Scanning LIDAR Application: Wind Resource Assessment, Meteorological Research, turbine Performance Optimization, Air Quality Monitoring End User: Wind Farm Operators, Research Institutions, Environmental Agencies, Utility Companies Deployment: Onshore, Offshore, Fixed, Mobile |
| Companies Covered | Vaisala, Movelaser, ZX Lidars, John Wood Group, Lockheed Martin, Qingdao Leice Transient Technology, Windar Photonics, Lumibird, Huahang Seaglet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind LIDAR Market Strategic Shifts
Pulsed laser architectures are displacing continuous-wave systems in offshore measurement roles while regulatory pressure on fluorinated gases accelerates auxiliary system redesign across European supply chains.
Solid-state beam steering is collapsing the mechanical complexity of offshore LIDAR platforms. Turbine OEMs in Northern Europe are specifying chip-based phased arrays for nacelle-mounted units to eliminate moving parts in salt-air environments. The shift is compressing maintenance intervals from quarterly to annual cycles while reducing unit weight for floating installation.
The EU F-Gas Regulation is forcing sulfur hexafluoride elimination from LIDAR auxiliary systems by 2030. Manufacturers serving North Sea markets are redesigning thermal management and high-voltage insulation around compressed air or vacuum alternatives. Offshore platform operators in Denmark and Germany are now specifying SF6-free units in procurement tenders, ahead of full compliance deadlines.
Service unbundling is fragmenting long-term contracts in European offshore wind. Independent service providers are capturing calibration and data validation work previously captive to equipment vendors. Danish and UK project financiers are driving this separation to reduce counterparty risk in 25-year asset lifecycles.
Global Wind LIDAR Market Segmentation
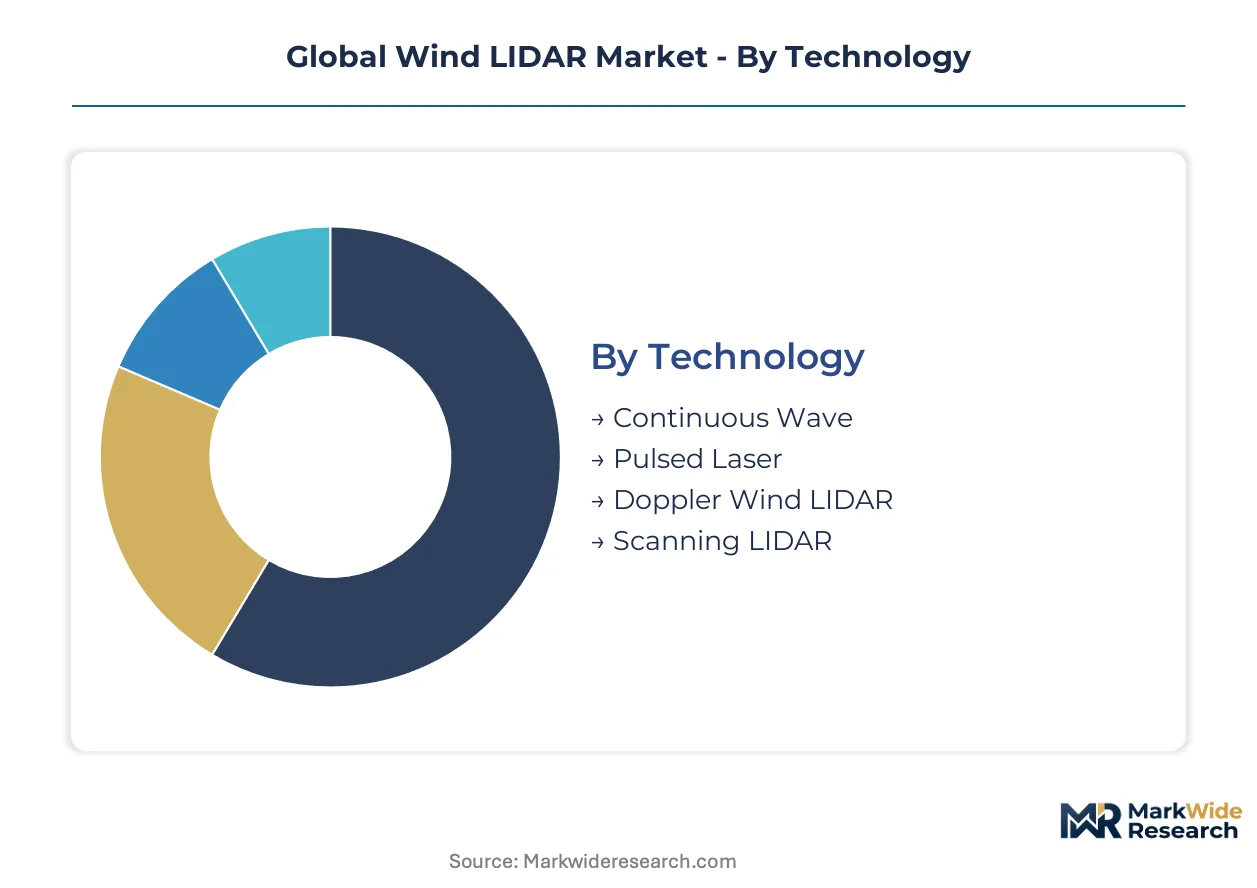
Wind LIDAR segmentation reveals divergent procurement rhythms across the value chain. Technology cycles compress as offshore requirements force architectural redesigns, while deployment modes separate capital-intensive fixed installations from rapidly redeployable mobile units.
Technology:
Replacement cycles vary from three years for nacelle-mounted continuous-wave units to seven-plus years for research-grade scanning systems, creating distinct aftermarket revenue profiles.
- Doppler Wind LIDAR:Doppler shift analysis enables real-time wind speed and direction measurement through frequency change detection in backscattered laser light. Turbine OEMs in China specify these systems for hub-height power curve verification under IEC 61400-12-1 mandates, locking in recurring certification-driven demand.
- Pulsed Laser:Nanosecond-duration laser pulses achieve 300-meter-plus range resolution through time-of-flight measurement. Floating offshore platforms in the North Sea and Celtic Sea deploy these configurations for wake-steering algorithms and platform positioning where longer measurement horizons justify unit premiums.
- Continuous Wave:Interferometric detection of coherent laser beams supports compact nacelle-mounted designs with lower power consumption. Chinese wind base developments favor these units for cost-sensitive turbine control applications.
- Scanning LIDAR:Three-dimensional beam steering creates volumetric wind field maps for research and aviation safety. European meteorological institutes and airport authorities in Germany and France procure these systems for shear detection where mapping fidelity commands premium pricing.
Doppler Wind LIDAR anchors the volume base while Pulsed Laser gains share at the steepest rate.
Application:
Commercial prioritization separates revenue-generating turbine optimization from grant-funded research, with procurement authority residing in distinct organizational functions.
- Wind Resource Assessment:Pre-construction measurement campaigns validate energy yield projections for project finance. Developers in Brazil's offshore licensing rounds deploy floating LIDAR to secure early-mover site control before fixed meteorological mast installation.
- Turbine Performance Optimization:Real-time yaw and pitch adjustment based on upstream wind detection maximizes array efficiency. Wake-steering deployments in Danish offshore clusters embed scanning LIDAR into OEM control architectures.
- Meteorological Research:Boundary layer studies and climate modeling require calibrated atmospheric profiling. Research institutions in Nordic maritime clusters concentrate specialized demand for motion-compensated platforms.
- Air Quality Monitoring:Aerosol backscatter measurement supports pollution dispersion modeling. Environmental agencies in China integrate these capabilities with wind measurement for industrial emission tracking.
Turbine Performance Optimization commands the largest revenue pool while Wind Resource Assessment shows the steepest expansion trajectory.
End User:
Procurement sophistication divides between asset owners optimizing 25-year operational lifecycles and research entities prioritizing measurement precision over total cost.
- Wind Farm Operators:Asset owners specify certified systems for warranty compliance and yield optimization. European offshore developers unbundle service contracts to reduce counterparty risk in long-dated project finance structures.
- Utility Companies:Grid-connected renewable portfolios require resource validation for power purchase agreement pricing. State-backed wind bases in China drive consolidated procurement through central planning mechanisms.
- Research Institutions:Academic and government laboratories demand calibrated traceability for publication-grade data. Nordic maritime research clusters concentrate specialized engineering talent for floating platform development.
- Environmental Agencies:Regulatory monitoring programs combine wind measurement with emission tracking. China's Ministry of Ecology and Environment mandates integrated sensing for industrial zone oversight.
Wind Farm Operators dominate current procurement volumes while Utility Companies expand most quickly as grid-scale renewable portfolios multiply.
Deployment:
Physical installation constraints separate capital-intensive permanent infrastructure from rapidly redeployable measurement campaigns, with offshore environments demanding specialized marine-grade engineering.
- Offshore:Salt-air corrosion resistance and motion compensation define system requirements. Floating platform deployments in the North Sea and Celtic Sea create specialized demand beyond fixed-foundation capabilities.
- Onshore:Ground-based and nacelle-mounted configurations serve established wind belt development. Chinese state-backed wind bases concentrate procurement of cost-optimized units for turbine control.
- Fixed:Permanent meteorological mast and platform installations support long-term resource monitoring. Certification timelines under IEC 61400-12-1 favor stable deployment configurations for warranty compliance.
- Mobile:Trailer-mounted and vessel-deployed units enable rapid site screening and campaign measurement. Brazilian pre-development wind resource campaigns utilize these systems for early-mover positioning.
Onshore deployment retains the volume base while Offshore climbs the fastest as deep-water projects proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Northern European waters where floating certification commands premiums, while Chinese procurement scales compress unit economics at the volume base.
China
The National Energy Administration mandates LIDAR integration across state-backed wind bases, locking in procurement volumes for nacelle-mounted systems. MIIT's equipment certification protocols favor domestic suppliers for grid-connected projects. Yangtze River Delta turbine OEMs consolidate purchasing through central planning mechanisms that standardize sensor specifications.
Germany
North Sea floating projects drive specialized demand for motion-compensated platforms beyond fixed-foundation limits. The EU F-Gas Regulation forces sulfur hexafluoride elimination from auxiliary systems by 2030, accelerating redesign timelines. Hamburg and Bremerhaven maritime clusters concentrate engineering talent for platform-stabilized measurement architectures.
United Kingdom
Celtic Sea deep-water developments exceed fixed-foundation viability, creating first-mover advantage for floating LIDAR deployments. The Crown Estate's offshore leasing rounds mandate pre-construction resource validation using certified remote sensing. Scottish maritime research institutes in Aberdeen and Edinburgh anchor specialized signal processing capabilities for motion-compensated systems.
Denmark
Wake-steering algorithm deployment in Danish offshore clusters embeds scanning LIDAR into OEM control architectures for real-time yaw optimization. National grid codes require hub-height wind characterization for warranty-compliant power curve verification. Copenhagen-area project financiers unbundle service contracts to reduce counterparty risk in 25-year asset structures.
Brazil
Búzios and Mero field adjacencies drive pre-development wind resource campaigns where floating LIDAR secures early-mover site control. ANVISA's environmental licensing timelines compress measurement campaign windows, favoring rapidly deployable mobile units. Rio de Janeiro and São Paulo engineering consultancies coordinate offshore resource assessment for licensing round preparation.
Global Wind LIDAR Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in laser source and photodetector supply. The vendor base separates between meteorological heritage players anchoring utility-scale validation programs and manufacturing-scale specialists serving cost-sensitive turbine OEM procurement. Three archetypes dominate: certification-driven system integrators, volume-focused nacelle-mounted suppliers, and floating-platform technical specialists. Competitive moves concentrate on motion-compensation engineering recruitment and SF6-free product architecture redesign ahead of regulatory deadlines.
Among Nordic meteorological heritage players, Vaisala anchors utility-scale validation programs across Northern European waters. Chinese manufacturing-scale specialists include Movelaser, which occupies the nacelle-mounted tier for domestic turbine OEM procurement. ZX Lidars represents the floating-platform technical specialist archetype, positioned for deep-water deployments beyond fixed-foundation limits. These three exemplify how geographic origin and technical focus stratify competitive positioning across certification-driven, volume-driven, and innovation-driven market segments.
| Leading Market Players |
|---|
| Vaisala |
| Movelaser |
| ZX Lidars |
| John Wood Group |
| Lockheed Martin |
| Qingdao Leice Transient Technology |
| Windar Photonics |
| Lumibird |
| Huahang Seaglet |
| Others |
Value Chain & Pricing Dynamics
East Asian foundry concentration in precision laser sources and photodetector arrays funnels margin capture downstream toward certified system integrators serving IEC 61400-12-1 mandates, while cost-optimized nacelle-mounted suppliers compete on manufacturing scale for Chinese wind base procurement.
Pricing Analysis
Configured-to-order pricing for motion-compensated floating platforms commands three-to-four multiples over standard nacelle-mounted units. Three-tier pricing structure across certified-premium, standard-compliance, and economy-volume levels reflects IEC certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because Chinese turbine OEMs consolidate purchasing through central planning mechanisms. Utility-scale offshore developers exhibit lowest price sensitivity, prioritizing warranty-compliant certification over unit economics.
Supply Chain Analysis
Precision laser diodes and avalanche photodetectors draw from specialized foundries in Japan, Taiwan, and South Korea. Optical coating substrates and fiber-coupled beam delivery systems rest on German and Swiss precision manufacturing. Single-source vulnerability in 1550nm laser sources creates exposure to export licensing shifts. Distribution runs through turbine OEM specification channels and independent service provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind LIDAR procurement is shifting toward platform-economics logic as wake-steering algorithms and digital twin convergence demand interoperable data feeds across OEM control architectures.
For Market Incumbents: Entrench certification leadership through accelerated IEC 61400-12-1 type-approval for motion-compensated floating platforms before regulatory protocols solidify. Capture in-house production of solid-state beam steering modules to eliminate mechanical parts maintenance in salt-air environments. Counter emerging volume-focused Chinese suppliers by unbundling long-term calibration and data validation services to reduce project financier counterparty risk.
For New Entrants and Emerging Players: Build out specialized engineering capabilities in marine dynamics and real-time signal processing for floating-platform deployments beyond fixed-foundation limits. Brazil's pre-development offshore resource campaigns present the most penetrable geography, where rapidly deployable mobile units compress measurement windows ahead of ANVISA environmental licensing. Partner with Rio de Janeiro engineering consultancies to anchor early-mover positioning in licensing round preparation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with meteorological heritage players holding utility-scale validation relationships across Northern European waters. Five-to-ten year viability hinges on SF6-free product architecture completion ahead of EU F-Gas Regulation deadlines. Monitor floating offshore certification protocol finalization as the inflection signal determining which technology suppliers secure preferred vendor status in deep-water markets.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Product Architecture Redesign | Eliminates sulfur hexafluoride from thermal management systems to meet EU F-Gas Regulation compliance deadlines in North Sea markets. |
| Motion-Compensated Platform Certification | Secures IEC 61400-12-1 type-approval for floating LIDAR ahead of evolving deep-water regulatory protocols. |
| Solid-State Beam Steering Integration | Replaces mechanical scanning with chip-based phased arrays to compress maintenance intervals in offshore salt-air environments. |
| Service Unbundling and Independent Validation | Separates equipment supply from calibration services to reduce counterparty risk in 25-year European project finance structures. |
| Wake-Steering Algorithm Partnership | Embeds scanning LIDAR into OEM control architectures for real-time yaw optimization in Danish offshore clusters. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with wind farm operators, turbine OEM procurement directors, EPC contractors, and offshore project financiers; and secondary validation against IEC certification databases, National Energy Administration procurement disclosures, EU F-Gas Regulation implementation timelines, and floating platform project development trackers. Bottom-up unit economics triangulated against top-down market sizing across technology and deployment segments.
Forecast inputs span technology substitution rates between continuous-wave and pulsed laser architectures, offshore floating project pipeline conversion probabilities, and Chinese wind base procurement trajectories. Segmentation modeling covers Doppler, pulsed, continuous-wave, and scanning configurations across onshore, offshore, fixed, and mobile deployments. CAGRs derive from fitted growth curves calibrated to disclosed procurement volumes and announced manufacturing capacity additions.
Practitioners should monitor IEC floating-platform certification protocol evolution and Chinese state-backed wind base procurement acceleration for early signals requiring forecast revision. Cross-checking against Crown Estate offshore leasing round timelines and ANVISA environmental licensing velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Global Marine Wind Turbine Market