
 Wind Power Market | 2026-2036
Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Market Intelligence
Operations and maintenance (O&M) service revenue is fragmenting as asset owners seek third-party and in-house solutions over OEM-exclusive contracts. This shift creates new competitive dynamics for established turbine manufacturers. Siemens Gamesa Renewable Energy specializes in high-capacity offshore turbine technologies to capture value. In contrast, GE Vernova leverages its broad energy portfolio to offer integrated solutions spanning generation and grid infrastructure.
Wind power involves the conversion of kinetic energy from air movement into electricity via turbines, which use airfoil-shaped blades often made from carbon fiber composites. Its primary purpose is large-scale power generation for utilities and industrial consumers. While the Onshore segment constitutes the largest installed base, the Offshore segment is expanding rapidly, driven by higher wind speeds. Turbines with capacity Above 5 MW are becoming standard for new utility-scale projects.
Regulatory frameworks are central to project development and investment security. The EU Green Deal and the US Inflation Reduction Act (IRA) provide significant tax credits and subsidies for wind energy projects. In parallel, China's dual carbon goals mandate massive expansion of renewable capacity, including wind power. Stakeholder focus is shifting toward securing supply chains for rare earth elements and managing grid intermittency at scale.
Market Dynamics
The convergence of national energy security mandates and supply chain vulnerabilities for critical materials is the central force shaping the wind power market. This dynamic compels governments to de-risk projects while pushing manufacturers to re-evaluate sourcing strategies.
Growth Catalysts
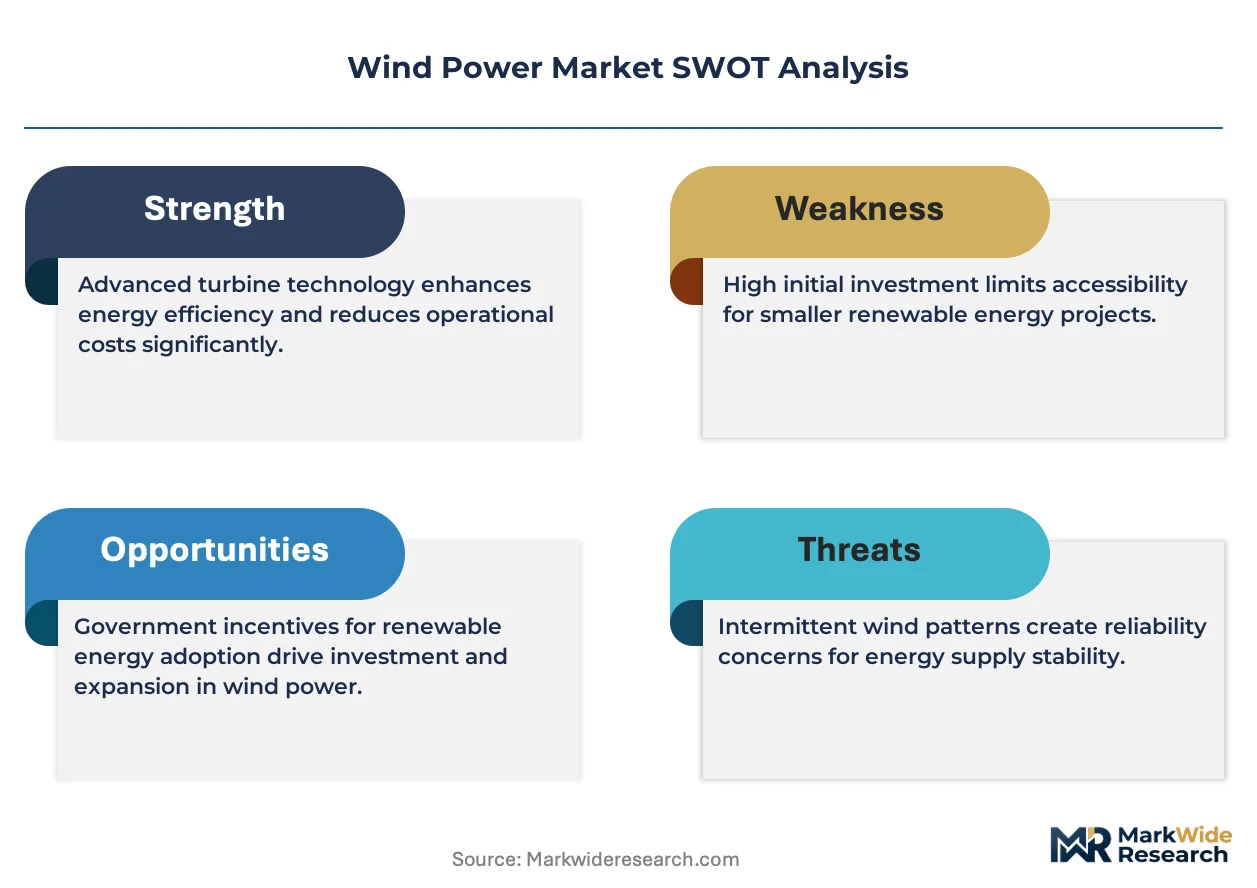
- Supportive Regulation:The US Inflation reduction Act and EU Green Deal provide significant subsidies, creating a stable investment climate for new utility-scale wind projects.
- Corporate Procurement:Industrial consumers are driving demand through power purchase agreements to secure low-cost renewable electricity and meet sustainability goals.
- Advanced Turbine Designs:Turbines exceeding 5 MW in capacity improve energy capture with longer carbon fiber blades, lowering the overall cost of generation.
Market Restraints
- Supply Chain Bottlenecks:Reliance on China for rare earth elements, essential for direct-drive turbines, creates significant geopolitical risk and price volatility for manufacturers globally.
- Grid Intermittency:Variable output from wind farms necessitates major investment in energy storage and grid upgrades to maintain electricity supply stability and prevent curtailment.
- Capital Intensity:Offshore wind projects demand massive upfront investment in foundations and specialized vessels, acting as a significant barrier for new developers.
Strategic Opportunities
- Floating Offshore Wind:New floating foundation technologies unlock deep-water sites, creating project opportunities in geographies like the US West Coast and Japan.
- Green Hydrogen Integration:Co-locating wind farms with electrolyzers to produce green hydrogen provides a new offtake market and a way to store surplus electricity.
- Service Market Disruption:The shift from OEM-exclusive contracts creates an opening for independent service providers to offer specialized O&M for post-warranty assets.
Industry Challenges
- Specialized Workforce Gaps:A shortage of qualified technicians exists for maintaining high-capacity offshore turbines, especially for work in demanding marine environments.
- Component Logistics:Transporting and installing immense turbine blades and nacelles requires specialized port infrastructure and vessels, creating bottlenecks for large-scale projects.
- Protracted Permitting:Securing approvals for new wind farms involves lengthy reviews by multiple agencies, often delaying project timelines and increasing development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Market |
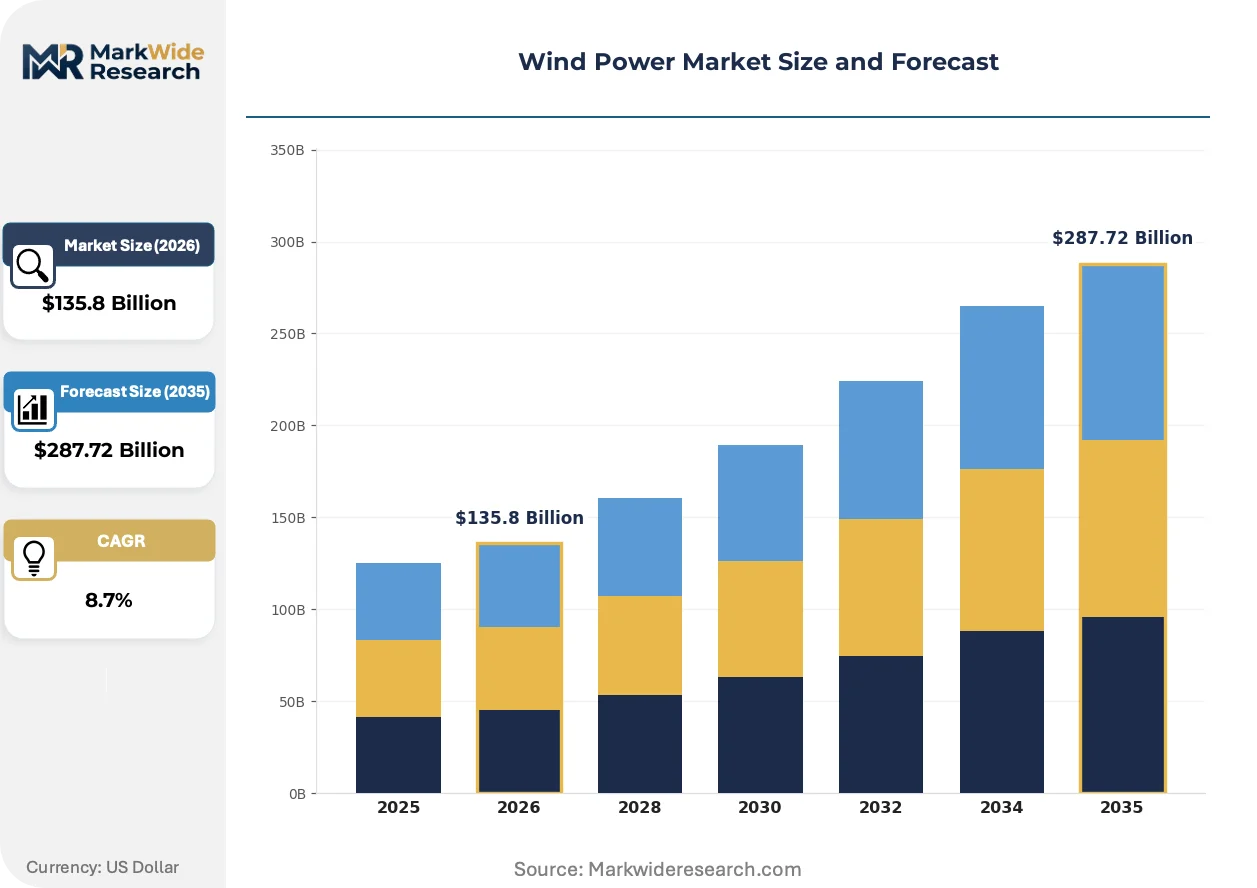
| Market Size in 2026 | $135.8 Billion |
| Market Size in 2035 | $287.72 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Onshore, Offshore, Floating, Small Wind Turbine Capacity: Below 1 MW, 1-3 MW, 3-5 MW, Above 5 MW Application: Power Generation, Distributed Energy, Grid Support, Remote Power Supply End User: Utility Companies, Independent Power Producers, Microgrid Operators, Industrial Power Consumers |
| Companies Covered | Vestas Wind Systems, GE Vernova, Siemens Gamesa Renewable Energy, NextEra Energy Resources, Goldwind Science & Technology, Invenergy, Acciona Energías Renovables, Adani Green Energy, Envision Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Market Strategic Shifts & Innovations
Technological evolution in asset management is converging with new regulatory frameworks and service delivery models. This combination is actively reconfiguring operational strategies and value capture across the wind power lifecycle, moving the focus toward efficiency and lifetime extension.
Digital twin technology creates virtual replicas of physical wind turbines, using sensor data to simulate performance and predict failures. Asset owners and O&M providers are adopting this for entire wind farms to optimize maintenance schedules. This advanced modeling capability is collapsing the gap between planned and unplanned maintenance, dramatically reducing costly turbine downtime.
The European Union's Green Deal framework includes provisions to accelerate permitting for renewable energy projects. This policy designates wind energy as an overriding public interest, compelling member states to streamline their approval processes. The offshore wind segment in countries bordering the North Sea is most affected, with developers now able to fast-track project development schedules.
A clear shift away from bundled, long-term OEM service agreements is underway as asset owners gain operational expertise. This unbundling sees turbine owners using a mix of in-house teams and specialized independent service providers (ISPs) for post-warranty maintenance. The trend is most visible in mature onshore markets across North America and Europe.
Wind Power Market Segmentation
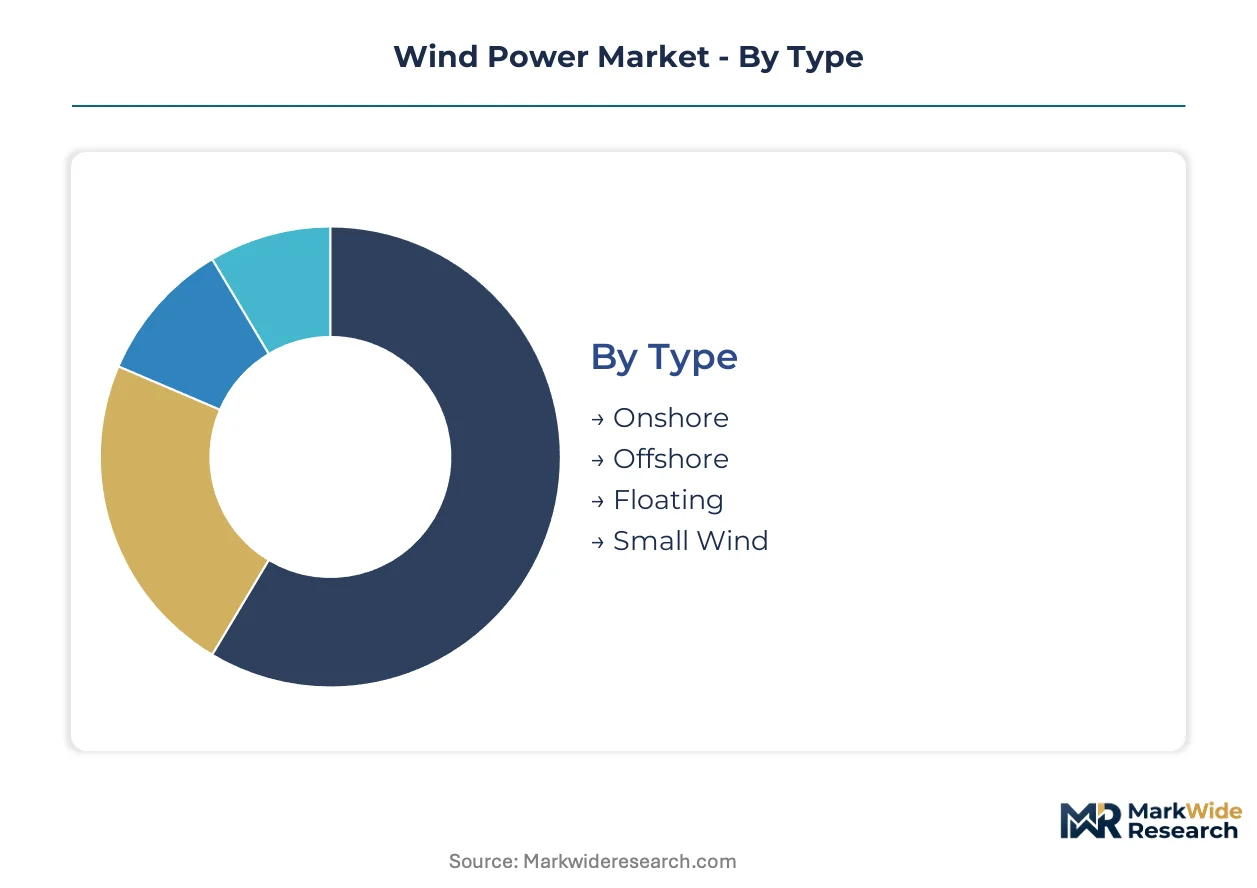
Understanding the segmentation of the wind power market reveals the diverse technological approaches and end-use applications driving its expansion. This detailed breakdown helps identify areas of established growth and emerging opportunities for stakeholders across the value chain.
Type:
The maturity spectrum of wind power technologies ranges from well-established ground-mounted systems to innovative deep-water solutions.
- Onshore:These wind farms deploy turbines on land, connecting to existing grid infrastructure. Demand concentrates in China, the United States, and India, driven by lower installation costs and readily available land resources for utility-scale projects.
- Offshore:Turbines are installed in coastal waters, benefiting from stronger and more consistent wind speeds. Europe, particularly countries bordering the North Sea, and emerging markets in Asia are driving significant investment due to higher energy yields and less land-use conflict.
- Floating:This emerging technology involves turbines mounted on floating platforms, unlocking deep-water sites previously inaccessible. Project opportunities are developing off the coasts of Japan and the US West Coast, expanding the geographic potential for wind energy.
- Small Wind:These smaller-scale turbines typically serve residential, agricultural, or remote off-grid applications. They provide localized power generation for individual homes and businesses, enhancing energy independence.
Onshore retains volume leadership; Offshore holds the steepest expansion curve.
Turbine Capacity:
Volume distribution across different capacity ranges defines the market's technological evolution and its suitability for various project scales.
- Above 5 MW:These high-capacity turbines are becoming the standard for new utility-scale projects, particularly in offshore environments. They maximize energy capture per turbine, significantly lowering the levelized cost of electricity for large power producers.
- 3-5 MW:This capacity range represents a common choice for new onshore utility-scale wind farms across Europe and North America. Developers select these turbines for their balance of efficiency, operational reliability, and proven performance characteristics.
- 1-3 MW:Mid-range turbines are often deployed in smaller wind farms or utilized for repowering older sites in mature markets. These units offer a balance between cost-effectiveness and energy output for regional projects.
- Below 1 MW:These smaller turbines primarily cater to distributed energy generation, microgrid applications, and remote power solutions. They are crucial for localized energy production in areas with limited grid access.
The shift towards higher capacity turbines reflects industry efforts to optimize energy yield and project economics.
Application:
The functional roles wind power fulfills span various energy needs, from large-scale grid supply to specialized off-grid solutions.
- Power Generation:This primary application involves the large-scale production of electricity for national and regional grids, serving utility companies and industrial consumers. It forms the backbone of renewable energy integration into mainstream power systems.
- Distributed Energy:This application focuses on localized power production, often smaller in scale, to serve specific communities or industrial sites directly. It reduces transmission losses and enhances local energy resilience for businesses and remote areas.
- Grid Support:Wind farms increasingly contribute to grid stability by providing ancillary services, helping balance supply fluctuations from other variable renewable sources. This role is vital for maintaining overall electricity system reliability.
- Remote Power Supply:Isolated communities, telecommunications infrastructure, and off-grid industrial operations utilize wind power for reliable electricity. These systems often combine wind with other renewables and storage for continuous power.
Core power generation remains the dominant application, while distributed and grid support functions gain strategic importance.
End User:
Procurement patterns for wind energy are diversifying across several key user groups, each with distinct investment drivers and operational models.
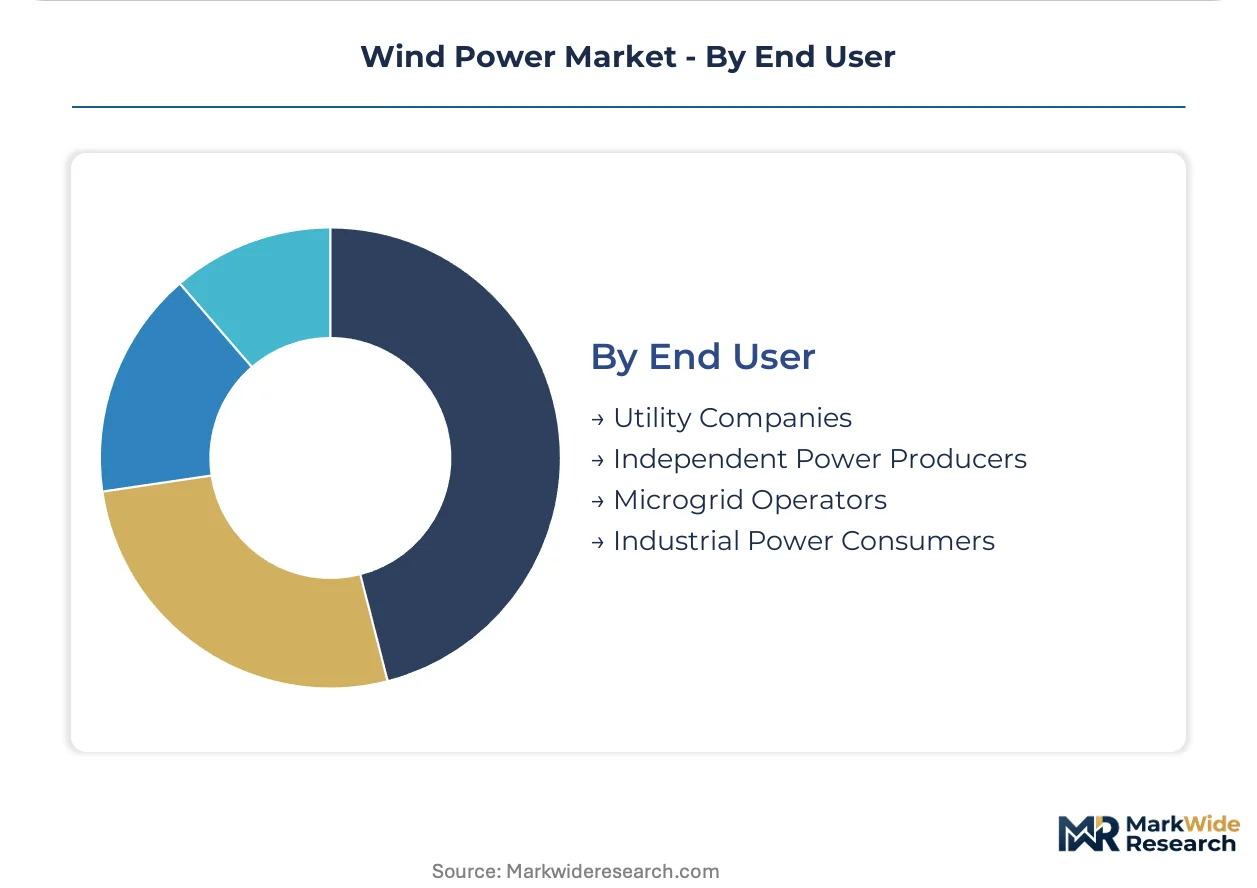
- Utility Companies:These entities are the largest purchasers of wind power, integrating it into national and regional electricity grids for broad distribution. Their investment secures stable, large-scale renewable energy sources to meet regulatory mandates and consumer demand.
- Industrial Power Consumers:Corporations with high energy demands procure wind power directly through power purchase agreements to meet sustainability goals and secure low-cost, stable electricity. This trend is prominent in sectors like manufacturing and data centers in the US and Europe.
- Independent Power Producers:These developers construct and operate wind farms, selling electricity to utilities or directly to consumers under long-term contracts. They play a significant role in financing and developing new projects globally.
- Microgrid Operators:Organizations managing localized grids integrate wind power to enhance energy resilience, reduce reliance on centralized power sources, and lower operational costs. This is critical for campus environments and remote industrial sites.
Traditional utility procurement continues to anchor demand, with industrial consumers increasingly shaping new project development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global wind power market exhibits a significant concentration of supply chain elements and manufacturing capabilities in specific regions. This dynamic influences project development and technology deployment worldwide. China's dominance in new capacity installations and critical material supply chains shapes the overall market landscape.
China
Demand is driven by massive renewable capacity expansion and industrial energy needs. China's dual carbon goals mandate extensive wind power development across the country. Coastal provinces like Jiangsu are seeing substantial offshore wind farm development and component manufacturing activities.
United States
Industrial power consumers and utility companies drive demand for large-scale wind projects. The US Inflation Reduction Act provides significant tax credits for wind energy projects. Texas continues to lead in onshore wind capacity, with new projects expanding across the Midwest.
Germany
Energy independence goals and decarbonization targets stimulate demand for both onshore and offshore wind. The EU Green Deal framework accelerates permitting for renewable energy projects. The North Sea region is a hub for offshore wind development, with specialized port infrastructure supporting installations.
India
Rapid industrialization and electrification efforts are boosting demand for utility-scale wind power. National renewable energy targets and state-level policies support new wind farm investments. Gujarat and Tamil Nadu are key states for onshore wind development, attracting significant project investments.
Japan
Energy security concerns and limited land availability foster demand for floating offshore wind technologies. METI initiatives support research and development in deep-water wind solutions. The waters off Fukushima are becoming a testing ground for innovative floating wind turbine deployments.
Wind Power Market Key Industry Players
Dedicated turbine manufacturers and diversified energy conglomerates split the market for wind power solutions, creating a complex competitive environment. This market structure reflects a blend of specialized technology focus and broad energy portfolio integration across generation and grid infrastructure. Strategic archetypes include high-capacity offshore specialists and integrated energy solution providers. Competitive dynamics are shaped by continuous technology advancements in turbine design and strategic partnerships aimed at securing critical supply chains.
Within the global turbine manufacturing tier, Vestas Wind Systems and Goldwind Science & Technology exemplify specialized wind energy OEMs. Vestas, a Danish company, focuses on developing and deploying advanced wind turbine technology, particularly in high-capacity segments. Goldwind Science & Technology, a Chinese corporation, occupies a significant position in onshore wind installations globally. GE Vernova, a US-based entity, represents the diversified energy conglomerate archetype, leveraging its extensive portfolio across power generation and grid infrastructure solutions.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| GE Vernova |
| Siemens Gamesa Renewable Energy |
| NextEra Energy Resources |
| Goldwind Science & Technology |
| Invenergy |
| Acciona Energías Renovables |
| Adani Green Energy |
| Envision Energy |
Cost & Logistics Intelligence
Offshore wind project undercapacity in Europe currently drives supplier behavior and pricing posture for specialized vessels and foundation components. This utilization signal reflects the rapid expansion curve in the North Sea region.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for wind energy projects, favoring long-term, contract-based power purchase agreements. Price differentiation stems from turbine capacity and geographic delivery costs, particularly for offshore installations. Pricing softness reflects intense competition among developers in mature onshore markets. Industrial power consumers exhibit the highest price sensitivity, while utility companies prioritize long-term supply stability over marginal cost savings.
Supply Chain Analysis
Reliance on China for rare earth elements dominates the wind power supply chain, creating significant geopolitical risk. Key inputs also include carbon fiber composites from Europe and specialized steel from various global producers. Single-source vulnerability for critical components affects turbine manufacturers like Vestas Wind Systems and Goldwind Science & Technology. Distribution centers on direct sales from OEMs to project developers or long-term contracts with utility companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wind power market presents a fragmentation opportunity as corporate procurement for green energy creates diverse niches. Industrial power consumers actively seek tailored solutions for their sustainability goals.
For Market Incumbents: Pre-empt the service market disruption by investing in advanced digital twin technology for predictive maintenance. This mitigates the threat from independent service providers offering specialized O&M for post-warranty assets. Siemens Gamesa Renewable Energy should expand its capacity for high-capacity offshore turbine manufacturing in key European hubs. Deepen vertical integration into specialized component production to secure critical supply chains.
For New Entrants and Emerging Players: Pursue floating offshore wind projects in geographies like Japan and the US West Coast, leveraging new foundation technologies. Target the deep-water sites that traditional fixed-bottom offshore wind cannot access. The offshore segment presents the most penetrable white space due to its rapid expansion and specialized requirements. Offer integrated green hydrogen solutions co-located with wind farms as a unique value proposition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent power producers and specialized O&M providers with long-term service contracts. These entities offer stable cash flows over the long term, making them attractive acquisition targets. Focus on firms with strong portfolios of post-warranty assets in mature onshore markets. The signal to watch is the acceleration of permitting for new utility-scale projects in Europe and the US.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout in Offshore Wind | Siemens Gamesa Renewable Energy can capture value from high-capacity turbine demand in the North Sea. |
| Green Hydrogen Project Integration | GE Vernova leverages its broad energy portfolio to create new off-take markets for surplus wind power. |
| Digital Twin Technology Adoption | Asset owners optimize maintenance schedules and reduce costly turbine downtime across entire wind farms. |
| Supply Chain Diversification for Rare Earths | Goldwind Science & Technology mitigates geopolitical risk and price volatility for direct-drive turbines. |
| Specialized Workforce Development | Addressing the shortage of qualified technicians ensures efficient O&M for high-capacity offshore turbines. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through public data sources. Conversations with utility planning officers, IPP project developers, EPC contractors, and grid operators provided qualitative insights. Secondary data included EIA data, IEA reports, FERC filings, and project development databases for bottom-up and top-down triangulation. This approach ensured comprehensive market understanding.
Forecast inputs considered included installed capacity additions, technology advancements, and regulatory support mechanisms. The analytical framework modeled segmentation across turbine type, capacity, application, and end-user, along with regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected investment cycles over the projection horizon. Specific inputs included carbon fiber composite pricing and rare earth element availability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large utility companies or national governments would shift outcomes. Forecasts reflect assumptions regarding policy stability and technology adoption rates, with geopolitical disruptions to critical material supply chains as a key risk factor. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Global Wind Power Equipment Market