
 Global Power Supply Market | 2026-2036
Global Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Supply Market Intelligence
The push for 80 PLUS Titanium efficiency certification is redrawing the competitive landscape for high-wattage units, especially in server and data center applications. Delta Electronics leverages its massive manufacturing scale to deliver these high-efficiency designs for major OEMs. Siemens AG integrates its power supply portfolio directly into its industrial automation platforms, creating a captive customer base. Murata Manufacturing differentiates through its expertise in ultra-compact, high-reliability DC-DC converters for embedded systems.
A power supply converts power from a source, like an AC outlet, into the specific DC voltage and current required by electronic components. Modern units primarily use switching-mode technology for high efficiency and compact form factors. While AC-DC supplies form the largest product segment, demand for DC-DC converters is growing in telecommunications and industrial automation. Requirements for data centers focus on extreme power density, contrasting with the ruggedness needed in industrial settings.
Compliance with electromagnetic compatibility standards, such as FCC Part 15 in the United States and the CE marking framework in Europe, is mandatory for market access. Concurrently, the EU's RoHS directive restricts the use of specific hazardous materials, influencing material selection and supply chain management. Vendors must continuously balance the engineering tradeoffs between higher efficiency, component cost, and effective thermal management to remain competitive.
Market Dynamics
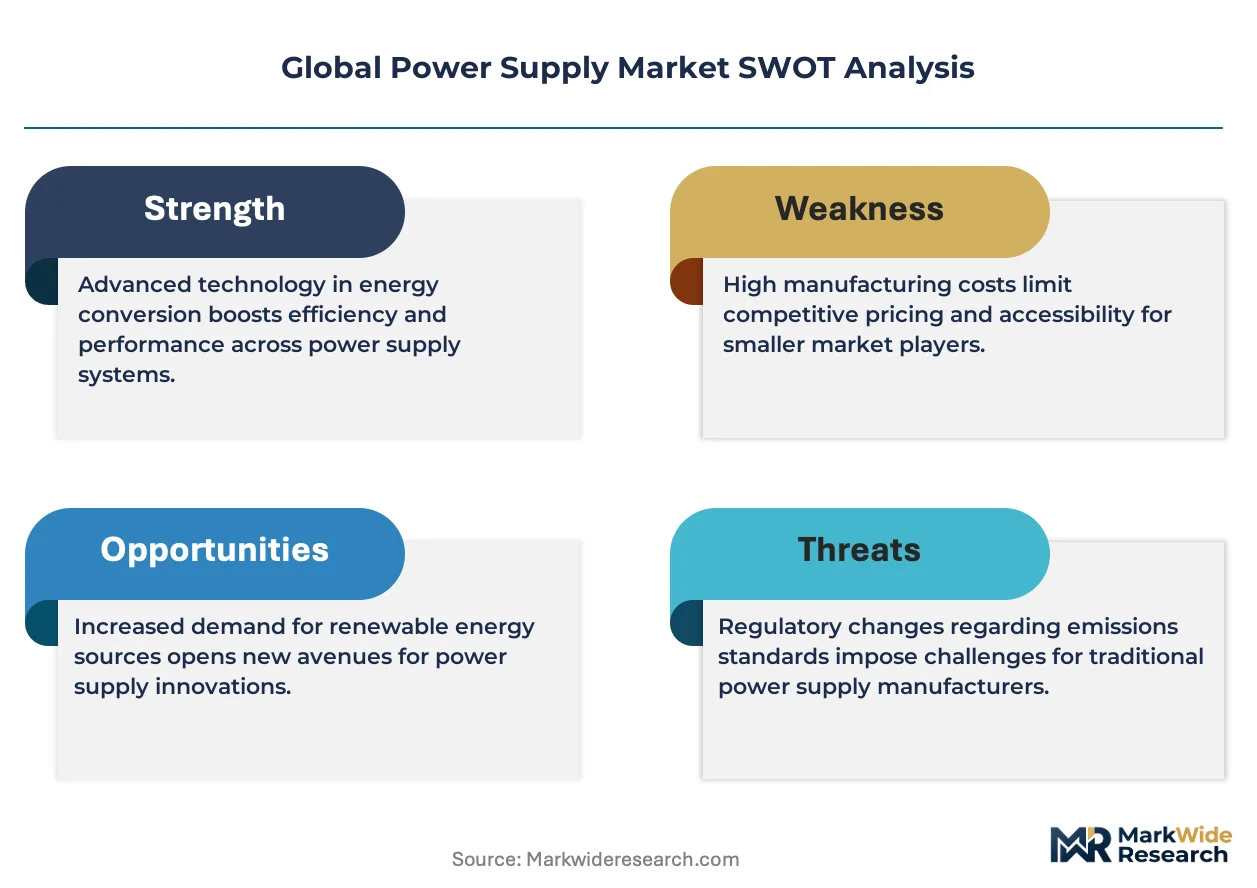
The fundamental market dynamic is the tension between escalating power density requirements from data centers and the physical limitations of thermal management. This conflict forces innovation in materials science, particularly the adoption of wide-bandgap semiconductors to achieve higher efficiency.
Growth Catalysts
- Data Center Expansion:The construction of new hyperscale data centers, especially in the United States and China, creates sustained demand for high-wattage power supplies that meet stringent 80 PLUS Titanium efficiency standards to minimize operational costs.
- Wide-Bandgap Semiconductors:The commercialization of Gallium Nitride (GaN) and Silicon Carbide (SiC) components enables smaller, more efficient power converters, opening new design possibilities for compact consumer electronics and telecom infrastructure.
- Ecodesign Regulations:Mandates such as the EU's Ecodesign Directive for external power supplies enforce stricter no-load and active-mode efficiency levels, compelling manufacturers to abandon older, less efficient topologies across a wide range of products.
Market Restraints
- Component Cost Premium:The higher manufacturing cost of GaN and SiC substrates and devices compared to mature silicon technology slows their adoption in cost-sensitive, high-volume applications like entry-level consumer goods.
- Thermal Management Complexity:Increasing power density concentrates heat generation, requiring more sophisticated and expensive thermal solutions like liquid cooling or advanced heat sink designs, which can offset the size benefits of new components.
- Magnetic Component Limitations:The performance of high-frequency power supplies is often constrained by the physical and material properties of magnetic components like inductors and transformers, which have not advanced as rapidly as semiconductors.
Strategic Opportunities
- Electric Vehicle Infrastructure:The global build-out of EV charging stations presents a significant opportunity for high-power AC-DC converters for Level 3 DC fast chargers and onboard DC-DC converters within vehicles.
- Digital Power Management:Integrating microcontrollers and digital signal processors allows for adaptive power control, real-time monitoring, and communication, creating value in smart grid applications and industrial automation.
- Industrial IoT Deployments:The proliferation of sensors and edge computing devices in manufacturing environments, particularly in Germany and Japan, requires a vast number of compact, highly reliable, low-power DC-DC converters.
Industry Challenges
- Regulatory Compliance Burden:Adhering to a complex web of international standards, including FCC Part 15 for electromagnetic interference in the US and the CE marking framework in Europe, adds significant testing time and expense to product development.
- Power Engineering Talent Scarcity:A persistent shortage of analog and power electronics engineers with expertise in high-frequency magnetics design and advanced control loop theory hampers research and development efforts.
- Supply Chain Volatility:The supply of critical passive components, such as multilayer ceramic capacitors (MLCCs) and resistors, is subject to periodic shortages and price fluctuations that can disrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Supply Market |
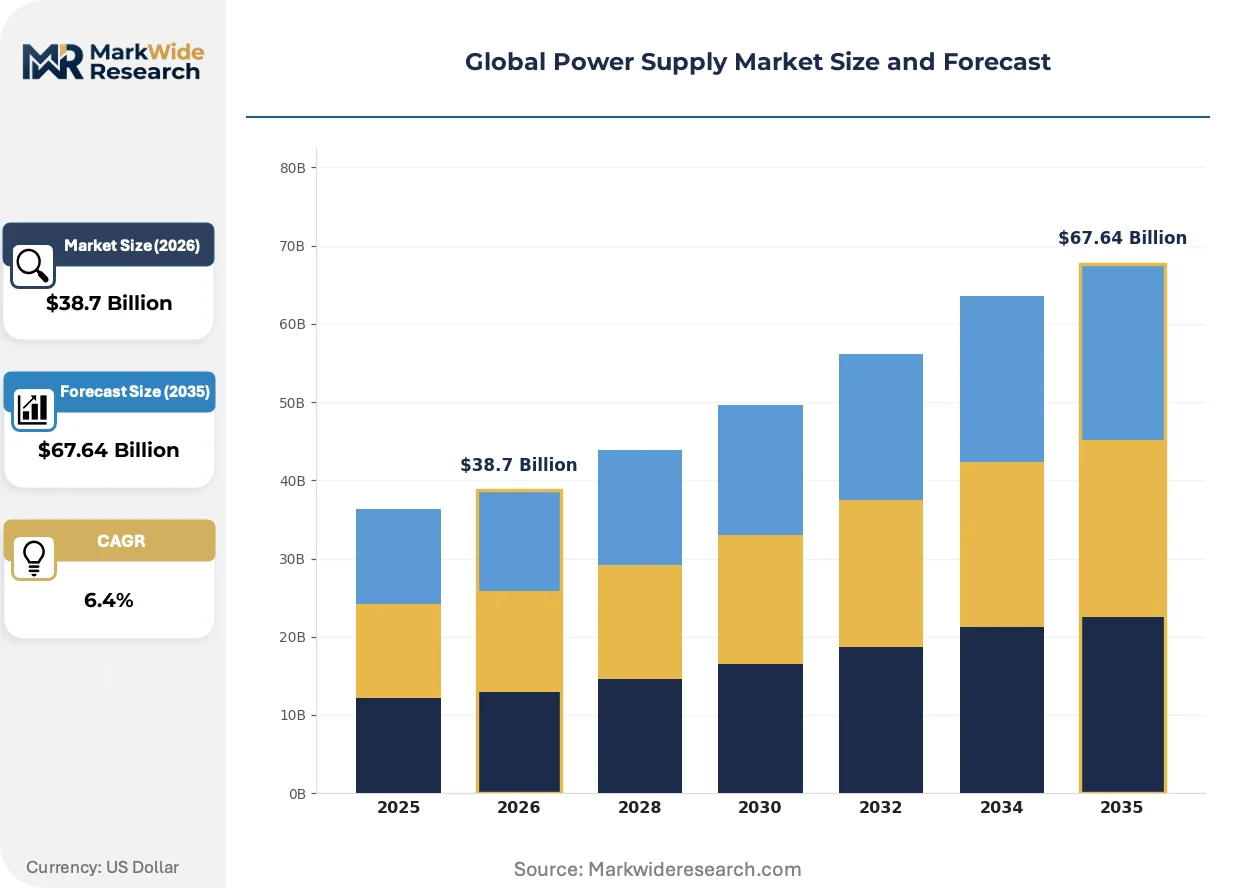
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC-DC Power Supplies, DC-DC Converters, Uninterruptible Power Supplies, Programmable Power Supplies Technology: Switching, Linear, Modular, Embedded Application: Telecommunications, Data Centers, Industrial Automation, Consumer Electronics End User: OEMs, Tier-1 Manufacturers, System Integrators, Aftermarket Service Providers |
| Companies Covered | Delta Electronics, TDK Corporation, Siemens AG, MEAN WELL Enterprises, XP Power, Murata Manufacturing, ABB Ltd, Phoenix Contact, Advanced Energy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Supply Market Strategic Shifts & Innovations
Material science advancements and the integration of digital control are transforming power supplies from simple converters into intelligent power management subsystems. This shift enables greater efficiency and application-specific performance, moving the market beyond generic, one-size-fits-all designs.
Wide-bandgap semiconductors like Gallium Nitride (GaN) provide superior thermal and electrical properties compared to traditional silicon. Enterprise and consumer electronics sectors are leading the adoption for server power supplies and fast chargers. This technological shift is fragmenting the market, moving it from general-purpose silicon designs to highly optimized GaN solutions for specific power and density needs.
The EU's RoHS directive, which restricts hazardous substances in electrical equipment, directly influences material selection and supply chain management globally. This regulation compels manufacturers to find and qualify lead-free solders and compliant components, a continuous engineering effort. The medical device and aerospace power supply segments are most affected, as their long product lifecycles and stringent validation processes make component substitution particularly challenging.
A definitive preference for certified performance is altering purchasing behavior, especially in enterprise applications. The 80 PLUS Titanium certification, for example, is now a key decision criterion for data center operators, shifting focus from upfront cost to total cost of ownership. This trend is most visible in North American and European data center procurement, where high energy costs make efficiency a primary operational concern.
Global Power Supply Market Segmentation
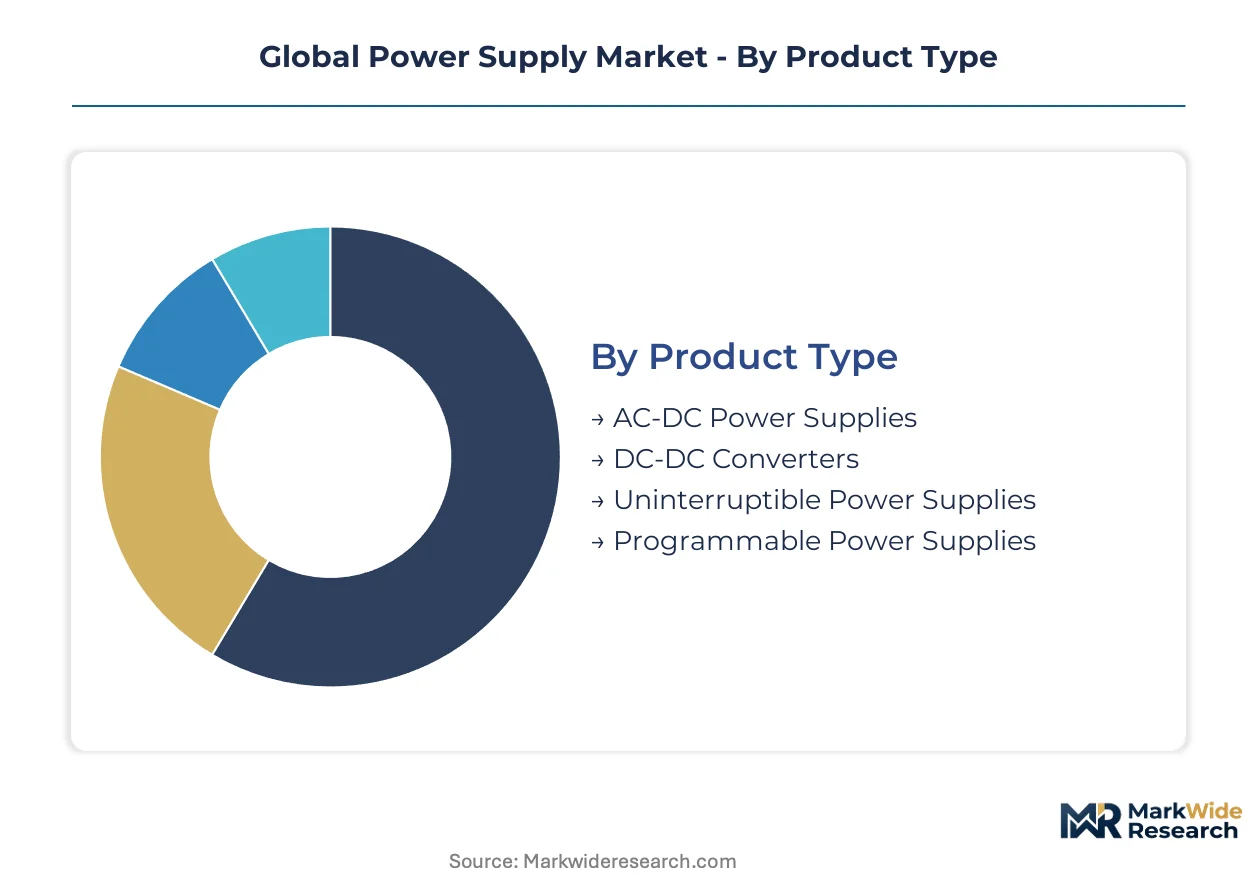
The global power supply market is segmented across diverse product types, technologies, applications, and end users, reflecting the varied demands of modern electronic systems. Understanding these segments is crucial for identifying areas of concentrated growth and specific technological requirements.
Product Type:
The product type segmentation reveals how different power conversion solutions cater to specific regional and industrial needs, often driven by domestic manufacturing capabilities versus export-led demand for specialized units.
- AC-DC Power Supplies:These units convert alternating current from a wall outlet into a stable direct current, forming the largest product segment. Demand concentrates in China and the United States for data center infrastructure, where high-efficiency 80 PLUS Titanium certified units minimize operational costs.
- DC-DC Converters:These devices transform one DC voltage level to another, essential for regulating power within complex electronic systems. Growing demand from telecommunications and industrial automation, particularly in Germany and Japan, drives innovation for ultra-compact, high-reliability designs.
- Uninterruptible Power Supplies:These systems provide emergency power to a load when the input power source fails, ensuring continuous operation. Their primary market is data centers and critical industrial facilities requiring constant uptime.
- Programmable Power Supplies:These units offer adjustable output voltage and current, controlled via analog inputs or digital interfaces. Research and development labs and automated test equipment in North America utilize these for precision control.
AC-DC Power Supplies holds the largest share; momentum sits with DC-DC Converters.
Technology:
Technological segmentation highlights the core engineering approaches to power conversion, with each method optimized for distinct application performance metrics and cost profiles.
- Switching:This technology employs high-frequency switching to achieve high efficiency and compact form factors, making it the dominant method for modern power supplies. Enterprise and consumer electronics sectors in China and the US widely adopt switching power supplies for server and fast charger applications.
- Modular:Modular power supplies consist of a main chassis and interchangeable output modules, offering flexibility and scalability for various voltage and current requirements. Industrial automation platforms and test equipment benefit from the reconfigurability of modular designs.
- Linear:Linear power supplies provide very clean, low-noise DC output but are less efficient and larger than switching types. Audio equipment and sensitive instrumentation still utilize linear designs for their superior ripple rejection.
- Embedded:Embedded power supplies are integrated directly onto a circuit board, designed for specific applications within a larger system. IoT devices and medical equipment often feature custom embedded power solutions for space optimization.
The market favors Switching technology for its efficiency, while Modular designs expand rapidly in industrial settings.
Application:
The application segmentation underscores the diverse end-use environments for power supplies, each with unique performance requirements and regulatory compliance needs.
- Data Centers:This segment demands extreme power density, high efficiency, and robust thermal management for servers and networking equipment. Hyperscale data center expansion in the United States and China drives significant demand for high-wattage, 80 PLUS Titanium certified units.
- Industrial Automation:Power supplies in this sector require ruggedness, high reliability, and often specialized form factors for harsh operating environments. Germany and Japan lead in industrial IoT deployments, creating sustained demand for compact, reliable DC-DC converters.
- Telecommunications:This application requires high-reliability DC-DC converters and AC-DC front ends for network infrastructure, base stations, and communication equipment. The global build-out of 5G networks drives demand for efficient power solutions.
- Consumer Electronics:This segment encompasses power adapters for laptops, smartphones, and other personal devices, emphasizing cost-effectiveness, compact size, and compliance with ecodesign regulations.
Demand for Data Centers is robust, with Industrial Automation seeing significant expansion.
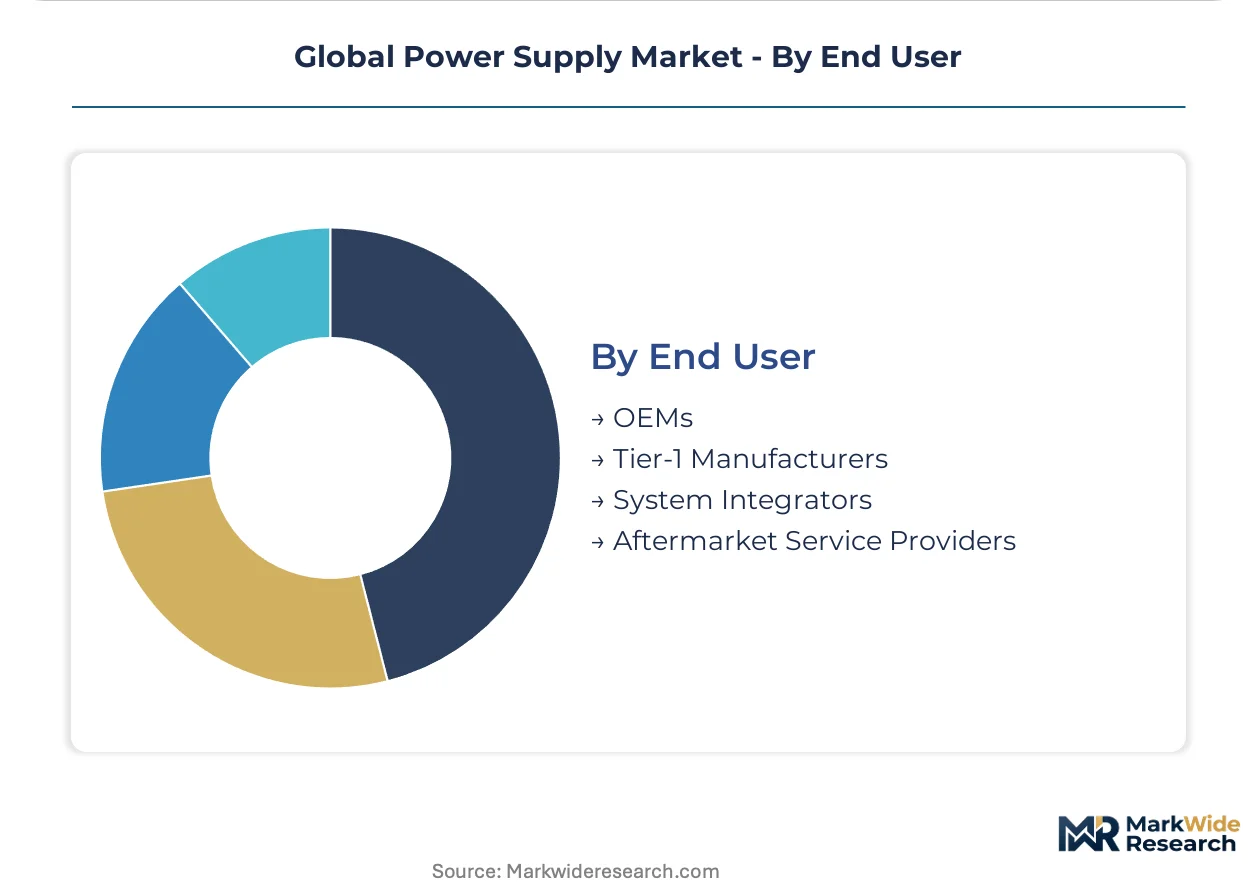
End User:
The end-user segmentation differentiates between the primary purchasers and integrators of power supply units, influencing procurement patterns and product development cycles.
- OEMs:Original Equipment Manufacturers integrate power supplies into their final products, seeking high-volume, cost-effective, and performance-optimized solutions. Delta Electronics serves major OEMs globally with its massive manufacturing scale.
- System Integrators:These entities design and implement complete systems for clients, often requiring custom or specialized power supply configurations. Industrial automation and defense sectors frequently engage system integrators for complex projects.
- Tier-1 Manufacturers:These large manufacturers produce components or sub-assemblies for OEMs, often requiring specific power supply designs for their modules. Automotive and aerospace industries rely on Tier-1 manufacturers for critical subsystems.
- Aftermarket Service Providers:These providers offer repair, maintenance, and replacement services for existing equipment, requiring access to compatible power supply units. The longevity of industrial equipment creates a steady demand for aftermarket support.
Key growth is observed in OEMs, driven by large-scale production, with System Integrators maintaining a steady presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global power supply market exhibits concentrated manufacturing capabilities in specific regions, influencing distribution patterns and technological advancements. This concentration drives specialized production for diverse applications, from hyperscale data centers to compact industrial systems. Key nations are pivotal in both demand generation and supply chain innovation.
United States
Demand for high-wattage power supplies in the United States stems from continuous hyperscale data center expansion. Compliance with FCC Part 15 for electromagnetic interference is mandatory for market entry. Research and development labs in Silicon Valley utilize programmable power supplies for precision control applications.
China
China's robust electronics manufacturing sector and rapid data center construction fuel substantial demand for AC-DC power supplies. Adherence to national GB standards ensures product quality and safety across various applications. The Yangtze River Delta region is a significant center for high-volume production of switching-mode power supplies.
Germany
German industrial automation initiatives and the growth of Industry 4.0 applications create strong demand for rugged power supplies. Products must meet the CE marking framework for European market access, ensuring safety and performance. Bavaria and Baden-Württemberg lead in industrial IoT, driving innovation in digital power management solutions.
Japan
Japanese telecommunications infrastructure and advanced industrial robotics require high-reliability DC-DC converters and specialized power solutions. METI guidelines often influence energy efficiency standards for electronic components. The Kanto region, including Tokyo, focuses on ultra-compact DC-DC converters for advanced electronics and embedded systems.
India
India's expanding digital infrastructure, including new data centers and 5G network rollouts, generates significant power supply demand. BIS certification is crucial for electronic products sold within the country, ensuring quality. Bengaluru and Chennai are emerging data center hubs, driving demand for efficient power units.
Global Power Supply Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global power supply market. The industry structure is tiered, with established multinational corporations competing alongside specialized niche players and high-volume manufacturers. Strategic archetypes include integrated power solution providers, component specialists, and regional assembly houses. Portfolio diversification is a common competitive move, alongside strategic partnerships to expand technological capabilities and geographical reach.
At the scale-driven end, Delta Electronics exemplifies a major OEM supplier, leveraging its extensive manufacturing capacity for high-volume production of AC-DC power supplies. Siemens AG, a German-based multinational corporation, occupies a position as an integrated industrial automation provider, embedding power solutions directly within its broader technology portfolio. Murata Manufacturing, a Japan-headquartered company, sits within the archetype of a component specialist, focusing on ultra-compact, high-reliability DC-DC converters for embedded systems and telecommunications.
| Leading Market Players |
|---|
| Delta Electronics |
| TDK Corporation |
| Siemens AG |
| MEAN WELL Enterprises |
| XP Power |
| Murata Manufacturing |
| ABB Ltd |
| Phoenix Contact |
| Advanced Energy Industries |
| Others |
Cost & Logistics Intelligence
Gallium Nitride (GaN) and Silicon Carbide (SiC) substitution for traditional silicon in power semiconductors simultaneously reshapes the supply geography towards specialized foundries and introduces higher component cost premiums into pricing economics.
Pricing Analysis
The EU's Ecodesign Directive dictates the pricing tier structure for external power supplies, emphasizing efficiency certifications. Price differentiation stems from 80 PLUS Titanium certification levels for data center units and customization required for industrial automation platforms. Pricing pressure stems from the higher manufacturing cost of wide-bandgap semiconductors, particularly in cost-sensitive consumer electronics applications. Data center operators are least price-sensitive due to total cost of ownership considerations, while entry-level consumer goods manufacturers are most price-sensitive.
Supply Chain Analysis
A strategic stockpile preference characterizes the power supply supply chain for critical components, mitigating risks from geopolitical tensions and material shortages. Geographic supply concentration for power supply manufacturing centers in China for high-volume production and in Japan for specialized, high-reliability DC-DC converters. Raw material dependencies include rare earth elements for magnetic components and specialized substrates for GaN and SiC devices. Single-source vulnerability for advanced semiconductor components represents a structural risk. Distribution runs through a blend of direct sales to large OEMs and a network of distributors for smaller system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global power supply market faces a scarcity of analog and power electronics engineers with expertise in high-frequency magnetics design, necessitating strategic investment in talent development.
For Market Incumbents: Fortify core competencies in wide-bandgap semiconductor integration to counter emerging specialized entrants. Invest in advanced thermal management solutions, including liquid cooling, to address escalating power density requirements from hyperscale data centers. Leverage massive manufacturing scale to drive down component costs for high-efficiency designs, maintaining a competitive edge against regional players.
For New Entrants and Emerging Players: Lead with niche solutions for industrial IoT deployments, particularly in Germany and Japan, where demand for compact, reliable DC-DC converters is high. Target the electric vehicle infrastructure segment with high-power AC-DC converters for fast chargers, capitalizing on the rapid build-out of charging networks. Focus on digital power management capabilities as a key go-to-market angle, offering adaptive control and real-time monitoring.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors component specialists with deep expertise in wide-bandgap materials or advanced magnetics. Long-term viability depends on acquiring firms with intellectual property in high-efficiency power conversion topologies for data centers and EV applications. The signal to watch is the increasing adoption rate of GaN and SiC in mainstream server power supplies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in GaN/SiC Manufacturing Capacity | This reduces reliance on external foundries and secures supply for high-growth applications like EVs. |
| Develop Liquid Cooling Solutions | Addresses the critical thermal management challenge in high-density data center power supplies. |
| Expand Digital Power Management Platforms | Enables adaptive control and real-time monitoring, creating value in smart grid applications. |
| Acquire Magnetics Design Expertise | Overcomes limitations in magnetic components, crucial for high-frequency power supply performance. |
| Strengthen Compliance Engineering Teams | Ensures adherence to evolving global standards like FCC Part 15 and the CE marking framework. |
Research Approach
A standing panel of power electronics engineers, data center architects, and industrial automation specialists provided ongoing calibration for the market model. Primary interviews with procurement managers at OEMs, system integrators, and Tier-1 manufacturers were validated against secondary sources like industry association reports, academic research, and regulatory body publications. This iterative process employed both bottom-up and top-down triangulation to ensure data accuracy.
Market volume and value outputs were validated for consistency against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data trends and projected demand from key end-use sectors like hyperscale data centers and 5G network build-outs. Power engineering talent availability served as a critical forecast input.
The analysis sits within stated boundaries; outcomes outside significant shifts in wide-bandgap semiconductor material costs or major regulatory changes would require recalibration. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Revision becomes warranted when component supply chain volatility crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Cogeneration Equipment Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Romania Power EPC Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Gas Insulated Power Equipment Market