
 Wind Turbine Yaw and Pitch Gearbox Market | 2026-2036
Wind Turbine Yaw and Pitch Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Yaw and Pitch Gearbox Market Insights
The direct-to-OEM supply channel is reconfiguring as turbine builders tighten vendor qualification criteria and consolidate preferred supplier lists. Bosch Rexroth AG leverages its hydraulics heritage to dominate pitch system integration for European offshore platforms. Nanjing High Speed Gear Manufacturing anchors high-volume production of megawatt-class yaw gearboxes for domestic Chinese wind farms. Schaeffler Group differentiates through integrated bearing-gearbox assemblies that reduce nacelle weight and maintenance intervals.
Wind turbine yaw and pitch gearboxes are precision speed-reduction drivetrains that translate low-speed, high-torque rotor inputs into controlled blade pitch and nacelle orientation adjustments, typically operating at input torques exceeding 2,000 kNm and output speeds below 30 rpm. These systems incorporate planetary or compound epicyclic stages with case-hardened alloy steel gears and synthetic lubrication circuits to survive 20-year service lives in variable load conditions. The gearbox product segment leads absolute revenue contribution due to replacement cycles and upsizing trends in offshore turbines. Electric technology is displacing hydraulic architectures in pitch control as variable-speed drives improve response precision and eliminate fluid leakage risks. Onshore installation types retain the largest installed base, though offshore deployments command premium pricing for corrosion-resistant designs and redundant sealing systems.
The EU F-Gas Regulation and REACH restrict fluorinated greenhouse gases and hazardous substances in gearbox lubricants, compelling reformulation of synthetic oils and seal materials. China's GB standards and MIIT efficiency mandates enforce domestic content ratios and noise limits for nacelle drivetrain components. Stakeholders must monitor evolving certification requirements for floating offshore platforms and assess backward integration into bearing and seal manufacturing to protect margin pools against raw material volatility.
Market Dynamics
Offshore wind farm operators are consolidating procurement around integrated yaw and pitch system suppliers as turbine capacities scale past 15 MW, compressing vendor lists and raising technical qualification barriers for gearbox manufacturers seeking nacelle integration contracts.
Growth Catalysts
- EU F-Gas Regulation:The framework mandates synthetic lubricant reformulation, creating replacement demand for seal and bearing systems compatible with next-generation low-GWP oils across North Sea installations.
- Floating platform deployment:Offshore wind developers in Portugal and Japan are procuring motion-compensated pitch control systems for pre-commercial floating arrays, opening new specification categories.
- Compound epicyclic architectures:These multi-stage designs achieve torque densities exceeding 300 kNm per tonne, enabling nacelle weight reductions that turbine OEMs specify for next-generation offshore units.
Market Restraints
- Specialized alloy steel supply:Case-hardened gear blanks require vacuum-degassed 18CrNiMo7-6 grades where European mill capacity concentrates among three producers, exposing procurement to lead time volatility.
- REACH substance restrictions:The framework's candidate list expansion for PFAS compounds threatens fluoropolymer seal inventories, forcing gearbox assemblers to qualify alternative elastomer compounds under accelerated timelines.
- Electromechanical substitution:Direct-drive permanent magnet generators eliminate main gearboxes entirely, constraining addressable market expansion in onshore segments below 3 MW.
Strategic Opportunities
- French floating wind pipeline:The country's 18 GW auction schedule through 2035 requires pitch systems rated for platform motion dynamics, a specification category where incumbent suppliers lack proven track records.
- Integrated bearing-gearbox assemblies:Converging planetary carriers with tapered roller bearing arrangements reduces part count and assembly labor, creating margin expansion for manufacturers with in-house bearing production.
- China MIIT efficiency mandates:Domestic content ratios for nacelle drivetrain components are tightening, favoring local gearbox producers with established relationships to state-owned wind farm developers.
Industry Challenges
- Floating platform certification:DNV and Bureau Veritas have not finalized unified standards for pitch system reliability under six-degree-of-freedom platform motion, delaying final investment decisions on pre-commercial projects.
- Electro-hydraulic skill convergence:Maintenance technicians must diagnose both variable-frequency drive faults and residual hydraulic accumulator systems during technology transition periods, stretching training program capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Yaw and Pitch Gearbox Market |
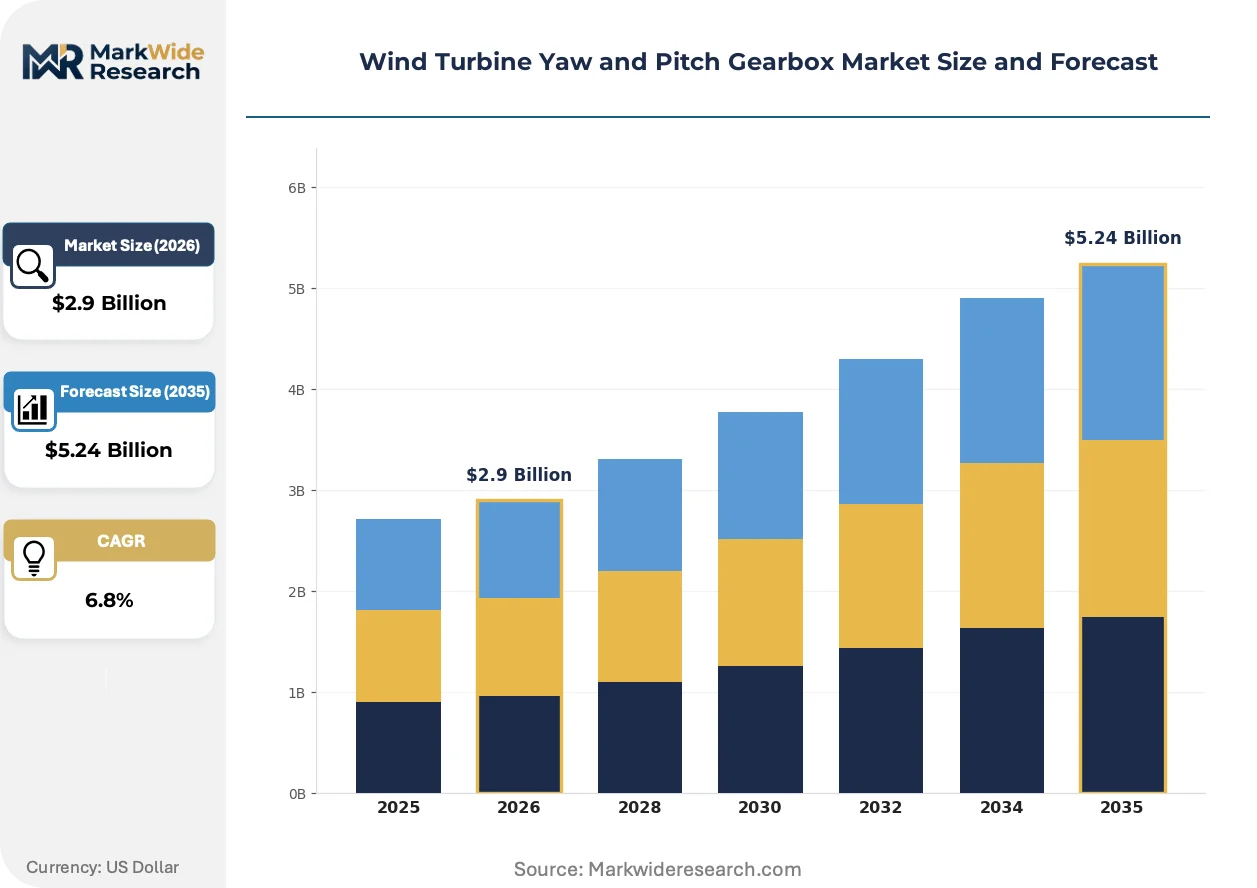
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gearbox, Motor, Actuator, Control System End User: Energy Producers, OEMs, Maintenance Providers, Operators Technology: Hydraulic, Electric, Mechanical, Hybrid Installation Type: Onshore, Offshore, Fixed, Adjustable |
| Companies Covered | Liebherr, Nanjing High Speed Gear Manufacturing, Bosch Rexroth AG, Nabtesco Corporation, Nidec Conversion, SIPCO–MLS, Schaeffler Group, ZOLLERN GmbH, NGC Transmission, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Yaw and Pitch Gearbox Market Trends and Innovations
Digital twin architectures are virtualizing gearbox condition monitoring, compressing maintenance intervals from calendar-based to predictive models while regulatory chemistry mandates force material system redesigns.
Model-based lubrication monitoring is virtualizing traditional oil analysis workflows. Offshore operators in the North Sea are deploying sensor-embedded drain ports that stream dielectric constant and particle count data to shore-based diagnostic centers. This capability is virtualizing scheduled sampling routines and enabling condition-based oil changes that extend drain intervals by 40% while satisfying EU F-Gas documentation requirements for sealed system integrity.
REACH Annex XIV authorization procedures are restricting chromium(VI) compounds in anti-corrosion surface treatments. Gearbox housings for offshore deployment now require plasma-electrolytic oxidation or zinc-nickel alloy alternatives that meet 3,000-hour salt spray specifications. European turbine OEMs are qualifying these finishes through accelerated life testing protocols, with supply contracts contingent on surface treatment vendor certification to the new specifications.
Service unbundling is fragmenting aftermarket relationships. Wind farm asset managers in Germany are separating gearbox overhaul procurement from original OEM service agreements, issuing competitive tenders to independent drivetrain specialists with floating crane vessel access. This pattern is most visible in the repowering segment, where 20-year-old onshore turbines undergo pitch system replacement ahead of full decommissioning.
Wind Turbine Yaw and Pitch Gearbox Market Segmentation
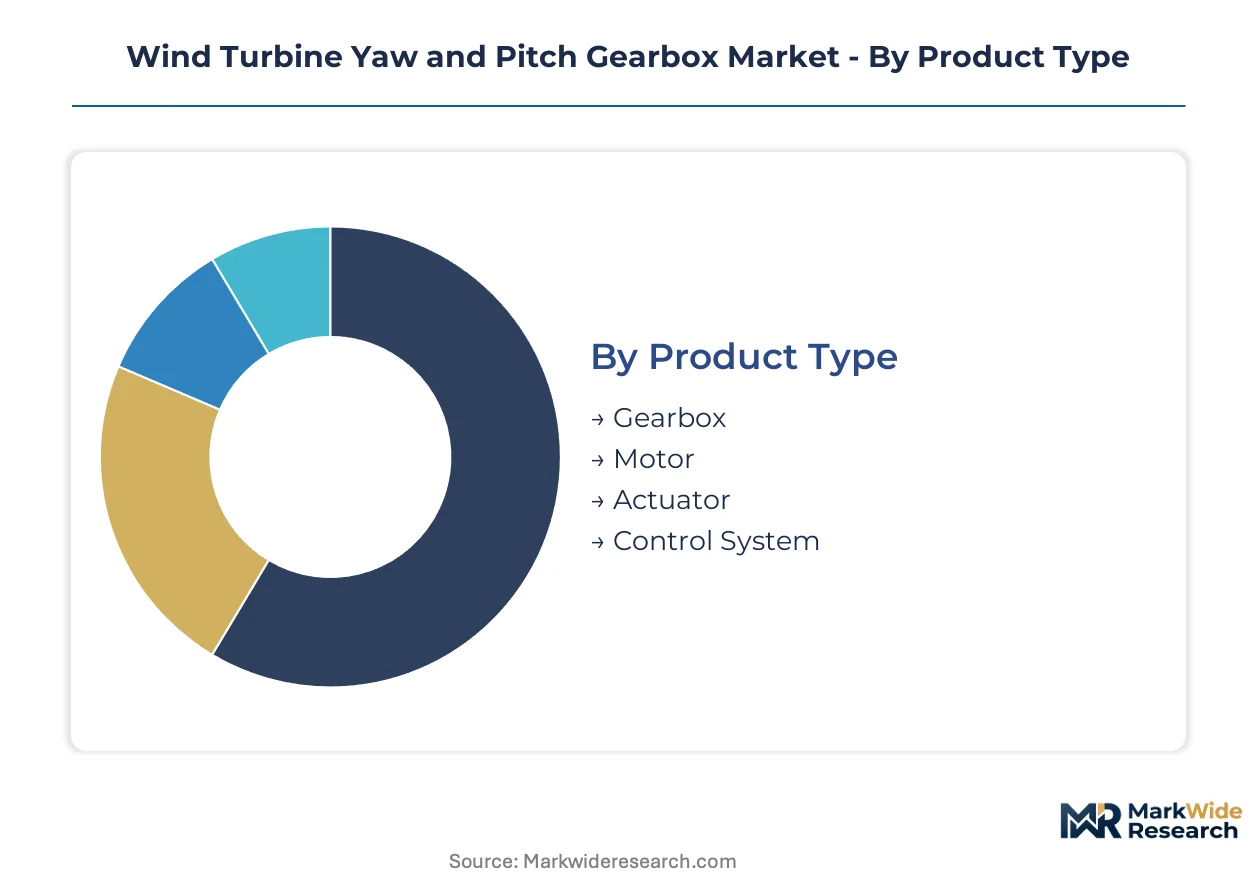
Wind turbine yaw and pitch gearboxes serve distinct operational roles across turbine architectures, installation environments, and maintenance regimes. Segmentation reveals how technology transitions and offshore expansion reshape procurement patterns and supplier qualification criteria.
Product Type:
Gearboxes anchor drivetrain mass and cost across the turbine nacelle, with component selection varying by torque rating, platform motion exposure, and replacement cycle economics.
- Gearbox:Planetary and compound epicyclic configurations handle input torques exceeding 2,000 kNm with case-hardened alloy steel gear sets. Demand concentrates in North Sea offshore installations where 15+ MW turbines require redundant sealing and corrosion-resistant housings.
- Control System:Variable-frequency drive architectures and sensor-embedded monitoring modules enable predictive maintenance models. Adoption accelerates in German repowering projects where operators unbundle service contracts from OEM agreements.
- Motor:Permanent magnet and induction motor variants for electromechanical pitch actuation.
- Actuator:Linear and rotary actuation mechanisms translating motor output to blade pitch adjustment.
Established volume favors Gearbox; emerging adoption favors Control System.
End User:
Procurement authority shifts between turbine builders, fleet operators, and independent service providers based on project phase and contract structure maturity.
- OEMs:Integrated nacelle manufacturers specify yaw and pitch systems during turbine platform development, locking in preferred supplier relationships through multi-year framework agreements. German and Chinese turbine builders maintain the tightest vendor qualification criteria.
- Operators:Wind farm asset managers increasingly direct aftermarket procurement for gearbox overhaul and pitch system replacement. German operators lead this unbundling trend, issuing competitive tenders to independent drivetrain specialists.
- Energy Producers:Utility and independent power producer direct procurement for greenfield projects.
- Maintenance Providers:Third-party service contractors performing scheduled maintenance and unscheduled repairs.
Contractual control favors OEMs for new capacity; operational control favors Operators for aftermarket spend.
Technology:
Actuation architectures differentiate by response precision, leakage risk tolerance, and platform motion compensation requirements.
- Electric:Variable-speed drives with permanent magnet motors displace hydraulic systems in pitch control, eliminating fluid leakage risks and improving blade angle precision. Portuguese and Japanese floating platform developers specify electric architectures for motion-compensated arrays.
- Hydraulic:Accumulator-based systems retain installed base in older onshore turbines and applications requiring extreme torque density.
- Mechanical:Direct mechanical linkages for yaw brake and locking functions.
- Hybrid:Combined electric-hydraulic architectures for specific load cases.
Technology transition favors Electric; residual installed base sustains Hydraulic.
Installation Type:
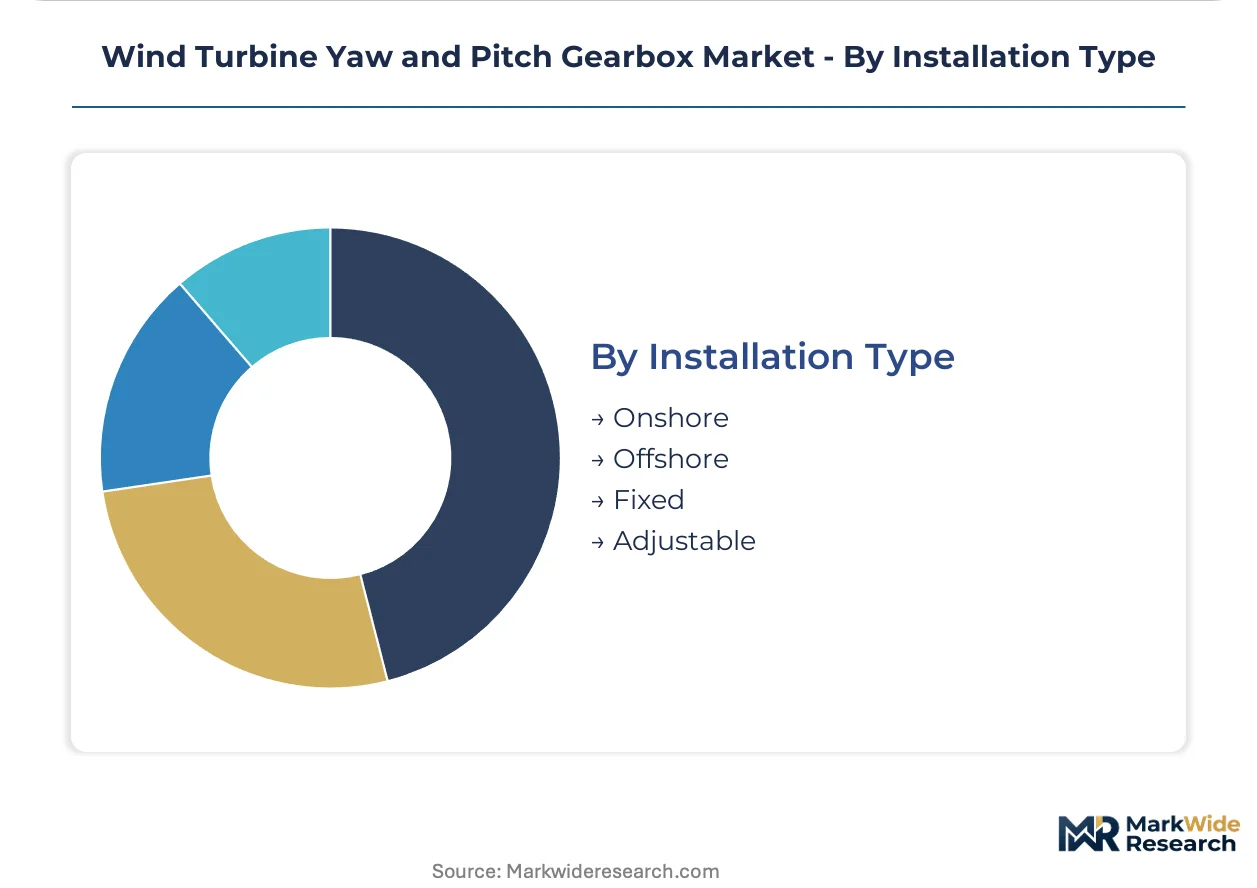
Environmental exposure and foundation mechanics dictate sealing specifications, corrosion protection, and redundancy requirements.
- Offshore:Fixed-bottom and floating platforms demand pitch systems with 3,000-hour salt spray housing finishes and redundant lubrication circuits. French auction pipelines through 2035 require motion-compensated designs lacking supplier track records.
- Onshore:Lower corrosion specifications and standard sealing configurations retain the largest installed base, though repowering cycles accelerate pitch system replacement ahead of full decommissioning.
- Fixed:Rigid foundation installations with standard nacelle orientation systems.
- Adjustable:Variable-tilt or self-erecting tower configurations.
Premium pricing favors Offshore; unit volume favors Onshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind farm operators in Germany command pricing premiums exceeding those in Chinese coastal provinces by margins reflecting corrosion-resistant specifications and redundant sealing systems mandated by EU F-Gas Regulation compliance.
Germany
North Sea offshore arrays drive demand for 15+ MW turbine yaw systems with 3,000-hour salt spray housing finishes. The EU F-Gas Regulation compels synthetic lubricant reformulation across Bremen and Hamburg industrial clusters, where Bosch Rexroth AG maintains integrated supply relationships for pitch system integration.
China
State-owned wind farm developers in Jiangsu and Guangdong provinces scale procurement of megawatt-class yaw gearboxes for domestic installations. MIIT efficiency mandates enforce domestic content ratios favoring local producers. Nanjing High Speed Gear Manufacturing anchors high-volume production in the Yangtze River Delta region.
United States
Offshore lease auctions along the Atlantic seaboard accelerate pitch system procurement for floating platform pre-commercial projects. FERC interconnection standards influence nacelle component specifications. Massachusetts and Rhode Island port infrastructure supports assembly of motion-compensated systems lacking supplier track records.
France
The 18 GW floating wind auction schedule through 2035 requires pitch systems rated for platform motion dynamics. REACH substance restrictions on PFAS compounds force accelerated qualification of alternative elastomer seal compounds. Port of Saint-Nazaire infrastructure concentrates pre-assembly activities for Atlantic coast deployments.
Japan
Floating platform developers in Goto City and Fukushima offshore zones procure electric pitch architectures for motion-compensated arrays. METI renewable energy targets drive turbine capacity expansion beyond 10 MW. Yokohama industrial corridors host testing facilities for next-generation gearbox designs.
Wind Turbine Yaw and Pitch Gearbox Market Competitive Landscape
Integrated drivetrain specialists and precision component fabricators split the market between nacelle-integrated supply contracts and aftermarket service relationships. Vendor qualification criteria tightened as turbine builders consolidated preferred supplier lists for 15+ MW offshore platforms. European hydraulics heritage and Chinese scale manufacturing represent the dominant strategic archetypes. Competitive moves center on backward integration into bearing and seal manufacturing, plus geographic expansion through port-proximate assembly facilities.
Among European integrated specialists, Bosch Rexroth AG and Schaeffler Group occupy positions reflecting distinct heritage advantages—hydraulics-driven pitch system integration versus bearing-gearbox assembly convergence. Nanjing High Speed Gear Manufacturing exemplifies the scale-driven archetype serving domestic content requirements. Liebherr and ZOLLERN GmbH represent precision fabrication capabilities anchored in German industrial clusters. Nabtesco Corporation and Nidec Conversion sit within the electromechanical transition tier supplying variable-speed drive architectures displacing hydraulic systems.
| Leading Market Players |
|---|
| Liebherr |
| Nanjing High Speed Gear Manufacturing |
| Bosch Rexroth AG |
| Nabtesco Corporation |
| Nidec Conversion |
| SIPCO–MLS |
| Schaeffler Group |
| ZOLLERN GmbH |
| NGC Transmission |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Bremerhaven container corridors carry vacuum-degassed 18CrNiMo7-6 gear blanks from European mills to North Sea nacelle assembly sites, where freight cost volatility compounds with mill capacity concentration to widen the spread between standard catalog pricing and configured-to-order offshore specifications.
Pricing Analysis
The customization-premium spread separates standard onshore yaw gearboxes from motion-compensated floating platform configurations. Pricing stratifies across corrosion-resistant offshore tiers, integrated bearing-gearbox assemblies, and standard onshore units. Price differentiation hinges on salt-spray certification grade and volume scale. Cost compression in standard onshore tiers is intensifying because electromechanical substitution eliminates main gearbox demand below 3 MW. Fleet operators exhibit highest price sensitivity in repowering aftermarket tenders, while floating platform developers accept premiums for unproven motion-compensated designs.
Supply Chain Analysis
Upstream feedstock for case-hardened gear blanks draws from German, Swedish, and Austrian vacuum-degassed steel mills. Critical inputs include 18CrNiMo7-6 alloy steel, synthetic PAO/ester lubricants, and fluoropolymer seal compounds. Single-source vulnerability concentrates in European mill capacity for specialized gear grades. Distribution runs through turbine OEM integrated supply agreements and independent aftermarket service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
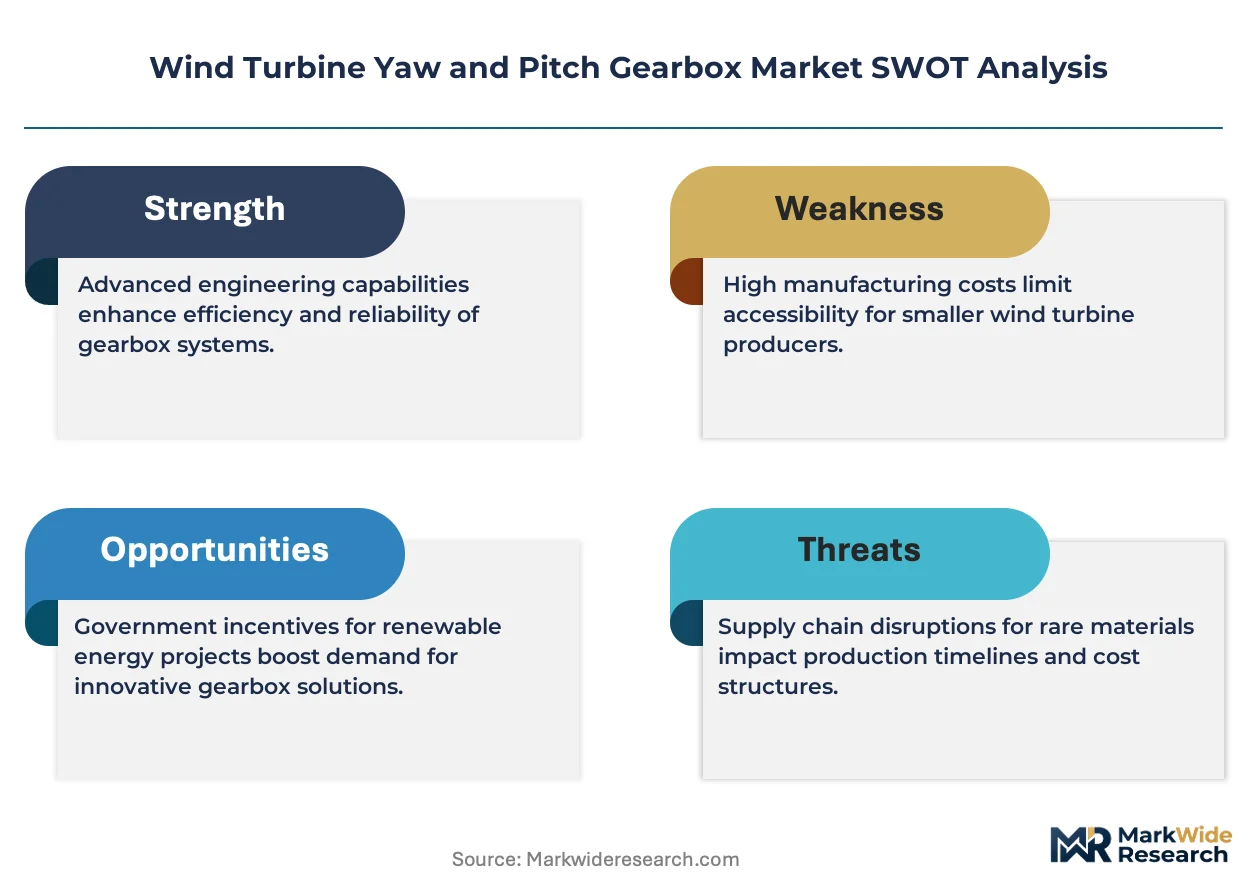
The Wind Turbine Yaw and Pitch Gearbox Market functions as a defensive-moat industry where regulatory entrenchment through EU F-Gas and REACH compliance creates high switching costs for turbine OEMs.
For Market Incumbents: Build certification moats around floating platform motion-compensated designs before DNV and Bureau Veritas finalize unified standards. Deepen backward integration into bearing manufacturing to protect margin pools against raw material volatility. Electromechanical substitution in sub-3 MW onshore segments threatens addressable market expansion. Channel control through port-proximate assembly facilities anchors nacelle integration contracts. For New Entrants and Emerging Players: Establish a beachhead in French floating wind auction pipelines where incumbent suppliers lack proven track records. Target motion-compensated pitch systems for pre-commercial arrays in Portugal and Japan. Independent drivetrain specialists with floating crane vessel access capture German repowering aftermarket spend unbundled from OEM agreements. Qualify alternative elastomer seal compounds under accelerated REACH timelines as a go-to-market wedge. For Investors and Strategic Acquirers: Precision fabrication specialists with plasma-electrolytic oxidation surface treatment capabilities represent acquisition targets with technology differentiation. Long-term viability rests on exposure to 15+ MW offshore turbine replacement cycles and floating platform deployment ramps. Watch DNV-Bureau Veritas certification standard finalization as the inflection signal triggering final investment decisions on pre-commercial projects.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Manufacturing | Schaeffler Group's integrated assemblies demonstrate margin expansion from captive tapered roller production. |
| Motion-Compensated Pitch System Development | French 18 GW auction schedule creates first-mover advantage for suppliers with platform dynamics expertise. |
| Alternative Elastomer Seal Qualification | REACH PFAS restrictions force accelerated validation of plasma-electrolytic oxidation-compatible compounds. |
| Port-Proximate Assembly Facility Expansion | Massachusetts and Rhode Island infrastructure supports floating platform pre-assembly for Atlantic lease areas. |
| Predictive Maintenance Platform Deployment | Sensor-embedded drain ports streaming dielectric data to shore-based centers extend oil drain intervals. |
Research Methodology
A standing panel of turbine OEM procurement directors, offshore wind farm asset managers, drivetrain maintenance technicians, and nacelle integration engineers provided ongoing calibration. Primary interviews combined with secondary validation from DNV certification databases, FERC interconnection filings, EU ECHA substance restriction updates, and MIIT efficiency mandate disclosures. Bottom-up unit economics and top-down market sizing triangulated across the analysis window.
Scenario-bracketing framed low, base, and high cases across technology transition pace and floating platform deployment timelines. Segmentation dimensions modeled include product type, installation environment, actuation architecture, and end-user procurement authority. CAGRs derived from installed base replacement cycles and capacity expansion pipelines. Industry-specific inputs incorporated turbine OEM framework agreement structures and port infrastructure buildout schedules.
Sensitivities concentrate around floating platform certification standard finalization and alloy steel mill capacity expansion timelines. Forecasts reflect assumptions on electromechanical substitution rates and REACH substance list evolution. Cross-checking against IEA offshore wind capacity announcements and turbine OEM order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
India Wind Energy Market