
 Mobile Energy Storage Systems Market | 2026-2036
Mobile Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Energy Storage Systems Market Foresight
China is narrowing its cost advantage in lithium-ion pack assembly as domestic cathode and cell capacity scales. LG Energy Solution leverages integrated cathode production to sustain margin stability across cylindrical and prismatic formats. Panasonic anchors its position through cylindrical cell specialization for high-discharge mobile platforms. CALB competes aggressively in LFP chemistry for commercial vehicle and stationary-mobile hybrid deployments.
Mobile energy storage systems are self-contained, transportable electrochemical or electrostatic units typically rated from 10 kWh to multiple MWh, designed for rapid deployment without permanent infrastructure. These systems employ battery management systems with thermal runaway protection, modular architectures for parallel operation, and containerized or trailer-mounted form factors to serve grid stabilization, disaster recovery, and remote power applications. Lithium-ion batteries dominate current deployments due to energy density and cycle life advantages, while flow batteries occupy niche roles in long-duration military and off-grid solutions where calendar longevity outweighs capital cost. Supercapacitors lead in pulse-power segments requiring sub-second response, though their limited energy density constrains broader mobile adoption.
The EPA enforces stationary source emissions thresholds that indirectly accelerate mobile storage as a compliance pathway for temporary power during facility upgrades. China's MIIT governs battery recycling traceability and GB standards for cell safety, shaping export eligibility for domestic manufacturers. The EU Green Deal and F-Gas Regulation constrain diesel generator alternatives, expanding addressable market for electrochemical mobile units. Stakeholders must monitor how carbon border adjustments and domestic content requirements reshape competitive access across the three largest demand centers.
Market Dynamics
Utility-scale renewable intermittency is forcing grid operators toward deployable electrochemical buffers that relocate across transmission nodes. This mobility imperative compresses procurement cycles and rewards modular architectures capable of rapid redeployment without permanent interconnection.
Growth Catalysts
- EPA Stationary Source Thresholds:Industrial facilities facing emissions caps during planned maintenance increasingly specify trailer-mounted battery systems as temporary compliance pathways.
- Remote Mining Electrification:Off-grid extraction operations in Western Australia and Chilean Atacama are eliminating diesel logistics through containerized lithium-ion deployments with solar hybridization.
- Grid-Edge Resilience Mandates:California's SB 100 directives and Texas PUCT emergency power rules accelerate municipal procurement of mobile units for critical infrastructure hardening.
Market Restraints
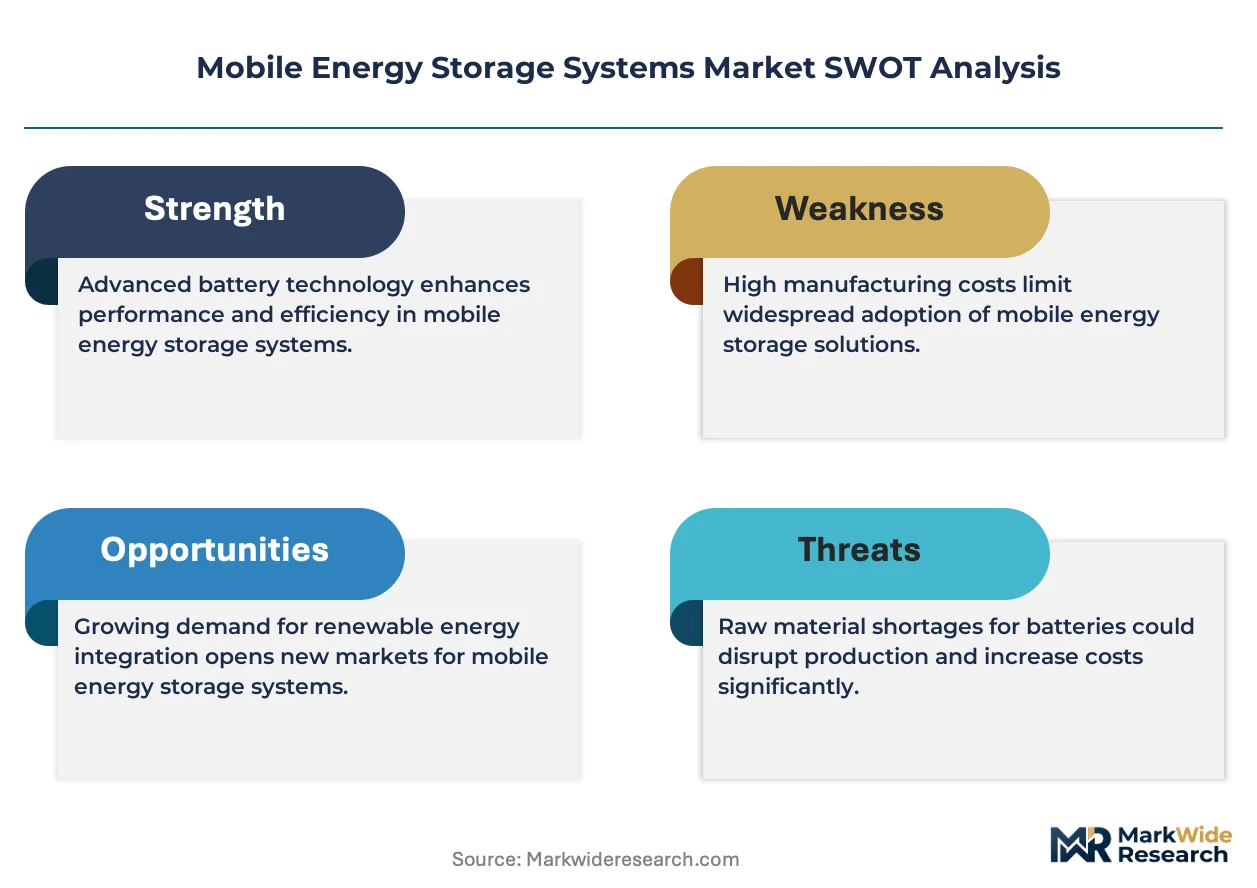
- Lithium Carbonate Volatility:Cathode material cost swings between 2022-2024 compressed pack margins and delayed utility procurement decisions.
- Single-Geography Cell Concentration:Over 70% of cylindrical cell capacity remains concentrated in East Asian manufacturing clusters, exposing buyers to logistics disruption.
- Flow Battery Capital Intensity:Vanadium redox systems require 2-3x upfront investment versus lithium-ion, limiting penetration beyond military and island microgrid niches.
Strategic Opportunities
- EU F-Gas Phase-Down:The regulation's diesel generator constraints open substation-scale mobile electrochemical deployment across German and Polish industrial corridors.
- EV Second-Life Integration:Repurposed automotive packs from early Nissan Leaf and Chevrolet Bolt fleets are entering commercial mobile storage at 40% cost reduction.
- Telecom Tower Hybridization:African and Southeast Asian tower operators are replacing diesel gensets with battery-solar mobile units to reduce fuel logistics.
Industry Challenges
- Thermal Runaway Containment Certification:UL 9540A test protocols extend validation timelines by 6-12 months for containerized multi-MWh systems.
- Interconnection Protocol Fragmentation:IEEE 1547 and local utility requirements vary across ISO territories, forcing redundant engineering for interstate mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Energy Storage Systems Market |
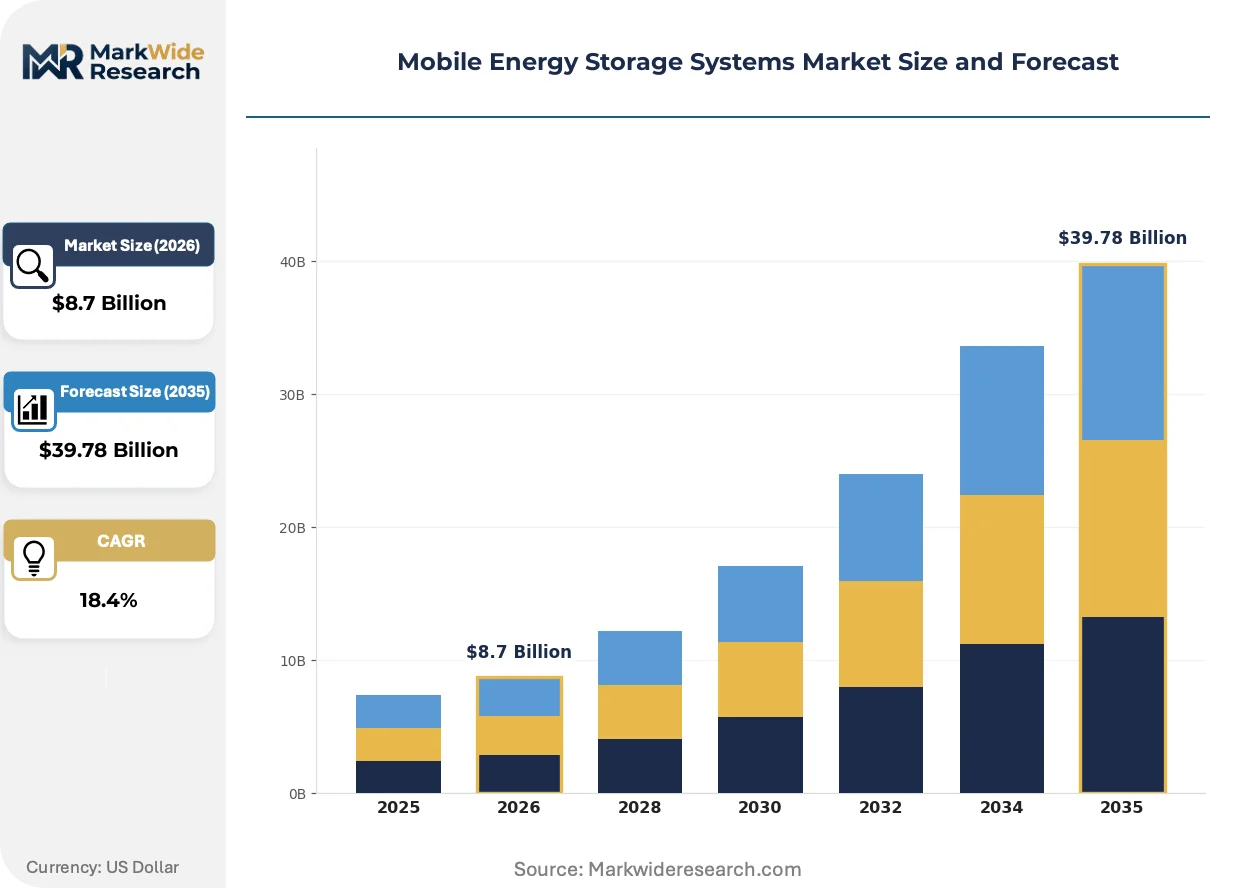
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion Batteries, Lead-Acid Batteries, Flow Batteries, Supercapacitors Application: Backup Power, Electric Vehicles, Renewable Energy Integration, Off-Grid Solutions End User: Residential, Commercial, Industrial, Military Distribution Channel: Online Retail, Direct Sales, Distributors, Aftermarket Providers |
| Companies Covered | LG Energy Solution, CALB, GE Renewable Energy, Panasonic, Amperex Technology Limited, Delta Electronics, Power Edison, Quanta Technology, Socomec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Energy Storage Systems Market Shifts & Advancements
Digital twin architectures and predictive degradation modeling are compressing operational risk premiums for mobile assets. These capabilities enable dynamic dispatch optimization and residual value forecasting that static installations cannot replicate.
Containerized solid-state battery prototypes are virtualizing the safety-performance tradeoff that has constrained lithium-ion deployment near population centers. Samsung SDI and Toyota pilot programs target 2026 commercialization for urban emergency response units. Early adopters include Japanese municipal fire departments and Singapore port authorities seeking reduced thermal management overhead.
The EU's CSRD disclosure requirements are mandating Scope 3 emissions tracking across temporary power procurement. Industrial buyers now require battery passport documentation tracing cell origin through recycling, favoring suppliers with certified closed-loop partnerships. German automotive manufacturers and Dutch data center operators have embedded these requirements into 2025 RFP templates.
Asset-light leasing structures are displacing capital purchase models for seasonal peak-shaving applications. Independent power producers and rental fleet operators capture margin through utilization-based pricing while transferring residual value risk. This shift concentrates most visibly in Texas ERCOT territory and Australian mining regions where demand duration varies significantly year-to-year.
Mobile Energy Storage Systems Market Segmentation
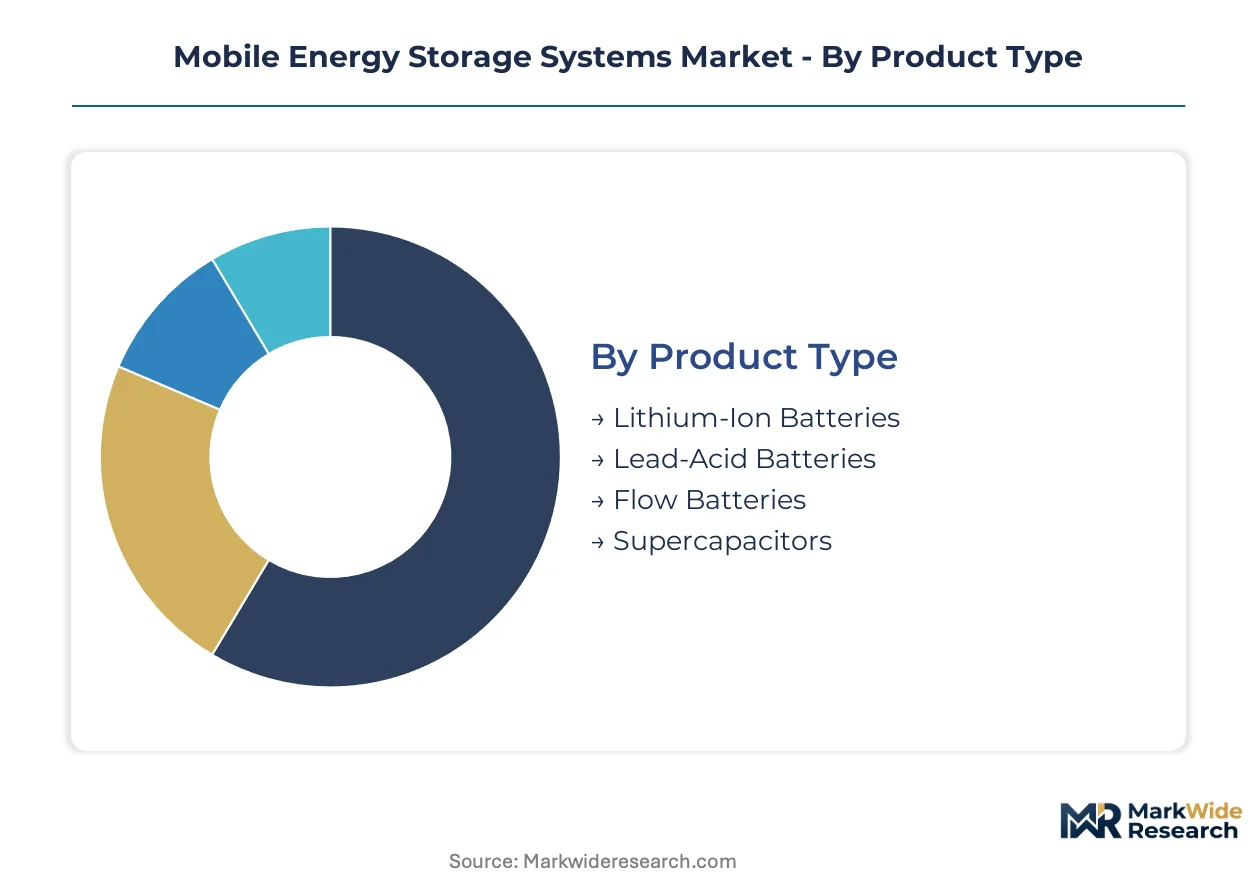
Segmentation reveals how technical specifications, deployment contexts, and procurement pathways fragment addressable demand. Chemistry choices, mobility requirements, and buyer sophistication create distinct competitive arenas with diverging margin profiles and certification burdens.
Product Type:
Mature lithium-ion formats dominate commercial deployments, while emerging chemistries target duration and safety niches that lithium-ion cannot serve profitably.
- Lithium-Ion Batteries:NMC and LFP cathode architectures deliver 150-250 Wh/kg energy density with 4,000-8,000 cycle lifespans. Demand concentrates in California utility microgrids and German industrial parks where rapid redeployment and high discharge rates justify premium pack costs.
- Lead-Acid Batteries:Flooded and AGM variants offer 30-50 Wh/kg density at 60-70% lower capital cost per kWh than lithium alternatives. Telecom backup in Nigeria and rural India sustains procurement volume despite weight penalties that restrict true mobility applications.
- Flow Batteries:Vanadium redox systems decouple power and energy scaling for 8-12 hour discharge durations. Military island installations and remote Australian mining camps absorb limited production where calendar longevity outweighs footprint constraints.
- Supercapacitors:Activated carbon double-layer cells achieve 100,000+ cycles with millisecond response times. Pulse-power roles in Singapore port crane regenerative braking and Japanese railway substations exploit cycle durability despite 5-10x lower energy density.
Lithium-ion retains volume leadership; flow batteries hold the steepest expansion curve as long-duration procurement criteria harden.
Application:
Application segmentation tracks how mobility value propositions vary across grid-connected versus isolation-dependent use cases.
- Backup Power:Trailer-mounted systems provide 15 minutes to 4 hours of critical load coverage during grid outages or maintenance windows. Texas hospital networks and Japanese semiconductor fabs specify these units for EPA compliance during diesel generator downtime.
- Electric Vehicles:Swappable battery packs and range-extender trailers serve commercial fleets with route flexibility requirements. Chinese electric bus operators and German logistics depots deploy mobile charging assets where fixed infrastructure lags vehicle deployment.
- Renewable Energy Integration:Containerized buffers smooth solar and wind intermittency at transmission nodes lacking permanent storage allocation. Chilean solar farms and Western Australian wind installations relocate units seasonally to match renewable generation patterns.
- Off-Grid Solutions:Self-contained solar-battery hybrids replace diesel logistics in extraction and humanitarian contexts. Canadian Arctic research stations and Congolese mining concessions eliminate fuel airlift costs through renewable-mobile storage pairing.
Backup power commands the largest installed base; renewable integration is gaining share fastest as grid operators procure mobility as a grid planning tool.
End User:
End user categories reflect diverging technical sophistication, contract scale, and safety certification requirements that reshape vendor go-to-market economics.
- Residential:5-20 kWh trailer or skid-mounted units serve home backup and recreational vehicle markets. Post-hurricane Florida and fire-prone California counties drive procurement through insurance mandates and self-sufficiency preferences.
- Commercial:Retail, hospitality, and healthcare facilities deploy 50-500 kWh systems for demand charge management and resilience. German automotive suppliers and Dutch cold-chain distributors embed battery passports to satisfy CSRD disclosure requirements.
- Industrial:Manufacturing and extraction operations specify 1-10 MWh containerized assets for peak shaving and process continuity. Western Australian iron ore mines and Chilean copper smelters achieve diesel displacement through solar-battery hybridization at remote sites.
- Military:Forward operating bases and naval vessels demand MIL-STD-810G certified systems with electromagnetic hardening. US Marine Corps expeditionary units and UK Royal Navy surface fleets prioritize silent signature and fuel logistics elimination over unit cost.
Industrial buyers generate the highest revenue per transaction; military procurement is climbing the fastest as defense ministries electrify tactical energy systems.
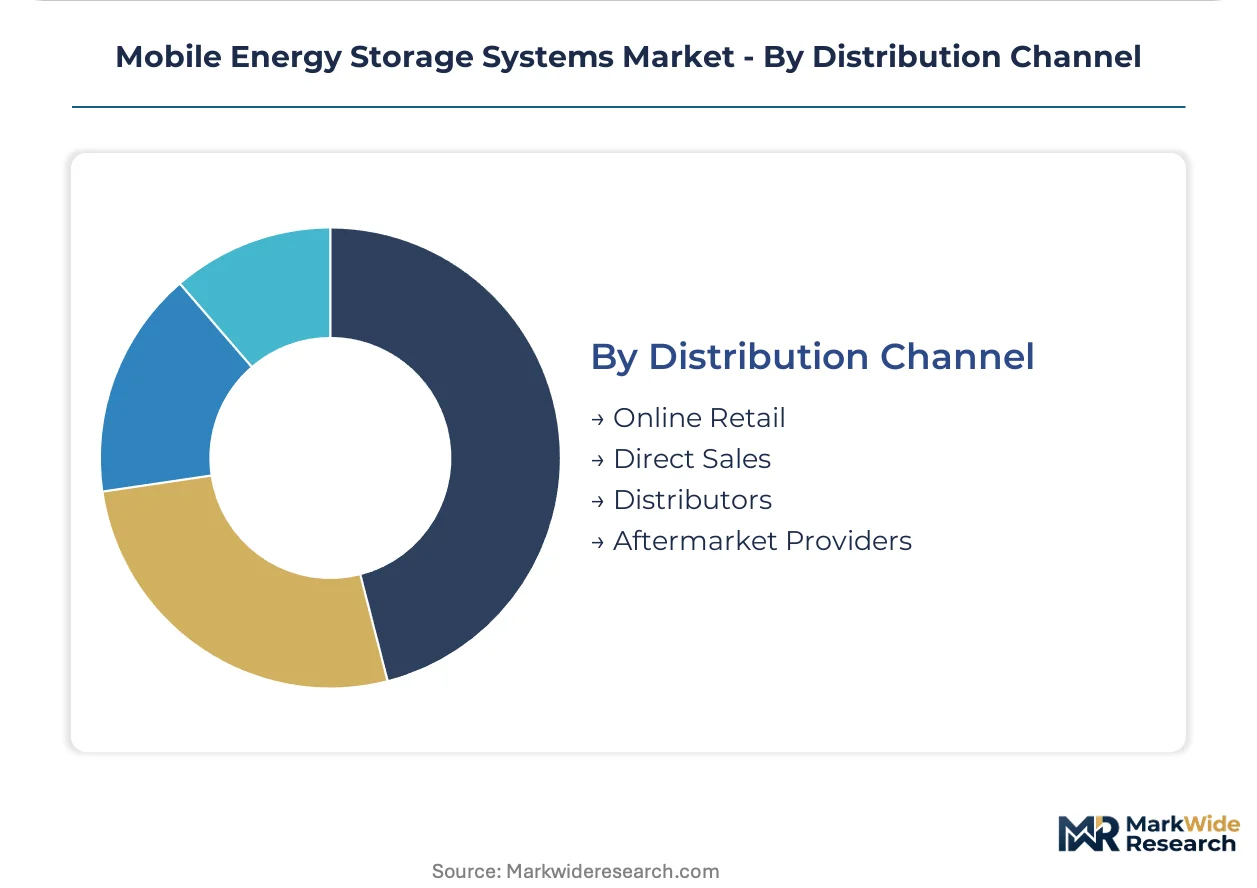
Distribution Channel:
Channel structure determines how technical validation burdens and working capital requirements allocate between manufacturers and intermediaries.
- Online Retail:E-commerce platforms serve sub-50 kWh residential and small commercial segments with standardized SKUs. Amazon Business and Alibaba consolidate demand for Chinese manufacturers seeking export volume without field engineering investment.
- Direct Sales:Manufacturer field teams engineer custom containerized solutions above 500 kWh. Tesla Energy and Fluence capture industrial and utility accounts through direct specification relationships that bundle installation and long-term service.
- Distributors:Regional electrical and industrial supply houses stock mid-range units for commercial contractors. Graybar and WESCO in the United States, Rexel in Germany, and local equivalents in India provide logistics and credit terms that manufacturers avoid.
- Aftermarket Providers:Leasing specialists and refurbished pack aggregators serve seasonal and project-based demand. Texas ERCOT territory and Australian mining regions concentrate asset-light rental models where utilization varies year-to-year.
Direct sales retains margin leadership; aftermarket providers are expanding most quickly as procurement shifts from capital purchase to operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT governs battery recycling traceability and GB standards for cell safety, shaping export eligibility for domestic manufacturers. The country's dual carbon goals accelerate domestic deployment of containerized mobile storage for grid stabilization and industrial peak shaving. Stakeholders must monitor how carbon border adjustments and domestic content requirements reshape competitive access across the three largest demand centers.
China
Utility-scale renewable intermittency drives procurement of trailer-mounted lithium-ion systems across transmission-constrained provinces. MIIT's battery passport requirements and GB/T standards for thermal runaway containment filter export-ready manufacturers from domestic-only players. Jiangsu and Guangdong manufacturing clusters scale cylindrical and prismatic cell capacity to serve both domestic grid operators and European industrial buyers.
United States
EPA stationary source thresholds compel industrial facilities to specify mobile battery systems during planned maintenance and diesel generator downtime. FERC Order 2222 and state-level mandates in California and Texas accelerate municipal procurement for critical infrastructure hardening. ERCOT territory concentrates asset-light leasing models where independent power producers capture margin through utilization-based pricing.
Germany
EU F-Gas Regulation phase-down constraints on diesel generators expand substation-scale mobile electrochemical deployment across industrial corridors. CSRD disclosure requirements mandate Scope 3 emissions tracking, embedding battery passport documentation into automotive and data center procurement. North Rhine-Westphalia and Bavaria anchor manufacturing and deployment clusters for containerized systems serving grid-edge resilience.
Australia
Remote mining electrification in Western Australia and Queensland eliminates diesel logistics through containerized lithium-ion deployments with solar hybridization. The country's national energy regulator oversees grid connection standards that vary across state territories, forcing redundant engineering for interstate mobility. Pilbara iron ore mines and Atacama-linked extraction operations sustain demand for long-duration mobile storage with seasonal relocation patterns.
Japan
METI procurement guidelines and JIS standards for stationary battery safety shape commercial deployment near population centers. Solid-state battery pilots by domestic manufacturers target municipal emergency response units seeking reduced thermal management overhead. Tokyo and Osaka metropolitan authorities specify mobile storage for disaster recovery and grid resilience in earthquake-prone zones.
Mobile Energy Storage Systems Market Competitive Landscape
Capability concentration sits with integrated cell manufacturers; scale advantage sits with system integrators and rental fleet operators. The vendor base stratifies across three tiers: cathode-to-pack integrated producers, modular system assemblers, and asset-light leasing specialists. Dominant competitive moves include backward integration into cell production and geographic expansion through certified service partnerships.
Among integrated cell-to-pack producers, LG Energy Solution and Panasonic occupy positions that exemplify chemistry specialization strategies, while CALB represents aggressive LFP positioning for commercial vehicle and stationary-mobile hybrid deployments. These manufacturers anchor tier-one supply relationships with industrial and utility buyers requiring traceable cell origin documentation. System integrators and aftermarket providers compete through utilization-based pricing models that transfer residual value risk from capital-constrained buyers.
| Leading Market Players |
|---|
| LG Energy Solution |
| CALB |
| GE Renewable Energy |
| Panasonic |
| Amperex Technology Limited |
| Delta Electronics |
| Power Edison |
| Quanta Technology |
| Socomec |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors impose 15-20% cost premiums on European-bound battery packs, compressing margins for non-integrated assemblers while amplifying price spreads between cathode-integrated producers and modular system integrators serving industrial buyers.
Pricing Analysis
East Asian export pricing runs 12-18% below European domestic assembly quotes for equivalent NMC chemistry packs. Three-tier pricing structure across premium UL-certified, standard CE-marked, and economy GB-tier configurations separates industrial utility buyers from commercial contractors and developing-market telecom operators. Cost compression in standard-tier lithium-ion systems is intensifying because Jiangsu and Guangdong cathode capacity expansion outpaces demand absorption. Commercial contractors exhibit highest price sensitivity, while military procurement tolerates 40-60% premiums for MIL-STD certification and electromagnetic hardening.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for cylindrical cell procurement. Manufacturing gravity centers on China, South Korea, and Japan, with over 70% of prismatic and cylindrical cell capacity concentrated in East Asian production clusters. Raw material flows draw from Chilean lithium brine, Indonesian nickel laterite, and Australian spodumene concentrate. Single-source vulnerability in cathode precursor refining constrains supply elasticity. Distribution runs through direct manufacturer-to-utility contracts above 500 kWh, regional electrical distributors for commercial mid-range units, and aftermarket leasing specialists for seasonal demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across utility, industrial, and military verticals creates defendable niche positions for specialists mastering certification-specific workflows rather than competing on undifferentiated pack economics.
For Market Incumbents: Entrench through backward integration into cathode production and captive cell capacity expansion in Jiangsu or South Korea to offset lithium carbonate volatility. Lock in multi-year offtake agreements with Western Australian mining operators before second-life EV pack competition intensifies. Prioritize UL 9540A pre-certification investments to compress validation timelines for containerized multi-MWh systems. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Indonesian and Vietnamese manufacturing parks lacking grid resilience infrastructure. African telecom tower hybridization offers second entry vector with lower certification burdens than European or North American procurement. Pursue asset-light leasing partnerships with regional EPC contractors rather than capital-intensive manufacturing scale-up. For Investors and Strategic Acquirers: Cell-to-pack integrators with certified closed-loop recycling partnerships and MIIT export eligibility constitute the highest-conviction acquisition archetype for long-term viability. Monitor F-Gas Regulation enforcement intensity across German industrial corridors as inflection indicator for mobile electrochemical substitution rates. Battery passport documentation capabilities separate investable suppliers from stranded asset risks under EU CSRD disclosure mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | LG Energy Solution and Panasonic sustain margin stability across cylindrical formats through captive cathode supply. |
| UL 9540A Pre-Certification Investment | Early validation compresses 6-12 month timeline extensions for containerized multi-MWh deployments. |
| Second-Life EV Pack Aggregation | Repurposed Nissan Leaf and Chevrolet Bolt batteries enter commercial mobile storage at 40% cost reduction. |
| Asset-Light Leasing Structure Deployment | Tesla Energy and Fluence capture Texas ERCOT margin through utilization-based pricing models. |
| Battery Passport Documentation Capability | German automotive manufacturers embed CSRD-compliant traceability into 2025 procurement templates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA technology roadmaps, FERC interconnection filings, and customs trade records. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided operational input on deployment economics and procurement criteria. Bottom-up unit economics modeling triangulates against top-down market sizing across chemistry, application, and end-user segments.
Forecast inputs span renewable integration targets, carbon neutrality mandate timelines, and lithium carbonate price trajectory assumptions across the analysis window. Segmentation dimensions include battery chemistry, mobility configuration, application context, and procurement channel structure. CAGRs derive from installed base evolution and replacement cycle analysis rather than extrapolated shipment data. Grid-edge resilience mandates and mining electrification commitments constitute industry-specific demand drivers.
Practitioners should monitor lithium carbonate volatility, tariff policy adjustments, and thermal runaway certification timeline extensions for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Battery Energy Storage Market
Energy Storage
South America Energy Storage Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Asia-Pacific Energy Storage Systems Market