
 North America Bunker Fuel Market | 2026-2036
North America Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bunker Fuel Market Analytics
IMO 2020 is recalibrating the cost-of-entry calculus for North American bunker fuel suppliers. ExxonMobil Corporation leverages its integrated Gulf Coast refining network to produce IMO-compliant very low sulfur fuel oil at scale. Chevron Corporation anchors its position through dedicated marine terminal infrastructure in Los Angeles and Vancouver. Shell PLC competes by extending its barge-based delivery footprint across the Pacific Northwest.
North America bunker fuel denotes residual and distillate petroleum products blended to meet marine engine combustion specifications, with sulfur content capped at 0.50% m/m for open-ocean vessels and 0.10% m/m in Emission Control Areas. Heavy fuel oil retains volume leadership among fuel types despite steady displacement by low sulfur fuel oil and marine gas oil in regulated zones. Ship-to-ship delivery dominates the delivery mode landscape for oceangoing cargo vessels, while port supply and truck modes capture fishing fleets and smaller coastal operators. Cargo vessels and tanker ships represent the deepest end user margin pools due to high throughput and long-term offtake contracts.
The U.S. EPA enforces marine diesel sulfur standards under the Clean Air Act, while the IMO MARPOL Annex VI framework governs cross-border vessel compliance across Canadian and U.S. waters. The U.S. Coast Guard and Transport Canada coordinate port state control inspections that directly determine market access for non-compliant fuel batches. Stakeholders must monitor the trajectory of California's Ocean-Going Vessel At-Berth Regulation and pending federal renewable marine fuel mandates to anticipate specification shifts and infrastructure investment timing.
Market Dynamics
The IMO 2020 sulfur cap is forcing a wholesale reconfiguration of North American marine fuel supply chains, compressing heavy fuel oil volumes while accelerating low-sulfur blending infrastructure investments across Gulf Coast and Pacific Northwest refining corridors.
Growth Catalysts
- IMO MARPOL Annex VI enforcement:The 0.50% m/m global sulfur limit and 0.10% m/m Emission Control Area standards are mandating compliant fuel procurement across U.S. and Canadian waters, locking in structural demand for very low sulfur fuel oil and marine gas oil.
- Container shipping fleet renewal:Newbuild vessels with dual-fuel engine architectures are requiring diversified bunker portfolios that blend conventional distillates with emerging biofuel and methanol pathways.
- Houston Ship Channel refining concentration:Integrated refiners with coker and hydrotreater assets are capturing margin expansion through captive production of IMO-compliant marine fuels for export and domestic bunkering.
Market Restraints
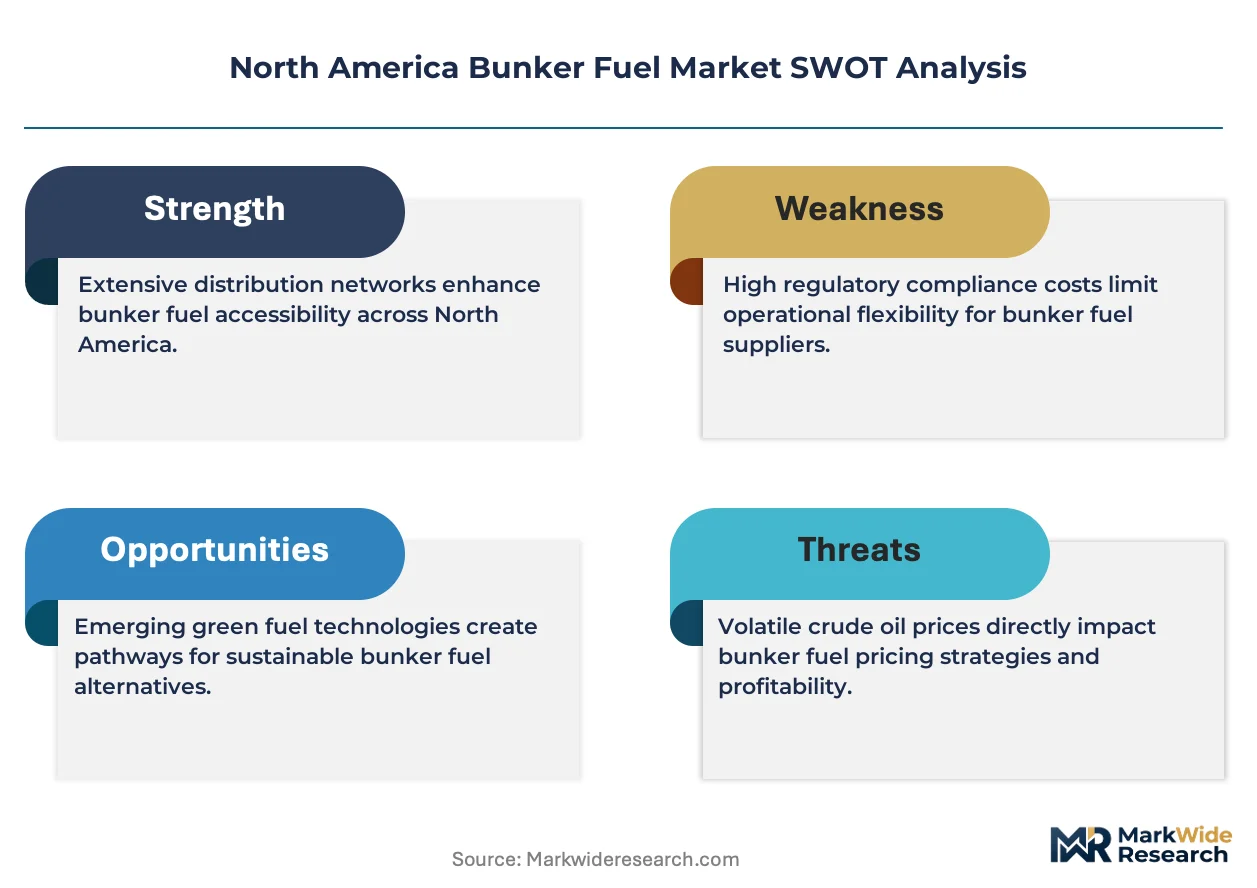
- Crude oil price volatility:Feedstock cost swings for vacuum gasoil and straight-run resid directly compress blending margins for low-sulfur fuel oil producers without long-term crude supply contracts.
- California Air Resources Board rulemaking uncertainty:Pending amendments to the Ocean-Going Vessel At-Berth Regulation are freezing terminal infrastructure investment timelines at Los Angeles and Long Beach ports.
- Liquefied natural gas substitution:LNG bunkering infrastructure at Jacksonville, Savannah, and Vancouver is capturing newbuild tanker and cruise vessel demand that would otherwise flow to liquid petroleum fuels.
Strategic Opportunities
- Mexican Pacific port development:Lázaro Cárdenas and Manzanillo container throughput expansion is creating greenfield demand for IMO-compliant bunkering services without legacy heavy fuel oil infrastructure constraints.
- California renewable marine fuel mandates:Proposed in-state production incentives for renewable diesel and bio-marine gas oil would establish first-mover premiums for compliant blenders ahead of federal action.
- Digital bunkering platforms:Real-time sulfur verification and mass-flow metering data integration is enabling spot-market transparency that rewards quality-certified suppliers with contract premiums.
Industry Challenges
- Marine fuel chemist talent scarcity:Specialized expertise in residual fuel stability, compatibility testing, and additive formulation is concentrating at legacy refiners, constraining independent blender technical capabilities.
- Barge fleet reconfiguration capex:Segregated tankage for multiple fuel grades and vapor recovery systems is requiring eight-figure terminal investments at Port of New York and New Jersey and Port of Seattle facilities.
- ISO 8217 certification timeline compression:Accelerated testing protocols for new biofuel blends and synthetic marine fuels are straining third-party laboratory capacity and extending batch release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bunker Fuel Market |
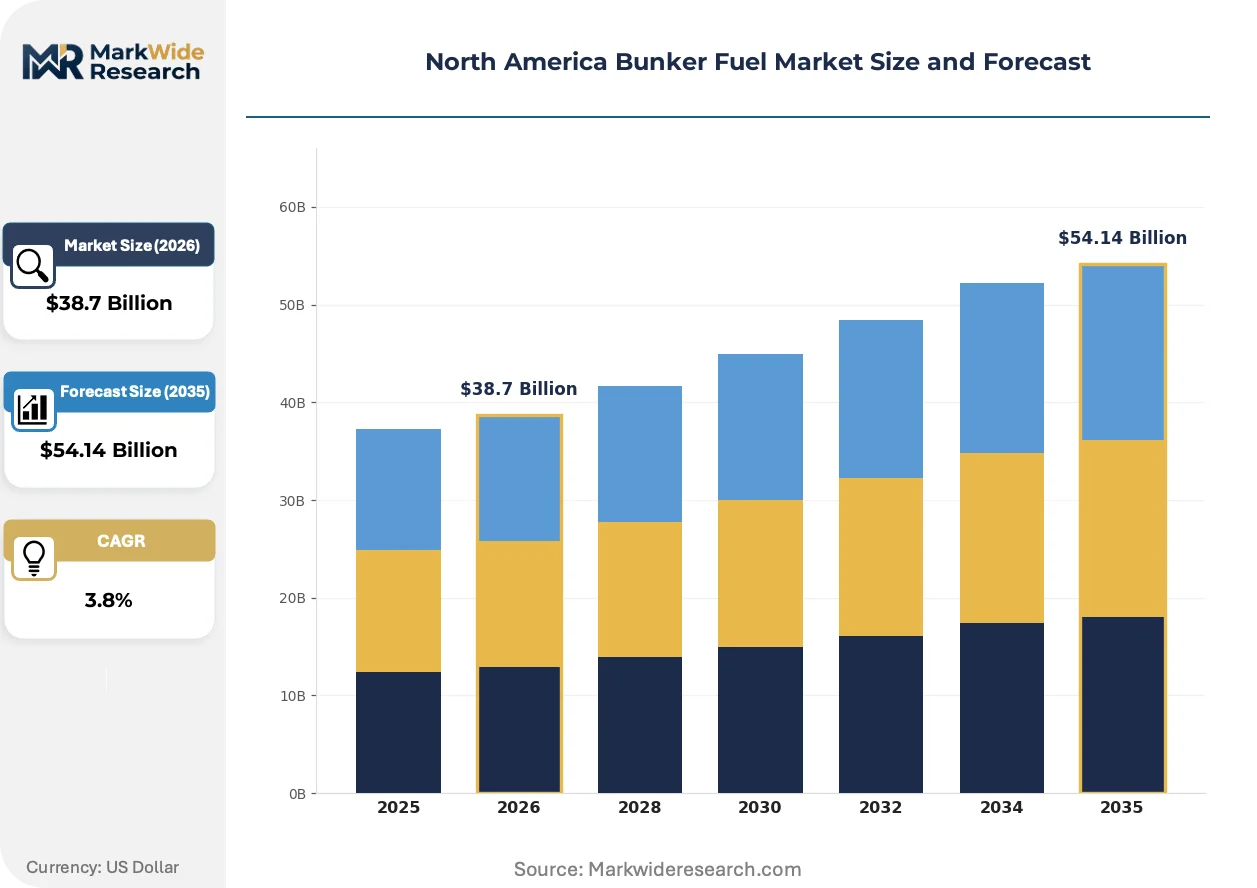
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Heavy Fuel Oil, Marine Gas Oil, Low Sulfur Fuel Oil, Biofuel Application: Shipping, Offshore, Fishing, Power Generation Delivery Mode: Ship-to-Ship, Port Supply, Barge, Truck End User: Cargo Vessels, Tanker Ships, Fishing Fleets, Cruise Liners |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell PLC, BP PLC, TotalEnergies SE, World Kinect Corporation, Valero Energy Corporation, Marathon Petroleum Corporation, Irving Oil Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bunker Fuel Market Evolving Landscape
Digitalization and fuel quality verification technologies are restructuring how marine buyers evaluate supplier performance, shifting procurement criteria from price-per-ton to sulfur compliance certainty and delivery reliability metrics.
Mass-flow metering with real-time sulfur content analysis is rewriting bunker transaction standards across North American ports. Container lines and bulk operators are mandating metered deliveries with automated sampling to eliminate quantity and quality disputes. This technology is compressing the market share of suppliers unable to provide ISO-corrected delivery documentation.
The U.S. EPA's pending marine diesel sulfur enforcement harmonization with IMO standards is tightening product specification windows for residual fuel oil sold in U.S. waters. Refiners without deep desulfurization capability are exiting the marine bunker pool entirely. The Gulf Coast complex is responding by redirecting high-sulfur resid to asphalt and coker feedstock markets.
Long-term offtake contracting is displacing spot-market purchasing for major container shipping alliances. Procurement departments at Mediterranean Shipping Company and CMA CGM vessels calling Oakland and Prince Rupert are negotiating twelve-month supply agreements with fixed sulfur premiums. This behavioral shift is most visible along the transpacific trade lane where schedule reliability outweighs marginal price savings.
North America Bunker Fuel Market Segmentation
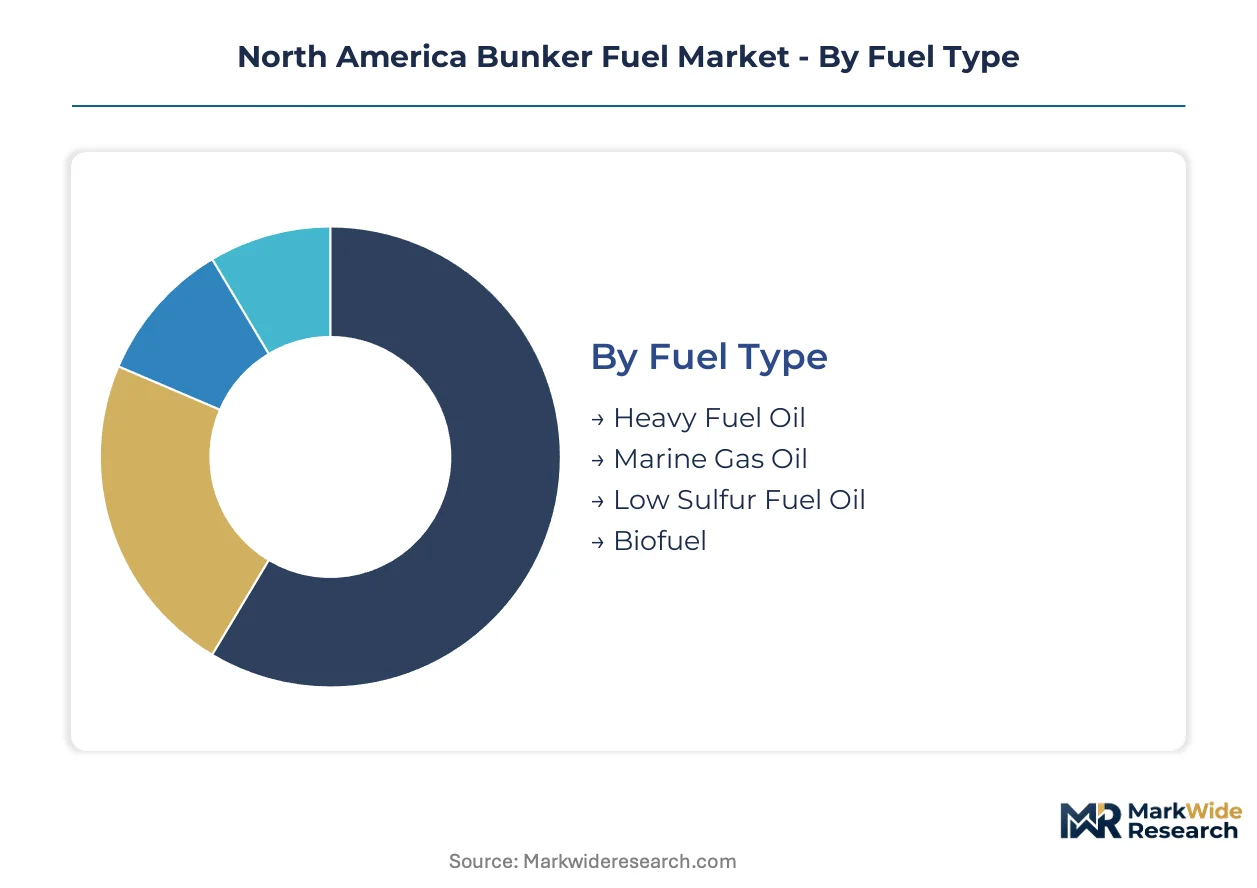
Marine fuel procurement in North America fragments across fuel chemistry, delivery logistics, and vessel class requirements. Each segmentation axis carries distinct margin structures and regulatory exposure that determine supplier profitability and investment priority.
Fuel Type:
Refining capacity concentration along the Gulf Coast and California corridor shapes which fuel grades achieve scale economics.
- Heavy Fuel Oil:Residual petroleum fraction with sulfur content historically above 3.5% m/m, now blended down or displaced in regulated zones. Demand concentrates in Mexican Pacific ports and certain Canadian coastal routes where IMO enforcement remains less stringent than U.S. waters.
- Low Sulfur Fuel Oil:Blended resid-distillate mixture meeting the 0.50% m/m global sulfur cap through vacuum gasoil cutting and hydrotreated component integration. California ports and the Houston Ship Channel refining complex anchor procurement volumes for transpacific container services.
- Marine Gas Oil:Distillate marine diesel with sub-0.10% m/m sulfur specification for Emission Control Area operations. The Pacific Northwest cruise terminal cluster and Alaska fishing fleet bases drive seasonal demand spikes.
- Biofuel:Fatty acid methyl ester and hydrotreated vegetable oil blends entering trial phases for California renewable marine fuel compliance pathways. Limited commercial volumes currently constrain widespread adoption.
Today's leader: Low Sulfur Fuel Oil. Tomorrow's challenger: Biofuel.
Application:
End-use economics vary dramatically between continuous commercial operations and intermittent seasonal demand patterns.
- Shipping:Deep-sea container, bulk, and tanker operations consuming the majority of North American bunker volumes. Long-term charter party fuel clauses and alliance procurement contracts stabilize demand at Los Angeles, Long Beach, and Prince Rupert.
- Offshore:Oil platform supply vessels and drilling rig support operations concentrated in the Gulf of Mexico. Hurricane seasonality and offshore permitting cycles create demand volatility.
- Fishing:Alaskan pollock and Pacific groundfish fleets operating under seasonal quota systems. Smaller volume per vessel but premium pricing for cold-weather operability specifications.
- Power Generation:Island and remote coastal installations in Alaska and Canada's northern territories using marine-grade residual fuel. Declining segment as grid interconnection and renewable alternatives advance.
Shipping commands absolute volume. Offshore presents the steepest expansion trajectory if Gulf of Mexico drilling activity accelerates.
Delivery Mode:
Physical infrastructure constraints at each port determine which delivery methods achieve operational scale.
- Ship-to-Ship:Direct transfer between bunker barge and oceangoing vessel outside port limits. The Houston Ship Channel and Southern California anchorage zones concentrate this high-throughput mode for container alliances.
- Port Supply:Quayside delivery through dedicated marine terminals. Vancouver and Oakland facilities are upgrading segregated tankage to handle multiple fuel grades simultaneously.
- Barge:Coastal and riverine distribution to ports lacking deepwater terminal infrastructure. The Mississippi River system and Pacific Northwest intracoastal routes depend on this flexible mode.
- Truck:Road tanker delivery for fishing fleets and small coastal operators at remote Alaskan and Atlantic Canadian ports. Highest per-unit logistics cost but essential for market coverage.
Ship-to-Ship dominates oceangoing throughput. Barge infrastructure is gaining share fastest in secondary port development.
End User:
Vessel size and operating pattern create tiered service requirements that segment supplier capabilities.
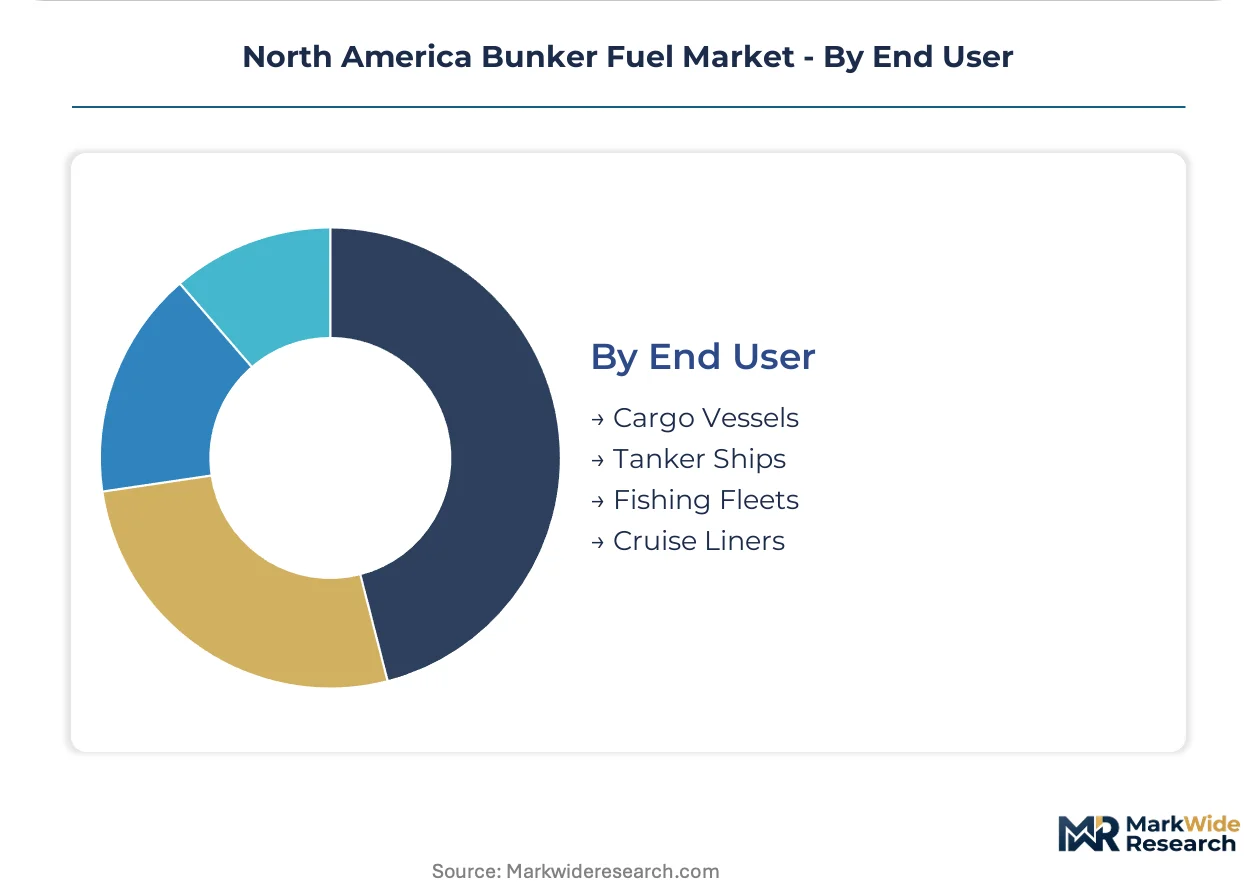
- Cargo Vessels:Container ships, bulk carriers, and general cargo operators with scheduled port calls and high-throughput fueling requirements. Mediterranean Shipping Company and CMA CGM alliance procurement drives contract structure standardization.
- Tanker Ships:Crude and product tankers with volatile routing patterns and spot-market fuel purchasing. Houston and Corpus Christi refining proximity supports this price-sensitive segment.
- Fishing Fleets:Owner-operator vessels with seasonal concentration in Alaska and New England. Smaller batch sizes and weather-dependent delivery windows challenge supplier economics.
- Cruise Liners:Passenger vessels with strict sulfur compliance requirements and premium service expectations. Vancouver, Seattle, and Miami homeport operations anchor demand.
Cargo Vessels anchor contract value. Cruise Liners are climbing the fastest on post-pandemic fleet expansion and itinerary diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American bunker fuel industry traces its modern configuration to post-World War II refinery expansion along the Gulf Coast, where integrated petroleum complexes first developed the residual fuel blending capabilities that now supply oceangoing vessels across two coasts and three national jurisdictions.
United States
The Houston Ship Channel refining corridor processes the majority of U.S. marine fuel output, with coker and hydrotreater assets producing IMO-compliant very low sulfur fuel oil at scale. EPA marine diesel sulfur standards under the Clean Air Act enforce stricter specifications than the IMO MARPOL Annex VI baseline in certain coastal zones. California's Los Angeles and Long Beach ports concentrate container shipping demand, where the Ocean-Going Vessel At-Berth Regulation drives 0.10% m/m sulfur compliance for vessels at berth.
Canada
Transport Canada coordinates port state control inspections with the U.S. Coast Guard across shared waterways, ensuring MARPOL Annex VI enforcement consistency in the Great Lakes and Pacific Northwest. Vancouver anchors West Coast bunkering volumes through cruise terminal operations and transpacific container services calling Prince Rupert. The British Columbia refining corridor supplies marine gas oil for Alaska-bound fishing fleets and seasonal cruise operations.
Mexico
Lázaro Cárdenas and Manzanillo container throughput expansion is creating greenfield demand for IMO-compliant bunkering without legacy heavy fuel oil infrastructure constraints. Mexican energy regulator CRE oversees fuel quality standards that increasingly align with IMO 2020 specifications. Pacific port development is attracting integrated suppliers seeking to bypass the congested Los Angeles-Long Beach anchorage zones.
Pacific Northwest
Seattle and Tacoma marine terminals are upgrading segregated tankage to handle multiple low-sulfur fuel grades simultaneously for Alaska cruise and fishing fleet operations. The region's hydropower-intensive grid supports electrification pilots that may eventually displace residual fuel demand for at-berth vessels. Barge-based distribution networks extend compliant fuel access to remote Alaskan ports lacking deepwater terminal infrastructure.
Gulf of Mexico
Corpus Christi and Houston refining proximity supports price-sensitive tanker spot-market purchasing, with offshore oil platform supply vessels creating hurricane-season demand volatility. The U.S. Coast Guard enforces fuel transfer documentation standards that exceed IMO baseline requirements. Jacksonville and Savannah LNG bunkering infrastructure is capturing newbuild tanker demand that would otherwise flow to liquid petroleum fuels.
North America Bunker Fuel Market Competitive Landscape
The competitive structure tilts toward integrated petroleum majors with captive refining and terminal assets. Market concentration is pronounced at the top tier, where Gulf Coast refining scale and Pacific Coast marine terminal ownership create durable barriers to independent blender entry. Three archetypes dominate: integrated majors with full supply chain control, midstream-focused terminal operators with barge fleets, and specialized marine fuel traders leveraging third-party storage. Capacity expansion and strategic terminal partnerships represent the primary competitive vectors, with players securing anchorage access and metered delivery certification to lock in container line offtake contracts.
Among integrated petroleum majors, ExxonMobil Corporation exemplifies the refining-scale archetype through its Gulf Coast network position, while Chevron Corporation and Shell PLC occupy positions defined by marine terminal infrastructure concentration in Los Angeles and Vancouver respectively. These entities represent the tier where captive production of very low sulfur fuel oil meets long-term procurement contracts from Mediterranean Shipping Company and CMA CGM alliance vessels. Independent terminal operators and fuel traders sit within a secondary tier, competing on spot-market flexibility and digital bunkering platform integration rather than refining integration depth.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell PLC |
| BP PLC |
| TotalEnergies SE |
| World Kinect Corporation |
| Valero Energy Corporation |
| Marathon Petroleum Corporation |
| Irving Oil Ltd |
| Others |
Value Network & Pricing Analysis
Integrated petroleum majors with captive Gulf Coast refining networks and dedicated marine terminal ownership patterns command pricing discipline through backward integration into vacuum gasoil and hydrotreated component production. Their control over both feedstock procurement and finished fuel delivery to California ports and the Houston Ship Channel insulates margin structures from spot-market volatility that compresses independent blender economics.
Pricing Analysis
Long-term offtake contracting with fixed sulfur premiums anchors the dominant pricing structure for transpacific container services, separating Mediterranean Shipping Company and CMA CGM alliance volumes from spot-market tanker purchasing. Price differentiation rests on ISO 8217 certification grade and metered delivery capability, with quality-verified suppliers capturing contract premiums. Cost compression in the independent blender tier is intensifying because crude oil price volatility without long-term supply agreements erodes blending margins. Tanker operators at Houston and Corpus Christi exhibit the highest price sensitivity, while cruise liners at Vancouver and Seattle prioritize compliance certainty over marginal savings.
Supply Chain Analysis
Specialized marine fuel chemist scarcity in the United States and Canada constrains technical capabilities at independent blenders, forcing reliance on legacy refiners for residual fuel stability expertise. Raw material flows draw from vacuum gasoil, straight-run resid, and hydrotreated distillate streams concentrated along the Gulf Coast refining corridor. Single-source vulnerability in barge fleet reconfiguration creates structural risk, as segregated tankage investments at Port of New York and New Jersey and Port of Seattle require eight-figure commitments. Distribution runs through ship-to-ship transfer at anchorage zones, port supply at marine terminals, and barge networks extending to remote Alaskan ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American bunker fuel rests on the shift from spot-market purchasing to long-term offtake contracting with embedded sulfur compliance premiums, compressing price-sensitive independents while rewarding integrated majors with quality verification infrastructure.
For Market Incumbents: Anchor contract renewal rates at Los Angeles and Long Beach by accelerating metered delivery certification ahead of California Air Resources Board rulemaking finalization. Deepen backward integration into hydrotreater capacity additions along the Houston Ship Channel to capture margin expansion from captive very low sulfur fuel oil production. LNG bunkering infrastructure at Jacksonville and Savannah represents the priority substitution threat requiring monitoring. For New Entrants and Emerging Players: Capture greenfield demand at Lázaro Cárdenas and Manzanillo without legacy heavy fuel oil infrastructure constraints, where Mexican Pacific port development creates first-mover positioning for IMO-compliant bunkering services. Digital bunkering platforms with real-time sulfur verification offer the most penetrable go-to-market angle, enabling spot-market transparency that rewards quality-certified suppliers with contract premiums against established terminal operators. For Investors and Strategic Acquirers: Integrated petroleum majors with Gulf Coast refining scale and Pacific Coast marine terminal ownership are the most active acquirer in this space, seeking terminal partnerships and anchorage access to lock in container line offtake. The five-to-ten year viability window favors targets with metered delivery certification and segregated tankage for multiple fuel grades. Watch California renewable marine fuel mandate trajectory as the inflection signal for bio-marine gas oil infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrotreater Capacity | Gulf Coast refiners capture margin expansion through captive very low sulfur fuel oil production at scale. |
| Metered Delivery Certification Investment | Mass-flow metering with automated sampling eliminates quantity disputes for Mediterranean Shipping Company alliance vessels. |
| Digital Bunkering Platform Development | Real-time sulfur verification enables spot-market transparency rewarding ISO-corrected documentation providers. |
| Segregated Tankage Expansion | Port of Seattle and Vancouver facilities upgrade simultaneous handling of multiple low-sulfur fuel grades. |
| Mexican Pacific Terminal Partnership | Lázaro Cárdenas greenfield positioning bypasses congested Los Angeles-Long Beach anchorage zones. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combining interviews with marine fuel procurement managers at container shipping alliances, refinery operations directors along the Gulf Coast, terminal infrastructure planners at Los Angeles and Long Beach, and regulatory affairs specialists at the EPA and California Air Resources Board. Secondary validation draws from U.S. Coast Guard fuel transfer documentation standards, Transport Canada port state control inspection records, IMO MARPOL Annex VI enforcement guidelines, and SEC filings from integrated petroleum majors. Bottom-up vessel fuel consumption estimates triangulate against top-down refinery marine fuel output data.
Rate-of-change decomposition across the analysis window segments the market by fuel chemistry, delivery logistics, and vessel class requirements, with fuel type and end user dimensions carrying distinct margin structures and regulatory exposure. CAGRs derive from historical volume trajectories adjusted for IMO 2020 compliance-driven specification shifts and container shipping fleet renewal patterns. Forecast inputs include crude slate quality assumptions for Gulf Coast refining complexes and California renewable marine fuel mandate implementation probability.
Crude oil price volatility, California Air Resources Board rulemaking uncertainty, and LNG bunkering infrastructure buildout pace are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about enforcement consistency across U.S. and Canadian waters and Mexican regulatory alignment with IMO specifications. Material deviation in feedstock cost swings, pending emission control amendments, or alternative fuel substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Tire Derived Fuel Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
China Coal Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Germany Bunker Fuel Market
Fuels
Europe Firewood Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
China Bunker Fuel Market
Fuels
Multifuel Gas Turbine Market
Fuels
Heavy Fuel Oil Market
Fuels
Storage Tank Market
Fuels
Fuel Analyzer Market
Fuels
Global Methane Hydrate Market