
 Offshore Wind Power Market | 2026-2036
Offshore Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Wind Power Market Intelligence
A demand rotation from national grid operators to specialized renewable energy developers is unwinding the market's traditional procurement model. This shift favors entities with agile project financing and development capabilities. Ørsted leverages its extensive project development experience to secure prime seabed leases. Equinor specializes in applying its offshore oil and gas expertise to complex floating wind projects, while Siemens Gamesa dominates the turbine manufacturing segment with its large-rotor technology.
Offshore wind power involves converting kinetic energy from wind into electricity using turbines installed in marine environments. These systems, often featuring turbines with capacities exceeding 15 MW, are engineered to withstand harsh oceanic conditions. Fixed-bottom technology in shallow water remains the dominant installation method, but floating platforms are essential for accessing deep water resources. While utility-scale generation is the primary application, green hydrogen production presents a significant new demand channel.
Regulatory frameworks are critical to project viability, with the US Inflation Reduction Act (IRA) providing substantial tax credits for domestic content. In parallel, the EU Green Deal and China's dual carbon goals create long-term policy certainty and auction pipelines. These policies directly influence investment decisions and component sourcing strategies. Stakeholder success now depends on securing supply chain capacity and navigating increasingly complex local content requirements.
Market Dynamics
The central tension shaping the market is the collision between immense capital expenditure requirements for utility-scale projects and the growing pressure from policy mandates, such as the US Inflation Reduction Act, for localized supply chains and domestic content.
Growth Catalysts
- Policy Frameworks:The EU Green Deal provides a clear, long-term auction pipeline, while China's dual carbon goals mandate significant renewable capacity additions, creating durable demand signals for developers.
- Turbine Technology Scaling:The commercialization of turbines with capacities exceeding 15 MW enhances the energy output per foundation, improving project economics and making more sites financially viable.
- Energy Security Mandates:National energy strategies in European countries like Germany and Poland are accelerating offshore wind development to reduce dependence on volatile imported gas markets.
Market Restraints
- Specialized Vessel Scarcity:A global shortage of wind turbine installation vessels (WTIVs) capable of handling next-generation large turbines creates significant project scheduling bottlenecks and inflates day rates.
- Grid Interconnection Delays:Inadequate onshore transmission infrastructure, particularly along the US East Coast, creates long queues and uncertainty for connecting new offshore capacity to the national grid.
- Input Cost Volatility:Fluctuations in the price of steel, a primary material for foundations and towers, expose project budgets to significant commodity market risk and can derail final investment decisions.
Strategic Opportunities
- Green Hydrogen Feedstock:Developing offshore wind projects specifically to power large-scale electrolyzers offers a direct route to the burgeoning green hydrogen market, bypassing grid constraints.
- Floating Wind Platforms:Commercializing floating foundation technology is critical for unlocking deep-water resources off the coasts of California, Scotland, and Japan, which are inaccessible to fixed-bottom turbines.
- Hybrid Asset Development:Integrating offshore wind farms with subsea interconnectors or large-scale battery storage creates new revenue streams and enhances grid stability, as seen in North Sea projects.
Industry Challenges
- High-Voltage Technician Shortage:A lack of qualified technicians certified for offshore high-voltage systems and complex blade repair work constrains operations and maintenance capacity, impacting asset availability.
- Foundation Design Standardization:The absence of standardized foundation designs across different developers and regions prevents the supply chain from achieving economies of scale in manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Wind Power Market |
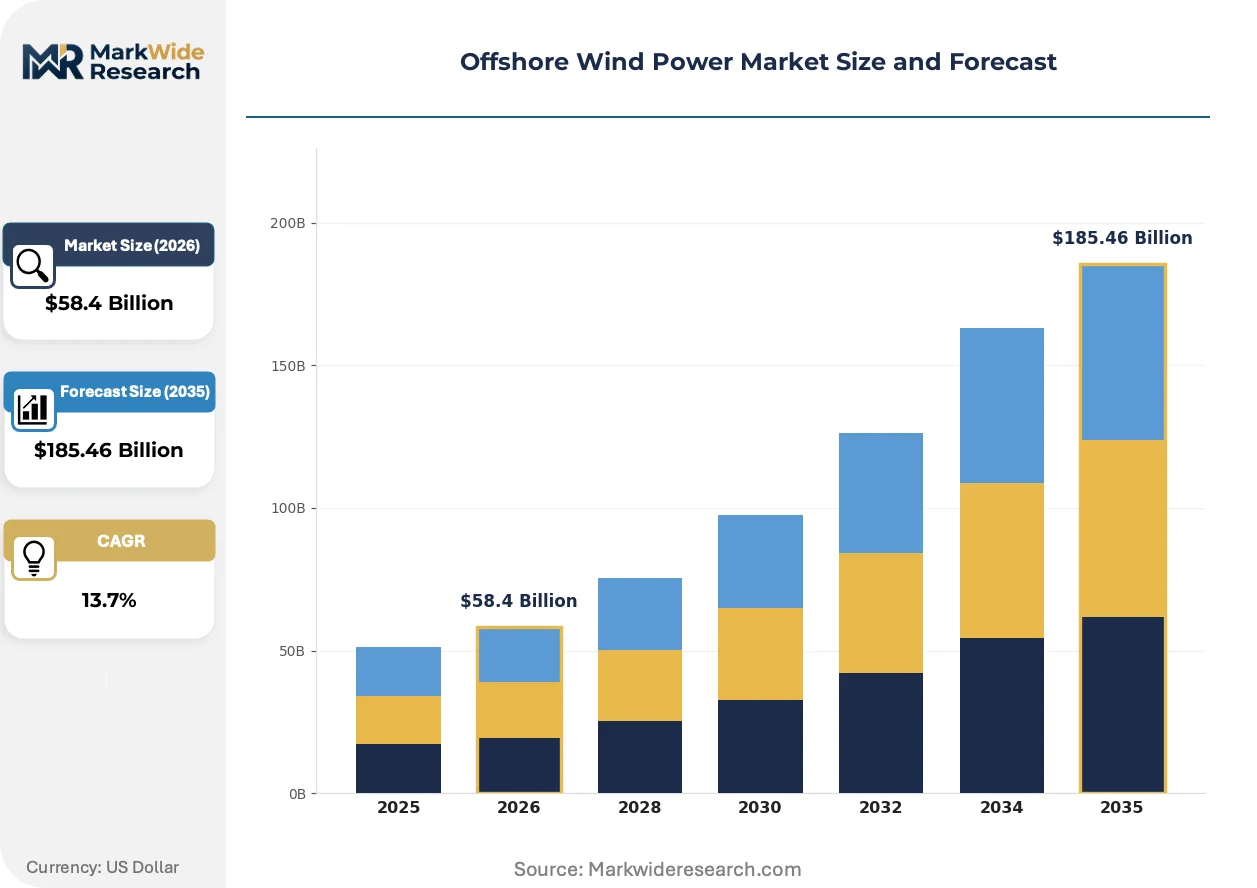
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $185.46 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed-Bottom, Floating, Semi-Submersible, Jacket, Spar-Buoy Application: Utility-Scale Generation, Grid Stabilization, Green Hydrogen Production, Desalination, Aquaculture Power Supply Installation Depth: Shallow Water, Transitional Depths, Deep Water, Ultra Deep Water End User: Independent Power Producers, National Grid Operators, Renewable Energy Developers, Power Trading Companies |
| Companies Covered | Ørsted, Equinor, Siemens Gamesa, GE Vernova, Vestas Wind Systems, RWE, Shell, BP, MHI Vestas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Wind Power Market Strategic Shifts & Innovations
The technological and commercial evolution of offshore wind is defined by a dual pursuit of greater scale in energy generation and more compact, efficient power transmission systems. This drive for efficiency influences component design, project siting, and regulatory engagement.
High-voltage direct current (HVDC) converter technology enables efficient power transmission from far-from-shore wind farms with minimal energy loss. Developers of large-scale projects in the North Sea and off the US Atlantic coast are increasingly specifying HVDC systems. This adoption is miniaturizing the physical footprint and weight of offshore substations, reducing the capital cost of the massive steel platforms required to house them.
Regulatory frameworks like the US Inflation Reduction Act (IRA) are directly influencing sourcing decisions through domestic content requirements. The act provides significant tax credits for projects utilizing US-made steel, foundations, and vessels. As a result, developers targeting auctions for sites off Massachusetts and New York are actively working to cultivate a domestic supply chain to maximize incentive value.
Corporate power purchase agreements (PPAs) are altering the traditional offtake model for offshore wind generation. Large industrial and technology firms are now contracting directly with developers for long-term energy supply, bypassing utility intermediaries. This trend is most prominent in Europe, where corporations in Germany and the Netherlands secure renewable power to meet internal decarbonization targets and gain cost certainty.
Offshore Wind Power Market Segmentation
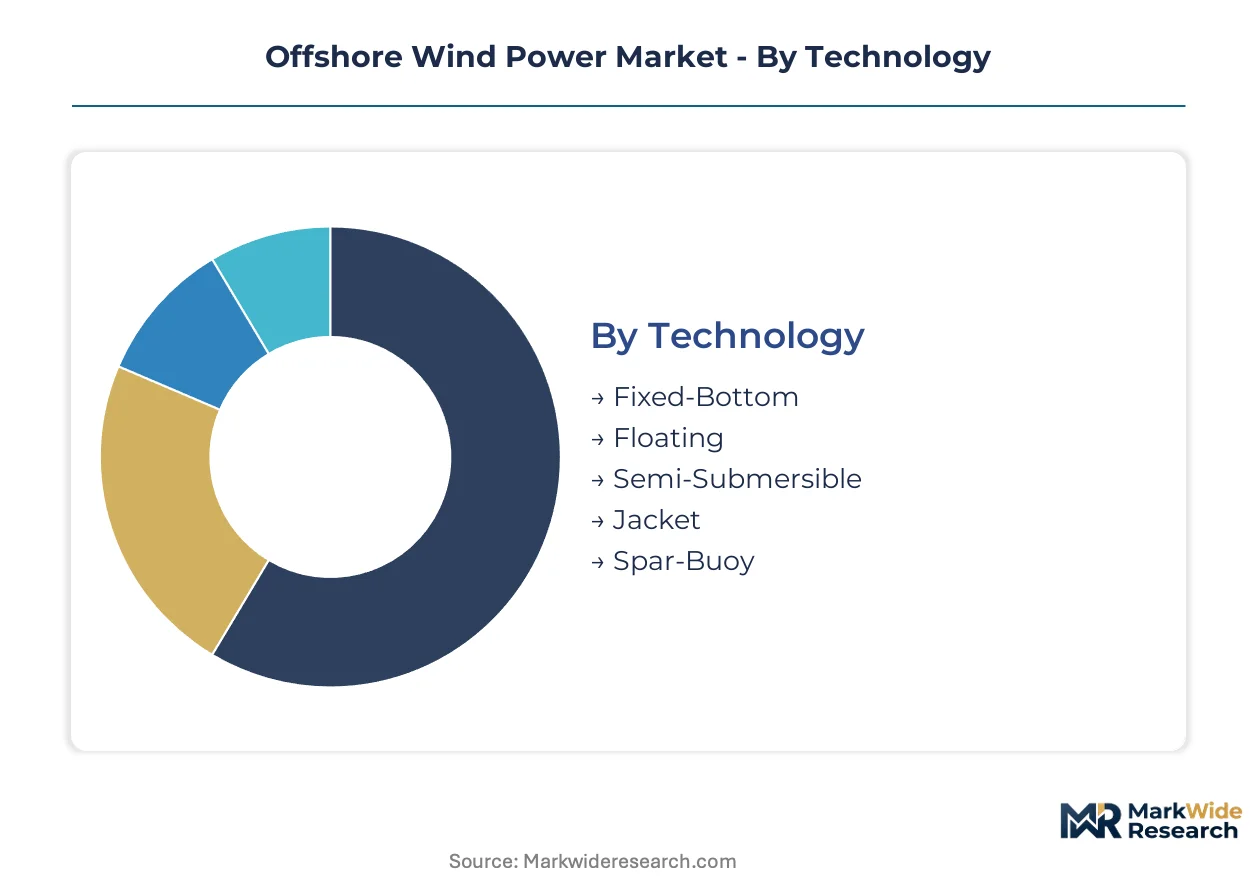
The offshore wind power market's segmentation reveals the diverse technological pathways and application areas driving its expansion. Understanding these distinct segments is critical for stakeholders to align investment with evolving demand and regulatory landscapes. This granular view highlights where innovation is most impactful and where established methods still dominate.
Technology:
The technology segment faces intense substitution pressure from novel designs that promise to unlock new geographic markets and reduce installation costs.
- Fixed-Bottom:These foundations are piled directly into the seabed, typically in waters up to 60 meters deep. Demand concentrates in the North Sea, driven by established infrastructure and mature supply chains in the United Kingdom and Germany.
- Floating:Floating platforms are moored to the seabed, allowing installation in deep waters inaccessible to fixed-bottom structures. This technology is critical for unlocking vast resources off the coasts of California and Scotland, addressing limited shallow water availability.
- Semi-Submersible:This floating foundation type uses ballast and mooring lines for stability, suitable for depths exceeding 60 meters. It offers a stable platform for large turbines.
- Jacket:Jacket foundations are lattice structures pinned to the seabed, often used in transitional depths between 30 and 80 meters. They provide robust support in challenging conditions.
- Spar-Buoy:Spar-buoy foundations are slender, cylindrical structures ballasted to float vertically, ideal for very deep waters. They offer stability with minimal seabed footprint.
Fixed-Bottom technology anchors the volume base while Floating platforms gain share at the steepest rate.
Application:
The application segment is differentiated by the value proposition each use case offers to stakeholders and the grid.
- Utility-Scale Generation:This involves large offshore wind farms directly feeding electricity into national grids to meet broad energy demand. Demand is concentrated in the United Kingdom and Germany, driven by national energy security mandates.
- Green Hydrogen Production:Offshore wind power directly supplies electricity to electrolyzers, producing hydrogen without reliance on grid infrastructure. This application is gaining traction in the Netherlands and Denmark, driven by decarbonization targets for heavy industry.
- Grid Stabilization:Offshore wind farms can contribute to grid stability through reactive power support and ancillary services. This function is particularly valuable for island grids or regions with high renewable penetration.
- Desalination:Using offshore wind to power desalination plants offers a sustainable solution for freshwater scarcity in coastal regions. Projects are being explored in arid coastal areas.
- Aquaculture Power Supply:Dedicated offshore wind systems can provide reliable power to remote aquaculture operations, reducing reliance on fossil fuels. This supports sustainable seafood production.
Utility-Scale Generation remains the primary revenue driver, but Green Hydrogen Production exhibits the most rapid expansion.
Installation Depth:
Installation depth segments are defined by the volume of accessible seabed resources and the engineering challenges associated with each.
- Shallow Water:Defined as depths up to 60 meters, this segment utilizes established fixed-bottom technologies like monopiles and jackets. Demand is highest in the North Sea, driven by favorable seabed conditions and lower installation costs.
- Deep Water:Covering depths from 60 meters to 1,000 meters, this segment necessitates floating wind platforms for economic viability. Development is accelerating off the coasts of Norway and Japan to access significant untapped wind resources.
- Transitional Depths:This range, typically between 30 and 80 meters, can accommodate both advanced fixed-bottom and early floating concepts. It serves as a bridge for technology evolution.
- Ultra Deep Water:Depths exceeding 1,000 meters represent the frontier for floating wind technology, requiring highly advanced mooring and dynamic cable solutions. This segment holds immense long-term potential.
Shallow Water installations currently account for the largest capacity, with Deep Water projects representing the next frontier for development.
End User:
End user segments are characterized by their procurement models and their capacity for project financing and risk absorption.
- Independent Power Producers:These entities develop, own, and operate power generation facilities, selling electricity to the grid or directly to consumers. Their role is expanding in the US market, propelled by tax incentives from the IRA.
- Renewable Energy Developers:Specialized firms focused on planning, financing, and executing renewable energy projects, including offshore wind. Ørsted and Equinor exemplify this segment, leveraging deep project development expertise.
- National Grid Operators:These public or private entities manage and operate national electricity transmission networks. They traditionally procure power but now face a shift towards direct developer engagement.
- Power Trading Companies:Firms that buy and sell electricity in wholesale markets, optimizing supply and demand across various sources. They facilitate market liquidity and price discovery for offshore wind.
Independent Power Producers and Renewable Energy Developers are increasingly shaping project development, shifting from traditional utility-led models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expansion of high-voltage direct current (HVDC) grid interconnectors underpins the global reach of offshore wind power development. These critical infrastructure assets facilitate efficient energy transmission from remote marine sites to onshore demand centers. This enables large-scale project viability across diverse geographies.
United Kingdom
Demand for offshore wind in the United Kingdom is driven by ambitious decarbonization targets and national energy security mandates. The Contracts for Difference (CfD) scheme provides long-term revenue stability for developers. Projects in the Dogger Bank zone off the North East coast represent significant capacity additions.
Germany
Germany's strong industrial base and commitment to renewable energy propel its offshore wind sector. The EU Green Deal and national energy laws mandate substantial capacity build-out. Large turbine assembly facilities in Emden support project deployment in the German Bight.
China
China's dual carbon goals create immense demand for new offshore wind capacity to meet industrial and urban energy needs. National policies provide incentives for domestic component manufacturing and project development. Coastal provinces like Jiangsu are rapidly expanding their offshore wind fleets and related supply chains.
United States
The United States East Coast faces demand for clean energy to power dense population centers and transition away from fossil fuels. The Inflation Reduction Act (IRA) offers substantial tax credits for projects with domestic content. New Bedford, Massachusetts, is developing specialized port infrastructure to support turbine staging and installation.
Japan
Japan's limited land area and deep-water coastlines generate demand for floating offshore wind technology to harness vast marine resources. METI is actively promoting demonstration projects and policy frameworks for deep-water development. Projects off the coast of Fukushima are exploring advanced floating platform designs for commercial viability.
Offshore Wind Power Market Key Industry Players
Concentration sits with integrated developers capable of managing complex project lifecycles, from seabed lease acquisition to power generation. The market exhibits a tiered structure, with a few large players dominating utility-scale projects and a broader base of specialized component suppliers. Strategic archetypes include vertically integrated developers, specialized floating wind innovators, and major turbine manufacturers. Portfolio diversification into green hydrogen production and strategic partnerships for grid interconnection represent dominant competitive moves.
Among the market's prominent participants, Ørsted represents the archetype of a large-scale renewable energy developer, demonstrating expertise in securing seabed leases and managing utility-scale projects. Equinor occupies a distinct position as a specialist in applying offshore oil and gas capabilities to complex floating wind installations, unlocking deep-water resources. Siemens Gamesa anchors the turbine manufacturing segment, exemplified by its focus on large-rotor technology for enhanced energy output. These companies collectively shape technological advancements and project execution strategies within the sector.
| Leading Market Players |
|---|
| Ørsted |
| Equinor |
| Siemens Gamesa |
| GE Vernova |
| Vestas Wind Systems |
| RWE |
| Shell |
| BP |
| MHI Vestas |
| Others |
Cost & Logistics Intelligence
Multi-year project lead times for offshore wind farms directly influence the supply chain's ability to scale and dictate long-term pricing power for specialized components. This dynamic creates significant cost visibility challenges for developers.
Pricing Analysis
Project-based pricing models dominate the offshore wind market, reflecting the bespoke nature of large-scale installations. Price differentiation stems from turbine capacity exceeding 15 MW and the complexity of installation depth, distinguishing fixed-bottom from floating projects. Pricing pressure is currently upward due to specialized vessel scarcity and input cost volatility for steel. Utility-scale generation projects, driven by national energy security mandates, exhibit lower price sensitivity compared to emerging green hydrogen production initiatives.
Supply Chain Analysis
The critical shortage of specialized Wind Turbine Installation Vessels (WTIVs) creates a significant chokepoint within the global offshore wind supply chain. Geographic supply concentration draws from Europe, particularly Germany for turbine assembly, and China for domestic component manufacturing. Raw material dependencies center on steel for foundations and towers, exposing project budgets to commodity market risk. Distribution runs through large renewable energy developers and specialized EPC contractors, managing complex logistics for oversized components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore wind market is undergoing a high-growth disruption, driven by the rapid commercialization of HVDC converter technology for efficient long-distance power transmission. This innovation unlocks previously inaccessible remote sites.
For Market Incumbents:Consolidate strategic seabed leases and invest in specialized vessel capacity to mitigate project scheduling bottlenecks. Developers like Ørsted should deepen vertical integration into critical supply chain elements, such as foundation manufacturing, to counter input cost volatility. This strategy protects project margins against emerging supply chain threats and ensures timely project completion.
For New Entrants and Emerging Players:Domestic content certification fast-tracks under the US Inflation Reduction Act offer a compelling entry point for specialized component manufacturers. Target deep-water floating wind solutions off the coasts of California or Japan, leveraging innovative platform designs. A focused go-to-market angle on modular floating substructures can capitalize on the evolving technology landscape.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across deep-water floating wind projects, driven by complex engineering requirements. Long-term viability rests on national decarbonization mandates and energy security imperatives, ensuring sustained investment over a decade. Focus on acquiring specialized floating platform developers or HVDC system integrators. Grid interconnection progress on the US East Coast serves as a crucial signal for investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout in North Sea | Expands utility-scale generation to meet European energy security mandates. |
| Corporate Power Purchase Agreements | Secures long-term revenue streams and supports corporate decarbonization targets. |
| Floating Platform Technology Licensing | Unlocks deep-water resources in regions like Japan and Scotland. |
| Vertical Integration into Battery Storage | Enhances grid stability and creates new revenue streams for hybrid assets. |
| Green Hydrogen Project Development | Addresses burgeoning demand for clean industrial feedstock and bypasses grid constraints. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to establish a comprehensive understanding of the offshore wind market dynamics. Primary interviews with renewable energy developers, national grid operators, turbine manufacturers, and EPC contractors were triangulated with extensive secondary validation. Data sources included government energy agency reports, regulatory filings from FERC, industry association publications from WindEurope, and financial reports of publicly listed companies, ensuring a robust bottom-up and top-down analytical approach.
The market assessment spans over the projection horizon, utilizing a robust analytical framework to model future growth trajectories. Segmentation dimensions included technology (fixed-bottom, floating), application (utility-scale generation, green hydrogen production), installation depth (shallow, deep), and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were extrapolated from historical growth trends and projected policy impacts. Key forecast inputs included anticipated turbine capacity scaling and confirmed regulatory auction pipelines from the EU Green Deal and US IRA.
Decision-makers should treat outputs as directional under assumptions of sustained policy support and stable commodity markets; material deviation would warrant model refresh. Forecasts reflect underlying assumptions regarding technological advancements in floating wind and grid infrastructure development. Practitioners should keep alternative scenarios live as global energy policies and supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Wind Power Couplings Market