
 Wind Turbine Lenses Market | 2026-2036
Wind Turbine Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Lenses Market Analytics
Aftermarket service revenue for turbine optical systems is fragmenting as OEMs and third-party specialists compete for replacement cycles and retrofit upgrades. Vestas Wind Systems AS leverages its installed base across European and North American fleets to capture recurring lens refurbishment demand. Siemens Gamesa Renewable Energy SA sustains captive supply chains for blade-tip lighting lenses, while Goldwind Science & Technology Co., Ltd. anchors domestic sourcing for China's expanding offshore installations.
Wind turbine lenses are precision optical components, typically molded from polycarbonate or acrylic substrates with anti-reflective and UV-stabilized coatings, engineered to direct, focus, or diffuse light for aviation obstruction marking, condition monitoring sensors, and nacelle illumination systems. Fresnel configurations dominate volume demand due to their lightweight, flat-profile design suited for blade-tip integration, while convex geometries command premium positioning in offshore applications requiring long-throw visibility under marine atmospheric conditions. Coating type segmentation splits between hydrophobic marine-grade treatments and standard aerodynamic finishes, with maintenance providers representing the fastest-growing end-user channel as fleet ages extend replacement intervals.
The EU Green Deal and F-Gas Regulation shape material compliance for sealed optical assemblies, while FAA obstruction lighting standards in the United States dictate photometric output and lens durability thresholds for aviation safety certification. China's GB standards and MIIT technical guidelines enforce localization ratios that influence supply chain configuration for foreign manufacturers serving domestic projects. Stakeholders must monitor evolving aviation authority mandates for offshore visibility zones and assess backward integration into coating application capabilities as margin pools shift from component supply to certified assembly provision.
Market Dynamics
Offshore wind farm developers are consolidating procurement specifications around marine-grade optical durability, compressing supplier qualification timelines as blade-tip lighting systems face intensified aviation authority scrutiny across North Sea and Atlantic installations.
Growth Catalysts
- EU Green Deal aviation safety mandates:Tightened obstruction marking requirements for offshore visibility zones are forcing blade-tip lighting retrofits across Danish and German fleets, accelerating replacement cycles for degraded lens assemblies.
- China's MIIT localization ratios:Domestic content thresholds for offshore wind components are redirecting supply chain configuration toward captive optical molding capacity in Jiangsu and Guangdong provinces.
- Fresnel lens lightweighting:Flat-profile polycarbonate configurations are displacing convex geometries in onshore blade applications, reducing aerodynamic drag penalties while maintaining photometric output.
Market Restraints
- Optical-grade polymer feedstock concentration:UV-stabilized polycarbonate resin supply concentrates among three petrochemical suppliers in Northeast Asia, exposing lens molders to price volatility and allocation risk.
- F-Gas Regulation sealed assembly compliance:EU restrictions on fluorinated greenhouse gases are complicating hydrophobic coating formulations for marine-grade lenses, extending R&D validation timelines.
- Glass optical fiber substitution:Illuminated blade-tip systems using embedded fiber bundles are capturing share in premium offshore applications where electromagnetic interference resistance outweighs cost premiums.
Strategic Opportunities
- US Atlantic seaboard offshore buildout:Massachusetts-to-Virginia lease auctions are creating demand for long-throw visibility lenses rated for marine atmospheric attenuation, a specification gap among incumbent suppliers.
- Condition monitoring sensor integration:Convergence of blade-tip lighting housings with LiDAR and camera payloads is opening design-in relationships with turbine OEMs seeking consolidated optical platforms.
- Aftermarket channel disintermediation:Direct procurement relationships between wind farm operators and specialized lens refurbishers are bypassing traditional OEM service networks, compressing replacement part margins.
Industry Challenges
- Multi-jurisdiction certification sequencing:Simultaneous FAA, EASA, and CAAC aviation safety approvals for new lens designs extend time-to-revenue by 18-24 months, straining smaller optical component specialists.
- Coating application talent scarcity:Vacuum deposition technicians capable of applying anti-reflective and hydrophobic multilayer stacks command premium wages, constraining capacity expansion for qualified assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Lenses Market |
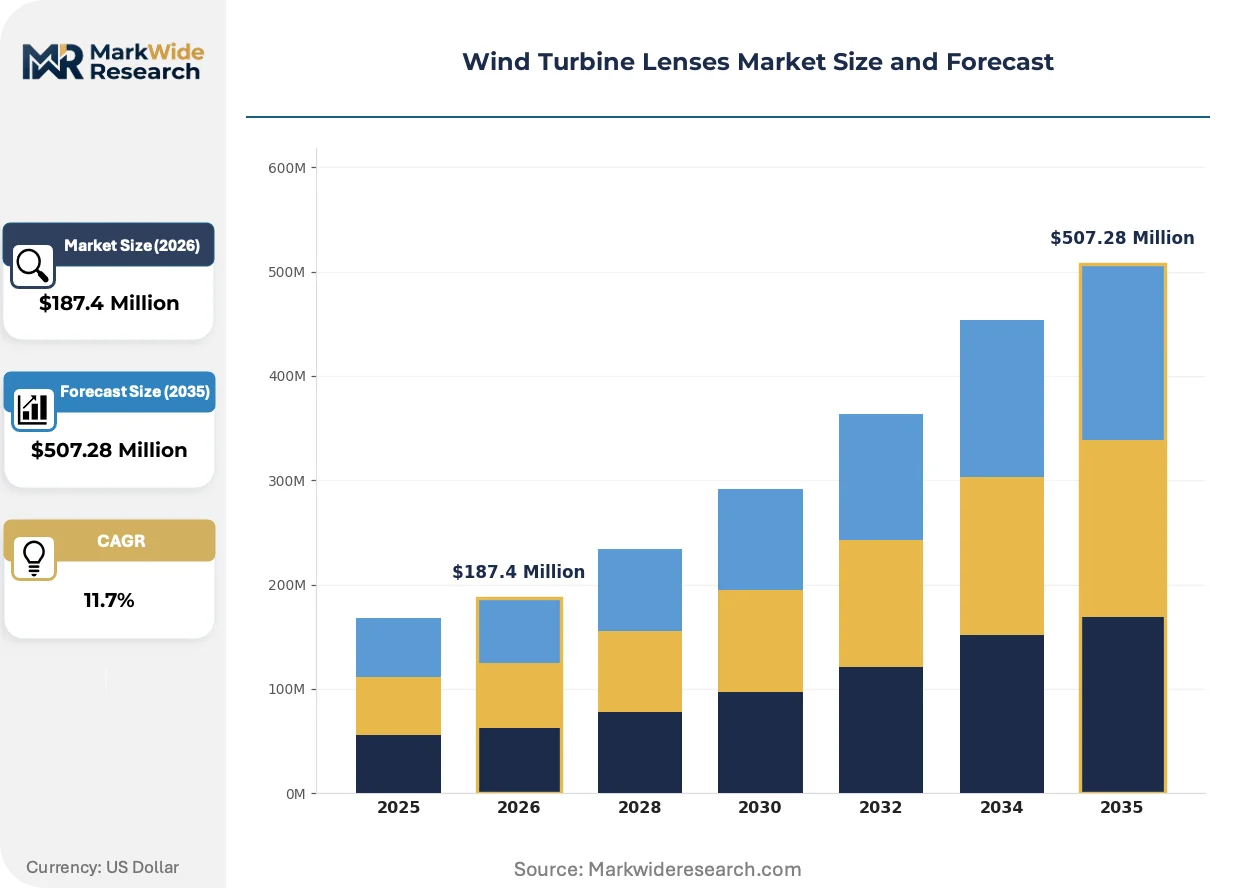
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Lens Material, Coating Type, Size, Shape End User: Manufacturers, Installers, Utilities, Maintenance Providers Application: Onshore, Offshore, Research, Development Technology: Fresnel, Convex, Concave, Flat |
| Companies Covered | Vestas Wind Systems AS, Siemens Gamesa Renewable Energy SA, Goldwind Science & Technology Co., Ltd., GE Vernova Inc., Nordex SE, Ming Yang Smart Energy Group Limited, Envision Energy, Enercon GmbH, TPI Composites Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Lenses Market Evolving Landscape
Photonic integration and materials science advances are compressing the functional boundary between passive optical components and active sensor housings, reshaping how turbine operators specify blade-tip assemblies.
Embedded LED arrays with integrated Fresnel optics are rendering obsolete separate lamp-and-lens assemblies in new turbine builds. Siemens Gamesa and Vestas procurement teams are specifying these consolidated modules for 2024-2025 offshore deliveries. The consolidation is compressing supplier tiers as lens molders must now certify complete photometric assemblies rather than discrete components.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of marine-grade hydrophobic coatings. ECHA's 2023 PFAS restriction proposals are accelerating substitution toward silicone-based water-repellent treatments. German and Danish turbine operators are demanding coating durability warranties exceeding 15 years, pushing suppliers toward accelerated salt-spray validation protocols.
Condition-based replacement scheduling is displacing fixed-interval lens refurbishment contracts. North Sea wind farm operators are procuring optical transmissivity monitoring as a bundled service, triggering spot replacement only when UV degradation thresholds breach aviation safety margins. This unbundling is most visible in Danish fleet management contracts, where Vestas faces third-party specialist competition for previously captive aftermarket revenue.
Wind Turbine Lenses Market Segmentation
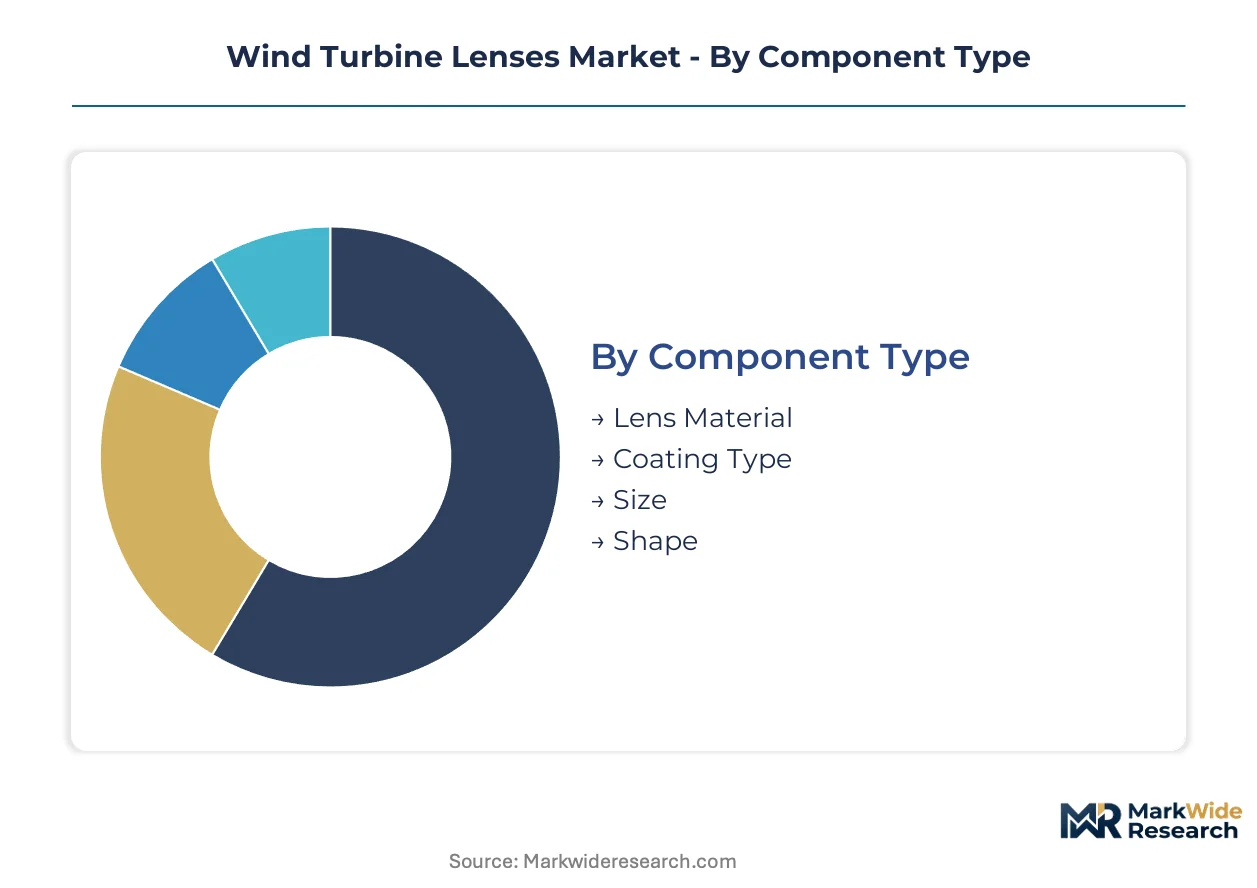
Wind turbine lens procurement fragments across four structural dimensions. Component specifications dictate coating durability and optical geometry, while end-user channel selection determines margin capture and replacement cycle timing.
Component Type:
Material composition and surface engineering separate cost tiers and performance grades for aviation safety compliance.
- Lens Material:Polycarbonate substrates dominate volume production for blade-tip integration due to impact resistance and UV stability. Demand concentrates in Jiangsu province molding facilities serving China's offshore buildout, constrained by optical-grade resin allocation from Northeast Asian petrochemical suppliers.
- Coating Type:Hydrophobic marine-grade treatments command premium positioning for North Sea atmospheric conditions. Installations across Denmark and Germany require 15-year salt-spray warranties under ECHA reformulation pressures, extending supplier validation timelines.
- Size:Standardized diameters for nacelle illumination systems reduce inventory complexity for maintenance providers.
- Shape:Custom aspheric profiles serve condition monitoring sensor housings in integrated optical platforms.
Lens material holds installed capacity. Coating type is rotating up the share rankings.
End User:
Customer type determines procurement sophistication and contract structure across the equipment lifecycle.
- Maintenance Providers:Third-party specialists capture aftermarket refurbishment demand through direct operator relationships, bypassing OEM service networks. Danish fleet management contracts now unbundle optical transmissivity monitoring from fixed-interval replacement, compressing margin pools for incumbent suppliers.
- Manufacturers:Turbine OEMs specify consolidated LED-Fresnel modules for new builds, requiring lens molders to certify complete photometric assemblies rather than discrete components.
- Installers:EPC contractors procure lens assemblies as part of blade-tip lighting system packages for US Atlantic seaboard projects.
- Utilities:Wind farm operators increasingly source replacement lenses directly from specialized refurbishers, disintermediating traditional supply chains.
Maintenance providers are climbing the fastest. Manufacturers retain specification authority.
Application:
Deployment environment dictates optical performance requirements and regulatory compliance burden.
- Offshore:Marine atmospheric attenuation demands long-throw visibility lenses with convex geometries for blade-tip marking. Massachusetts-to-Virginia lease auctions create specification gaps among incumbent suppliers unaccustomed to Atlantic seaboard salt-load conditions.
- Onshore:Fresnel configurations reduce aerodynamic drag penalties while maintaining photometric output for aviation obstruction compliance. Flat-profile polycarbonate designs displace heavier convex alternatives in land-based installations.
- Research:Test turbine fleets evaluate embedded fiber bundle illumination as electromagnetic interference-resistant alternatives to polymer lenses.
- Development:Prototype blade programs pilot LiDAR-integrated optical housings for condition monitoring convergence.
Offshore commands premium positioning. Onshore rotates toward volume efficiency.
Technology:
Optical geometry selection balances weight, throw distance, and manufacturing complexity against application-specific visibility mandates.
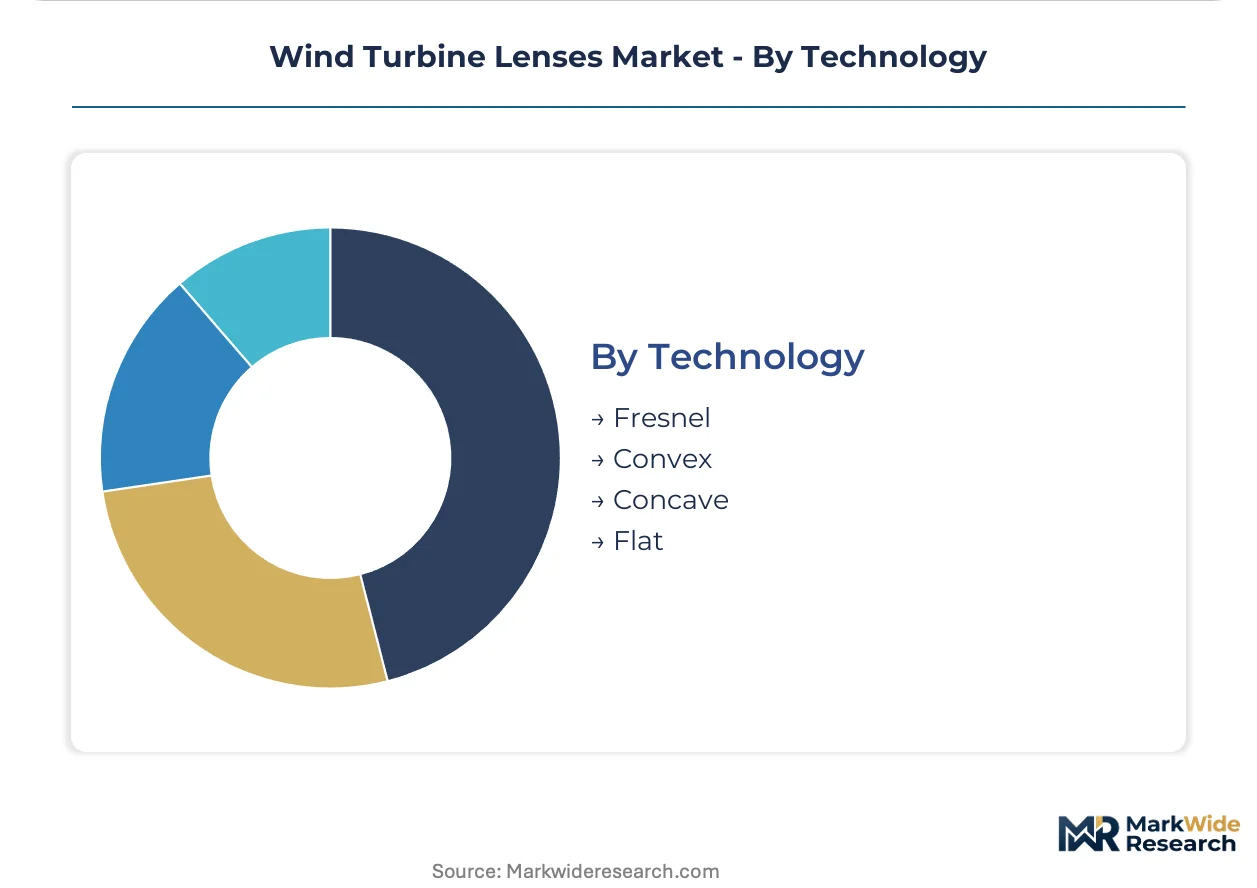
- Fresnel:Concentric prism arrays achieve flat-profile lightweighting ideal for rotating blade integration. Procurement teams at Vestas and Siemens Gamesa specify these configurations for 2024-2025 offshore deliveries, consolidating previously separate lamp-and-lens assemblies.
- Convex:Positive curvature delivers concentrated light output for marine visibility zones under atmospheric attenuation. German and Danish aviation authority scrutiny intensifies qualification requirements for these premium geometries.
- Concave:Diverging beam patterns serve nacelle interior illumination with reduced glare for technician access.
- Flat:Minimal optical power substrates function as protective covers and diffusers in secondary lighting systems.
Fresnel holds volume leadership. Convex maintains premium tier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys turbine lenses primarily for new offshore installations, while European operators concentrate spending on retrofit cycles for aging North Sea fleets. This consumption-mix differential shapes supplier strategies across procurement channels.
China
Offshore wind buildout in Jiangsu and Guangdong provinces drives volume demand for blade-tip lighting assemblies. MIIT localization ratios redirect supply chains toward domestic optical molding capacity. Coastal manufacturing clusters in Yancheng and Zhuhai are scaling polycarbonate lens production for 15+ MW turbine platforms.
Germany
Aviation authority scrutiny of North Sea visibility zones accelerates lens replacement cycles across existing fleets. EU Green Deal mandates and F-Gas Regulation compliance reshape hydrophobic coating specifications. Industrial concentration in Lower Saxony and Schleswig-Holstein anchors refurbishment service networks for Danish-German cross-border installations.
United States
Massachusetts-to-Virginia lease auctions create demand for marine-grade lenses rated for Atlantic seaboard salt-load conditions. FAA obstruction lighting standards dictate photometric output thresholds for certification. Providence and Hampton Roads port clusters are emerging as logistics hubs for offshore construction supply chains.
Denmark
Condition-based replacement scheduling displaces fixed-interval contracts across mature offshore fleets. ECHA PFAS restriction proposals force coating reformulation toward silicone-based alternatives. Copenhagen-Aarhus corridor hosts specialized lens refurbishers competing directly with OEM service networks.
United Kingdom
Dogger Bank and Hornsea zone developments require long-throw visibility lenses under intensified aviation safety marking rules. Crown Estate leasing rounds concentrate developer procurement specifications. Hull and Grimsby offshore wind clusters are integrating optical component logistics into blade manufacturing supply chains.
Wind Turbine Lenses Market Competitive Landscape
Capability concentration sits with specialized optical molders holding coating application expertise; scale advantage sits with turbine OEMs leveraging installed base access for aftermarket capture. The market structures around three tiers: integrated turbine manufacturers with captive supply, independent lens specialists with certified coating capacity, and regional molders serving localized procurement mandates. Dominant competitive moves include backward integration into coating application capabilities and direct procurement relationships that bypass traditional OEM service networks.
Among European-anchored turbine manufacturers, Vestas Wind Systems AS, Siemens Gamesa Renewable Energy SA, and Enercon GmbH exemplify the integrated tier, each leveraging fleet scale to shape lens specification standards and capture recurring refurbishment demand through service network control. These entities occupy positions where installed base access translates into procurement influence over optical component suppliers.
| Leading Market Players |
|---|
| Vestas Wind Systems AS |
| Siemens Gamesa Renewable Energy SA |
| Goldwind Science & Technology Co., Ltd. |
| GE Vernova Inc. |
| Nordex SE |
| Ming Yang Smart Energy Group Limited |
| Envision Energy |
| Enercon GmbH |
| TPI Composites Inc |
| Others |
Value Network & Pricing Analysis
Rotterdam-Hamburg container corridor freight volatility cascades through polycarbonate resin allocation cycles, amplifying price spreads between marine-grade coated lenses and standard aerodynamic finishes while compressing margins for molders without captive coating capacity.
Pricing Analysis
Long-term offtake contracts dominate procurement between turbine OEMs and optical molders, though spot purchasing resurges for aftermarket refurbishment cycles. Three-tier pricing structure across aviation-certified marine-grade, standard offshore-compliant, and onshore economy tiers separates buyers by certification burden and coating durability. Pricing pressure stems from direct procurement relationships between wind farm operators and third-party refurbishers bypassing OEM service networks. Maintenance providers exhibit highest price sensitivity due to unbundled optical transmissivity monitoring contracts, while offshore developers accept premiums for convex geometries rated under EASA visibility mandates.
Supply Chain Analysis
Tariff exposure between China and the European Union complicates supply chain configuration for foreign manufacturers serving domestic projects under MIIT localization ratios. Optical-grade polycarbonate resin production concentrates in South Korea, Japan, and Taiwan, drawing lens molders into allocation risk during petrochemical feedstock disruptions. Hydrophobic coating formulations hinge on silicone-based substitutes as ECHA PFAS restrictions phase out fluorinated compounds. Distribution runs through turbine OEM captive supply chains for new builds, while direct operator relationships reshape aftermarket logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation safety certification entrenchment creates formidable defensive moats for incumbent suppliers, as multi-jurisdiction approval timelines deter rapid competitive entry.
For Market Incumbents: Insulate aftermarket revenue streams by acquiring specialized lens refurbishers in the Copenhagen-Aarhus corridor, neutralizing third-party disintermediation threats. Deepen backward integration into vacuum deposition coating capabilities to capture margin pools shifting from component supply to certified assembly provision, countering price erosion from direct operator procurement. For New Entrants and Emerging Players: Build out coating application capacity targeting the US Atlantic seaboard specification gap for long-throw visibility lenses under marine atmospheric attenuation requirements. Penetrate the Massachusetts-to-Virginia lease auction supply chains through EPC contractor partnerships, leveraging absence of incumbent marine-grade validation as entry wedge. For Investors and Strategic Acquirers: ECHA's 2023 PFAS restriction proposals reshape the acquisition landscape toward silicone-based coating specialists with accelerated salt-spray validation protocols. Target independent optical molders holding FAA-EASA dual certification as consolidation candidates, monitoring aviation authority mandate tightening across North Sea visibility zones as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Application | Captures margin shift from component supply to certified photometric assembly under FAA-EASA mandates. |
| Marine-Grade Validation Acceleration | Addresses specification gaps for Atlantic seaboard salt-load conditions in Massachusetts-to-Virginia projects. |
| Direct Operator Procurement Relationships | Bypasses OEM service networks to capture unbundled aftermarket refurbishment demand in Danish fleets. |
| Silicone-Based Coating Reformulation | Ensures compliance with ECHA PFAS restrictions while maintaining 15-year salt-spray warranties. |
| LiDAR-Integrated Optical Platform Development | Positions for consolidated blade-tip lighting and condition monitoring sensor housing specifications. |
Research Methodology
A standing panel of turbine OEM procurement directors, wind farm operations managers, vacuum deposition technicians, and EPC contractor supply chain leads provided ongoing calibration against secondary validation from FAA certification databases, ECHA regulatory filings, MIIT technical guidelines, and customs trade records. Primary interviews with maintenance provider specialists and optical molder technical directors combined with bottom-up and top-down triangulation to anchor demand estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling component type, end-user channel, application environment, and optical geometry dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating offshore buildout pipelines, aviation authority mandate evolution, and coating technology substitution curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by turbine OEMs or rapid silicone coating scale-up by Asian petrochemical suppliers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Floating Wind Turbine Market