
 Wind Energy Foundation Market | 2026-2036
Wind Energy Foundation Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Energy Foundation Market Outlook
Market Dynamics
Capital-intensity divergence between integrated steel fabricators and pure-play foundation designers is redrawing competitive boundaries in the Wind Energy Foundation Market. Vestas Wind Systems leverages captive steel supply and in-house engineering to sustain margin control across monopile and jacket contracts. GE Renewable Energy anchors its position through turbine-foundation integration packages that reduce interface risk for offshore developers. Bladt Industries specializes in multi-thousand-ton steel structures, occupying a narrow but defensible niche in North European fabrication.
Structural Segments
A wind energy foundation is a subsea or ground-anchored structural element that transfers turbine loads to bearing strata, typically fabricated from rolled steel plate exceeding 80 millimeters thickness with cathodic protection systems and transition piece welding for tower connection. Monopile foundations dominate shallow-water installations up to 40 meters depth, while jacket structures capture margin pools in deeper North Sea and Asian offshore zones where fatigue loading demands complex lattice engineering. Gravity-based concrete designs retain share in markets with restricted pile-driving permits, and suction bucket technology is gaining traction in sensitive seabed environments where noise mitigation governs project approval timelines.
Regulatory Environment
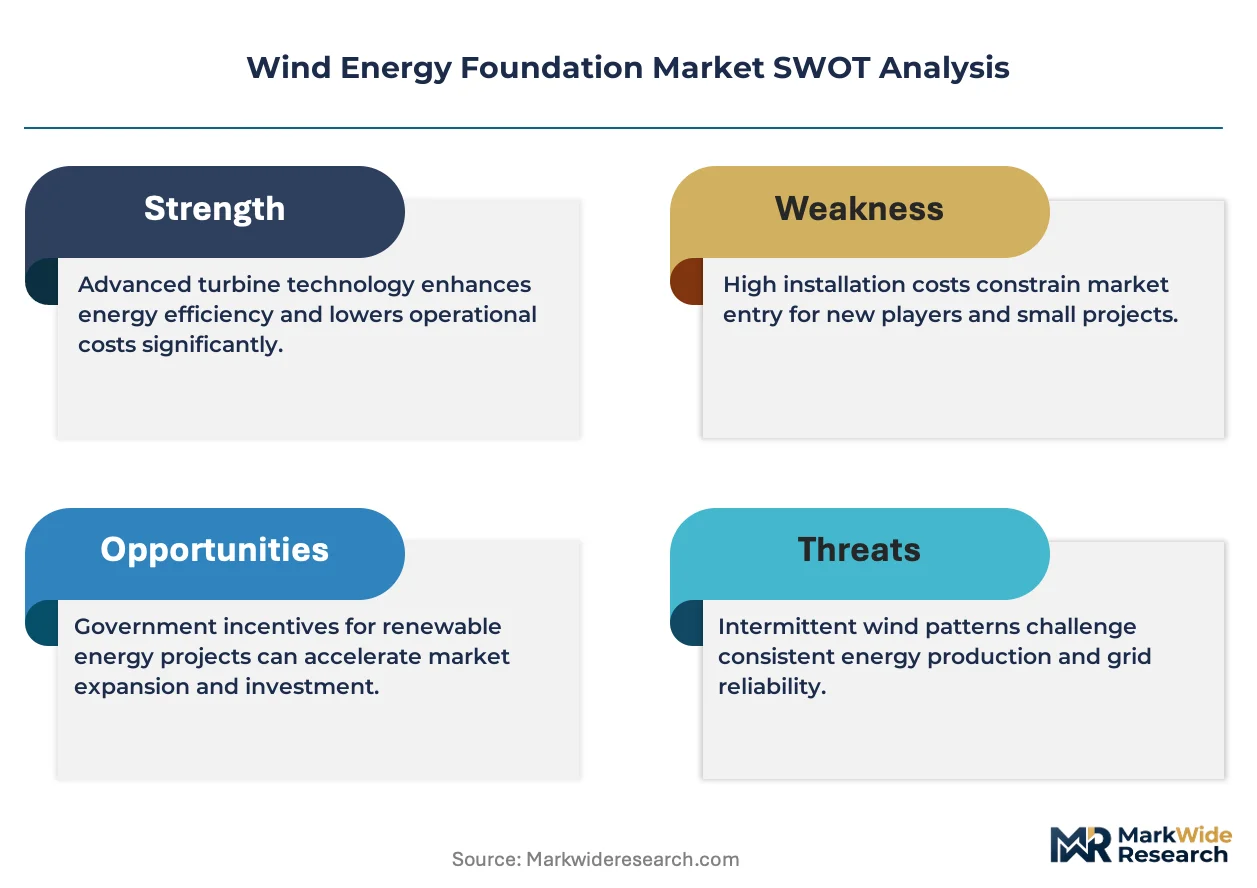
Foundation certification in Europe runs through DNV standards and the EU Green Deal's embedded carbon tracking requirements, while China's MIIT enforces GB steel grading rules for domestic offshore structures. The F-Gas Regulation and REACH compliance on anti-corrosion coatings shape material selection and supply chain qualification for foundation fabricators serving European waters. Stakeholders must monitor evolving national offshore wind auction criteria that increasingly weight foundation recyclability and embedded carbon scores alongside levelized cost metrics.
Market Dynamics
Deep-water foundation procurement is accelerating as North Sea developers push beyond 50-meter depths, triggering a structural shift from monopile to jacket and floating substructure systems that demands new fabrication capacity and specialized installation assets.
Growth Catalysts
- EU Green Deal carbon tracking:Embedded carbon scoring in foundation tenders is forcing fabricators to adopt electric arc furnaces and renewable-powered rolling mills, tightening certification requirements across German and Danish auction rounds.
- Offshore wind lease expansion:The Netherlands, Germany, and Denmark are accelerating seabed licensing for 2030-2035 project pipelines, concentrating demand along clustered North Sea port corridors with heavy-lift vessel access.
- Suction bucket foundation maturation:Noise-sensitive seabed environments in the Baltic and Irish Sea are driving adoption of suction-installed alternatives to pile driving, compressing environmental approval timelines by eliminating acoustic disturbance permits.
Market Restraints
- Steel plate supply concentration:Rolled plate exceeding 80 millimeters thickness is dominated by European and Asian integrated mills, creating input cost volatility when energy-intensive production faces carbon border adjustments.
- Installation vessel scarcity:Heavy-lift jack-up vessels capable of handling 2,000+ ton foundations are concentrated among three European operators, bottlenecking deployment schedules during concentrated construction windows.
- Fixed-bottom technical ceiling:Monopile fatigue limits and scour protection requirements restrict economic viability beyond 60-meter water depths, forcing premature technology transitions in deeper North Sea zones.
Strategic Opportunities
- Floating foundation emergence:Semi-submersible and tension-leg platforms unlock Japanese, South Korean, and US West Coast markets where deep continental shelves exclude fixed-bottom economics.
- Foundation-turbine integration packages:Developers are consolidating procurement under single-contractor models that absorb interface risk between steel structures and tower OEMs, creating margin pools for integrated engineering specialists.
- Port infrastructure monetization:Quayside fabrication facilities in Esbjerg, Cuxhaven, and Rotterdam are capturing value through vertical service integration into storage, load-out, and marshalling operations.
Industry Challenges
- Welding certification bottlenecks:Transition piece fabrication demands specialized offshore-grade welders qualified to DNV-OS-C401 standards, with training pipelines failing to match capacity expansion timelines.
- Cathodic protection system integration:Coating compatibility between sacrificial anodes and high-strength steel substrates requires extended qualification cycles that compress project execution schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Energy Foundation Market |
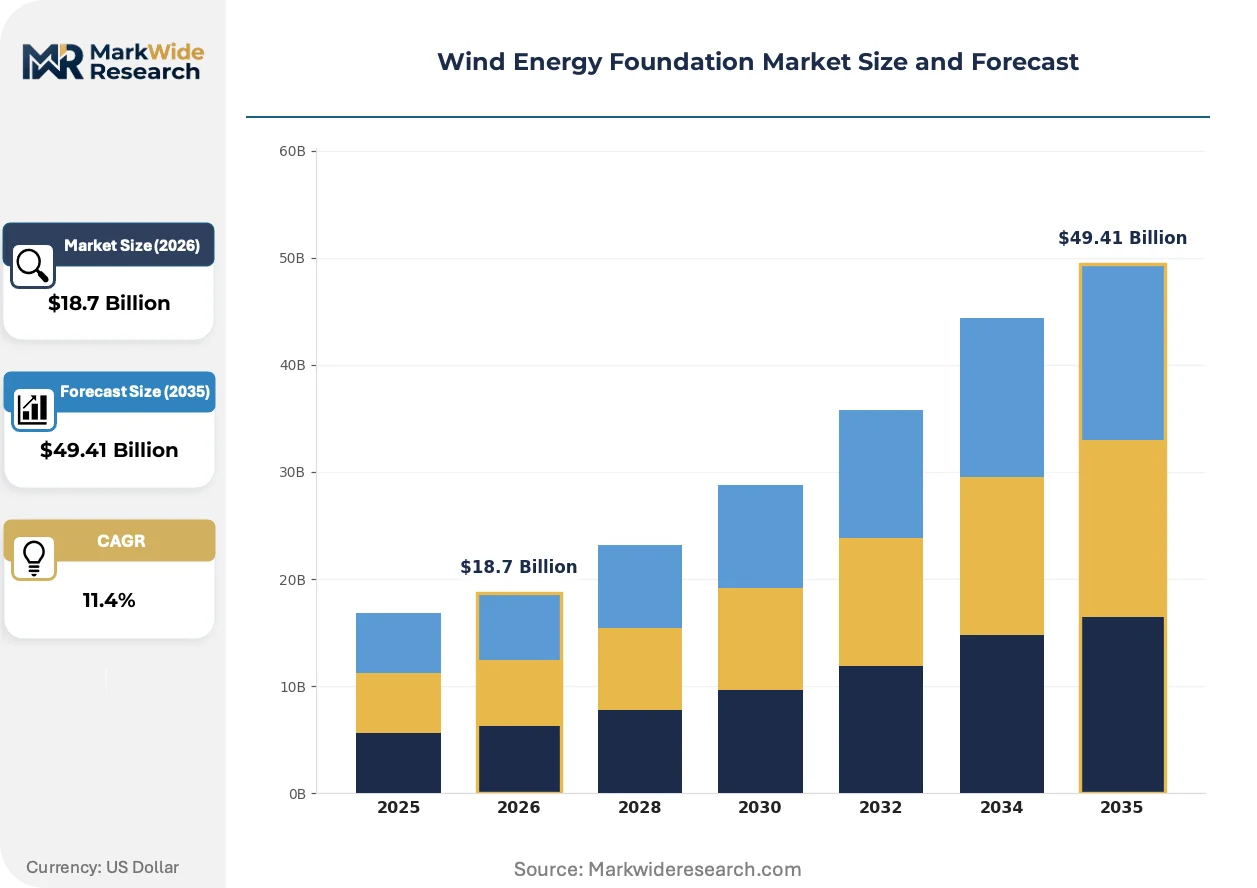
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Foundation Type: Monopile, Gravity, Suction Bucket, Jacket Installation Method: Bottom-Fixed, Floating, Hybrid, Onshore Material: Concrete, Steel, Composite, Reinforced End User: Utilities, Developers, Contractors, Government |
| Companies Covered | Vestas Wind Systems, GE Renewable Energy, Fugro Inc., Nordex, Ørsted, Bladt Industries, Siemens Gamesa Renewable Energy, Goldwind, Iberdrola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Energy Foundation Market Strategic Shifts
Fabrication methodologies and foundation architectures are undergoing rapid transformation as water depths, turbine ratings, and environmental constraints outpace legacy design paradigms established for shallow-water monopile deployment.
Modular jacket structures assembled from tubular nodes and chords are decomposing traditional integrated fabrication workflows. Offshore developers in the North Sea and Taiwan are specifying component-level transport and offshore assembly to bypass quayside crane capacity constraints. This decomposition is compressing the addressable market for single-source heavy-fabrication yards while expanding opportunities for specialized tubular suppliers and offshore construction contractors.
The EU F-Gas Regulation and REACH compliance on anti-corrosion coatings are reshaping material selection across European foundation supply chains. Coatings containing restricted fluorinated compounds face phase-out timelines, forcing reformulation of splash-zone protection systems. Fabricators serving German and Dutch markets are accelerating qualification of silicone-modified epoxy alternatives to maintain certification continuity under DNV-ST-0126 standards.
Developer procurement teams are consolidating foundation-tower-nacelle packages under single-point accountability contracts. This bundling is displacing discrete component tendering that previously segmented risk across steel fabricators, turbine OEMs, and marine contractors. The shift is most visible in Danish and UK Round 4/5 auctions where levelized cost optimization favors integrated performance warranties over component-level price competition.
Wind Energy Foundation Market Segmentation
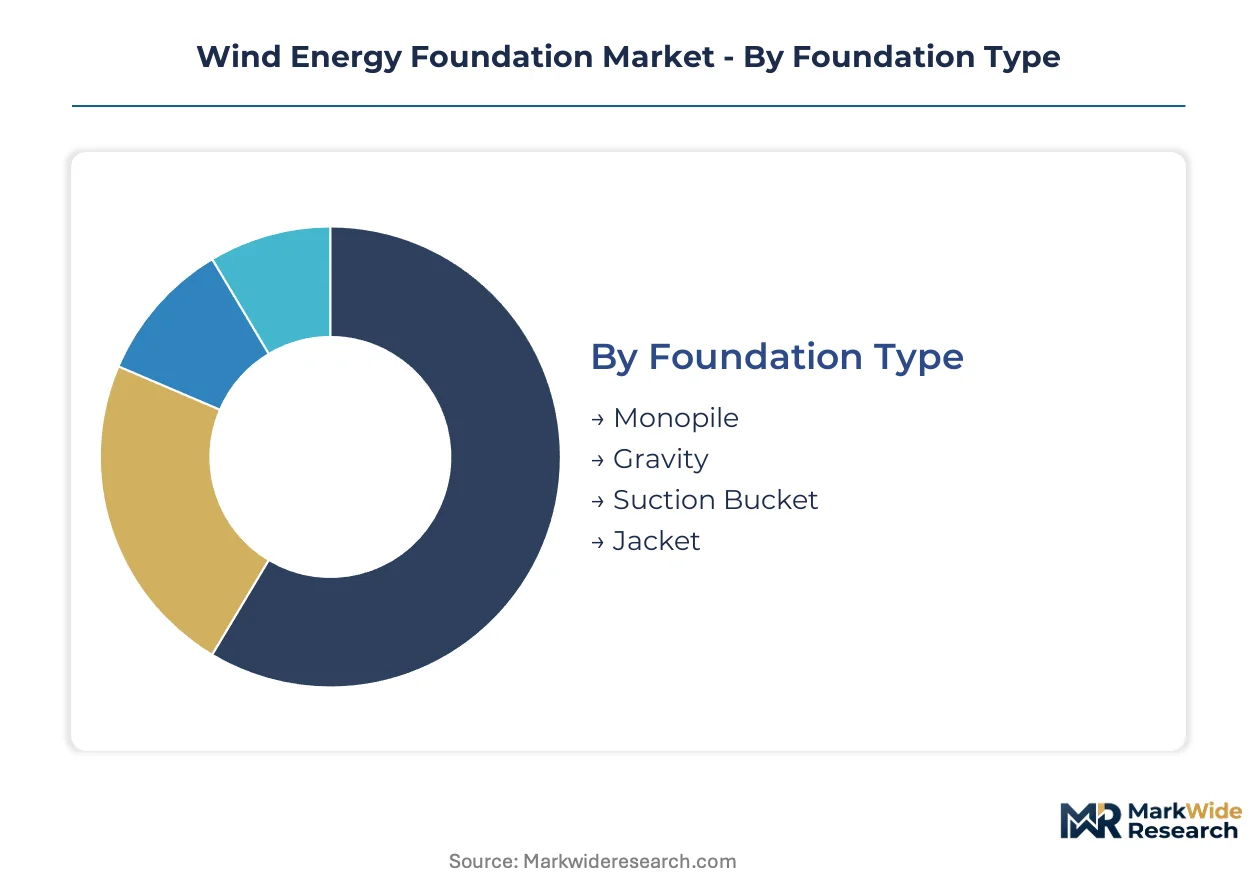
Foundation segmentation determines fabrication capacity allocation, installation vessel deployment, and steel procurement strategies across offshore wind supply chains. Technology choices in this market lock in capital commitments years ahead of turbine installation, making segment-level demand forecasting critical for yard planning and heavy-lift fleet positioning.
Foundation Type:
Margin pools concentrate in deep-water structural systems where engineering complexity and fabrication scarcity protect pricing power against commoditization pressures in shallow-water segments.
- Monopile:Single large-diameter steel cylinders driven or drilled into seabed, typically 6-10 meters diameter with wall thickness exceeding 80 millimeters. Demand clusters in German Bight and Dutch coastal zones where water depths stay below 40 meters and pile-driving permits remain obtainable; fatigue limits and scour protection costs erode economics beyond 50-meter depths.
- Jacket:Lattice steel frameworks of tubular nodes and chords transferring turbine loads through multiple pile points. North Sea developers beyond 50-meter depths specify these structures for their superior stiffness under cyclic loading; specialized fabrication yards in Esbjerg and Cuxhaven capture margin premiums through DNV-certified welding programs.
- Gravity:Massive concrete or steel-concrete composite bases relying on dead weight for stability. Deployed in Baltic Sea markets where Denmark and Germany restrict acoustic disturbance from pile driving.
- Suction Bucket:Steel caissons installed through pressure differential rather than impact driving. Irish Sea and sensitive seabed environments specify these to compress environmental approval timelines.
Monopile holds installed capacity. Jacket is rotating up the share rankings.
Installation Method:
Volume concentration tracks water depth gradients and regulatory constraints on seabed disturbance, with floating systems unlocking previously inaccessible markets.
- Bottom-Fixed:Piled or gravity-based structures anchored directly to seabed. Dominates North Sea deployment where 90% of operating capacity uses this approach; jack-up vessel availability governs installation scheduling.
- Floating:Semi-submersible or tension-leg platforms moored in deep water. Japanese and South Korean developers specify these where continental shelves drop beyond fixed-bottom economic limits; port infrastructure for assembly and tow-out remains scarce outside Nagasaki and Ulsan corridors.
- Hybrid:Combined fixed-floating systems or structures with buoyancy-assisted installation. Taiwan Strait projects evaluate these to reduce heavy-lift vessel requirements.
- Onshore:Ground-anchored foundations for terrestrial wind farms. Concrete gravity and reinforced steel designs serve utility-scale projects with established crane access and geotechnical predictability.
Bottom-Fixed retains deployment dominance. Floating is climbing the fastest as East Asian markets open.
Material:
Cost tier differentiation separates high-strength steel specifications from commodity concrete, with composite materials capturing niche applications in corrosion-critical zones.
- Steel:Rolled plate and tubular sections exceeding S355 grade with through-thickness properties. European mills in Germany and Sweden supply heavy plate under EU Green Deal carbon tracking; offshore structures demand 80-120 millimeter thickness with Z-direction ductility.
- Concrete:High-density marine concrete with specialized mix designs for splash-zone durability. Gravity base manufacturers in Denmark and the Netherlands specify these for Baltic deployments where noise restrictions apply.
- Composite:Fiber-reinforced polymers for secondary structural elements or corrosion barriers. Transition piece internal platforms and cable protection systems specify these to reduce cathodic protection demands.
- Reinforced:Steel-concrete composite configurations combining tensile and compressive performance. Jacket leg grouting connections and monopile transition pieces use these hybrid approaches.
Steel dominates fabrication tonnage. Composite is gaining share fastest in accessory applications.
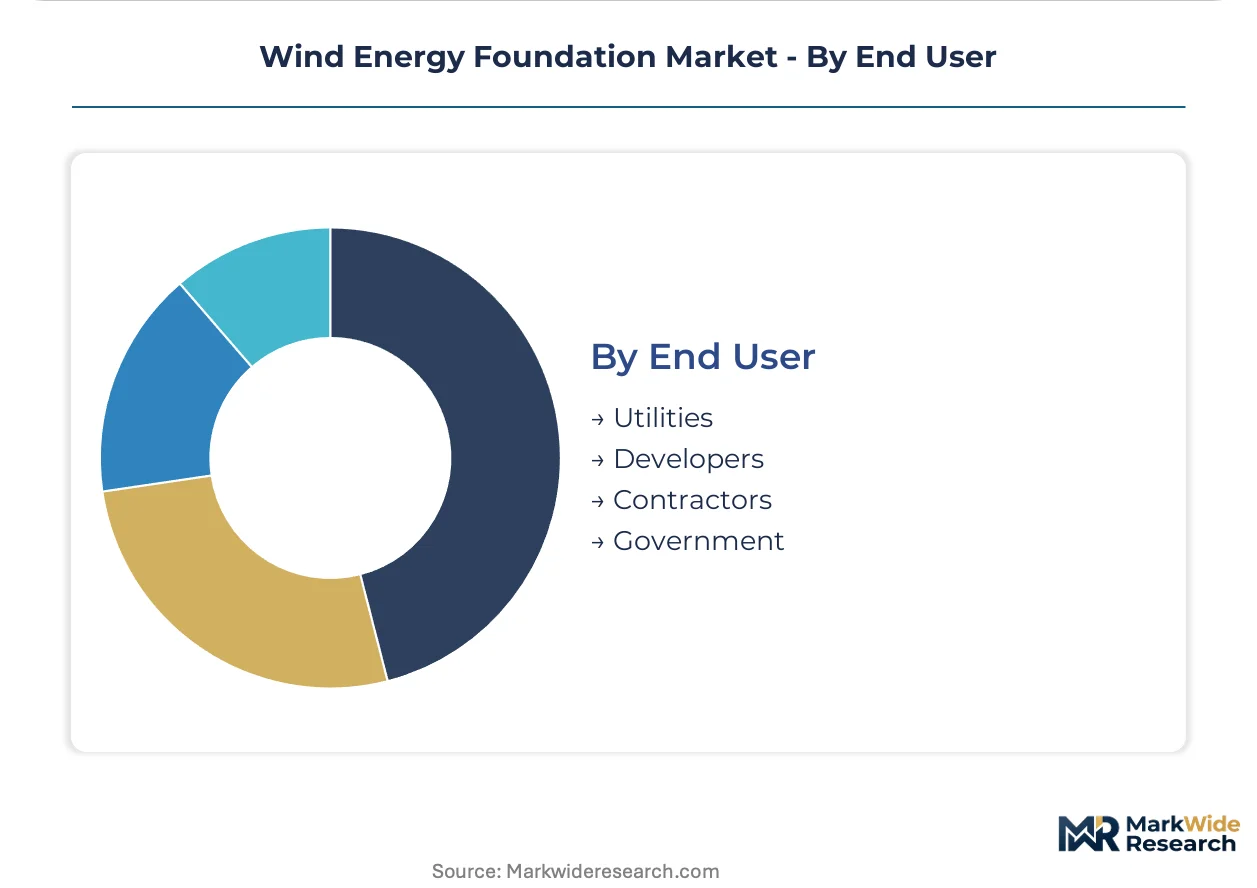
End User:
Procurement consolidation among integrated developers is compressing the contractor addressable market while government-owned pipelines reshape risk allocation.
- Utilities:Vertically integrated power companies with captive offshore wind portfolios. Orsted and RWE specify foundation-turbine integration packages to internalize interface risk.
- Developers:Independent project sponsors aggregating seabed leases and offtake agreements. UK Round 4/5 and German auction winners drive demand for bankable foundation supply contracts.
- Contractors:Engineering-procurement-construction firms delivering turnkey offshore packages. Van Oord and DEME specify foundation fabrication slots years ahead to secure installation vessel coordination.
- Government:State-owned entities and sovereign wealth funds direct-investing in offshore infrastructure. Danish and Dutch state participation shapes local content requirements and port infrastructure prioritization.
Utilities hold procurement volume. Developers are rotating up the share rankings as independent sponsors proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement markets. German and Danish developers prioritize embedded carbon scores and DNV certification over unit cost, while Asian markets weight steel tonnage pricing more heavily in contractor selection.
Germany
Offshore wind auctions under the EU Green Deal mandate carbon tracking for foundation steel, favoring electric arc furnace supply from domestic mills. The Federal Maritime and Hydrographic Agency enforces strict noise mitigation protocols that restrict pile-driving windows. Cuxhaven and Rostock host clustered fabrication yards where Vestas and GE Renewable Energy coordinate monopile load-out with specialized jack-up vessels.
United Kingdom
Round 4 and Round 5 seabed leases are driving demand for jacket structures in deeper North Sea zones beyond 50 meters. The Crown Estate mandates supply chain transparency disclosures that foundation fabricators must embed in tender documentation. Port of Tyne and Able Seaton Port are expanding heavy-lift quayside capacity to accommodate multi-thousand-ton structures.
China
Provincial offshore wind targets in Guangdong and Fujian are accelerating suction bucket foundation trials in sensitive seabed environments. MIIT enforces GB steel grading rules for domestic structures that diverge from European DNV standards. Yantai and Qidong fabrication corridors are scaling jacket production for Taiwan Strait projects.
Netherlands
Hollandse Kust and IJmuiden Ver lease rounds specify foundation recyclability metrics alongside levelized cost thresholds. The Human Environment and Transport Inspectorate coordinates environmental permitting with EU F-Gas Regulation compliance on coating systems. Rotterdam Maasvlakte terminals are integrating storage and marshalling services into foundation supply contracts.
Denmark
Thor and Kriegers Flak extensions are tightening local content requirements for steel fabrication. The Danish Energy Agency embeds embedded carbon scoring in auction evaluation criteria alongside price bids. Esbjerg port infrastructure is capturing value through vertical service integration from quayside welding to offshore load-out coordination.
Wind Energy Foundation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in the Wind Energy Foundation Market. Integrated turbine OEMs with captive steel engineering capabilities command premium positioning in bundled foundation-tower contracts, while pure-play fabricators compete on throughput and port access. The structure fragments across three strategic archetypes: integrated renewable energy conglomerates, specialized heavy-steel fabricators, and geotechnical engineering specialists. Dominant competitive moves include M&A to secure fabrication yard capacity and strategic partnerships to coordinate installation vessel fleets.
Among European-based heavy fabricators, Bladt Industries and Siemens Gamesa Renewable Energy occupy positions that exemplify divergent strategic paths. Bladt Industries represents the specialized fabrication archetype concentrated in North European steel structures. Siemens Gamesa Renewable Energy anchors the integrated OEM tier where turbine-foundation bundling absorbs interface risk. Vestas Wind Systems sits within the captive supply archetype, leveraging in-house engineering to sustain margin control across contract types. These three patterns illustrate how capital-intensity divergence is redrawing competitive boundaries without requiring specific claims about individual company performance or market share.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| GE Renewable Energy |
| Fugro Inc. |
| Nordex |
| Ørsted |
| Bladt Industries |
| Siemens Gamesa Renewable Energy |
| Goldwind |
| Iberdrola |
| Others |
Value Chain & Pricing Dynamics
Suction bucket foundations displacing driven piles in noise-restricted zones simultaneously relocate fabrication demand from heavy-lift ports to specialized assembly corridors and compress environmental approval premiums into structural cost economics. This substitution dynamic concentrates pricing power with yards holding DNV-certified welding programs while eroding margins for conventional monopile suppliers facing permit window constraints.
Pricing Analysis
After-market service contracts covering cathodic protection renewal and transition piece inspection drive lifetime value capture for foundation fabricators. Project-based lump-sum contracting dominates procurement, with price differentiation separating DNV-certified structures from MIIT-grade alternatives and bundling premiums for integrated foundation-tower packages. Cost compression in shallow-water monopile tiers intensifies as Chinese fabricators enter European auction rounds. Independent developers exhibit highest price sensitivity, while integrated utilities prioritize performance warranties over unit cost.
Supply Chain Analysis
Inventory cycles for 80-120 millimeter heavy plate extend 18-24 months ahead of installation windows, forcing fabricators to pre-position steel commitments before auction outcomes. Supply concentrates in Germany, Sweden, and China for rolled plate, with Japan and South Korea anchoring floating substructure assembly. Raw material dependencies center on high-strength S355+ grades, sacrificial aluminum anodes, and silicone-modified epoxy coatings. Single-source vulnerability runs through European electric arc furnace capacity under EU Green Deal carbon tracking. Distribution runs through clustered North Sea port corridors with heavy-lift quayside access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wind Energy Foundation Market tracks offshore wind capital expenditure cycles, with procurement volumes expanding as North Sea lease rounds accelerate through 2030-2035 pipelines.
For Market Incumbents: Compound fabrication yard utilization through backward integration into steel rolling partnerships that secure EU Green Deal-compliant plate supply. Defend margin position by locking multi-year installation vessel charters before newbuild jack-ups enter service. Floating foundation specialists represent the emerging competitive threat requiring pre-emptive technology licensing moves. For New Entrants and Emerging Players: Anchor in Baltic and Irish Sea markets where suction bucket specifications outpace incumbent jacket capacity. Target environmental consultancy bundling as the go-to-market angle, compressing approval timelines for noise-sensitive seabed developers. Modular component fabrication for offshore assembly presents the most penetrable white space against integrated heavy-fabrication yards. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed port infrastructure operators holding Esbjerg and Cuxhaven quayside capacity. Five-to-ten year viability hinges on floating foundation fabrication readiness for East Asian market entry. Monitor EU carbon border adjustment implementation timelines as the critical inflection signal for European steel cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Foundation-Tower Integration Packaging | Absorbs interface risk between Vestas and GE Renewable Energy turbine supply contracts. |
| Electric Arc Furnace Steel Sourcing | Secures EU Green Deal carbon scoring compliance for German and Danish auction participation. |
| Heavy-Lift Vessel Charter Lock-In | Guarantees installation scheduling against Van Oord and DEME fleet concentration bottlenecks. |
| Suction Bucket Technology Licensing | Unlocks Baltic Sea and Irish Sea markets under strict BSH and EPA noise mitigation protocols. |
| Port Infrastructure Vertical Expansion | Captures value from quayside welding through offshore load-out at Rotterdam Maasvlakte terminals. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across foundation fabricators, offshore wind developers, and installation vessel operators. Primary interviews captured procurement officers at Ørsted and RWE, fabrication yard managers in Esbjerg and Cuxhaven, and marine contractors coordinating heavy-lift schedules. Secondary validation drew from EU auction documentation, DNV certification registries, BSH permitting records, and customs data tracking heavy plate imports. Bottom-up project pipeline aggregation and top-down steel demand modeling were triangulated against capacity expansion announcements.
Across the analysis window, forecasts segment by foundation type, water depth tier, installation method, and end-user procurement structure. CAGRs were derived from project-level capital expenditure phasing and fabrication yard commissioning timelines. Modeled inputs include turbine rating escalation curves, port infrastructure utilization rates, and regulatory auction criteria weighting embedded carbon scores.
Material uncertainties — steel price volatility under carbon border adjustments, jack-up vessel delivery delays, and seabed lease award timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding DNV certification continuity and EU F-Gas Regulation coating compliance timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Turbine Blades Market