
 Floating LNG Power Plant Market | 2026-2036
Floating LNG Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Floating LNG Power Plant Market Foresight
Class-A marine-grade steel specifications is rotating procurement standards upward for hull and topside construction. Samsung Heavy Industries leverages its Geoje shipyard complex to dominate FLNG newbuild output. Wärtsilä Corporation anchors the power generation package segment with dual-fuel engine technology. MODEC, Inc. sustains its position through proprietary mooring systems for harsh-environment deployments.
A floating LNG power plant integrates liquefied natural gas storage, regasification, and power generation systems aboard a barge, vessel, or semi-submersible platform, typically employing gas turbines or combined-cycle configurations delivering 50 MW to 400 MW. These units serve remote coastal communities, industrial zones, and maritime facilities lacking pipeline infrastructure or grid interconnection. The 151-300 MW power capacity band leads order intake due to optimal economies of scale for island utility offtake. Combined cycle technology captures expanding share as efficiency thresholds tighten; permanent mooring installations dominate Southeast Asian contracts where typhoon exposure demands fixed positioning.
The International Maritime Organization enforces Tier III NOx limits through MARPOL Annex VI, compelling engine technology upgrades across the supply chain. Classification societies including DNV and Bureau Veritas certify structural integrity standards for floating power installations. South Korea's Ministry of Trade, Industry and Energy (METI-equivalent ministry) channels shipyard subsidies toward LNG-powered vessel and platform construction. Stakeholders must monitor how evolving carbon accounting rules for Scope 3 emissions reshape financing terms for floating power projects in climate-vulnerable jurisdictions.
Market Dynamics
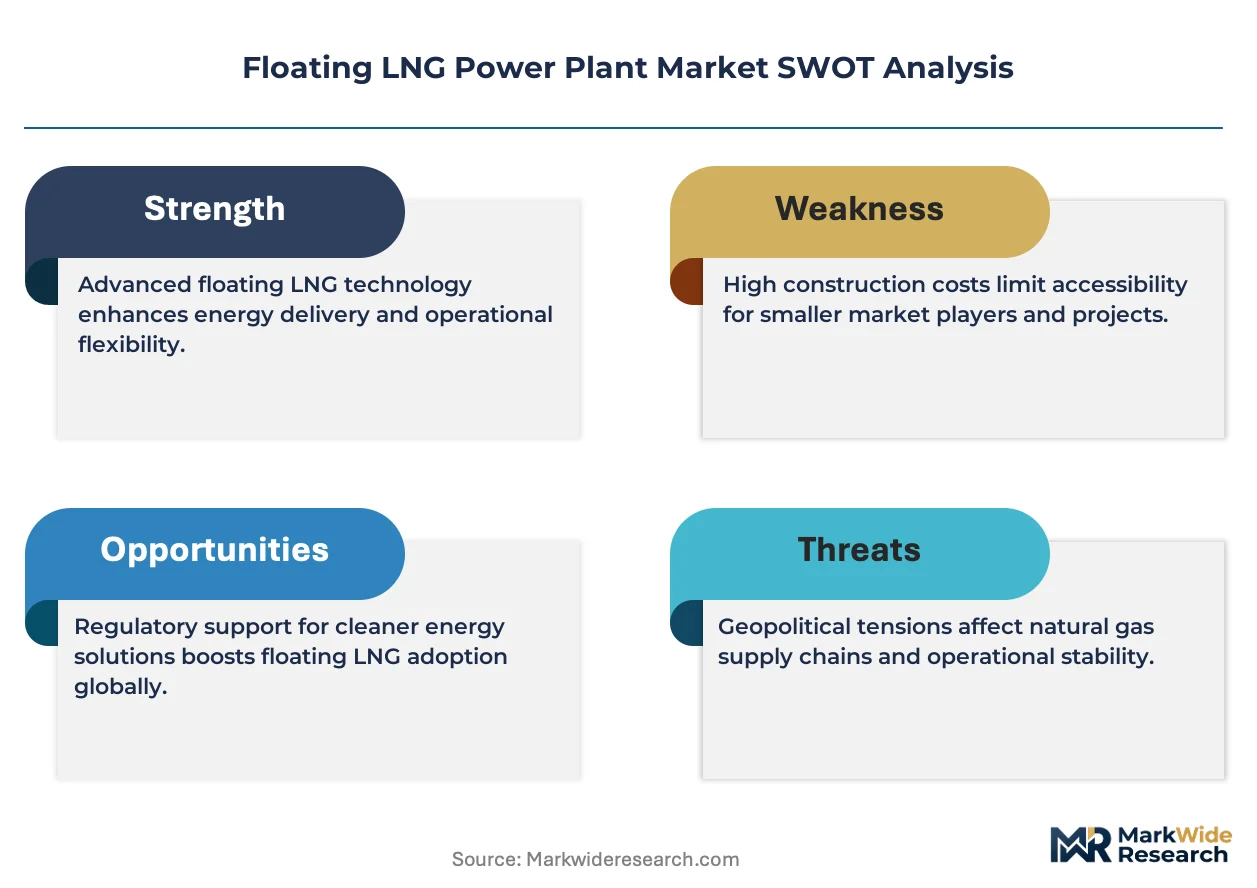
The International Maritime Organization's Tier III NOx emission limits under MARPOL Annex VI are forcing engine technology upgrades across the floating LNG power plant supply chain, compressing margins for vessel operators while accelerating dual-fuel engine adoption in newbuild specifications.
Growth Catalysts
- Island utility electrification mandates:Southeast Asian governments are channeling infrastructure budgets toward coastal power projects that bypass pipeline constraints, with Indonesia's state electricity corporation prioritizing floating LNG units for archipelago connectivity.
- IMO emission enforcement:Classification societies including DNV and Bureau Veritas are certifying stricter structural integrity standards that favor LNG over diesel marine power, redirecting procurement specifications toward cleaner fuel conversion.
- Combined-cycle efficiency gains:Gas turbine manufacturers are integrating heat recovery steam generators that push thermal efficiency above 55 percent, making mid-scale floating plants economically viable for industrial zone offtake.
Market Restraints
- Specialized steel input volatility:Class-A marine-grade steel specifications for hull and topside construction concentrate procurement among Korean and Japanese mills, exposing project budgets to nickel alloy price swings.
- Shipyard capacity concentration:FLNG newbuild output clusters at the Geoje complex in South Korea, creating bottlenecks when defense or commercial vessel orders compete for drydock slots.
- Mooring system technical limitations:Proprietary tension leg and spread mooring designs from single-source suppliers limit buyer negotiation leverage and extend engineering lead times for harsh-environment deployments.
Strategic Opportunities
- Philippines archipelago expansion:The country's Department of Energy is soliciting independent power producers for island-hopping electrification projects where submarine cable costs prove prohibitive.
- Carbon accounting regulatory tailwind:Evolving Scope 3 emission disclosure requirements under the EU Green Deal and CSRD are reshaping financing terms, creating preferential debt structures for floating LNG projects in climate-vulnerable jurisdictions.
- Digital twin convergence:Integration of real-time asset monitoring with predictive maintenance algorithms is reducing unplanned downtime, opening performance-guarantee contracting models for power capacity bands above 200 MW.
Industry Challenges
- Marine welding certification timelines:Qualified ASME Section IX welders for cryogenic LNG containment systems face 18-24 month training pipelines, constraining construction velocity at expanding shipyards.
- Legacy grid synchronization complexity:Island utilities with aging distribution infrastructure require substantial upstream investment to absorb floating plant output, delaying commercial operation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating LNG Power Plant Market |
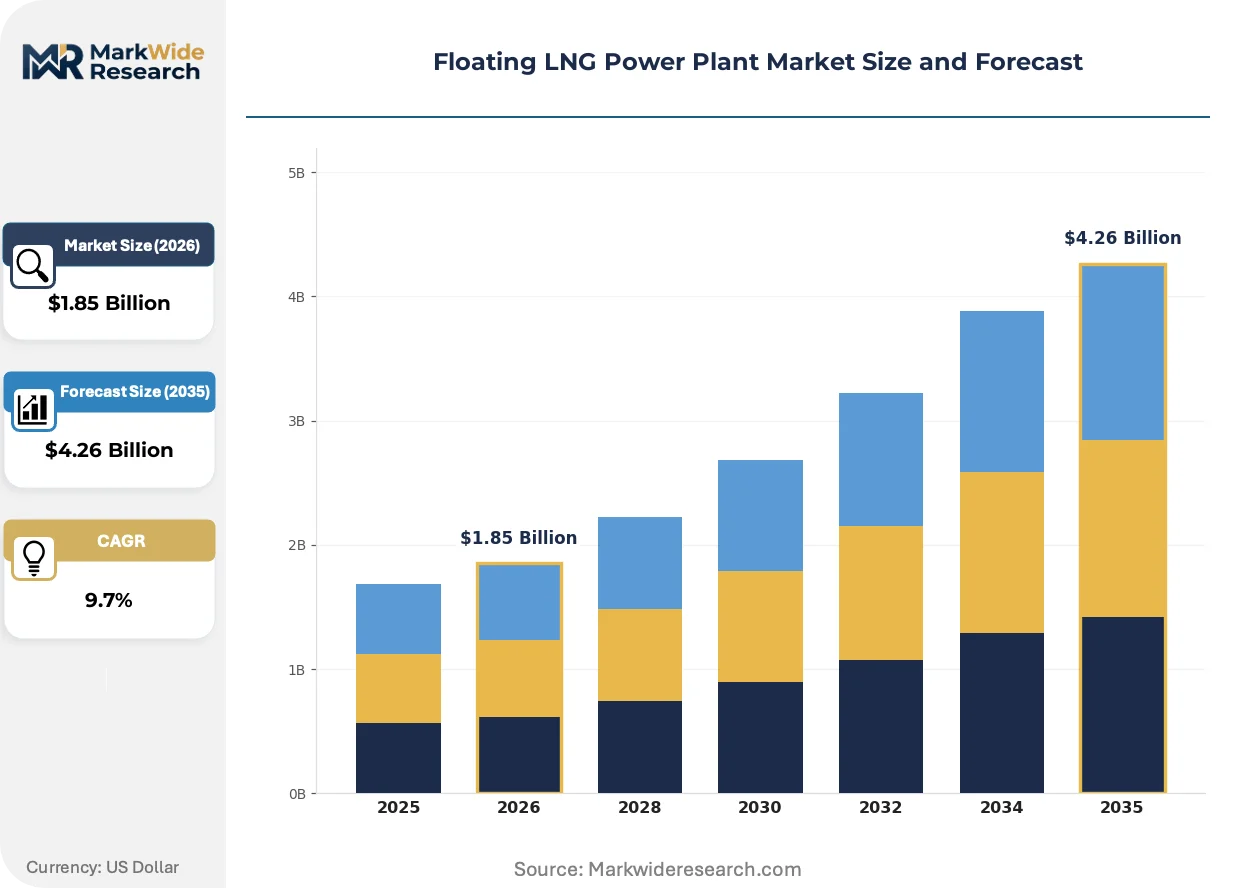
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Capacity: Below 50 MW, 50-150 MW, 151-300 MW, Above 300 MW Power Generation Technology: Gas Turbines, Steam Turbines, Combined Cycle, Reciprocating Engines End User Industry: Maritime Transport, Offshore Research, Marine Infrastructure, Island Utilities Installation Type: Permanent Mooring, Dynamic Positioning, Semi-submersible, Spar Platforms |
| Companies Covered | MODEC, Inc., Samsung Heavy Industries, Shell, SBM Offshore, Chevron, ExxonMobil, Hyundai Heavy Industries, Wärtsilä Corporation, Golar LNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating LNG Power Plant Market Shifts & Advancements
Dual-fuel engine architectures are compressing the competitive window for single-fuel marine power systems, while digital integration and modular fabrication methods are reshaping how floating LNG plants are engineered, procured, and commissioned.
Combined-cycle configurations integrating gas turbines with heat recovery steam generators are supplanting simple-cycle alternatives in orders above 150 MW capacity. Island utilities across Indonesia and Vietnam are specifying these systems for baseload power contracts where fuel efficiency directly determines tariff competitiveness. The technology is enabling project developers to bid lower levelized costs of electricity while maintaining reserve margins for typhoon-season grid stability.
The European Union's F-Gas Regulation is tightening leak detection and containment requirements for onboard refrigeration and regasification systems. Equipment suppliers must now certify fluorinated gas management protocols that add engineering complexity but reduce methane slip during cargo transfer operations. Vessel operators serving EU-flagged terminals or European development finance-backed projects are retrofitting existing fleets to comply, diverting maintenance budgets from other capital priorities.
Power purchase agreement structures are migrating from take-or-pay toward availability-based contracting with stringent uptime guarantees. Industrial zone offtakers in Vietnam and the Philippines are unbundling engineering-procurement-construction risk from long-term operations, transferring performance accountability to vessel owners. This shift concentrates credit risk among specialized floating power operators while compressing bid preparation timelines for new entrant developers.
Floating LNG Power Plant Market Segmentation
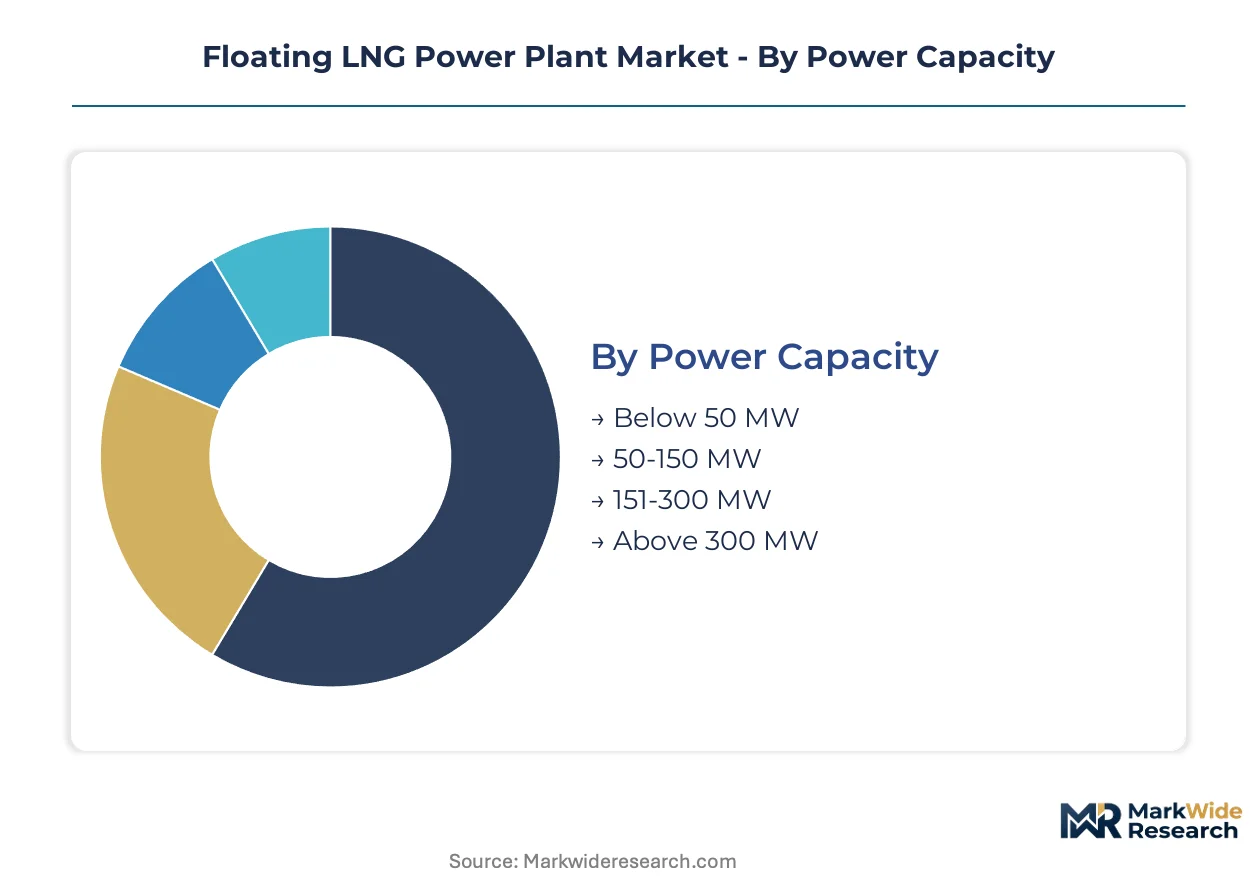
Floating LNG power plant procurement decisions cluster around four structural dimensions. Capacity bands determine unit economics, technology choices fix efficiency profiles, end-use sectors dictate mooring requirements, and installation types anchor project risk allocation.
Power Capacity:
Margin pools concentrate in the mid-capacity band where economies of scale intersect with deployability constraints for island utilities.
- Below 50 MW:Compact barge-mounted units serve remote maritime facilities and small industrial zones with limited space envelopes. Demand clusters at Philippine coastal municipalities where submarine cable extension costs exceed floating plant capital outlay.
- 50-150 MW:Modular configurations bridge harbor infrastructure and open-water deployment, attracting Vietnamese industrial zone developers seeking phased capacity expansion without pipeline commitment.
- 151-300 MW:Optimal scale for baseload island utility contracts, combining thermal efficiency with manageable mooring complexity. Indonesian state electricity procurement prioritizes this band for archipelago grid stabilization.
- Above 300 MW:Semi-submersible platforms and dedicated vessel designs serve multi-facility industrial clusters. Lead times extend due to specialized steel requirements and limited shipyard slots.
The dominant share belongs to 151-300 MW, while 50-150 MW is closing the gap fastest.
Power Generation Technology:
Technology selection pivots on thermal efficiency thresholds and fuel flexibility requirements under tightening emission protocols.
- Gas Turbines:Simple-cycle configurations dominate sub-150 MW installations for their rapid start capability and compact footprint. Offshore research facilities in Indonesian waters specify aeroderivative turbines for load-following duty cycles.
- Steam Turbines:Standalone steam systems persist in retrofitted vessel conversions where waste heat sources are captive. Newbuild orders have declined as combined-cycle alternatives achieve cost parity.
- Combined Cycle:Integrated gas turbine and heat recovery steam generator architectures push thermal efficiency past 55 percent. Vietnamese island utilities specify these systems for 20-year power purchase agreements where fuel cost directly determines tariff competitiveness.
- Reciprocating Engines:Dual-fuel medium-speed engines from Wärtsilä and MAN Energy Solutions capture sub-100 MW applications requiring operational flexibility. The technology enables rapid fuel switching between LNG and diesel for grid emergency reserve.
Combined cycle holds the dominant position, though reciprocating engines are expanding most quickly in sub-utility scale deployments.
End User Industry:
Customer archetypes diverge sharply in uptime requirements, fuel security protocols, and contract duration preferences.
- Maritime Transport:Port electrification and vessel charging infrastructure drives demand for mobile power barges. Singapore's Jurong Port and Rotterdam's Maasvlakte terminals are evaluating floating LNG units to replace shore-side diesel generation.
- Offshore Research:Scientific drilling platforms and oceanographic stations require continuous power with minimal environmental footprint. The Scripps Institution of Oceanography and Japan Agency for Marine-Earth Science specify low-noise, low-emission configurations.
- Marine Infrastructure:Desalination plants, ship repair yards, and cargo handling facilities anchor permanent mooring installations. Saudi Arabia's Red Sea coastal development projects incorporate floating power for desalination feedstock.
- Island Utilities:Archipelago grid operators in Indonesia, the Philippines, and Vietnam constitute the primary demand pool. These offtakers prioritize fuel diversity and typhoon resilience over pure thermal efficiency.
Island utilities command the dominant share, while marine infrastructure is gaining share fastest on desalination co-location trends.
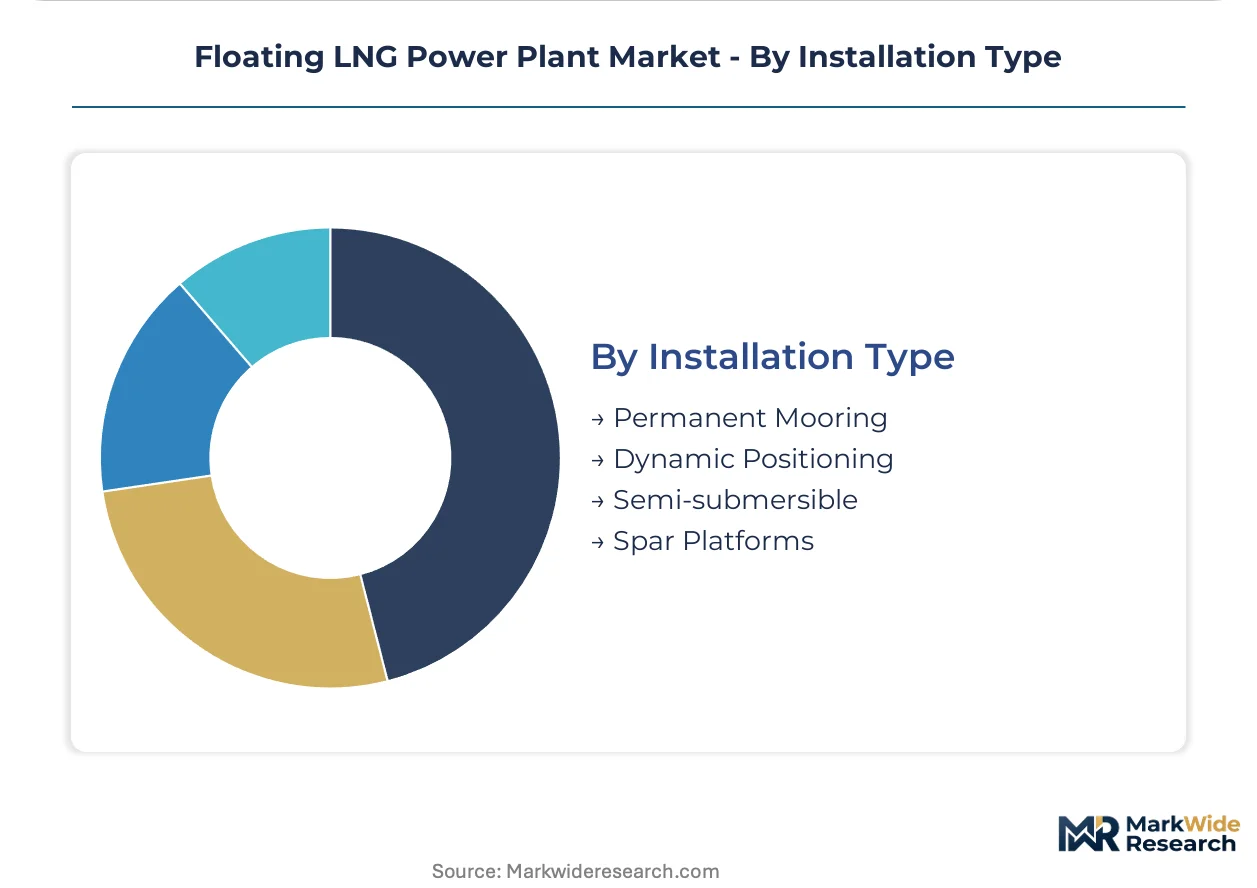
Installation Type:
Mooring system selection determines capital intensity, operational flexibility, and environmental exposure limits.
- Permanent Mooring:Spread mooring and tension leg systems fix vessels to seabed foundations for multi-decade service life. Southeast Asian typhoon corridors mandate this configuration for insurance and regulatory compliance.
- Dynamic Positioning:Thruster-based station-keeping enables rapid relocation between sites, serving offshore research and temporary industrial power needs. Fuel consumption penalties limit economic viability for baseload duty.
- Semi-submersible:Column-stabilized platforms with minimal waterplane area reduce wave-induced motion, supporting combined-cycle equipment sensitive to platform tilt. MODEC and SBM Offshore dominate this specialized fabrication segment.
- Spar Platforms:Deep-draft single-column designs anchor in water depths exceeding 500 meters, opening frontier basins off Vietnam and eastern Indonesia to floating power deployment.
Permanent mooring retains the dominant position, though semi-submersible designs are climbing the fastest on deep-water frontier access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy shipbuilding economies dominate FLNG power plant fabrication, while import-dependent island nations drive deployment demand. South Korea and Japan supply hull and topside components, but Indonesia, the Philippines, and Vietnam absorb the majority of operational units for coastal electrification.
Indonesia
Archipelago grid stabilization mandates from PLN, the state electricity corporation, prioritize floating LNG units for outer island connectivity. The country's national energy regulator, BPH Migas, oversees LNG import terminal licensing that enables floating power mooring. Procurement concentrates around the Java Sea and Sulawesi corridors where submarine cable extension costs prove prohibitive.
South Korea
The Geoje shipyard complex anchors global FLNG newbuild output through concentrated heavy-industry fabrication capacity. The Ministry of Trade, Industry and Energy channels subsidies toward LNG-powered vessel and platform construction under national shipbuilding competitiveness programs. Samsung Heavy Industries and Hyundai Heavy Industries occupy the dominant fabrication positions at this coastal industrial cluster.
Philippines
Department of Energy electrification targets for unserved island municipalities create procurement pull for mid-capacity floating units. The country's national power regulator, ERC, oversees independent power producer bidding frameworks that favor fast-track deployment over transmission infrastructure. Project development clusters around the Visayas archipelago where typhoon exposure demands permanent mooring configurations.
Vietnam
Industrial zone developers in the south-central coastal belt specify combined-cycle floating plants to bypass pipeline construction timelines. The Ministry of Industry and Trade governs power purchase agreement frameworks that enable direct offtake from floating LNG facilities. Concentrated demand emerges around the Vung Tau petroleum services corridor and emerging deep-water frontier blocks off the central coast.
Japan
Post-Fukushima grid diversification policies sustain modest floating power interest for remote island utilities and disaster-reserve applications. The Ministry of Economy, Trade and Industry (METI) administers subsidy programs for LNG infrastructure that includes barge-mounted generation. Fabrication and engineering activity concentrates at the Nagoya-Chubu industrial belt and the Kure-Hiroshima maritime cluster.
Floating LNG Power Plant Market Competitive Landscape
Concentration sits with integrated shipyard-energy conglomerates that control hull fabrication, power system integration, and long-term vessel operation. The competitive structure tiers between full-service platform developers, specialized power package suppliers, and LNG infrastructure operators. Three archetypes dominate: Korean heavy-industry fabricators with captive shipyard capacity, European engineering specialists with proprietary mooring technology, and diversified energy majors leveraging upstream LNG supply positions. Capacity reservation agreements and strategic joint ventures for specific project developments represent the dominant competitive moves, with technology licensing for dual-fuel engine systems serving as secondary differentiation.
Among Korean fabricators, Samsung Heavy Industries and Hyundai Heavy Industries occupy positions exemplifying the integrated shipyard model. MODEC, Inc. anchors the specialized engineering tier through its Tokyo-based corporate structure. Wärtsilä Corporation represents the power generation package archetype with its Finnish corporate origins. These three entities collectively illustrate how competitive positioning fragments across fabrication, engineering, and power system domains rather than consolidating vertically.
| Leading Market Players |
|---|
| MODEC, Inc. |
| Samsung Heavy Industries |
| Shell |
| SBM Offshore |
| Chevron |
| ExxonMobil |
| Hyundai Heavy Industries |
| Wärtsilä Corporation |
| Golar LNG |
| Others |
Supply & Pricing Matrix
Geoje shipyard capacity utilization above 85 percent compresses pricing leverage for vessel buyers while elevating Korean fabricator margin capture. Scale concentration at this single coastal cluster anchors price floors for hull and topside packages, forcing project developers to absorb steel input volatility through long-term offtake structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across 151-300 MW power capacity bands. Price differentiation rests on certification grade—DNV and Bureau Veritas Tier III compliance tiers command premiums over legacy MARPOL Annex VI configurations—and volume scale from repeat Indonesian utility procurement. Pricing pressure stems from nickel alloy cost swings in Class-A marine-grade steel specifications, compressing EPC contractor margins. Island utilities with PLN-style archipelago mandates exhibit lowest price sensitivity due to bypass value against submarine cable alternatives, while Vietnamese industrial zone developers face highest budget elasticity.
Supply Chain Analysis
Strategic stockpiling of nickel alloy plate and cryogenic insulation material dominates inventory strategy given 18-24 month marine welding certification pipelines. Geographic supply concentration draws from South Korea, Japan, and Finland—Korean mills feed hull fabrication, Japanese suppliers anchor mooring system components, and Finnish engineering houses source power generation packages. Raw material dependencies center on nickel-molybdenum alloy steel, LNG containment membrane systems, and dual-fuel engine crankshafts. Single-source vulnerability from MODEC-proprietary tension leg designs concentrates technical risk. Distribution runs through EPC contractor consortiums that bundle shipyard output with power system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating LNG power plant markets sustain defensive moats through regulatory entrenchment: IMO Tier III certification timelines and ASME Section IX welder scarcity create 24-month barriers that protect incumbent shipyard positions.
For Market Incumbents: Fortify captive supply positions through backward integration into nickel alloy steel distribution and cryogenic containment membrane fabrication. Samsung Heavy Industries and Hyundai Heavy Industries should expand Geoje complex capacity reservation agreements to preempt defense vessel order competition. Certification investment in Bureau Veritas ammonia-ready notations addresses emerging substitute technology threats from zero-carbon marine fuels. For New Entrants and Emerging Players: Differentiate on dynamic positioning system integration for rapid-relocation industrial power applications. The Philippines Visayas archipelago presents the most penetrable geography given ERC fast-track IPP frameworks and prohibitive submarine cable economics. Target marine infrastructure desalination co-location projects where Saudi Red Sea development finance creates first-mover anchoring opportunities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors combined-cycle power package specialists with heat recovery steam generator integration capabilities. Long-term viability hinges on Scope 3 carbon accounting rule convergence under EU Green Deal implementation. Acquisition target archetype: European engineering houses with proprietary mooring IP and established DNV certification track records. Watch for EU F-Gas Regulation enforcement intensity as inflection indicator for methane containment technology premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Agreements | Secures drydock slots at Geoje complex against defense vessel order competition. |
| Dual-Fuel Engine Technology Licensing | Wärtsilä and MAN Energy Solutions transfer IP to capture IMO Tier III compliance premiums. |
| Permanent Mooring System Certification | DNV typhoon-resistance validation unlocks Indonesian PLN archipelago procurement. |
| Carbon Accounting Compliance Program | EU CSRD-aligned disclosure frameworks attract Green Deal-linked development finance. |
| Digital Twin Platform Integration | Real-time asset monitoring enables availability-based PPA structures above 200 MW. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and classification society surveyors; and secondary validation through IEA power project databases, FERC LNG facility filings, DNV maritime advisory reports, and shipyard order books. Bottom-up triangulation aggregated individual vessel contract values and capacity specifications while top-down cross-checks applied regional electrification mandate targets from Indonesia's BPH Migas, Philippines ERC, and Vietnam's Ministry of Industry and Trade.
Across the analysis window, the forecasting framework modeled capacity band segmentation, power generation technology efficiency tiers, end-user industry mooring requirements, and installation type capital intensity. CAGRs derived from regression against historical FLNG vessel delivery schedules and announced utility procurement pipelines. Industry-specific inputs incorporated IMO MARPOL Annex VI implementation timelines and EU F-Gas Regulation leak detection compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained South Korean shipyard subsidy programs and Southeast Asian archipelago electrification budget commitments would require recalibration. Forecasts reflect assumptions on nickel alloy price stability and qualified cryogenic welder supply expansion. Revision becomes warranted when IMO carbon intensity indicator thresholds tighten beyond current Tier III NOx limits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market