
 Egypt Wind Energy Market | 2026-2036
Egypt Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Wind Energy Market Foresight
Utility-scale turbine certification standards are reorganizing supplier qualification requirements across Egypt's wind development pipeline. ENGIE leverages its operational track record at Ras Ghareb to sustain bidding credibility for upcoming rounds. Lekela Power B.V. anchors its position through exclusive development rights in the West Bakr zone. Orascom Construction PLC dominates civil and electrical infrastructure scope for most active projects.
Egypt wind energy encompasses the conversion of kinetic wind resources into grid-connected electricity through horizontal-axis turbines typically rated between 2.5 MW and 6 MW, with rotor diameters exceeding 120 meters optimized for Gulf of Suez wind regimes averaging 8-10 m/s at hub height. The technology segment splits between onshore installations commanding current capacity additions and offshore designs awaiting seabed lease frameworks. Utility-scale capacity clusters attract the deepest financing pools, while industrial end users seek captive power purchase agreements to hedge against grid tariff volatility.
Egypt's New and Renewable Energy Authority coordinates project allocation under the feed-in tariff regime supervised by the Egyptian Electricity Regulatory Agency, with environmental impact assessments mandated by the Egyptian Environmental Affairs Agency. Compliance with grid codes issued by the Egyptian Electricity Transmission Company determines interconnection sequencing and revenue dispatch priority. Stakeholders must monitor upcoming sovereign guarantee structures and currency convertibility terms before committing capital to round three allocations.
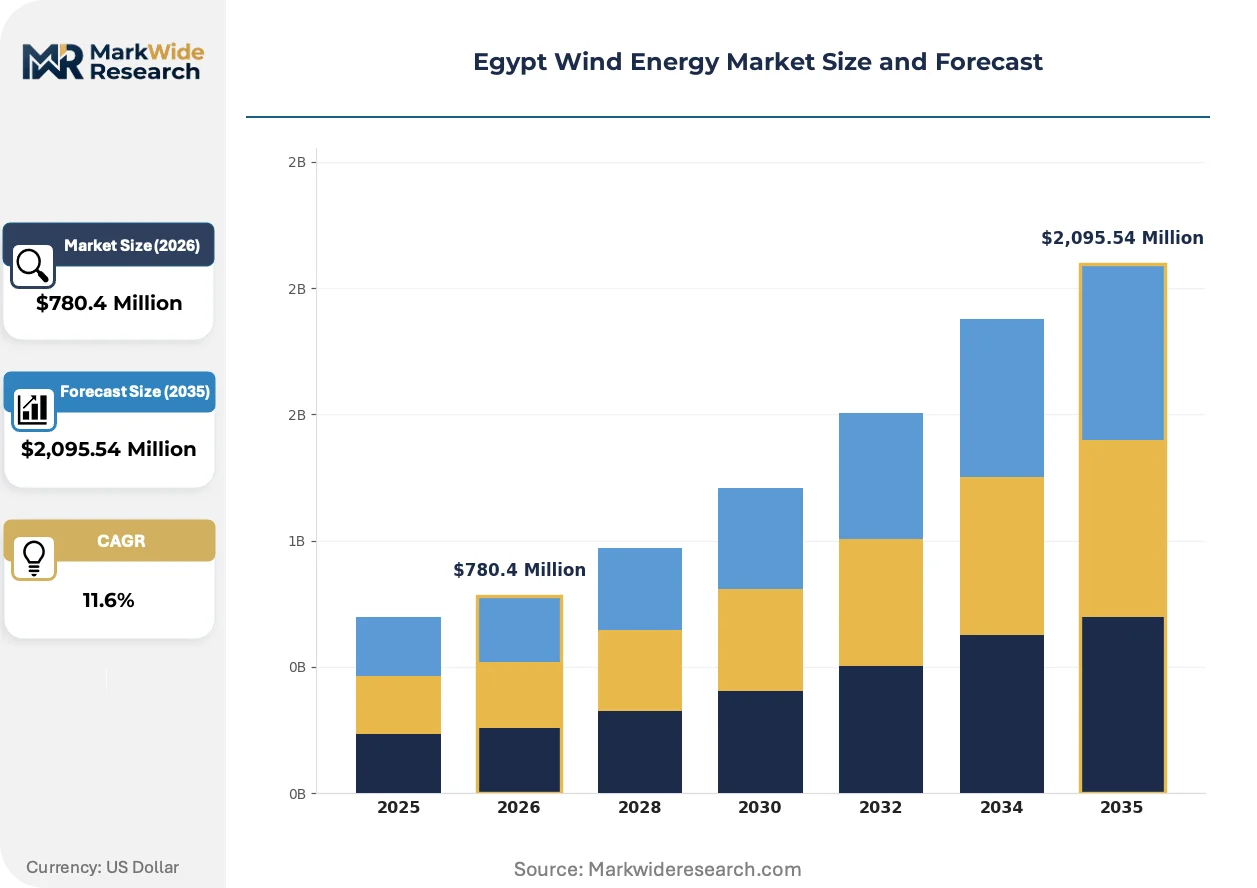
Market Dynamics
The Egyptian Electricity Transmission Company is accelerating utility-scale procurement through sovereign-backed power purchase agreements, compressing project development timelines and attracting international turbine suppliers to the Gulf of Suez corridor.
Growth Catalysts
- Feed-in Tariff Framework:The Egyptian Electricity Regulatory Agency's renewable energy tariff regime guarantees long-term revenue streams for independent power producers, de-risking capital deployment.
- Gulf of Suez Wind Regime:Consistent wind speeds averaging 8-10 m/s at hub height deliver capacity factors exceeding 45 percent, justifying larger rotor diameters and higher turbine ratings.
- Industrial Captive Demand:Energy-intensive manufacturing facilities seek direct power purchase agreements to hedge against grid tariff volatility and currency convertibility risks.
Market Restraints
- Currency Convertibility Risk:Egyptian pound volatility complicates foreign debt servicing for projects with dollar-denominated equipment procurement.
- Grid Interconnection Bottlenecks:Egyptian Electricity Transmission Company sequencing constraints delay revenue dispatch for completed installations.
- Local Content Requirements:Domestic manufacturing capacity gaps in nacelle assembly and blade production inflate project costs.
Strategic Opportunities
- West Nile Delta Zone:Unallocated development rights in this corridor offer first-mover advantages before transmission infrastructure saturation.
- Offshore Lease Frameworks:Pending seabed allocation regulations would unlock deeper water sites with superior wind resource consistency.
- Green Hydrogen Integration:Electrolyzer co-location with wind farms creates offtake certainty for surplus generation during low-demand periods.
Industry Challenges
- Turbine Certification Timelines:Egyptian Environmental Affairs Agency impact assessments and Egyptian Electricity Regulatory Agency grid code compliance extend pre-construction phases.
- Specialized Installation Vessel Scarcity:Heavy-lift crane capacity constraints for 6 MW+ nacelle erection compress construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Wind Energy Market |
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $2,095.54 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Industrial, Commercial, Residential Capacity: Small Scale, Medium Scale, Large Scale, Utility Scale Installation: Fixed, Floating, Hybrid, Others |
| Companies Covered | Orascom Construction PLC, SGS SA, ENGIE, Sumitomo Mitsui Banking Corporation, Ras Ghareb Wind Energy S.A.E., Eurus Energy Holdings Corporation, Lekela Power B.V., European Bank for Reconstruction and Development, Toyota Tsusho Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Wind Energy Market Shifts & Advancements
Turbine scaling and digitalization are compressing levelized cost trajectories while regulatory frameworks mature to accommodate merchant risk exposure. These shifts are redrawing competitive positioning across Egypt's wind development pipeline.
Rotor diameter expansion is bifurcating supplier strategies in Egypt's onshore segment. Turbines exceeding 140-meter rotors capture more energy at lower wind speeds, enabling project viability in marginal zones. International OEMs deploy these platforms at Ras Ghareb and West Bakr, while domestic developers face equipment availability constraints. The technology is bifurcating the market between premium-capture sites and secondary corridors requiring next-generation efficiency.
The Egyptian Environmental Affairs Agency is tightening cumulative impact assessment protocols for Gulf of Suez clusters. Developers must now demonstrate avian migration corridor mitigation and marine ecosystem protection in sequential project filings. Utility-scale allocations face extended review timelines, pushing sponsors toward integrated environmental management systems.
Industrial offtakers are consolidating procurement through consortium structures to achieve scale pricing. Cement, steel, and chemical manufacturers pool demand to negotiate long-term contracts directly with project developers, bypassing Egyptian Electricity Transmission Company intermediation. This concentration is most visible in the Suez Canal Economic Zone, where energy-intensive tenants seek tariff certainty.
Egypt Wind Energy Market Segmentation
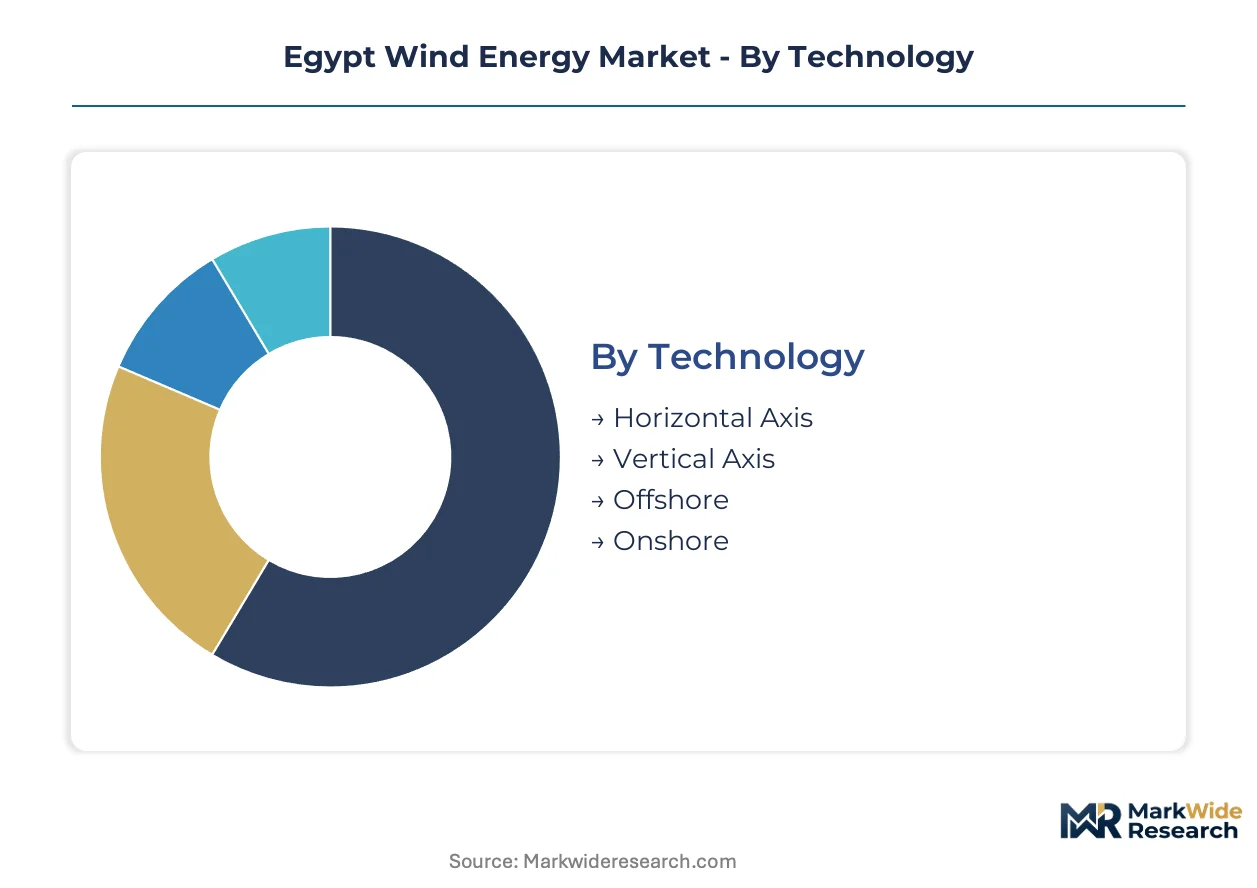
Segmentation in Egypt's wind energy market reveals how capital flows through distinct procurement channels. Utility-scale auctions channel the largest turbine volumes through sovereign-backed power purchase agreements, while industrial offtakers drive commercial-scale deployments through direct negotiations.
Technology:
Technology segments flow through divergent financing channels. Horizontal-axis platforms dominate utility-scale auctions administered by the Egyptian Electricity Transmission Company. Vertical-axis designs and emerging offshore configurations access alternative capital pools through development finance institutions and concessional lending windows.
- Horizontal Axis:These turbines convert wind kinetic energy through rotor blades mounted on a horizontal shaft, typically rated between 2.5 MW and 6 MW with rotor diameters exceeding 120 meters. Demand concentrates in the Gulf of Suez corridor where the Egyptian Electricity Regulatory Agency's feed-in tariff regime de-risks capital deployment for independent power producers. The Egyptian Environmental Affairs Agency mandates cumulative impact assessments for sequential projects in this zone.
- Onshore:Land-based installations anchor current capacity additions across Egypt's wind development pipeline. Procurement runs through the New and Renewable Energy Authority's allocation rounds, with interconnection sequencing determined by Egyptian Electricity Transmission Company grid code compliance. Industrial captive users in the Suez Canal Economic Zone seek direct power purchase agreements to hedge currency convertibility exposure.
- Vertical Axis:These designs orient rotor blades around a vertical shaft, offering omnidirectional wind capture without yaw mechanisms. Smaller-scale deployments serve remote industrial facilities and distributed commercial loads.
- Offshore:Seabed-based installations await pending lease frameworks from maritime regulators. Superior wind resource consistency at deeper water sites attracts pre-development capital from international sponsors.
By volume, horizontal-axis installations lead. By growth pace, offshore designs are expanding most quickly as regulatory frameworks mature.
End User:
End-user segments stratify by risk tolerance and contract structure. Utilities absorb sovereign-backed offtake through long-term power purchase agreements. Industrial consumers negotiate directly with developers to bypass grid tariff volatility.
- Utilities:The Egyptian Electricity Transmission Company procures capacity through competitive auctions under the feed-in tariff regime, with revenue dispatch priority tied to grid code compliance.
- Industrial:Energy-intensive manufacturing facilities—cement, steel, and chemical producers—consolidate demand through consortium structures to achieve scale pricing. Procurement concentrates in the Suez Canal Economic Zone where tenants seek tariff certainty against Egyptian pound volatility.
- Commercial:Retail and office developments pursue smaller-scale installations through net metering arrangements with distribution utilities.
- Residential:Single-family and multi-unit dwellings access distributed generation through limited rooftop programs administered by local distribution companies.
By installed capacity, utility procurement dominates. By contract innovation, industrial direct agreements are gaining share fastest.
Capacity:
Capacity tiers align with financing depth and regulatory oversight intensity. Larger installations attract multilateral development bank participation and sovereign guarantee structures.
- Utility Scale:Installations exceeding 50 MW anchor Egypt's renewable energy targets, accessing the deepest financing pools through the Egyptian Electricity Regulatory Agency's feed-in tariff rounds. The New and Renewable Energy Authority coordinates allocation sequencing.
- Large Scale:Projects between 20 MW and 50 MW serve regional grid reinforcement needs, with interconnection studies mandated by the Egyptian Electricity Transmission Company.
- Medium Scale:Capacity clusters between 5 MW and 20 MW target industrial zone load centers, qualifying for streamlined environmental review protocols.
- Small Scale:Sub-5 MW installations address captive demand from isolated commercial and agricultural operations, often financed through local banking channels without sovereign guarantee backing.
By capital deployed, utility-scale projects lead. By project count, medium-scale installations show the steepest expansion trajectory.
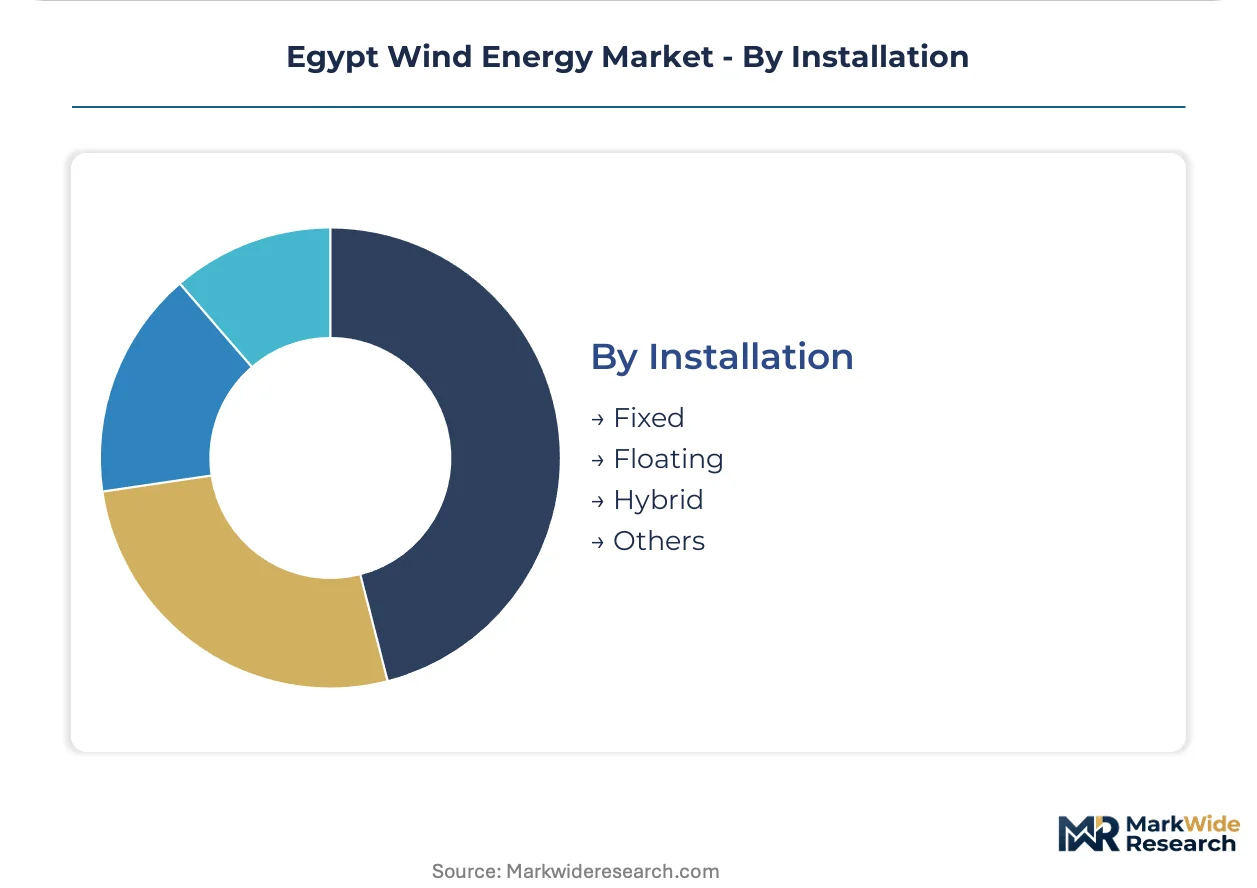
Installation:
Installation type determines supply chain requirements and construction window constraints. Fixed-bottom foundations dominate current procurement, while floating designs await technology cost reduction.
- Fixed:Concrete and steel monopile foundations anchor turbines to seabed or terrestrial bedrock, requiring heavy-lift crane capacity that constrains construction scheduling in the Gulf of Suez.
- Hybrid:Configurations combining wind generation with solar photovoltaic or battery storage optimize capacity factor and grid stability, attracting interest from industrial offtakers seeking round-the-clock renewable supply.
- Floating:Mooring-based platforms enable deployment at water depths exceeding 60 meters, pending seabed lease regulations from maritime authorities.
- Others:Emerging foundation concepts including tension-leg platforms and gravity-base structures remain in pilot phases without commercial scale deployment.
By current deployment, fixed installations dominate. By technology maturation, hybrid configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind development concentrates along Egypt's Gulf of Suez corridor, where transmission infrastructure and resource quality align. The New and Renewable Energy Authority coordinates allocation sequencing across four distinct development zones.
Gulf of Suez
The corridor anchors Egypt's utility-scale pipeline with consistent wind speeds exceeding 8 m/s at hub height. The Egyptian Electricity Regulatory Agency's feed-in tariff regime guarantees long-term revenue streams for independent power producers. Ras Ghareb hosts operational capacity from international developers, with grid interconnection managed by the Egyptian Electricity Transmission Company.
West Bakr Zone
Unallocated development rights in this corridor attract first-mover capital ahead of transmission saturation. The New and Renewable Energy Authority designates parcels through competitive auction rounds. Lekela Power B.V. holds exclusive development rights, with civil infrastructure scope awarded to regional construction specialists.
West Nile Delta
Emerging wind corridors in this zone offer lower capacity factors but reduced land competition. The Egyptian Environmental Affairs Agency mandates cumulative impact assessments for sequential project filings. Industrial offtakers in nearby manufacturing clusters seek direct power purchase agreements to hedge currency exposure.
Suez Canal Economic Zone
Energy-intensive tenants consolidate demand through consortium procurement structures. Cement, steel, and chemical manufacturers pool volume to negotiate long-term contracts directly with developers. The zone's special economic status streamlines customs clearance for imported turbine components.
Egypt Wind Energy Market Competitive Landscape
Concentration sits with integrated developers holding sovereign-backed power purchase agreements. The market structures around three tiers: international utilities with operational track records, regional construction conglomerates controlling civil scope, and development finance institutions providing construction debt. Strategic moves center on securing exclusive development rights and consolidating engineering-procurement-construction capabilities.
Among utility-scale developers, ENGIE leverages its Ras Ghareb operational history to sustain bidding credibility for upcoming allocation rounds. Lekela Power B.V. anchors its position through exclusive West Bakr zone rights. Orascom Construction PLC exemplifies the regional construction archetype, dominating civil and electrical infrastructure scope across most active projects in the pipeline.
| Leading Market Players |
|---|
| Orascom Construction PLC |
| SGS SA |
| ENGIE |
| Sumitomo Mitsui Banking Corporation |
| Ras Ghareb Wind Energy S.A.E. |
| Eurus Energy Holdings Corporation |
| Lekela Power B.V. |
| European Bank for Reconstruction and Development |
| Toyota Tsusho Corporation |
| Others |
Supply & Pricing Matrix
Scale economies at Ras Ghareb and West Bakr compress unit costs for 6 MW turbine platforms while concentrating procurement leverage among three international OEMs. This supply concentration reinforces price floors for Egyptian developers facing currency convertibility constraints on dollar-denominated equipment.
Pricing Analysis
The Egyptian Electricity Regulatory Agency's feed-in tariff regime dictates the pricing tier structure across Egypt's wind development pipeline. Project-based long-term offtake agreements dominate, with price differentiation driven by turbine certification grade and sovereign guarantee backing. Pricing pressure stems from Egyptian pound volatility against dollar procurement costs, squeezing margins for developers without hard currency hedging. Industrial captive buyers in the Suez Canal Economic Zone exhibit highest price sensitivity due to tariff certainty requirements, while utility-scale IPPs with sovereign PPA backing show lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of nacelle components precedes construction windows given heavy-lift crane scarcity in the Gulf of Suez. Supply concentrates in Denmark, Germany, and Spain for turbine assembly, with blade production drawing from Turkey and domestic Egyptian facilities. Rare earth magnet dependencies from China and steel tower sourcing from regional mills create single-source vulnerability. Distribution runs through EPC contractors consolidating civil, electrical, and turbine installation scope.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as industrial offtaker consortiums bypass Egyptian Electricity Transmission Company intermediation, creating niche openings for mid-scale developers with direct PPA structuring capabilities.
For Market Incumbents: Compound operational track records at Ras Ghareb and West Bakr into exclusive development rights for West Nile Delta allocations. Secure backward integration into blade manufacturing through joint ventures with Turkish suppliers to offset local content requirement costs. Currency hedging infrastructure represents the critical lever against pound volatility eroding dollar-denominated equipment margins. For New Entrants and Emerging Players: Service-layer gaps in environmental impact assessment and grid code compliance consulting create entry points for specialized advisory firms. Target medium-scale industrial captive projects between 5 MW and 20 MW in the Suez Canal Economic Zone where incumbent saturation remains lowest. Lead with integrated environmental management system offerings to compress pre-construction timelines for sequential Gulf of Suez filings. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with secured seabed lease options ahead of offshore regulatory finalization. Long-term viability hinges on electrolyzer co-location strategies for green hydrogen offtake. Watch Egyptian Environmental Affairs Agency cumulative impact assessment protocol tightening as the inflection signal for environmental compliance capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands utility-scale presence in West Nile Delta ahead of transmission saturation. |
| Power Purchase Agreement | Locks long-term revenue streams under Egyptian Electricity Regulatory Agency tariff guarantees. |
| Technology Licensing | Transfers 140-meter rotor platforms to domestic assembly partners for local content compliance. |
| Vertical Integration into Storage | Captures hybrid configuration demand from industrial offtakers seeking round-the-clock supply. |
| Green Certification Program | Accelerates Egyptian Environmental Affairs Agency approvals through pre-validated impact assessments. |
Research Methodology
The analysis maps horizontal-axis onshore, vertical-axis distributed, and offshore pending segments, each validated through IPP project developers, EPC contractors, and Egyptian Electricity Transmission Company planning officers. Primary interviews with turbine OEM procurement leads, New and Renewable Energy Authority allocation administrators, and Suez Canal Economic Zone facility managers combined with secondary validation against EIA country data, IEA renewable market reports, Egyptian Electricity Regulatory Agency tariff filings, and multilateral development bank project databases. Bottom-up project pipeline aggregation triangulates against top-down macroeconomic capacity targets.
Consistency checks validated volume and value outputs against Egyptian sovereign renewable energy targets and Gulf of Suez transmission interconnection schedules. Segmentation dimensions span technology type, end-user procurement channel, capacity tier, and installation foundation configuration across the projection horizon. CAGRs derive from project commissioning timelines, tariff escalation clauses, and equipment cost curves. Forecast inputs incorporate currency convertibility risk premiums and grid code compliance duration assumptions.
Forecasts assume regulatory continuity in Egyptian Electricity Regulatory Agency feed-in tariff regimes and New and Renewable Energy Authority allocation sequencing; material policy shifts would require re-modeling. Revision becomes warranted when Egyptian pound volatility or seabed lease framework delays cross threshold levels disrupting project finance viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
North America Large Wind Turbine Market