
 Wind Turbine Brakes Market | 2026-2036
Wind Turbine Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Brakes Market Outlook
OEM-direct procurement channels is rewriting how brake suppliers reach wind turbine manufacturers, compressing distributor margins and favoring technical partnership models. Dellner Bubenzer leverages its integrated service footprint across European offshore clusters to sustain long-term supply agreements. Kendrion N.V. anchors its position through captive R&D in electromechanical brake architectures. Altra Industrial Motion Corp. competes on manufacturing scale across North American onshore supply chains.
Wind turbine brakes are friction-based or electromechanical safety systems designed to arrest rotor rotation during emergency stops, maintenance lockouts, or grid-disconnect events, typically rated for torque capacities exceeding 20 kNm and operating temperatures from -40°C to +80°C. Their primary purpose is protecting drivetrain components and enabling controlled shutdown per IEC 61400-4 gearbox standards. Disc brake configurations dominate new turbine platforms due to superior heat dissipation and pad replacement accessibility, while hydraulic brake system types retain share in retrofits where infrastructure reuse limits conversion economics. Electric brakes represent the fastest-expanding segment as pitch-independent architectures eliminate hydraulic fluid leakage risks in offshore environments.
FAA obstruction lighting coordination, EPA wetland construction permitting, and IEC 61400-1 structural design standards collectively shape brake system certification requirements and market access timelines across jurisdictions. The EU F-Gas Regulation accelerates hydraulic system displacement by restricting fluorinated greenhouse gas use in offshore service equipment. Stakeholders must monitor brake-by-wire technology maturation and evolving grid-code ride-through specifications as turbine ratings exceed 15 MW.
Market Dynamics
Electromechanical brake architectures are displacing hydraulic systems across offshore installations, driven by EU F-Gas Regulation restrictions on fluorinated greenhouse gases and turbine OEM demands for pitch-independent safety systems.
Growth Catalysts
- EU F-Gas Regulation:Mandates restricting fluorinated greenhouse gas use in offshore service equipment accelerate hydraulic brake displacement across North Sea installations.
- 15 MW+ turbine scale:Larger rotor diameters and higher torque loads necessitate advanced brake systems with capacities exceeding 50 kNm.
- Repowering cycles:Germany, China, and the United States cluster replacement demand as first-generation wind farms reach end-of-design-life.
Market Restraints
- Rare earth magnet supply:Electromechanical brake production depends on neodymium-dysprosium supply chains concentrated in Chinese processing facilities.
- Offshore certification timelines:IEC 61400-4 gearbox standard compliance extends brake system qualification periods by 18-24 months.
- Copper price volatility:Electromechanical actuator windings expose manufacturers to London Metal Exchange copper futures fluctuations.
Strategic Opportunities
- Floating offshore wind:Norway, Portugal, and Japan pilot projects require brake systems adapted to platform motion dynamics.
- Digital brake monitoring:IoT-enabled condition monitoring converges with predictive maintenance platforms to create service revenue streams.
- US Inflation Reduction Act:Domestic content bonuses for offshore wind components incentivize localized brake manufacturing capacity.
Industry Challenges
- Electromechanical engineering talent:Brake system manufacturers compete with automotive and aerospace sectors for motor control specialists.
- Legacy hydraulic infrastructure:Retrofit economics limit conversion rates where existing offshore service vessels and port facilities maintain hydraulic tool compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Brakes Market |
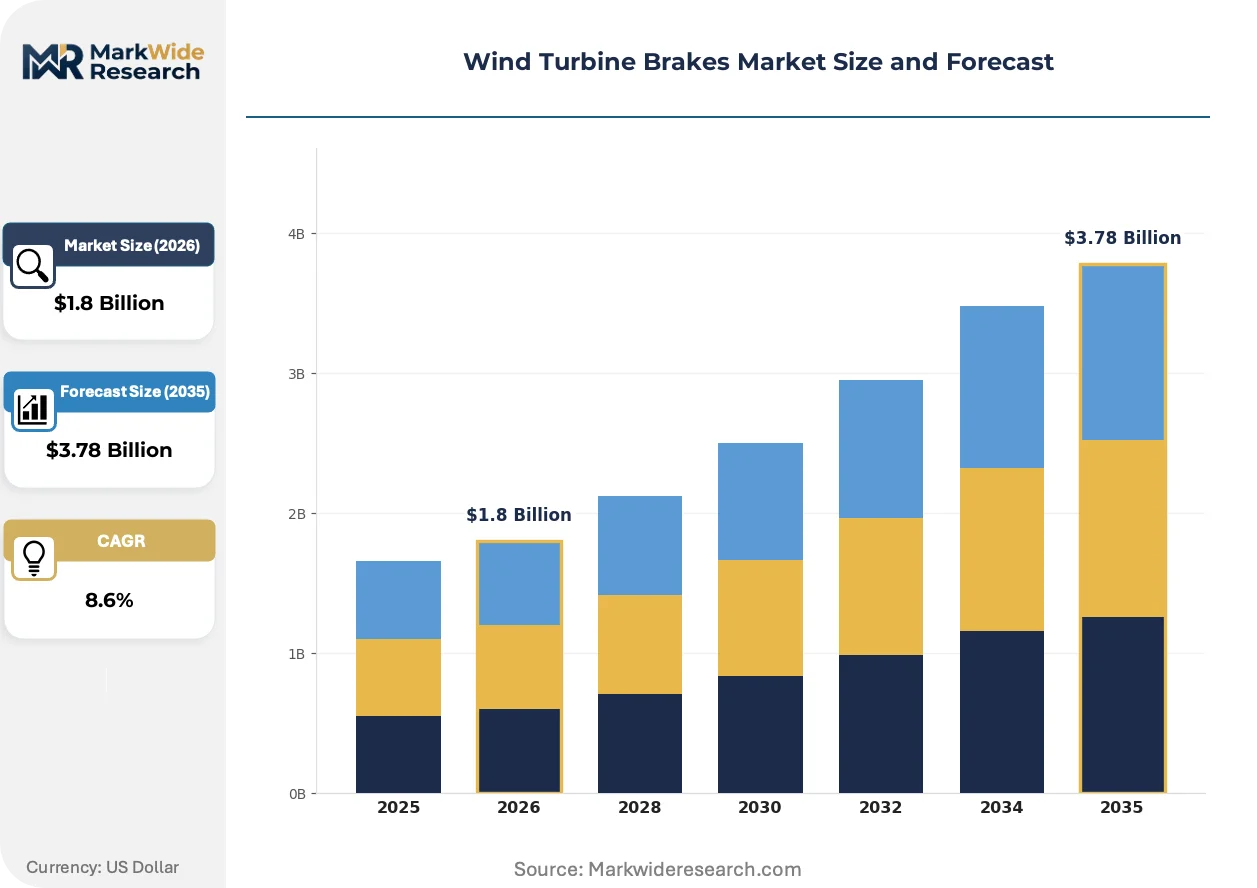
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Disc Brakes, Drum Brakes, Hydraulic Brakes, Electric Brakes Brake System Type: Active Braking, Passive Braking, Emergency Braking, Dynamic Braking End User: Wind Farm Operators, OEMs, Maintenance Providers, Utilities Deployment Model: Onshore, Offshore, Hybrid, Retrofit |
| Companies Covered | Kendrion N.V., Industrial Clutch Parts (ICP Wind), Dellner Bubenzer, ANTEC Group, Hydratech Industries, mayr power transmission, Hindon LLC, Siber Siegerland Bremsen GmbH, Altra Industrial Motion Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Brakes Market Strategic Shifts
Brake system architectures are fragmenting along offshore-versus-onshore fault lines, with digitalization and electrification commanding R&D investment priority over incremental hydraulic improvements.
Electromechanical disc brakes with integrated torque sensors are virtualizing traditional hydraulic control circuits. Offshore wind farm operators in the North Sea and Baltic Sea are specifying all-electric pitch and brake systems to eliminate hydraulic fluid leakage risks in marine environments. This shift is virtualizing the role of hydraulic power units and dedicated fluid conditioning equipment, compressing supplier margins in legacy pump and valve segments.
EU F-Gas Regulation amendments tighten phase-down schedules for hydrofluorocarbon use in industrial equipment. Brake system manufacturers must redesign hydraulic actuators to use approved alternatives or abandon fluid power entirely. Offshore turbine OEMs are responding by deleting hydraulic circuits from nacelle specifications, favoring electromechanical architectures in 12 MW and larger platforms.
Direct procurement contracts between brake suppliers and turbine OEMs are consolidating channel power. Distributor networks that historically stocked hydraulic components face volume erosion as technical partnership models embed brake suppliers into early-stage turbine design cycles. Germany and Denmark exhibit the most compressed distributor roles, with OEM engineering teams co-developing brake specifications alongside specialized suppliers.
Wind Turbine Brakes Market Segmentation
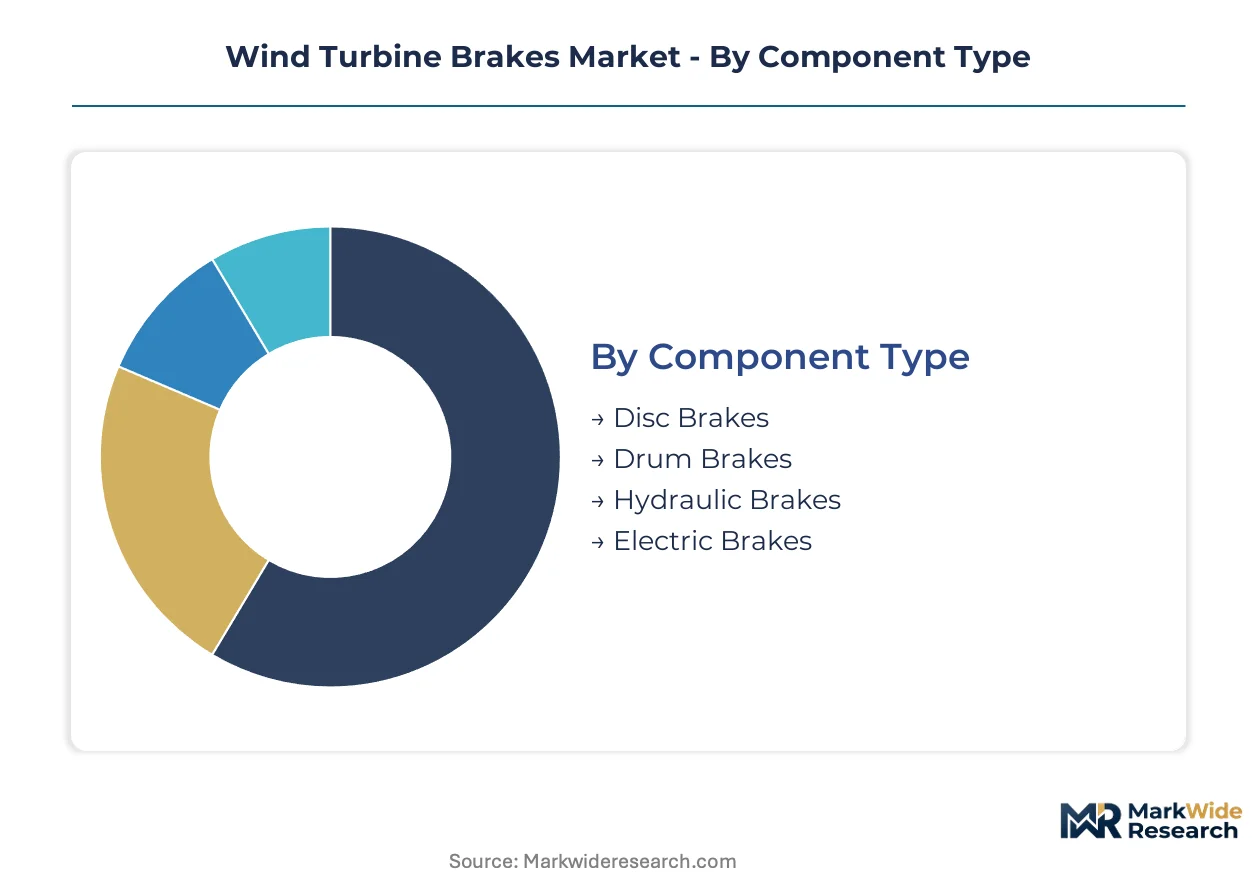
Wind turbine brake architectures fragment across torque requirements, environmental exposure, and turbine OEM integration depth. Component selection directly determines maintenance intervals, certification pathways, and lifecycle cost structures for operators managing multi-gigawatt portfolios.
Component Type:
Brake component selection spans friction-based mechanical systems through fully electrified architectures, with each technology imposing distinct supply chain and service footprints.
- Disc Brakes:Multi-piston caliper configurations with sintered or organic friction pads dominate new turbine platforms above 5 MW. Heat dissipation advantages and field-replaceable pad designs concentrate demand in German and Chinese offshore clusters where accessibility constraints amplify maintenance economics.
- Electric Brakes:Electromechanical actuators with integrated motor control eliminate hydraulic infrastructure entirely. EU F-Gas Regulation compliance requirements and pitch-independent safety architectures drive specification across 12 MW+ platforms in the North Sea, though rare earth magnet supply chains create procurement vulnerability.
- Drum Brakes:Enclosed shoe-and-drum configurations persist in legacy onshore turbines below 2 MW where retrofit economics favor component reuse.
- Hydraulic Brakes:Fluid-power systems with accumulator-backed pressure circuits retain installed base in older offshore fleets where service vessel tooling compatibility slows conversion timelines.
The dominant share belongs to disc brakes, while electric brakes are closing the gap fastest.
Brake System Type:
Functional classification separates routine operational braking from catastrophic event protection, with regulatory standards dictating redundancy requirements.
- Active Braking:Computer-controlled torque modulation for normal shutdown sequences and grid-code compliance. Demand concentrates in utility-scale projects where FERC ride-through specifications and European grid codes mandate precise rotor deceleration curves.
- Emergency Braking:Fail-safe systems triggered by overspeed, vibration, or grid disconnect events. Offshore installations in the Baltic Sea and US Atlantic coast specify redundant emergency circuits per IEC 61400-1 structural safety requirements.
- Passive Braking:Spring-applied, pressure-released configurations that engage automatically upon system failure. Cost-sensitive onshore deployments in Texas and Iowa favor passive architectures for their independence from control system integrity.
- Dynamic Braking:Generator-side electrical resistance braking that supplements mechanical systems. Grid-stabilization requirements in Germany and Denmark drive dynamic brake integration for frequency response services.
Emergency braking commands the largest specification volume, yet active braking is gaining share fastest as grid-code sophistication advances.
End User:
Procurement authority has shifted toward turbine OEMs and large fleet operators, compressing traditional distributor and maintenance provider roles.
- OEMs:Vestas, Siemens Gamesa, and Goldwind specify brakes during nacelle design, embedding suppliers in multi-year framework agreements. Direct technical partnerships have displaced arm's-length component purchasing across European and Chinese supply chains.
- Wind Farm Operators:Orsted, NextEra, and Enel Green Power influence brake selection through long-term service contracts and repowering procurement. Fleet standardization drives volume consolidation toward electromechanical platforms.
- Maintenance Providers:Independent service companies source replacement pads and caliper assemblies for out-of-warranty turbines. Margin compression in hydraulic component segments limits growth in this channel.
- Utilities:Vertically integrated power companies with captive wind assets specify brakes through centralized engineering procurement.
OEMs retain procurement dominance, though operator direct sourcing is expanding fastest as asset ownership concentrates.
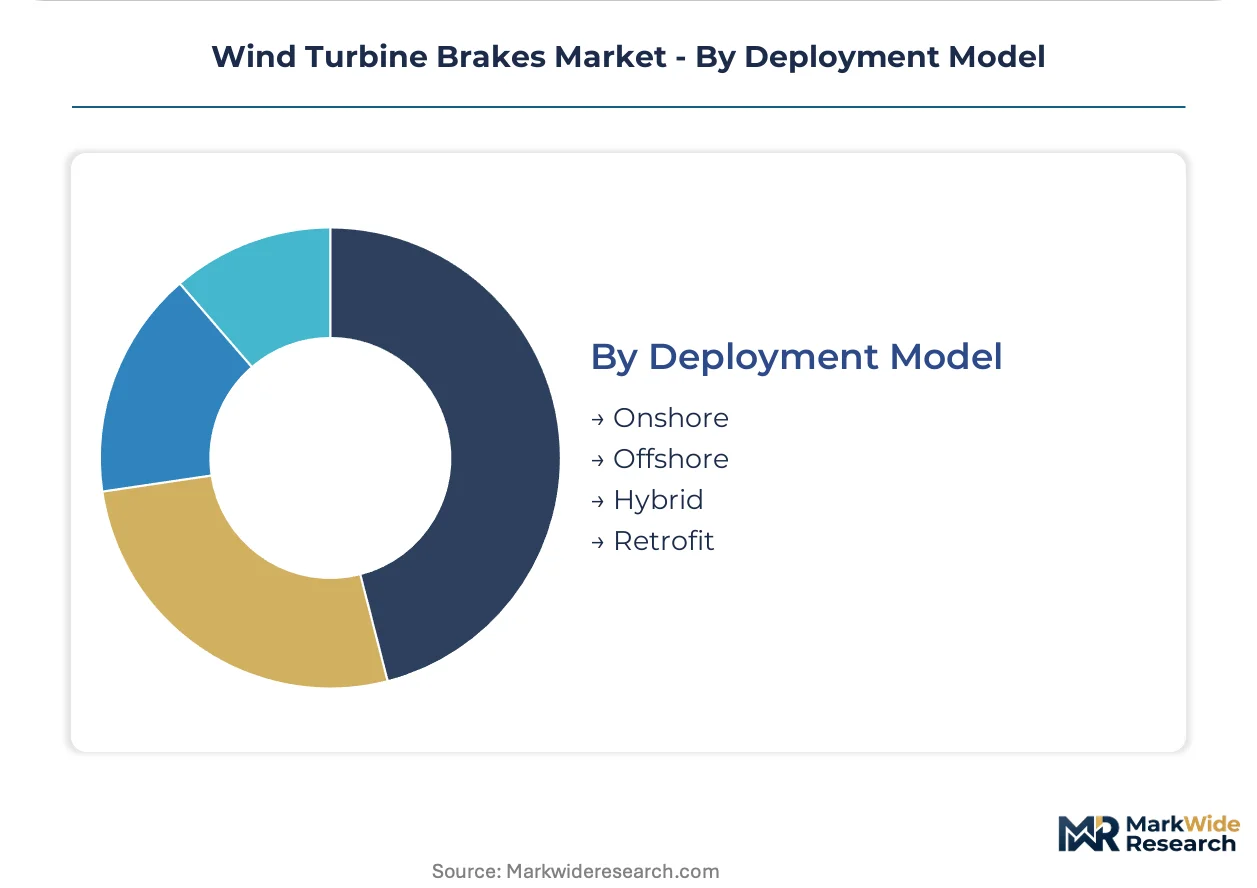
Deployment Model:
Environmental exposure and foundation type impose divergent brake performance specifications, with marine corrosion and platform motion creating distinct engineering challenges.
- Offshore:Fixed-bottom and floating installations demand sealed electromechanical architectures rated for salt spray, humidity cycling, and limited accessibility. Norwegian floating pilot projects and UK Round 4 developments specify brakes with platform-motion compensation capabilities.
- Onshore:Land-based turbines across the US Great Plains and Chinese northern provinces prioritize cost efficiency and dust ingress protection over marine-grade sealing.
- Retrofit:End-of-design-life turbine replacements in Germany's first-generation wind regions and California's Altamont Pass create demand for brake system upgrades compatible with existing tower and foundation infrastructure.
- Hybrid:Co-located wind-storage or wind-solar configurations with shared grid connection infrastructure.
Offshore deployments absorb the highest brake system value per MW, while retrofit activity is accelerating fastest as early wind farms reach repowering thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cuxhaven offshore port infrastructure underwrites Germany's commanding position in wind turbine brake demand, while China's Jiangsu coastal manufacturing corridor and the US Atlantic seaboard vessel staging network anchor the other two demand poles.
Germany
North Sea offshore clusters at Bremerhaven and Cuxhaven drive specification of electromechanical brake systems for 15 MW+ turbines. The EU F-Gas Regulation accelerates hydraulic displacement across German waters. Siemens Gamesa and Vestas engineering teams in Hamburg co-develop brake architectures with specialized suppliers.
China
Jiangsu and Guangdong province offshore installations concentrate demand for high-torque brake systems. The country's dual carbon goals mandate domestic content ratios for wind components. Goldwind and Envision Energy procurement in Beijing and Shanghai consolidate supplier relationships through multi-year framework agreements.
United States
Atlantic coast vessel staging at New Bedford and Port of Providence supports offshore brake deployment. The Inflation Reduction Act domestic content bonuses incentivize localized brake manufacturing capacity. Orsted and Vineyard Wind projects off Massachusetts and New York specify marine-grade electromechanical architectures.
United Kingdom
Dogger Bank and Hornsea offshore zones absorb premium brake system value per MW. The Contracts for Difference auction mechanism underwrites project finance for 12 MW+ turbine platforms. Scottish floating wind pilots at Kincardine require brake systems with platform-motion compensation capabilities.
Denmark
Baltic Sea installations and Esbjerg port infrastructure anchor Nordic offshore brake demand. The Danish Energy Agency grid-code specifications mandate precise rotor deceleration curves. Vestas headquarters in Aarhus embeds brake suppliers into nacelle design cycles from project conception.
Wind Turbine Brakes Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: integrated European brake specialists with offshore service footprints, North American industrial conglomerates with manufacturing scale advantages, and German engineering houses with captive R&D in electromechanical architectures. Competitive positioning hardens through direct OEM technical partnerships and multi-year framework agreements that displace traditional distributor channels. M&A activity concentrates on electromechanical capability acquisition, while capacity expansion targets US Gulf Coast and Chinese Yangtze Delta manufacturing zones.
Within the integrated European tier, Dellner Bubenzer and Kendrion N.V. represent the archetype of suppliers embedding into early-stage turbine design cycles through long-term supply agreements. Altra Industrial Motion Corp. anchors the North American scale-driven segment, competing on manufacturing throughput across onshore supply chains. These three exemplify the strategic divergence between technical partnership models and volume-based procurement channels.
| Leading Market Players |
|---|
| Kendrion N.V. |
| Industrial Clutch Parts (ICP Wind) |
| Dellner Bubenzer |
| ANTEC Group |
| Hydratech Industries |
| mayr power transmission |
| Hindon LLC |
| Siber Siegerland Bremsen GmbH |
| Altra Industrial Motion Corp. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese rare earth magnet processing is compressing margins for electromechanical brake actuators while simultaneously granting procurement leverage to turbine OEMs consolidating supplier panels across the North Sea and US Atlantic coast.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies brake system procurement, with marine-grade electromechanical architectures commanding certification premiums against hydraulic retrofits and onshore disc brake configurations. Price differentiation hinges on IEC 61400-4 compliance tier and volume scale in multi-year framework agreements. Pricing pressure stems from OEM-direct procurement compressing distributor margins. Onshore wind farm operators exhibit highest price sensitivity, while offshore developers prioritize reliability over unit cost.
Supply Chain Analysis
Export control regimes restricting rare earth processing technology flows have concentrated neodymium-dysprosium supply in Chinese refining facilities. Brake actuator manufacturing draws from German engineering houses, Chinese magnet processors, and North American copper winding suppliers. Single-source vulnerability in rare earth magnet supply chains threatens production continuity. Distribution runs through direct technical partnerships between brake specialists and turbine OEMs, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical motor control engineering talent scarcity is constraining brake system innovation pipelines, with turbine OEMs and automotive electrification programs competing for identical skill sets across European and North American labor markets.
For Market Incumbents: Harden competitive moats through captive R&D investment in platform-motion compensation algorithms for floating offshore applications. Deepen backward integration into rare earth magnet supply through offtake agreements with Australian and Canadian mining ventures. Prioritize certification pre-positioning against evolving IEC 61400 amendments before qualification timelines extend further.
For New Entrants and Emerging Players: US Gulf Coast port infrastructure underpenetration by established brake suppliers creates white-space opportunity for localized electromechanical assembly capacity serving Vineyard Wind and Revolution Wind developments. Target floating offshore wind pilot programs in Portugal and Japan where platform-motion dynamics demand novel brake architectures. Pursue joint development agreements with emerging turbine OEMs outside Vestas-Siemens Gamesa-Goldwind triopoly.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical brake manufacturing as rare earth magnet stockpiling and copper hedging programs tie up working capital. Long-term viability favors suppliers with demonstrated IEC 61400-4 qualification track records and embedded OEM relationships. Monitor F-Gas Regulation amendment timelines as inflection indicator for hydraulic displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Architecture Transition | Eliminates hydraulic fluid leakage risks in North Sea marine environments per EU F-Gas mandates. |
| Rare Earth Magnet Supply Agreement | Secures neodymium-dysprosium flows from Australian miners to de-risk Chinese processing concentration. |
| Platform-Motion Compensation R&D | Enables brake system qualification for Kincardine and Hywind floating offshore pilot projects. |
| US Gulf Coast Manufacturing Buildout | Captures Inflation Reduction Act domestic content bonuses for Orsted and Vineyard Wind supply chains. |
| Digital Condition Monitoring Integration | Converges IoT brake sensors with predictive maintenance platforms serving Enel Green Power fleets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of turbine OEM technical specifications, FERC interconnection filings, and EU offshore wind auction documentation. Primary interviews engaged brake system engineering directors, wind farm asset managers at Orsted and NextEra, and procurement leads at Vestas and Goldwind. Secondary validation drew from IEC 61400 standard drafts, EIA generation capacity databases, and customs trade records. Bottom-up unit economics triangulate against top-down market sizing across component type and deployment model segments.
Forecast inputs span installed capacity pipelines, repowering cycle timing, and regulatory phase-in schedules across the analysis window. Segmentation modeling incorporates brake system architecture, turbine rating tier, and environmental exposure classification. CAGRs derive from polynomial trend fitting against historical deployment data. Industry-specific inputs include F-Gas Regulation compliance deadlines and floating offshore wind demonstration project announcements.
Practitioners should monitor rare earth export license restrictions and IEC 61400-4 amendment publication for early signals of supply constraint or qualification timeline extension. Forecasts reflect assumptions regarding electromechanical displacement rates and OEM procurement consolidation trajectories. Material shifts in Chinese magnet processing policy or North Atlantic offshore wind permitting velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Europe Small Wind Turbine Market