
 Floating Wind Power Market | 2026-2036
Floating Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Wind Power Market Intelligence
The capital investment divergence between developing proprietary foundation technologies and licensing proven designs is rotating the competitive landscape for project developers and technology providers. Equinor ASA pioneers full-scale project development, integrating various technologies to de-risk its investments. Principle Power Inc. specializes in its WindFloat semisubmersible foundation, licensing its intellectual property to a broad base of developers. GE Vernova competes by providing high-capacity turbines specifically optimized for the unique dynamic loads of floating platforms.
Floating wind power involves generating electricity from turbines installed on buoyant substructures moored in water depths exceeding 60 meters, far beyond the reach of fixed-bottom towers. This approach unlocks vast, high-quality wind resources in deep-water areas previously inaccessible for utility-scale energy generation. Semisubmersible platforms are gaining significant traction over spar-buoy designs due to superior stability and simpler port-side assembly logistics. Utilities represent the dominant end-user segment, initiating large-scale projects to fulfill national renewable energy mandates.
Government policies like the EU Green Deal and national offshore wind leasing auctions, managed by entities like the US Bureau of Ocean Energy Management (BOEM), create essential market pull. These frameworks provide revenue support and exclusive site rights, underpinning project bankability. Future project viability depends on the successful industrialization of the supply chain to reduce costs and accelerate construction timelines.
Market Dynamics
The central force shaping the market is the imperative to industrialize the supply chain. This involves balancing high capital expenditure for specialized ports and vessels against intense pressure from utilities to reduce the levelized cost of energy.
Growth Catalysts
- Policy Mandates:National decarbonization targets, reinforced by frameworks like the EU Green Deal, compel utilities to invest in large-scale floating wind projects to meet renewable energy quotas.
- Technology Maturation:Advancements in dynamic mooring systems and subsea cables are enabling projects in deeper waters with superior wind resources, expanding the viable project area.
- Geographic Resource Concentration:Favorable wind conditions and maritime planning have concentrated initial development in zones off Scotland, South Korea, and California, creating focused investment hubs.
Market Restraints
- Cost Parity Gap:The high cost of steel for foundations keeps the levelized cost of energy for floating wind above that of fixed-bottom and onshore alternatives.
- Infrastructure Deficits:A global shortage of ports with the necessary water depth, quay strength, and assembly areas constrains the serial production of floating foundations.
- Grid Integration Hurdles:Connecting large projects far from shore requires substantial, costly upgrades to onshore transmission infrastructure, creating commissioning bottlenecks.
Strategic Opportunities
- Green Hydrogen Production:Co-locating floating wind farms with electrolyzers offers a way to produce green hydrogen, creating a new offtake market independent of grid constraints.
- Untapped Geographies:Deep-water areas off Japan, Norway, and the US Pacific Northwest present significant expansion opportunities where fixed-bottom solutions are not feasible.
- Digital Twin Integration:Applying AI and digital twins for predictive maintenance of turbines and moorings can reduce operational expenditures and improve asset reliability.
Industry Challenges
- Specialized Labor Scarcity:A shortage of maritime engineers and high-voltage technicians with offshore experience threatens to delay project execution timelines across multiple regions.
- Foundation Standardization:The lack of standardized foundation designs complicates the supply chain, prevents economies of scale, and increases project-specific engineering costs.
- Permitting Complexity:Navigating multi-agency environmental and maritime permitting, such as processes managed by the US Bureau of Ocean Energy Management, can cause significant project delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Wind Power Market |
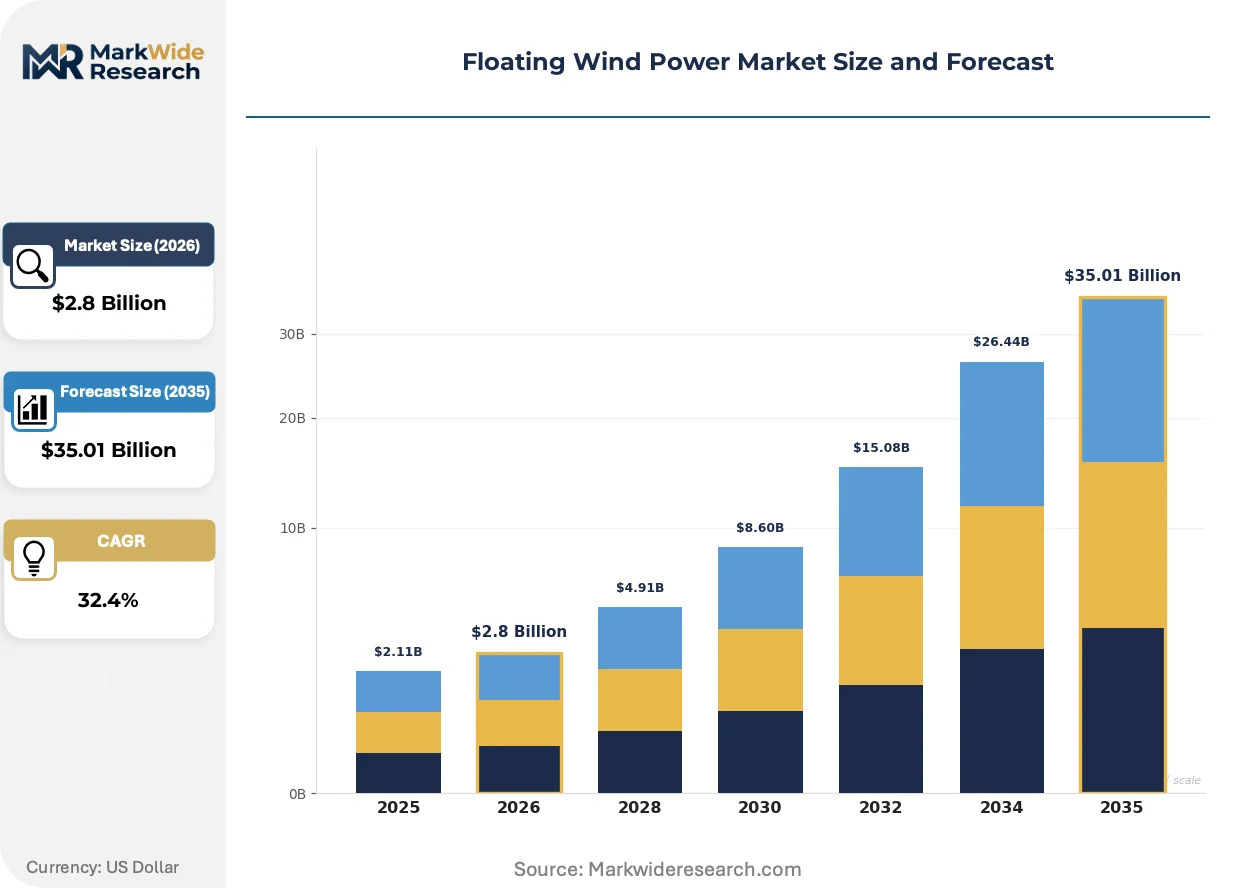
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $35.01 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Semisubmersible, Spar-Buoy, Tension Leg Platform, Floating Wind Turbines End User: Utilities, Offshore Developers, Government Projects, Independent Power Producers Deployment: Fixed, Mobile, Permanent, Temporary Component: Turbines, Anchors, Buoys, Mooring Systems |
| Companies Covered | Siemens Gamesa Renewable Energy S.A., MHI Vestas, GE Vernova, Vestas Wind Systems A/S, Equinor ASA, Ørsted A/S, Principle Power Inc., BW Ideol, Aker Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Wind Power Market Strategic Shifts & Innovations
The push for industrialization is transforming floating wind from bespoke engineering projects into a scalable energy sector. This transition prioritizes manufacturing efficiency, supply chain optimization, and standardized deployment.
Modular foundation design is a key technological enabler, breaking down substructures into smaller components for mass production. Project developers and EPC contractors are adopting this approach to reduce reliance on specialized shipyards. This modularity is fragmenting the monolithic fabrication model, creating a more distributed and competitive ecosystem of component suppliers.
Leasing auctions for offshore wind sites increasingly incorporate non-price criteria. Regulators like the UK's Crown Estate and the US BOEM now evaluate bids on commitments to local supply chain investment. This shift forces developers to formulate industrial strategies, not just low-cost bids. Project developers are most affected, embedding local content plans into their bidding strategy.
A clear shift is occurring from single-project power purchase agreements to portfolio-level offtake strategies. This change disrupts the project-by-project financing cycle, as large utilities seek to secure large blocks of renewable capacity. The trend is most pronounced in Europe, where major energy companies aggregate floating wind capacity to meet long-term decarbonization goals.
Floating Wind Power Market Segmentation
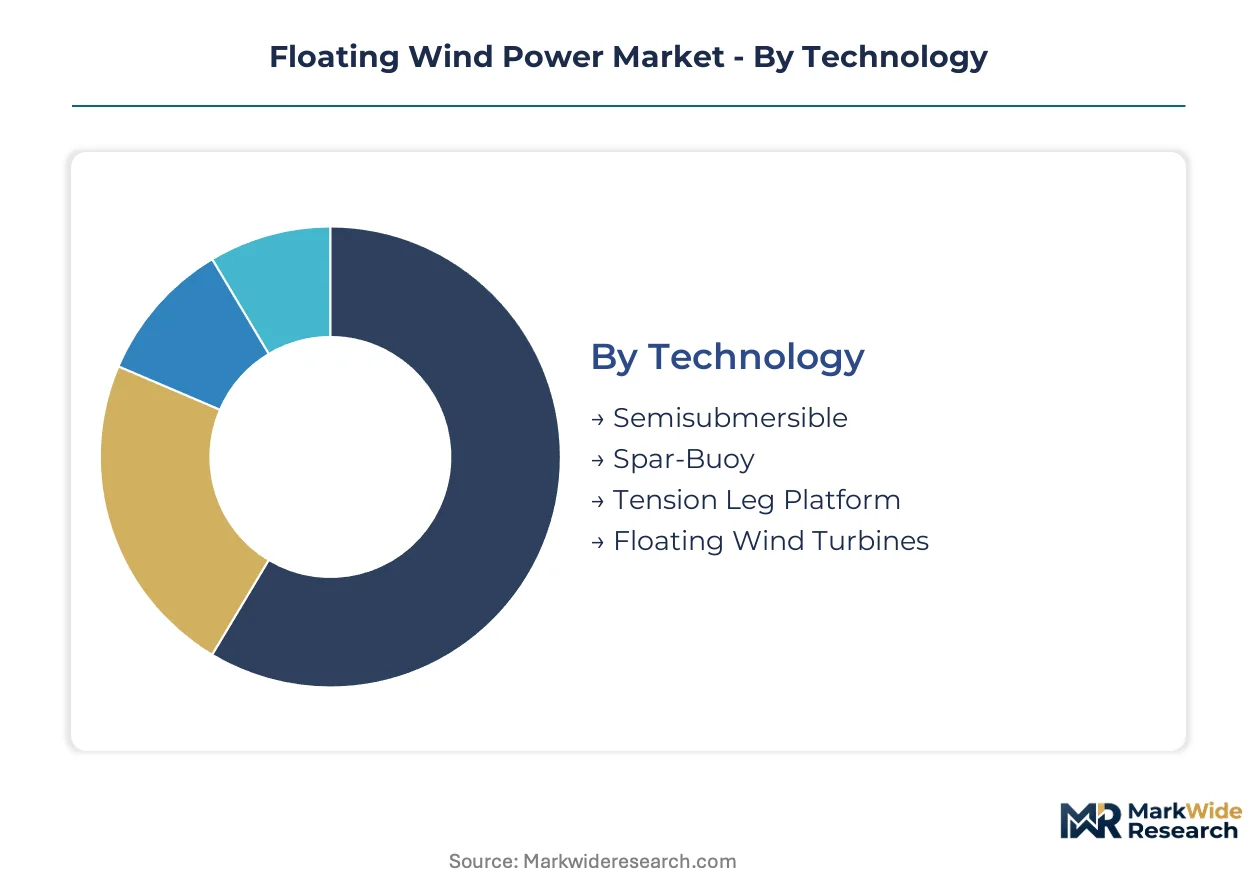
Understanding the Floating Wind Power Market through its constituent segments reveals the critical sub-sectors driving its expansion. Analysis of technology, end-user, deployment, and component categories provides clarity on where investment and innovation are concentrating. This segmentation highlights the diverse approaches to developing deep-water renewable energy projects.
Technology:
The technology landscape for floating wind power showcases solutions optimized for varied maritime conditions, influencing their adoption across different national and regional project specifications.
- Semisubmersible:These platforms feature multiple columns connected by pontoons, offering superior stability and reduced motion characteristics, making them suitable for turbulent deep-water environments. Demand focuses off Scotland and South Korea, where large-scale projects benefit from their robust design for high-wind conditions.
- Floating Wind Turbines:These are the actual power generation units, specifically engineered to withstand the dynamic loads and movements inherent to floating platforms. Demand is highest in California, where high-capacity turbines are crucial for maximizing energy capture from rich Pacific offshore wind resources.
- Spar-Buoy:Spar-Buoy designs feature large, cylindrical buoys partially submerged, achieving stability via deep drafts, often necessitating deep-water ports for assembly.
- Tension Leg Platform:Tension Leg Platforms utilize vertical tethers anchored to the seabed, providing stability by minimizing platform motion and reducing ocean surface footprint.
Semisubmersible technology holds the largest share; momentum sits with Floating Wind Turbines.
End User:
The end-user segmentation highlights the primary entities driving the procurement and deployment of floating wind solutions, reflecting diverse strategic objectives for energy generation.
- Utilities:These are large-scale power providers seeking to meet national decarbonization targets and secure long-term renewable energy supplies for their grids. Demand is prominent in Europe, where energy companies aggregate floating wind capacity to fulfill ambitious decarbonization goals.
- Offshore Developers:These companies specialize in the planning, financing, and execution of offshore energy projects, often working in partnership with utilities or independently. Demand is strong off the coasts of Scotland, driven by favorable regulatory frameworks for project development.
- Government Projects:These initiatives are typically state-funded or supported, focusing on strategic energy security, technological demonstration, or regional economic development goals.
- Independent Power Producers:These entities generate electricity for sale to utilities or directly to consumers, often focusing on optimizing project costs and energy output.
Utilities represent the largest consumer segment; Offshore Developers are expanding their project portfolios most quickly.
Deployment:
The deployment segment differentiates floating wind installations based on their operational duration and structural permanence, impacting project planning and resource allocation.
- Permanent:These deployments involve long-term installations designed for continuous power generation over decades, utilizing robust mooring systems and subsea cable infrastructure. Demand concentrates in deep-water zones off Norway, where projects are designed for multi-generational energy production.
- Temporary:These deployments are typically for research, pilot projects, or specific short-duration energy needs, often using less complex mooring and grid connection solutions. Demand for temporary setups is observed in test sites off Portugal, facilitating rapid iteration and technological validation.
- Fixed:This term, while broadly referring to fixed-bottom, can also describe floating platforms that remain in a single, long-term operational location using permanent mooring.
- Mobile:These deployments involve platforms designed for repositioning, potentially serving different locations or being moved for maintenance, though less common for utility-scale floating wind.
Permanent deployments constitute the overwhelming majority of current projects; Temporary deployments are gaining momentum for pilot programs.
Component:
The component breakdown illuminates the specialized subsystems required for floating wind farms, revealing critical areas for supply chain industrialization and cost reduction efforts.
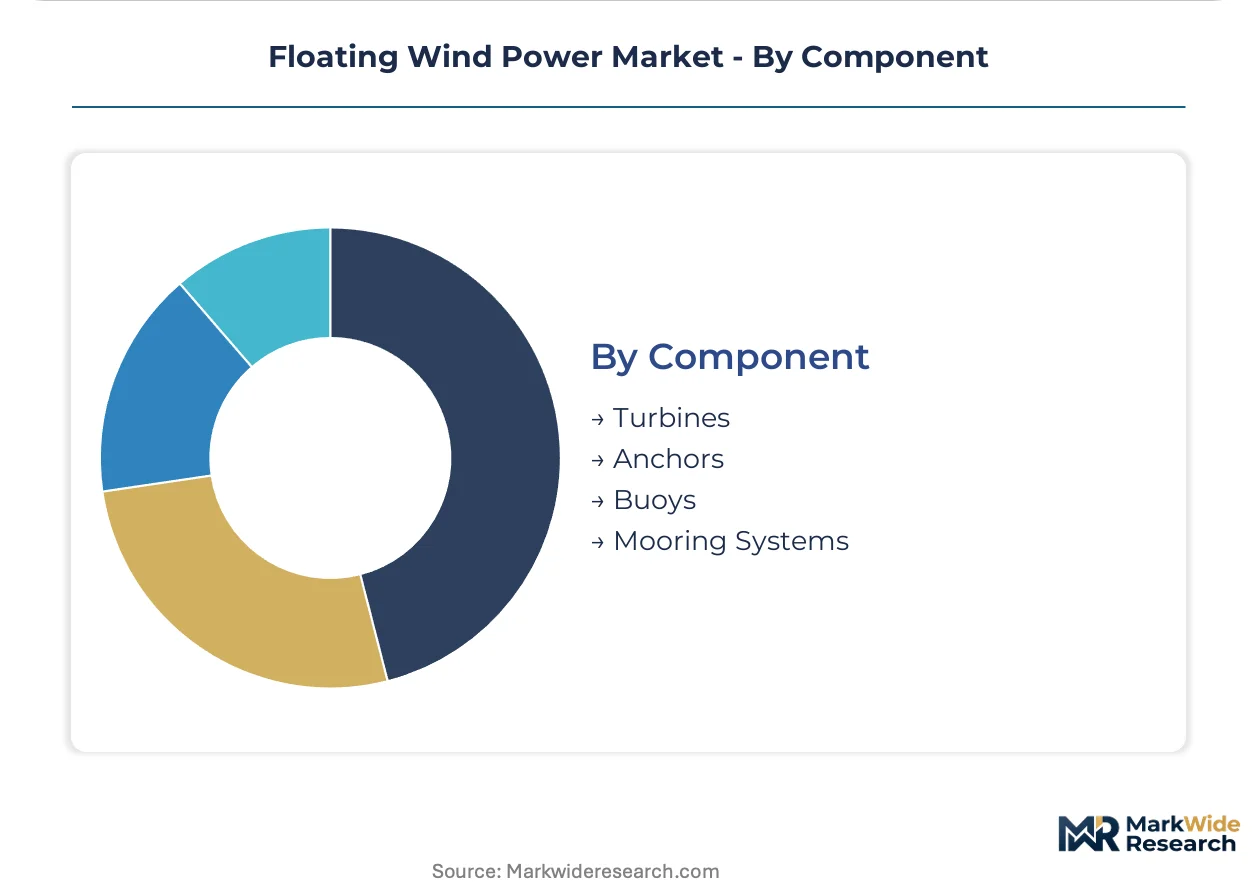
- Turbines:These are the primary energy conversion devices, specifically designed for the dynamic conditions of floating platforms, often featuring higher capacities to optimize deep-water wind resources. Demand is significant in California, where high-capacity units are essential for unlocking vast offshore wind potential.
- Mooring Systems:These critical components secure the floating platforms to the seabed, comprising chains, ropes, and anchors, and are undergoing significant advancements for deeper waters. Demand is pronounced off Scotland, driven by the need for robust solutions in challenging North Sea conditions.
- Anchors:These foundational elements connect the mooring lines to the seabed, requiring site-specific design for various geological conditions and load requirements.
- Buoys:These components provide buoyancy and support within the mooring lines, helping to manage tension and maintain the platform's position.
Turbines represent the highest value component; Mooring Systems are experiencing the most rapid technological evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Floating wind power demand exhibits varying price sensitivities, with some regions prioritizing long-term energy security over immediate cost parity. Other markets, driven by decarbonization targets, absorb higher initial capital expenditures. This dynamic shapes investment patterns and project viability.
United Kingdom
The United Kingdom drives demand through extensive North Sea wind resources and ambitious decarbonization goals. The Crown Estate's leasing rounds promote large-scale floating wind projects off the Scottish coast. Port of Nigg in Scotland expands facilities for fabrication and deployment of massive floating foundations.
South Korea
South Korea's energy security imperative and limited land availability underpin its strong demand for floating wind solutions. National renewable energy mandates provide significant incentives for utility-scale offshore wind development. Ulsan, a major industrial city, actively invests in port infrastructure to support floating wind farm construction.
United States
California's deep offshore waters and aggressive renewable energy targets create substantial demand for floating wind technology. The US Bureau of Ocean Energy Management (BOEM) manages site leasing auctions crucial for project development on the Pacific coast. Humboldt Bay in California is assessing port upgrades for floating wind infrastructure.
Japan
Japan's high reliance on energy imports and extensive deep-water coastlines necessitate investment in floating wind power. The Ministry of Economy, Trade and Industry (METI) actively supports offshore wind development through various promotion policies. Fukushima, Japan, hosts several demonstration projects validating floating wind technologies for commercial scale deployment.
Norway
Norway leverages its vast offshore expertise and abundant deep-water wind resources to drive floating wind development. The Norwegian government's offshore energy policies provide a framework for new licensing rounds in promising areas. Mongstad, Norway, serves as a significant industrial base for integrating floating wind projects with existing oil and gas platforms.
Floating Wind Power Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the floating wind power market. This market structure is consolidating around a few major players capable of large-scale project development and technology integration. Strategic archetypes include turbine manufacturers, foundation design specialists, and utility-scale project developers. Competitive moves center on technology licensing and strategic partnerships to scale deployment capabilities.
Specialists in foundation design and integrated project development exemplify the diverse approaches to market participation. Principle Power Inc. occupies a position as a leading technology provider, licensing its WindFloat semisubmersible foundation to a broad developer base globally. Equinor ASA represents a pioneer in full-scale project development, integrating various technologies to de-risk its investments and accelerate deployment. GE Vernova, an Inc. company, anchors a segment focused on providing high-capacity turbines specifically optimized for the unique dynamic loads of floating platforms. This company also emphasizes turbine optimization for challenging deep-water conditions.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy S.A. |
| MHI Vestas |
| GE Vernova |
| Vestas Wind Systems A/S |
| Equinor ASA |
| Ørsted A/S |
| Principle Power Inc. |
| BW Ideol |
| Aker Solutions |
| Others |
Cost & Logistics Intelligence
Industrialization of the supply chain, driven by scale economies, directly shapes both supply concentration and the achievable price floors for floating wind power. The imperative to reduce the levelized cost of energy forces efficiency across fabrication and deployment.
Pricing Analysis
After-sales service and long-term maintenance contracts represent a crucial revenue tier that drives lifetime value for floating wind projects. Pricing for large-scale floating wind projects primarily follows a contract-based long-term offtake model, often through power purchase agreements. Price differentiation stems from technology maturity and project complexity, alongside geographic delivery costs for specialized components. Intense pressure from utilities to reduce the levelized cost of energy is forcing cost compression across the value chain. Utilities represent the most price-sensitive buyers, while government-backed strategic projects may exhibit lower price sensitivity.
Supply Chain Analysis
Strategic stockpiling of critical components like specialized high-capacity turbines and subsea cables is emerging to mitigate supply chain risks in the floating wind market. Geographic supply concentration for fabrication and assembly centers on established maritime industrial hubs such as Scotland, South Korea, and California. Raw material dependencies include high-grade steel for foundations and rare earth elements for turbine magnets. Infrastructure deficits, particularly the global shortage of specialized ports and vessels, pose a significant supply chain risk. Distribution runs through project-specific logistics, with large components often delivered directly to port-side assembly areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The floating wind market represents a high-growth disruption, fundamentally reshaped by national decarbonization targets and advancements enabling deep-water energy access.
For Market Incumbents: Fortify existing market positions by investing heavily in specialized port infrastructure and advanced manufacturing capabilities for modular foundation designs. This defends against the cost parity gap with fixed-bottom alternatives and mitigates specialized labor scarcity. Strategic partnerships with engineering and construction firms can accelerate supply chain industrialization and de-risk project execution.
For New Entrants and Emerging Players: A certification fast-track for innovative mooring systems or digital twin solutions offers a viable entry point into the floating wind market. Target temporary deployments for pilot programs in nascent markets like Japan or Norway, where regulatory frameworks are still evolving. A technology licensing model to larger project developers provides a capital-efficient go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized technology providers and experienced EPC contractors capable of scaling deployment. Long-term viability over the next 5-10 years is strong, driven by vast untapped deep-water resources and policy mandates. Acquire companies with proven intellectual property in foundation design or advanced subsea cable technology. The successful commissioning of large-scale projects in new, challenging regions is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Modular Foundation Manufacturing | This reduces reliance on specialized shipyards and lowers project-specific engineering costs for developers. |
| Secure Long-term Offtake Agreements | This provides revenue stability for project financing and attracts investment from utilities like Equinor ASA. |
| Develop Specialized Port Infrastructure | This enables serial production and efficient assembly of large floating wind components in regions like Ulsan. |
| Advance Dynamic Mooring System R&D | This unlocks deeper water sites and improves project stability in challenging maritime conditions off Scotland. |
| Implement Digital Twin for O&M | This enhances predictive maintenance and reduces operational expenditures for large-scale floating wind farms. |
Research Approach
Operator-level perspectives from utility planning officers, offshore developers, technology providers, and government regulators anchored the qualitative base for this analysis. Primary interviews were triangulated with secondary data from IEA reports, national energy agency publications from METI, project development databases, and company reports. This approach ensured a robust bottom-up and top-down validation of market dynamics.
Sensitivity analysis framed the quantitative projections, modeling market dimensions across the analysis window. Segmentation dimensions included technology (semisubmersible, spar-buoy), end-user (utilities, offshore developers), deployment (permanent, temporary), component (turbines, mooring systems), and regional policy frameworks. Compound annual growth rates were derived from historical growth trends and anticipated future project pipelines. National decarbonization targets and offshore wind leasing auction schedules served as critical forecast inputs.
Decision-makers should treat outputs as directional under current policy mandates and technology maturation assumptions; material deviation would warrant model refresh. Forecasts reflect a comprehensive assessment of market drivers and restraints, acknowledging inherent uncertainties. Revision becomes warranted when supply chain industrialization delays or significant grid integration cost overruns cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Greece Wind Energy Market