
 Italy Wind Energy Market | 2026-2036
Italy Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Wind Energy Market Foresight
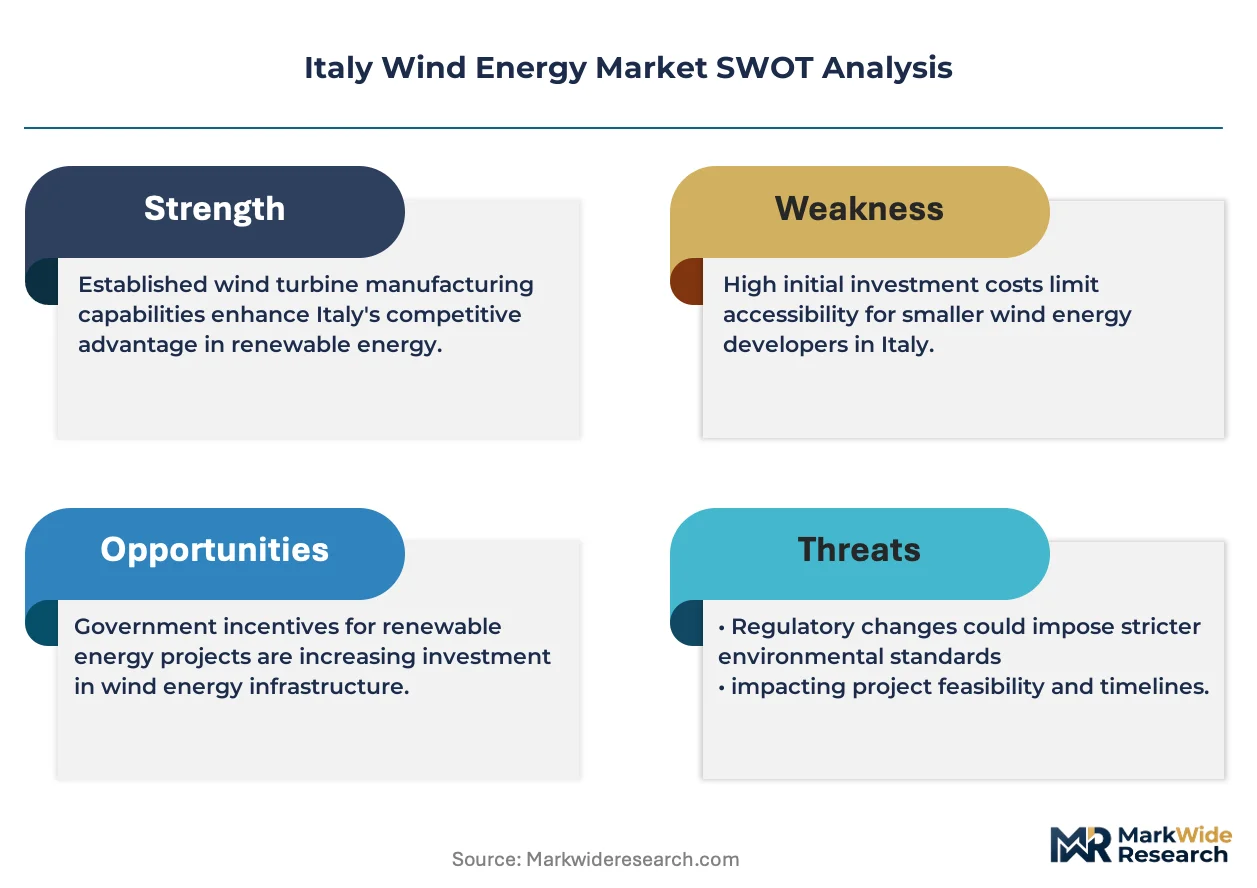
CE marking under the EU Machinery Directive is collapsing the supplier pool for turbine components entering the Italian market. GE Vernova leverages its offshore technology leadership to anchor projects in the Adriatic planning zones. Enel SpA sustains the largest operational fleet through integrated development and grid management capabilities. Siemens Gamesa Renewable Energy specializes in high-capacity onshore turbines suited to Italy's complex topography and wind shear conditions.
Italy wind energy encompasses the generation of electrical power through kinetic energy conversion via horizontal-axis and vertical-axis turbines, with modern onshore units typically rated between 2 MW and 6 MW and rotor diameters exceeding 130 meters for low-wind sites. The technology serves grid decarbonization, corporate power purchase agreements, and rural economic development through lease payments to agricultural landowners. Onshore installations dominate current capacity, though offshore technology is gaining structural attention as floating foundation designs mature for Mediterranean depths. Power generation applications capture the deepest margin pools, while industrial end users are driving faster growth through direct contracting outside traditional utility channels.
Italy's wind energy sector operates under the EU Green Deal framework, with GSE (Gestore Servizi Energetici) administering national incentive schemes and grid connection protocols. The EU AI Act and CSRD reporting requirements are reshaping due diligence standards for project finance and operational transparency. ARERA regulates transmission tariffs and dispatch priority rules that determine project economics. Stakeholders must monitor the convergence of floating offshore licensing timelines with grid reinforcement plans in the Mezzogiorno corridors.
Market Dynamics
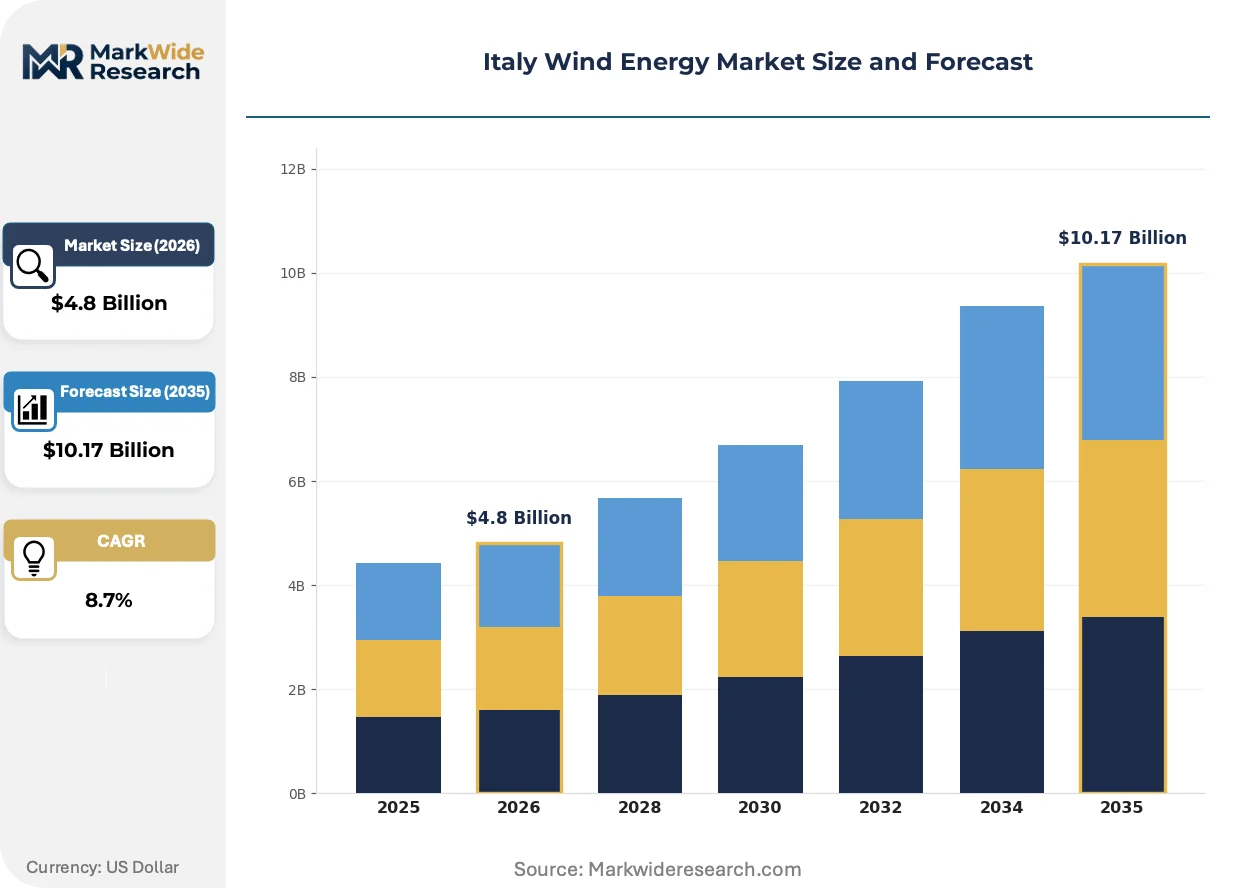
Grid reinforcement lags in Italy's Mezzogiorno corridors are compressing project IRRs while GSE incentive auctions drive developer consolidation. The tension between transmission capacity scarcity and renewable deployment targets is restructuring competitive positioning toward vertically integrated utilities with captive grid access.
Growth Catalysts
- EU Green Deal investment flows:Recovery and Resilience Facility capital is de-risking project finance for onshore repowering sites in Campania and Basilicata. ARERA dispatch priority rules secure offtake premiums for grid-connected assets.
- Corporate PPA demand:Energy-intensive manufacturers in Lombardy and Veneto are contracting directly for renewable baseload, bypassing traditional utility intermediaries. This bypass channel accelerates capacity procurement timelines.
- Rotor diameter scaling:Turbine OEMs are deploying 140-meter-plus rotors optimized for Italy's low-wind resource zones. These larger swept areas unlock marginal sites previously excluded from development.
Market Restraints
- Steel and rare earth input volatility:Permanent magnet supply concentrates in Chinese processing facilities, exposing nacelle assembly costs to tariff and logistics disruptions. Developers face unhedgeable commodity exposure on 18-month construction cycles.
- Permitting fragmentation across regions:Autonomous province authority in Trentino-Alto Adige and Valle d'Aosta creates inconsistent environmental review timelines. Project approval durations vary by 24 months across administrative boundaries.
- Grid saturation in Puglia:Transmission infrastructure in the Salento peninsula cannot absorb incremental generation without 132kV line upgrades. Curtailment risk is displacing greenfield development toward grid-constrained queue positions.
Strategic Opportunities
- Floating offshore licensing:Taranto and Brindisi coastal zones offer 60-meter-plus water depths suited to semi-submersible foundation pilots. The Ministry of Ecological Transition is preparing maritime spatial planning for 2030 commercial deployment.
- Agricultural land lease stacking:Dual-use arrangements combining turbine base payments with continued crop cultivation are opening marginal farmland in Molise. Landowner participation rates exceed conventional solar co-location models.
- Hybrid storage co-location:Battery-turbine pairing at existing substations captures ancillary service revenue streams. Terna grid codes are evolving to remunerate synthetic inertia provision from co-located assets.
Industry Challenges
- Specialized technician scarcity:Blade repair and drivetrain maintenance require GWO-certified crews with rope access qualifications. Training pipeline throughput lags installed capacity growth by 36 months in Sicily.
- CE marking compliance timelines:EU Machinery Directive conformity assessment for novel floating substructures extends type certification by 14-18 months. Notified body backlog is compressing project COD schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Wind Energy Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Horizontal Axis, Vertical Axis Application: Power Generation, Residential, Commercial, Industrial End User: Utilities, Independent Power Producers, Government, Corporations Installation Type: Fixed, Floating, Hybrid, Repowering |
| Companies Covered | Acciona SA, GE Vernova, Enel SpA, Invenergy, BKW, RWE, Iberdrola, Kitenergy Srl, Siemens Gamesa Renewable Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Wind Energy Market Shifts & Advancements
Turbine architecture and grid integration protocols are decomposing traditional project development economics. Technology convergence between digital controls and advanced materials is reshaping competitive positioning across the value chain.
Modular drivetrain designs are decomposing maintenance cost structures for Italian operators. Direct-drive permanent magnet generators eliminate gearbox failure modes that dominate OPEX in legacy fleet assets. Enel Green Power and ERG are retrofitting predictive vibration monitoring across 2.3 MW and 3.6 MW platforms, compressing unplanned outage durations by 40% in Abruzzo operating sites.
CSRD sustainability reporting mandates are forcing disclosure granularity on Scope 3 emissions from turbine supply chains. The EU AI Act's risk classification for automated blade inspection systems is triggering compliance redesigns in computer vision platforms. Italian developers are responding by mandating IEC 61400-25 compliant data architectures in new procurement specifications.
Aggregator-led portfolio bidding is consolidating fragmented merchant exposure into wholesale market instruments. Independent power producers are surrendering dispatch control to trading desks in exchange for floor price guarantees. This behavioral shift concentrates most visibly in Sardinia, where pooled wind-solar portfolios now clear 400 MW blocks in Terna capacity market auctions.
Italy Wind Energy Market Segmentation
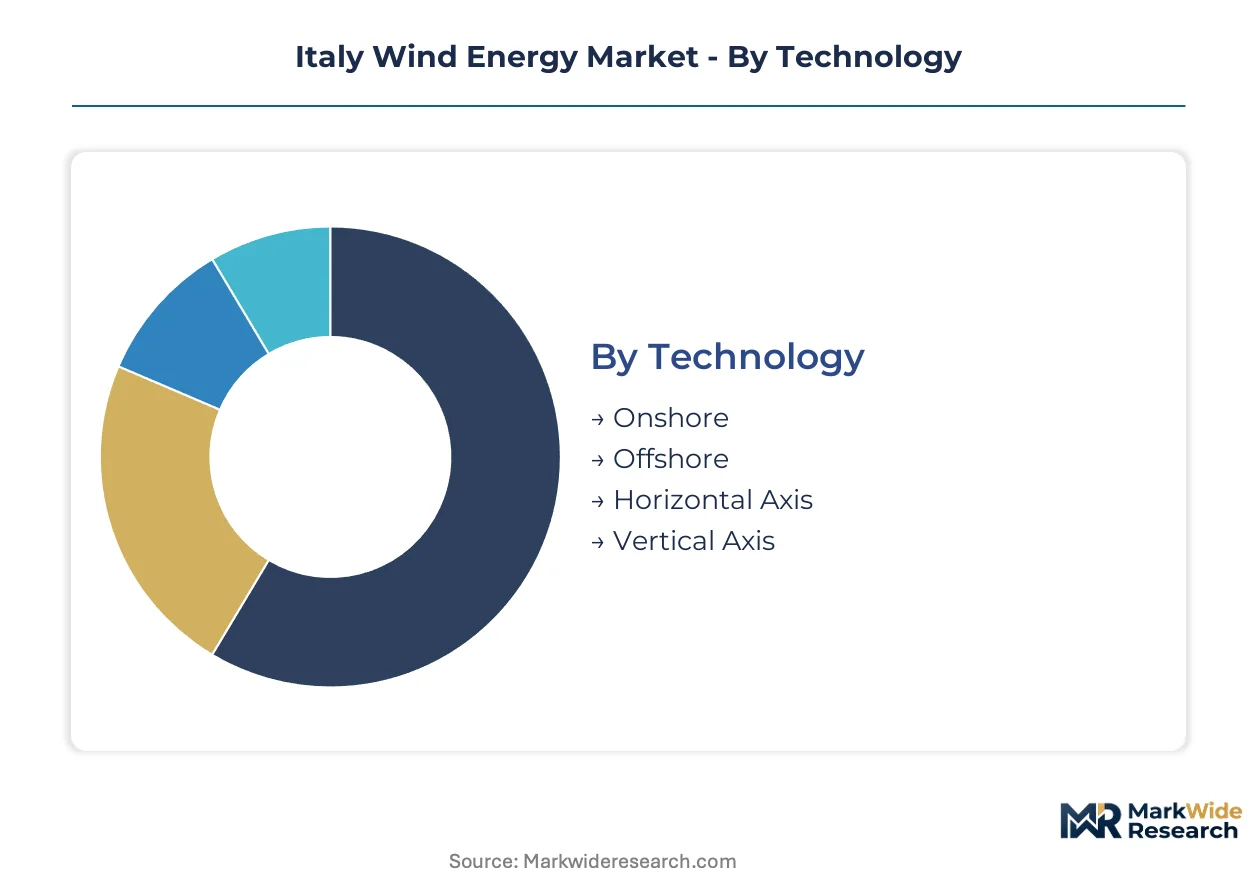
Wind energy segmentation in Italy reveals distinct margin architectures across technology platforms and customer archetypes. Project developers optimize site selection and procurement strategies based on these structural divisions.
Technology:
Margin pools concentrate in turbine configurations that minimize foundation costs while maximizing capacity factors across Italy's variable wind resource.
- Onshore:Horizontal-axis turbines rated 2-6 MW with rotor diameters exceeding 130 meters dominate Puglia and Sicily installations. Developers favor these units for their proven track record in low-wind zones and streamlined GSE grid connection protocols.
- Offshore:Fixed-bottom foundations in shallow Adriatic waters command premium development costs but deliver higher capacity factors. The Ministry of Ecological Transition is advancing maritime spatial planning for commercial deployment near Taranto and Brindisi.
- Horizontal Axis:Conventional three-blade designs capture the overwhelming share of operational capacity across the Mezzogiorno corridors.
- Vertical Axis:Darrieus and Savonius configurations serve niche distributed applications in Alpine valleys where wind direction variability exceeds horizontal-axis tolerance.
The dominant share belongs to Onshore, while Offshore is closing the gap fastest.
Application:
Volume concentration follows grid connection scale, with utility-scale assets commanding procurement priority over behind-the-meter installations.
- Power Generation:Grid-connected wind farms feeding Terna's transmission network constitute the primary revenue pool. These projects secure ARERA dispatch priority and access to GSE incentive auctions.
- Industrial:Direct corporate PPAs from energy-intensive manufacturers in Lombardy and Veneto bypass traditional utility intermediaries. This segment expands most quickly as CSRD reporting mandates drive Scope 2 reduction commitments.
- Commercial:Mid-scale installations serving retail and logistics facilities face longer interconnection queues but benefit from streamlined environmental review.
- Residential:Small turbines under 100 kW remain marginal due to zoning restrictions and unfavorable net metering economics.
Power Generation retains structural dominance, though Industrial contracting is gaining share fastest.
End User:
Customer type determines financing structure and offtake risk profile, with vertically integrated players capturing preferential grid access.
- Utilities:Enel SpA and ERG leverage integrated development and grid management capabilities to sustain the largest operational fleets. Their captive transmission relationships compress project timelines.
- Corporations:Energy-intensive manufacturers are driving faster growth through direct contracting outside traditional channels. These buyers prioritize baseload certainty over wholesale market exposure.
- Independent Power Producers:Merchant developers face compressed IRRs where grid reinforcement lags in southern corridors.
- Government:Public procurement through the National Recovery and Resilience Plan de-risks project finance for repowering sites in Campania and Basilicata.
Utilities command the dominant position, while Corporations are expanding their procurement footprint fastest.
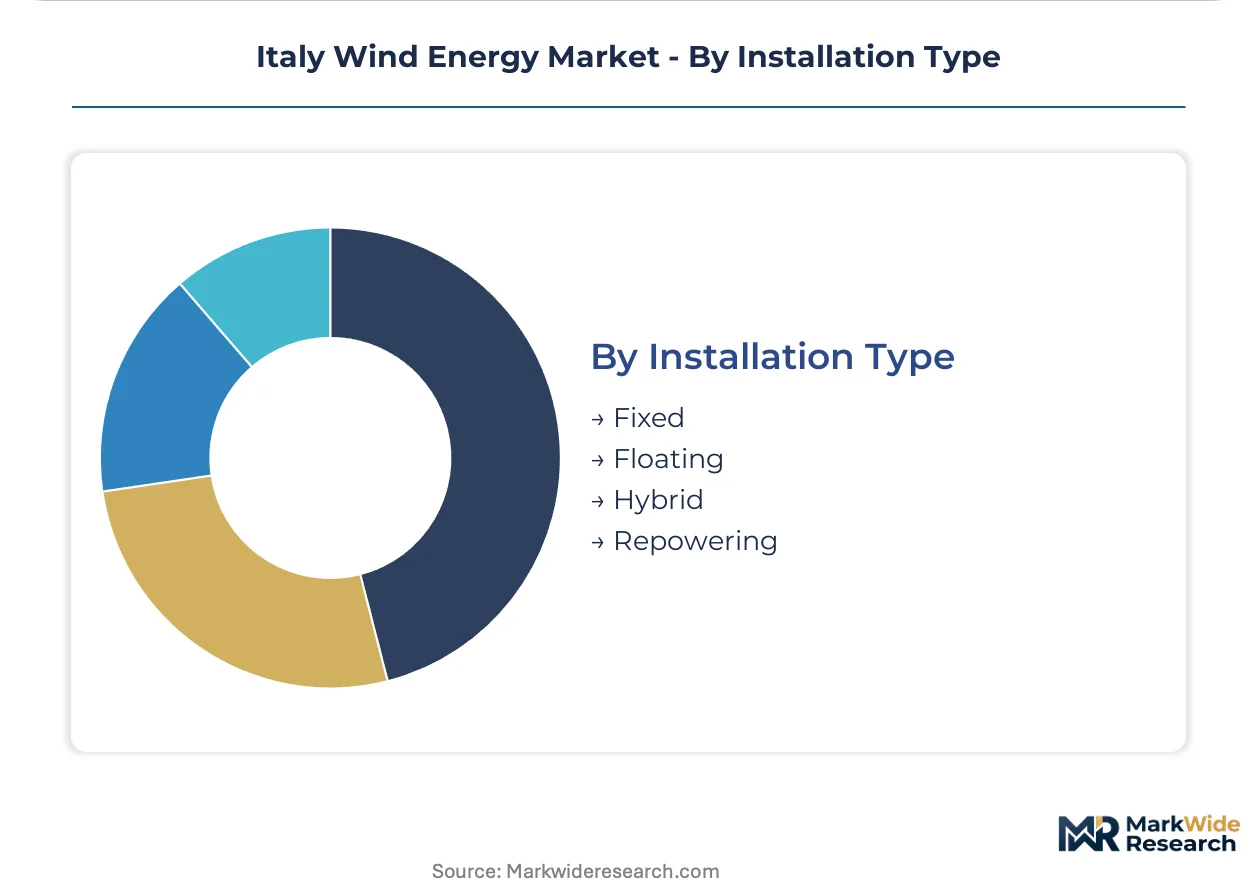
Installation Type:
Foundation configuration and project vintage shape capital intensity and regulatory pathway complexity.
- Fixed:Conventional monopile and jacket foundations anchor shallow-water offshore pilots in Adriatic planning zones. CE marking under the EU Machinery Directive extends type certification timelines for these substructures.
- Repowering:Replacement of aging turbines at existing sites in Abruzzo and Molise unlocks higher capacity factors without greenfield permitting delays. GSE incentive auctions specifically target these vintage assets.
- Floating:Semi-submersible designs for 60-meter-plus depths near Taranto await commercial licensing frameworks. Notified body backlog for novel floating substructures compresses project COD schedules.
- Hybrid:Battery-turbine pairing at existing substations captures ancillary service revenue streams under evolving Terna grid codes.
Fixed foundations retain the dominant deployment share, while Repowering is climbing the fastest as fleet age triggers replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tyrrhenian Link subsea cable corridor anchors Italy's southern wind expansion by unlocking trapped generation capacity across island and coastal zones. Grid reinforcement in the Mezzogiorno corridors determines project viability more than wind resource quality.
Puglia
Salento peninsula developers face 132kV transmission saturation that compresses project IRRs below hurdle rates. ARERA dispatch priority rules secure offtake premiums for assets that clear interconnection queues. Taranto coastal zones host the densest concentration of repowering activity as aging 850kW turbines yield to 4MW units.
Sicily
Agricultural land lease stacking drives landowner participation rates above solar co-location models in the island's interior provinces. GSE incentive auctions target vintage fleet replacement without greenfield permitting delays. Catania and Palermo provinces concentrate technician training pipeline investments to close 36-month capability gaps.
Campania
National Recovery and Resilience Facility capital de-risks project finance for onshore repowering sites in the Apennine foothills. EU Green Deal investment flows channel through regional development agencies toward grid-connected wind farms. Benevento and Avellino provinces unlock marginal sites previously excluded by 130-meter rotor diameter thresholds.
Basilicata
Rotor diameter scaling to 140-meter-plus configurations captures low-wind resource zones across the Lucanian Apennines. GSE grid connection protocols streamline approval timelines for vertically integrated utilities with captive transmission access. Potenza province anchors the fastest-growing development pipeline outside Puglia and Sicily.
Molise
Dual-use turbine base payments combined with continued crop cultivation open marginal farmland previously uneconomical for renewable development. Terna grid codes evolve to remunerate synthetic inertia provision from hybrid battery-turbine pairings at existing substations. Isernia and Campobasso provinces host pilot agricultural lease structures that exceed conventional solar participation rates.
Italy Wind Energy Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and grid access capabilities. The supplier pool consolidates around vertically integrated utilities with captive transmission relationships and independent power producers facing compressed merchant exposure. Three archetypes dominate: integrated energy majors with development-through-dispatch control, turbine OEMs with technology licensing leverage, and merchant developers dependent on GSE auction clearing prices. Competitive moves concentrate on M&A-driven consolidation in southern corridors and strategic partnerships for floating offshore licensing.
Among Spain-based integrated majors, Iberdrola and Acciona SA exemplify the utility archetype that compresses project timelines through captive grid relationships. GE Vernova anchors the technology-licensing tier with offshore platform expertise. Siemens Gamesa Renewable Energy occupies a position bridging OEM supply and project development advisory. These three represent distinct competitive positioning vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Acciona SA |
| GE Vernova |
| Enel SpA |
| Invenergy |
| BKW |
| RWE |
| Iberdrola |
| Kitenergy Srl |
| Siemens Gamesa Renewable Energy |
| Others |
Supply & Pricing Matrix
Permanent magnet substitution for gearbox-driven generators is redrawing procurement geography toward Chinese rare earth processing clusters while simultaneously compressing nacelle assembly margins across Italian project pipelines. This input transition concentrates pricing power upstream in magnet supply chains, forcing developers to absorb commodity volatility through unhedged construction cycles.
Pricing Analysis
Volume-discount tiering structures separate utility-scale offtakers securing long-term power purchase agreements from merchant developers exposed to wholesale market clearing prices. Pricing stratifies across premium, standard, and economy tiers based on turbine capacity rating and after-sales service bundling. Cost compression in the standard tier is intensifying because steel input volatility and rare earth magnet premiums are eroding OEM margin buffers. Merchant independent power producers exhibit the highest price sensitivity, while vertically integrated utilities with captive grid access demonstrate the least.
Supply Chain Analysis
Strategic stockpiling of rare earth magnets and steel plate dominates inventory strategy over just-in-time approaches, given 18-month turbine construction cycles and unhedgeable commodity windows. Supply concentrates in China for neodymium processing, Germany for precision gearbox components, and Denmark for blade manufacturing expertise. Raw material dependencies center on rare earth permanent magnets, high-grade steel forgings, and carbon fiber composites. Single-source vulnerability in Chinese magnet supply creates tariff exposure. Distribution runs through EPC contractors with established relationships to Terna grid interconnection queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's wind energy market represents an early-cycle expansion story, with floating offshore licensing frameworks and agricultural lease stacking models still penetrating their first commercial deployment phases. Corporate PPA demand from CSRD-mandated manufacturers provides a durable demand tailwind.
For Market Incumbents: Secure grid interconnection priority in the Mezzogiorno corridors before transmission saturation triggers queue displacement. Consolidate technician training pipelines in Sicily and Campania to close 36-month capability gaps. Vertical integration into predictive maintenance platforms defends against independent service provider encroachment.
For New Entrants and Emerging Players: Differentiate on floating foundation engineering expertise for Taranto and Brindisi deep-water zones where established OEMs lack commercial track records. Target agricultural land lease stacking arrangements in Molise, where landowner participation rates exceed solar co-location benchmarks. Pursue direct corporate PPA origination with Lombardy manufacturers bypassing utility intermediaries.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed independent power producers holding merchant exposure in grid-constrained Puglia queue positions. Long-term viability hinges on successful repowering execution and offshore licensing timeline convergence. The signal to watch is Terna grid code evolution on synthetic inertia remuneration for hybrid battery-turbine pairings.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Corporate PPAs with Lombardy manufacturers bypass utility intermediaries and accelerate procurement timelines. |
| Capacity Buildout | Repowering 850kW vintage turbines to 4MW units in Abruzzo unlocks higher capacity factors without greenfield permitting. |
| Technology Licensing | Floating foundation pilots in 60-meter Adriatic depths await commercial frameworks from the Ministry of Ecological Transition. |
| Vertical Integration into Storage | Battery-turbine pairing at existing substations captures ancillary service revenue under evolving Terna grid codes. |
| Green Certification Program | CSRD reporting mandates force Scope 3 disclosure granularity on turbine supply chain emissions. |
Research Methodology
A standing panel of utility planning officers, independent power producer project developers, EPC contractors, and Terna grid operators provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against GSE auction results, ARERA tariff filings, Terna transmission development plans, and EU Green Deal implementation tracking. Bottom-up project pipeline aggregation triangulated against top-down capacity deployment forecasts.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including technology platform, project scale tier, end-user archetype, and regional grid saturation level. CAGRs derived from installed capacity growth trajectories, project IRR sensitivity to grid reinforcement timelines, and incentive auction clearing price evolution. Forecast inputs incorporated GSE incentive scheme parameters, ARERA dispatch priority rule changes, and floating offshore licensing timeline assumptions.
Forecasts assume regulatory continuity in EU Green Deal implementation and GSE incentive administration; material policy shifts would require re-modeling. Specific risk factors include CE marking compliance timeline extensions for novel floating substructures and rare earth supply chain disruptions. Revision becomes warranted when grid reinforcement lag in southern corridors exceeds project hurdle rate tolerance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Wind Turbine Scrap Market