
 United Kingdom Wind Energy Market | 2026-2036
United Kingdom Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Wind Energy Market Analytics
Data center operators is broadening the end-use base for UK wind capacity. Siemens Gamesa leverages its offshore turbine scale to anchor large North Sea projects. Vestas Wind Systems sustains onshore competitiveness through modular platform designs. Ørsted dominates the development pipeline with extensive seabed lease holdings.
Wind energy in the United Kingdom encompasses electricity generation from aerodynamic turbine blades converting kinetic wind flow into mechanical rotation, with offshore units now exceeding 15 MW power ratings and rotor diameters surpassing 220 meters for maximum swept-area efficiency. The technology serves grid decarbonization and corporate renewable procurement targets. Offshore installations command the deepest capital pools due to higher construction complexity and longer asset lifespans. Floating technology represents the fastest-expanding segment as deeper-water sites open beyond fixed-bottom economic limits. Power ratings above 5 MW now occupy the dominant share of new capacity additions.
The Contracts for Difference scheme administered by the Low Carbon Contracts Company shapes revenue certainty for developers, while the Crown Estate manages seabed licensing access. Marine Scotland governs consenting in Scottish waters, adding a layered regulatory topology. Ofgem's grid connection queue reforms will determine which projects secure timely transmission access. Stakeholders must monitor CfD auction strike-price floors and supply-chain bottleneck resolution in turbine component manufacturing.
Market Dynamics
The Contracts for Difference scheme administered by the Low Carbon Contracts Company is compressing developer risk premiums and accelerating capital deployment into Scottish seabed zones, while Ofgem's grid connection queue reforms determine which projects secure timely transmission access.
Growth Catalysts
- Corporate power purchase agreements:Data center operators are contracting directly for offshore capacity, diversifying revenue streams beyond traditional utility offtake and reducing merchant price exposure for developers.
- Floating foundation maturation:Deeper-water sites beyond fixed-bottom economic limits are opening as tension-leg and semi-submersible designs achieve commercial scale, expanding addressable seabed area.
- Crown Estate leasing rounds:Competitive seabed auctions in England, Wales and Northern Ireland are allocating development rights with increasing spatial efficiency and shorter consenting timelines.
Market Restraints
- Supply chain concentration:Turbine nacelle assembly and blade manufacturing capacity clusters in Denmark and Germany, creating bottleneck risk for UK project execution schedules.
- Steel and rare earth input volatility:Permanent magnet direct-drive generators depend on neodymium-dysprosium supply chains concentrated in China, exposing turbine costs to export restriction risk.
- Grid reinforcement lag:National Grid's onshore transmission upgrade timelines trail offshore construction cycles, stranding generation capacity in Scottish waters from southern demand centers.
Strategic Opportunities
- Floating wind in Celtic Sea depths:Water depths exceeding 60 meters off Cornwall and Wales are inaccessible to fixed-bottom technology, creating first-mover advantage for floating platform specialists.
- Green hydrogen offtake integration:Electrolyzer co-location at offshore substations enables power-to-X conversion, capturing otherwise curtailed generation and creating synthetic fuel revenue streams.
- Marine Scotland consenting streamlining:Reforms to the Section 36 and Marine Licence processes are compressing pre-construction timelines for Scottish offshore zones relative to English waters.
Industry Challenges
- Specialized vessel scarcity:Heavy-lift jack-up installation ships and cable-laying vessels face global demand competition, extending charter rates and project scheduling uncertainty.
- Grid code compliance complexity:National Grid's Grid Code requirements for fault ride-through and frequency response demand turbine control system modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Wind Energy Market |
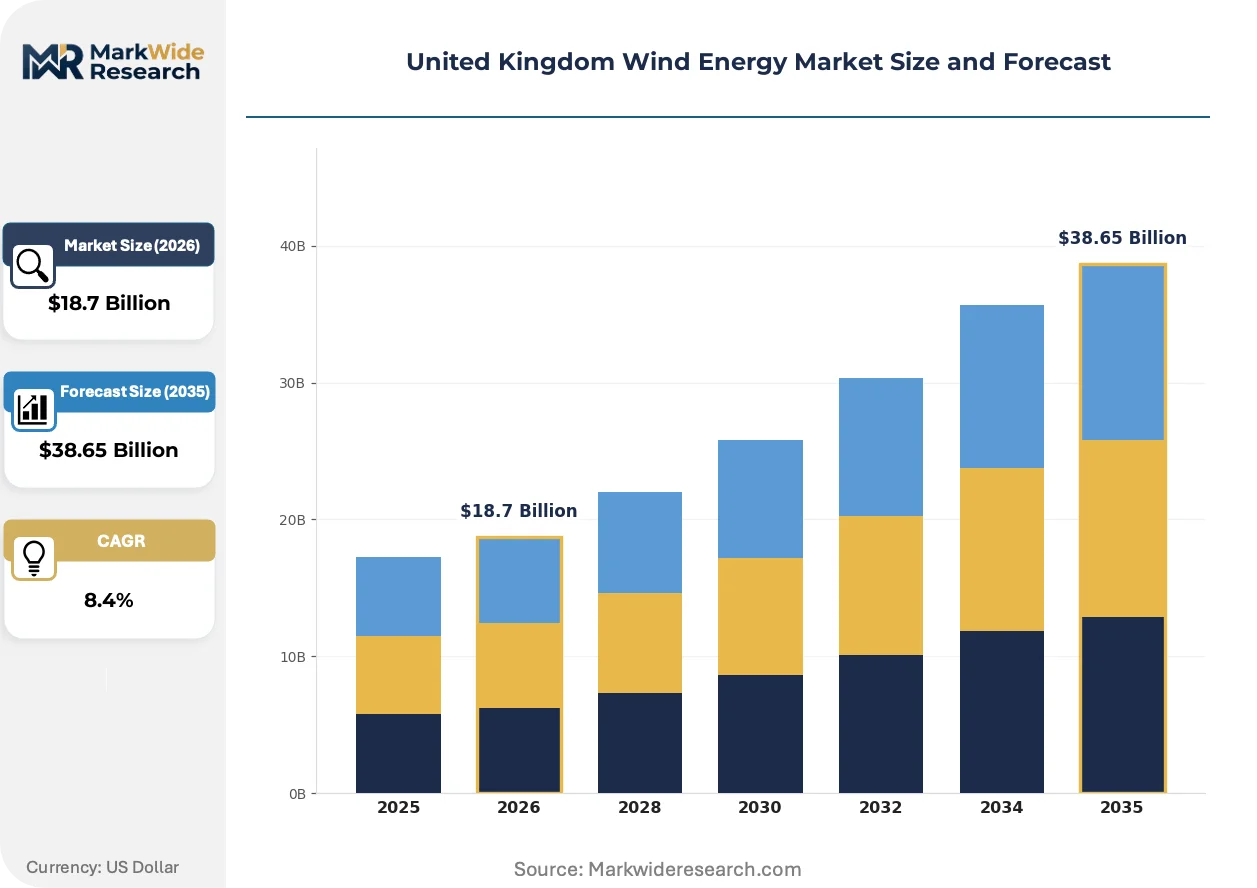
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Floating, Fixed-Bottom End User: Utilities, Independent Power Producers, Government, Corporations Installation: New Build, Retrofit, Expansion, Decommissioning Power Rating: Below 1 MW, 1-3 MW, 3-5 MW, Above 5 MW |
| Companies Covered | Siemens Gamesa, Vestas Wind Systems, GE Vernova, Nordex, Ørsted, EDP Renewables, Schroders Greencoat, Enercon UK, Goldwind, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Wind Energy Market Evolving Landscape
Technology scale-up and procurement model evolution are compressing levelized cost trajectories while regulatory frameworks adapt to deeper-water deployment economics.
Turbine scaling is absorbing capital efficiency gains into larger unit configurations. 15 MW+ offshore platforms with rotor diameters exceeding 220 meters are now standard for North Sea auctions, reducing balance-of-plant costs per installed megawatt. Ørsted and SSE Renewables are specifying these units for Dogger Bank phases, compressing wake losses and array cable requirements across lease areas.
Ofgem's grid connection queue reforms are reshaping project sequencing discipline. The connect-and-manage regime is being replaced by firmer transmission access commitments contingent on construction milestones, forcing developers to advance financial close timelines. Scottish projects in Moray Firth and Firth of Forth clusters face the steepest compliance compression under these rules.
Corporate offtake structures are displacing traditional utility procurement in capacity allocation. Data center operators including Amazon Web Services and Microsoft are contracting directly for baseload-equivalent renewable supply, unbundling energy from renewable obligation certificates. This pattern concentrates in England's East Coast zones with shortest latency to London hyperscale facilities.
United Kingdom Wind Energy Market Segmentation
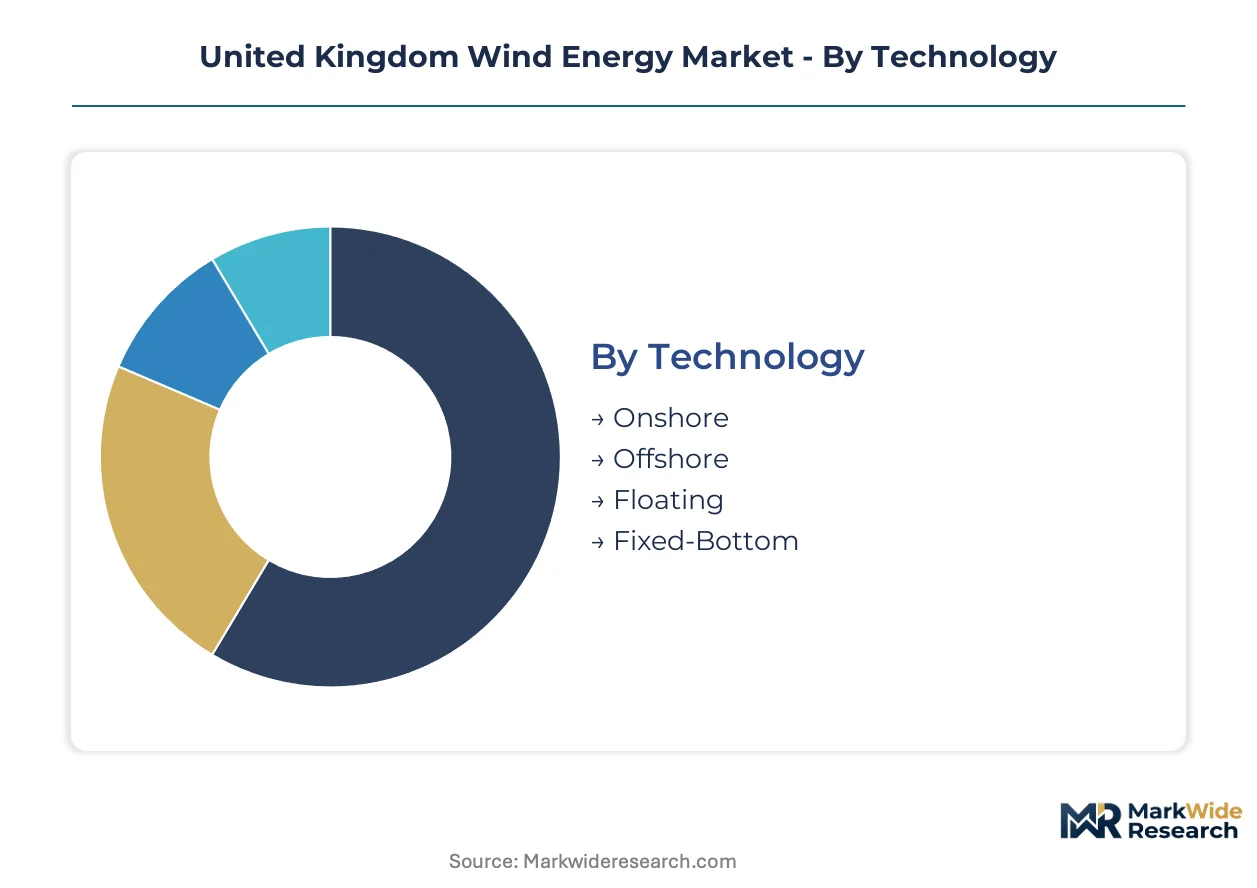
Segmentation in the United Kingdom wind energy market reveals how capital allocation, regulatory pathways, and grid integration requirements diverge across technology configurations and buyer types. Developers navigate distinct consenting timelines, turbine supply chains, and offtake structures depending on which segment they target. Understanding these boundaries shapes project economics and strategic positioning.
Technology:
Marine Scotland and the Crown Estate apply divergent consenting burdens across these technology classes, with floating platforms facing the steepest unproven-design scrutiny while fixed-bottom units clear established environmental assessment pathways.
- Onshore:Turbine clusters sited on land typically range from 2 MW to 6 MW per unit, with rotor diameters optimized for lower wind shear environments. Deployment concentrates in Scotland's upland zones and Welsh hill regions where wind resource density meets lower seabed leasing competition, though grid connection queue delays now constrain new capacity absorption.
- Offshore:Fixed-foundation installations in water depths up to 60 meters dominate capital deployment, with 15 MW+ turbines now standard for North Sea lease areas. Dogger Bank and Moray Firth clusters anchor execution pipelines, drawing specialized heavy-lift vessel fleets from Esbjerg and Rotterdam.
- Floating:Tension-leg and semi-submersible platforms enable turbine placement beyond fixed-bottom economic limits. Celtic Sea depths off Cornwall and Wales host early commercial arrays.
- Fixed-Bottom:Monopile and jacket substructures remain the cost baseline for shallow-water development. Manufacturing capacity clusters in Scottish and Northern English fabrication yards.
Leading the category by volume: Offshore. Expanding most quickly: Floating.
End User:
Procurement patterns diverge sharply by counterparty risk profile and contract duration preferences, with corporate buyers demanding unbundled energy supply while utilities seek bundled renewable obligation certificate structures.
- Utilities:Traditional integrated generators and supply entities procure capacity under long-term regulated frameworks, leveraging existing grid connection rights and balance-sheet capacity for project finance. ScottishPower and SSE Renewables anchor utility-scale pipelines through vertically controlled development arms.
- Independent Power Producers:Developer-specialists without retail supply obligations rely on merchant exposure or corporate offtake to monetize generation, concentrating development expertise in seabed origination and turbine procurement rather than customer acquisition.
- Government:Direct procurement through the Contracts for Difference scheme administered by the Low Carbon Contracts Company sets strike-price floors, de-risking capital for all developer categories.
- Corporations:Data center operators and industrial load-serving entities contract directly for baseload-equivalent renewable supply, unbundling energy from certificates and specifying delivery points proximate to hyperscale facilities.
Dominating procurement volume: Utilities. Gaining share fastest: Corporations.
Installation:
Asset lifecycle stage determines supply chain mobilization intensity and regulatory touchpoint density, with new build commanding full environmental consenting while retrofit and expansion navigate abbreviated review pathways.
- New Build:Greenfield development on unleased seabed or previously undeveloped land triggers full Section 36 consenting in England and Wales or Marine Licence procedures in Scottish waters, with construction spanning 3-5 years from financial close to commercial operation.
- Retrofit:Turbine replacement within existing arrays—repowering—leverages permitted development rights and existing grid infrastructure, compressing consenting timelines and reusing foundation structures where fatigue life permits.
- Expansion:Array extension into adjacent lease areas requires fresh seabed licensing but benefits from established environmental baselines and shared offshore substation infrastructure.
- Decommissioning:End-of-life removal obligations under the Energy Act 2004 impose site restoration liabilities, with pile-cutting and cable recovery now forming a discrete vessel-demand segment.
Absorbing maximum capital: New Build. Steepest activity growth: Retrofit.
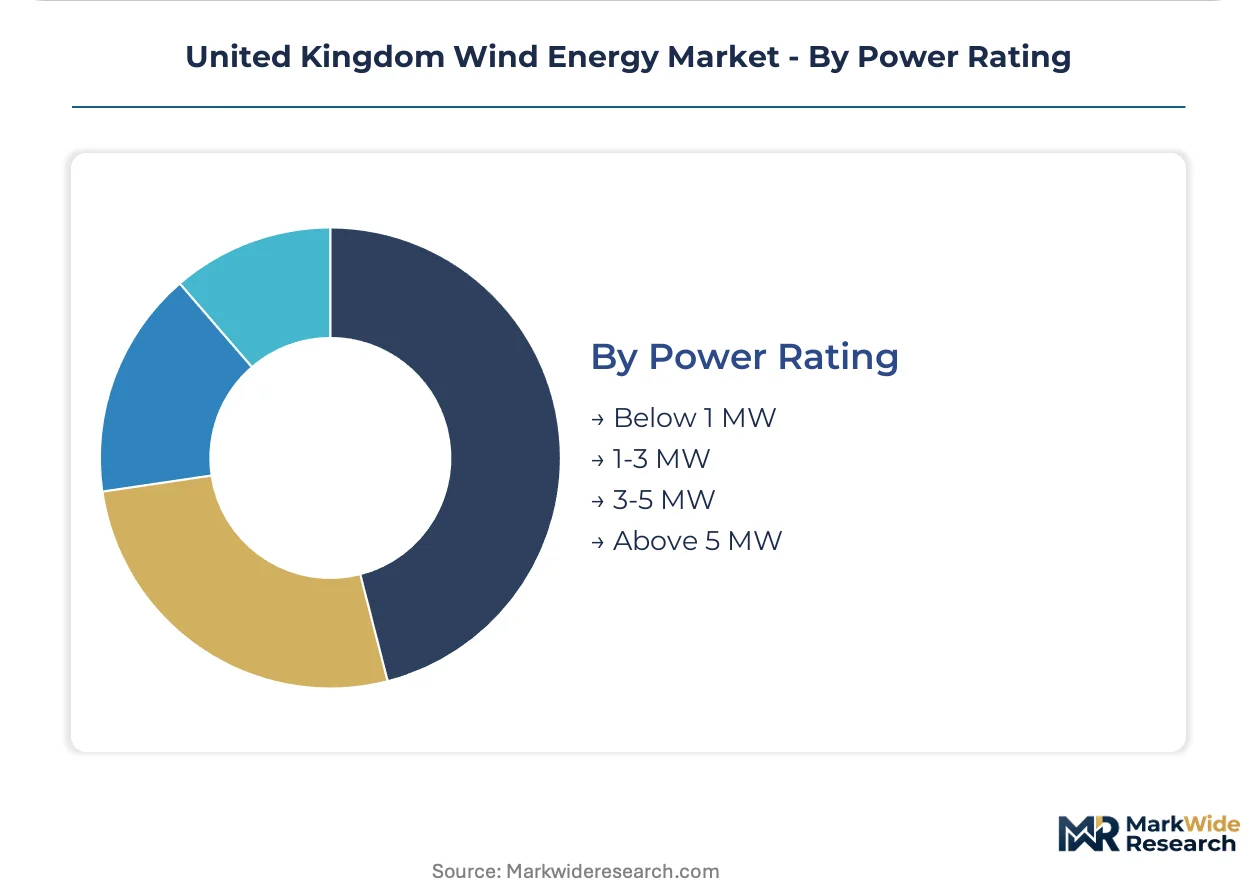
Power Rating:
Turbine scale directly determines balance-of-plant efficiency and wake loss profiles, with unit economics favoring larger configurations where grid connection capacity and vessel availability permit.
- Below 1 MW:Small-scale units serve distributed generation and remote community supply, with limited relevance to grid-scale UK deployment.
- 1-3 MW:Mid-scale platforms dominate legacy onshore fleets and early offshore arrays, now principally relevant for retrofit replacement cycles.
- 3-5 MW:Transitional scale class bridging onshore and early offshore deployment, still specified for constrained sites with grid or logistics limitations.
- Above 5 MW:Large-scale turbines now standard for all new UK capacity, with 15 MW+ offshore units reducing per-megawatt foundation, cable, and installation costs while maximizing swept-area energy yield. Siemens Gamesa and Vestas compete on platform modularity for this segment.
Commanding new capacity share: Above 5 MW. Fading from procurement: Below 1 MW.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Celtic Sea Freeport zone anchors capital concentration through enhanced capital allowances and streamlined consenting pathways for floating wind manufacturing clusters.
Scotland
Scotland's Moray Firth and Firth of Forth seabed zones drive fixed-bottom deployment at scale, with Marine Scotland administering Section 36 consenting and Marine Licences. Aberdeen hosts the Energy Transition Zone fabrication cluster, where jacket substructure manufacturing capacity is expanding to serve Dogger Bank phase execution.
England
England's East Coast zones from Yorkshire to Norfolk concentrate offshore capacity closest to London hyperscale data center demand, with the Crown Estate managing seabed leasing rounds. Grimsby and Hull anchor Operations and Maintenance port infrastructure, with Siemens Gamesa blade manufacturing facilities at Alexandra Dock supporting turbine supply chains.
Wales
Wales hosts Celtic Sea floating wind pilot arrays in water depths exceeding 60 meters off Pembrokeshire and Carmarthen Bay, with the Welsh Government's Net Zero Wales strategy targeting 20 GW offshore capacity. Port Talbot and Milford Haven are positioning for floating platform assembly through the Celtic Sea Freeport designation.
Northern Ireland
Northern Ireland's onshore wind resource in County Antrim and County Londonderry supports distributed generation, with the Department for the Economy administering renewable obligation certificate frameworks. Belfast Harbour clusters turbine component logistics for Irish Sea offshore zones.
United Kingdom Wind Energy Market Competitive Landscape
Top-tier vendors anchor turbine supply through integrated platform scale, while mid-tier developers compete on seabed origination speed and consenting expertise. The vendor base stratifies across three tiers: original equipment manufacturers with 15 MW+ offshore platforms, developer-specialists holding Crown Estate lease portfolios, and independent power producers relying on merchant offtake structures. Strategic moves concentrate on seabed lease accumulation and floating foundation technology licensing.
Within the integrated manufacturer tier, Siemens Gamesa and Vestas Wind Systems occupy positions defined by offshore platform modularity and onshore competitiveness respectively. Ørsted exemplifies the developer-specialist archetype through extensive seabed lease holdings in Scottish waters. These three entities represent distinct competitive vectors: manufacturing scale, technology breadth, and development pipeline depth.
| Leading Market Players |
|---|
| Siemens Gamesa |
| Vestas Wind Systems |
| GE Vernova |
| Nordex |
| Ørsted |
| EDP Renewables |
| Schroders Greencoat |
| Enercon UK |
| Goldwind |
| Others |
Value Network & Pricing Analysis
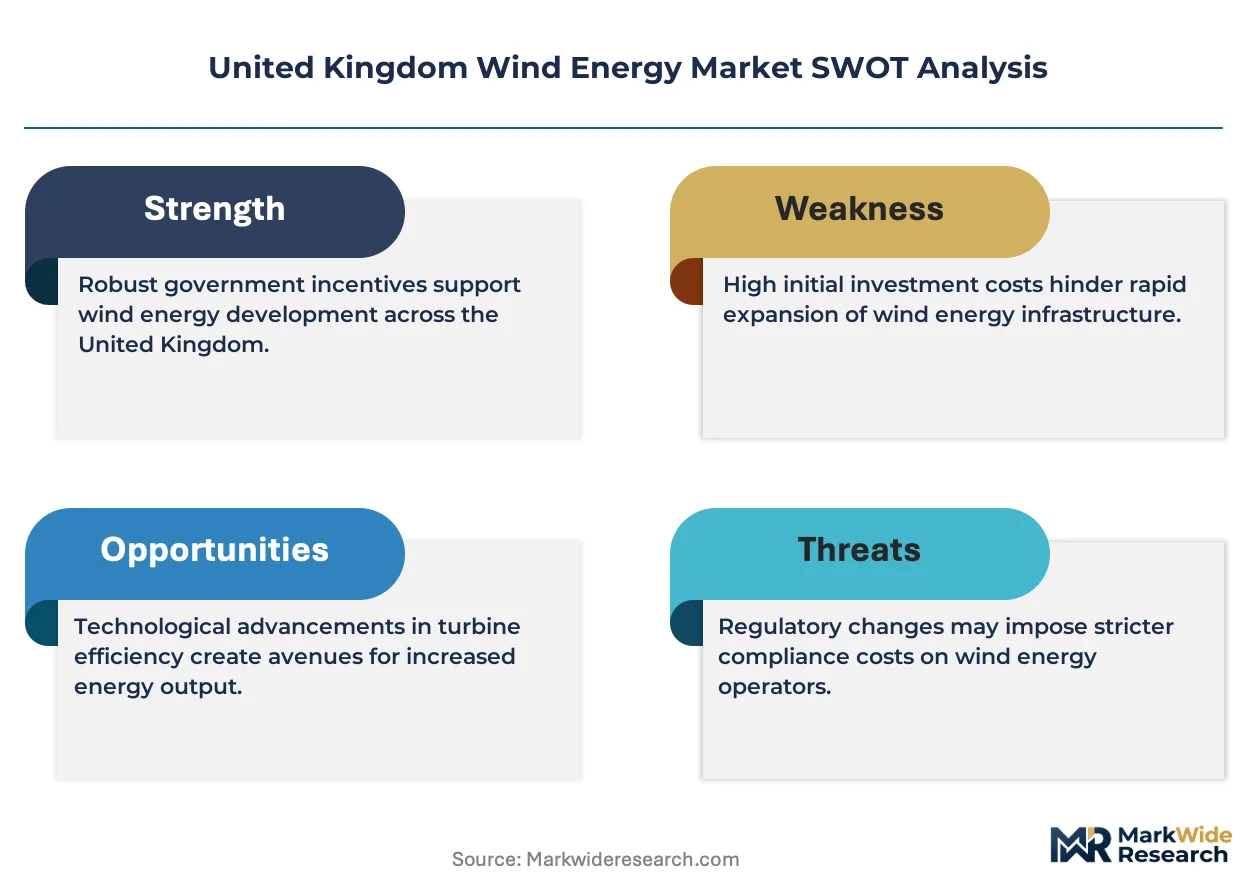
Sovereign wealth-backed developers and private-equity rolled-up IPPs anchor turbine procurement discipline, compressing supplier margins through consolidated offtake negotiations while passing steel and rare earth cost volatility into CfD strike-price bids.
Pricing Analysis
Lead-time-driven pricing premiums attach to nacelle assembly slots secured within eighteen-month construction windows, while spot inventory from Danish and German blade manufacturers trades at discounts reflecting demand cyclicality. Contract-based long-term offtake structures dominate, with price differentiation resting on turbine power rating tier and installation water depth classification. Cost compression in sub-10 MW fixed-bottom segments is intensifying because OEMs compete for Scottish seabed allocation volume. Corporate offtakers exhibit lowest price sensitivity due to sustainability procurement mandates, while merchant-exposed IPPs face acute margin pressure from wholesale price volatility.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for permanent magnet direct-drive generators, exposing turbine costs to export restriction risk. Manufacturing draws from Denmark, Germany, and Spain for nacelle assembly and blade fabrication, with steel plate and copper winding feedstock anchored in European mills. Supply chain risk centers on specialized heavy-lift jack-up vessel scarcity competing with offshore oil decommissioning demand. Distribution runs through Esbjerg, Rotterdam, and Scottish O&M ports for component staging and installation fleet mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom wind energy market sits in a technology-transition phase where 15 MW+ fixed-bottom platforms displace sub-10 MW legacy units, and floating foundation designs open deeper-water economics previously inaccessible to monopile structures.
For Market Incumbents: Acquire floating platform technology licenses from semi-submersible specialists to secure Celtic Sea first-mover positioning before Crown Estate leasing rounds accelerate. Consolidate Scottish seabed lease portfolios through farm-down arrangements with capital-constrained developers facing Ofgem grid connection queue compliance compression. Defend against merchant price exposure by locking corporate PPA tenors with data center operators ahead of CfD auction strike-price competition. For New Entrants and Emerging Players: Capture floating wind EPC specialization in Welsh and Cornish waters where established developers lack tension-leg platform installation experience. Target marine consenting advisory services as Marine Scotland streamlines Section 36 processes for Scottish offshore zones. Pursue electrolyzer co-location partnerships at offshore substations to monetize curtailed generation through green hydrogen offtake structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale IPPs with advanced-stage Scottish projects facing grid connection milestone compression under Ofgem reforms. Long-term viability over the coming decade rests on seabed lease accumulation velocity and turbine OEM relationship depth. Watch CfD auction strike-price floors as the inflection signal for developer margin recovery versus continued capital discipline.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Accumulation | Crown Estate and Marine Scotland allocation velocity determines project pipeline depth for Scottish and English zones. |
| Floating Platform Technology Licensing | Tension-leg and semi-submersible designs unlock Celtic Sea depths beyond fixed-bottom economic limits. |
| Corporate Power Purchase Agreements | Data center operators including Amazon Web Services and Microsoft unbundle energy from renewable obligation certificates. |
| Grid Connection Queue Compliance | Ofgem's connect-and-manage replacement forces financial close acceleration for Moray Firth and Firth of Forth clusters. |
| Green Hydrogen Offtake Integration | Electrolyzer co-location at offshore substations captures curtailed generation for synthetic fuel revenue streams. |
Research Methodology
Independent corroboration across developer financial disclosures, Crown Estate leasing round documentation, and Ofgem regulatory filings underwrites the qualitative findings. Primary interviews with IPP project developers, utility planning officers, EPC contractors, and turbine OEM procurement leads combined with secondary validation from SEC filings, project development databases, and IEA offshore wind reports. Bottom-up capacity addition modeling and top-down CfD auction allocation triangulation anchored the market sizing framework.
Comparable-period anchoring tied the projection horizon to historical installation cycles spanning the 2015-2024 offshore buildout wave. Segmentation dimensions modeled include technology class, power rating tier, end-user procurement structure, and regional grid type across the analysis window. CAGRs derived from unit economics trajectories incorporating turbine scale-up, foundation cost curves, and installation vessel day-rate assumptions. Forecast inputs incorporated Crown Estate leasing round schedules and Marine Scotland consenting timeline reforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel and rare earth input volatility, specialized vessel availability, and grid reinforcement lag. Deviation in CfD auction strike-price floors or Ofgem transmission access milestone enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
India Wind Industry Market