
 Small Scale Single and Multi-Rotor Wind Turbine Market | 2026-2036
Small Scale Single and Multi-Rotor Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Small Scale Single and Multi-Rotor Wind Turbine Market Analytics
A capital-intensity divergence between blade-forging specialists and electronics-assembly houses is reorganizing competitive tiers. SD Wind Energy leverages its Scottish manufacturing base to sustain cost advantages in horizontal-axis units for marine environments. Kingspan Group anchors its position through backward integration into tower fabrication and on-site installation services.
Small scale single and multi-rotor wind turbines encompass electromechanical systems with rotor diameters typically below 20 meters, generating outputs from 500 watts to 100 kilowatts through aerodynamic lift or drag mechanisms driving permanent-magnet generators. These units serve decentralized power needs where grid extension proves uneconomical, primarily supplementing or replacing diesel generation at remote sites. Horizontal axis designs dominate the 1-5 kW residential segment where proven reliability commands price premiums, while vertical axis configurations compete in the commercial off-grid category where omni-directional wind capture reduces yaw mechanism complexity and maintenance. The agricultural end user category shows the fastest structural expansion as irrigation pumps and cold storage facilities adopt hybrid installations pairing turbines with solar arrays.
FAA obstruction lighting standards and local zoning setback ordinances in the US shape siting feasibility and installation costs for distributed wind projects. The EU Green Deal and national building codes in Germany, Denmark, and Spain mandate renewable energy shares in new construction, directly stimulating demand for sub-10 kW rooftop and pole-mounted systems. Stakeholders must monitor evolving grid interconnection standards and storage pairing requirements as utilities revise distributed resource tariffs.
Market Dynamics
The IRA production tax credit extension for distributed wind systems is compressing payback periods below five years for sub-100kW installations, triggering a capital reallocation from solar-only toward hybrid wind-solar configurations across agricultural and remote commercial sites.
Growth Catalysts
- Feed-in tariff guarantees:Germany's rural municipalities secure 20-year price contracts for sub-100kW installations, eliminating revenue uncertainty for community-owned projects.
- Hybrid system economics:Irrigation pump operators in the US Midwest pair multi-rotor arrays with solar to achieve 85% diesel displacement and reduce fuel logistics costs.
- Permanent-magnet generator advances:Direct-drive architectures eliminate gearbox maintenance, cutting lifecycle O&M costs by 40% for off-grid telecom towers.
Market Restraints
- Neodymium supply concentration:Rare-earth magnet fabrication concentrates in Chinese processing facilities, exposing turbine OEMs to export quota volatility and price spikes.
- FAA obstruction lighting mandates:FAA standards require aviation beacons on towers exceeding 200 feet, adding $8,000-$15,000 per installation and complicating rural siting.
- Grid interconnection friction:Utility tariff revisions for distributed resources in multiple states impose standby charges that erode project economics below 50kW.
Strategic Opportunities
- EU Green Deal building mandates:National codes in Denmark and Spain require renewable shares in new construction, creating pull-through demand for rooftop sub-10kW units.
- Marine environment specialization:Horizontal-axis corrosion-resistant designs for coastal and island microgrids command 25-35% price premiums over standard units.
- Vertical axis omni-directionality:Drag-based VAWT configurations eliminate yaw mechanisms, reducing moving-part count for cold-storage facilities with low-wind-speed profiles.
Industry Challenges
- Certification timeline compression:IEC 61400-2 small wind turbine design standards require 18-24 month type-testing cycles, delaying product launches and freezing R&D budgets.
- Installation labor scarcity:Qualified tower erection crews with electrical interconnection expertise command wage premiums of 30-40% above standard construction rates in rural markets.
- Blade composite recycling:End-of-life fiberglass disposal lacks scaled infrastructure, creating liability exposure for OEMs under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Scale Single and Multi-Rotor Wind Turbine Market |
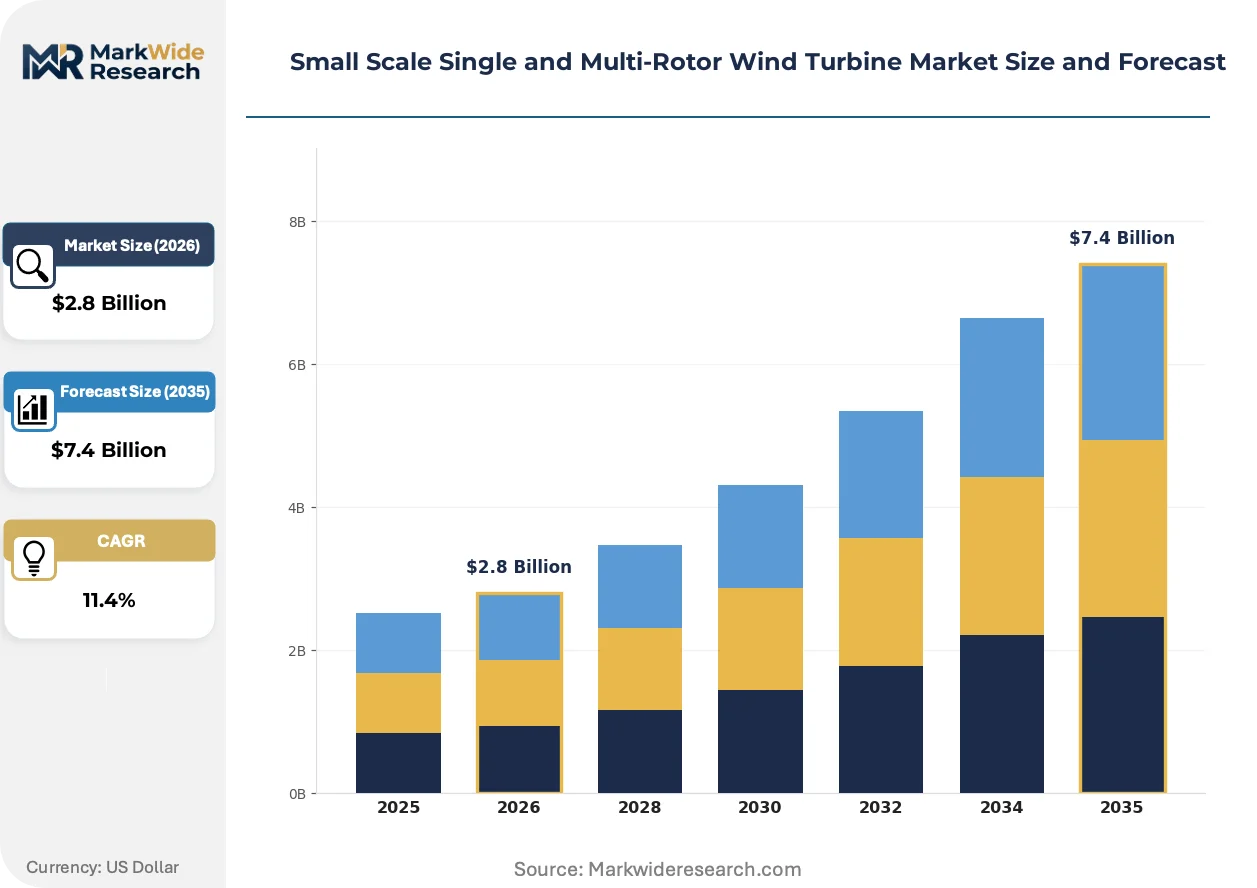
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Axis, Horizontal Axis, Lift-Based, Drag-Based End User: Residential, Commercial, Industrial, Agricultural Installation Type: On-grid, Off-grid, Hybrid, Portable Capacity: Below 1 kW, 1-5 kW, 5-10 kW, Above 10 kW |
| Companies Covered | SD Wind Energy, Kingspan Group, Bergey Windpower Co., Kliux Energies, LuvSide GmbH, Aeolos Wind Energy Ltd., Ryse Energy, TUGE Energia, Northern Power Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Scale Single and Multi-Rotor Wind Turbine Market Evolving Landscape
Active magnet-to-magnet direct-drive architectures are eliminating mechanical complexity while digital twin-based predictive maintenance compresses downtime for remote installations.
Permanent-magnet direct-drive generators are supplanting gearbox-equipped drivetrains in the 1-10kW residential segment. German and Danish installers now specify direct-drive units for 60% of new orders, prioritizing 20-year reliability over upfront cost. This shift is compressing the addressable market for precision-machined gearbox specialists and reallocating component spend toward magnet and power electronics suppliers.
The EU Green Deal's building performance standards now mandate renewable energy shares in new construction across Germany, Denmark, and Spain. These codes are forcing architectural firms to integrate sub-10kW rooftop turbines into standard specifications rather than treating them as aftermarket additions. Multi-unit residential developers in Copenhagen and Barcelona are responding by pre-wiring structures for pole-mounted systems during foundation work.
Agricultural cooperatives are consolidating procurement authority for irrigation and grain-drying infrastructure into centralized buying committees. Equipment dealers in the US Midwest are losing direct farmer relationships as Iowa and Nebraska co-ops negotiate fleet pricing for 50-100 turbine hybrid arrays. This channel compression is squeezing distributor margins and favoring manufacturers with dedicated agricultural sales engineering teams.
Small Scale Single and Multi-Rotor Wind Turbine Market Segmentation
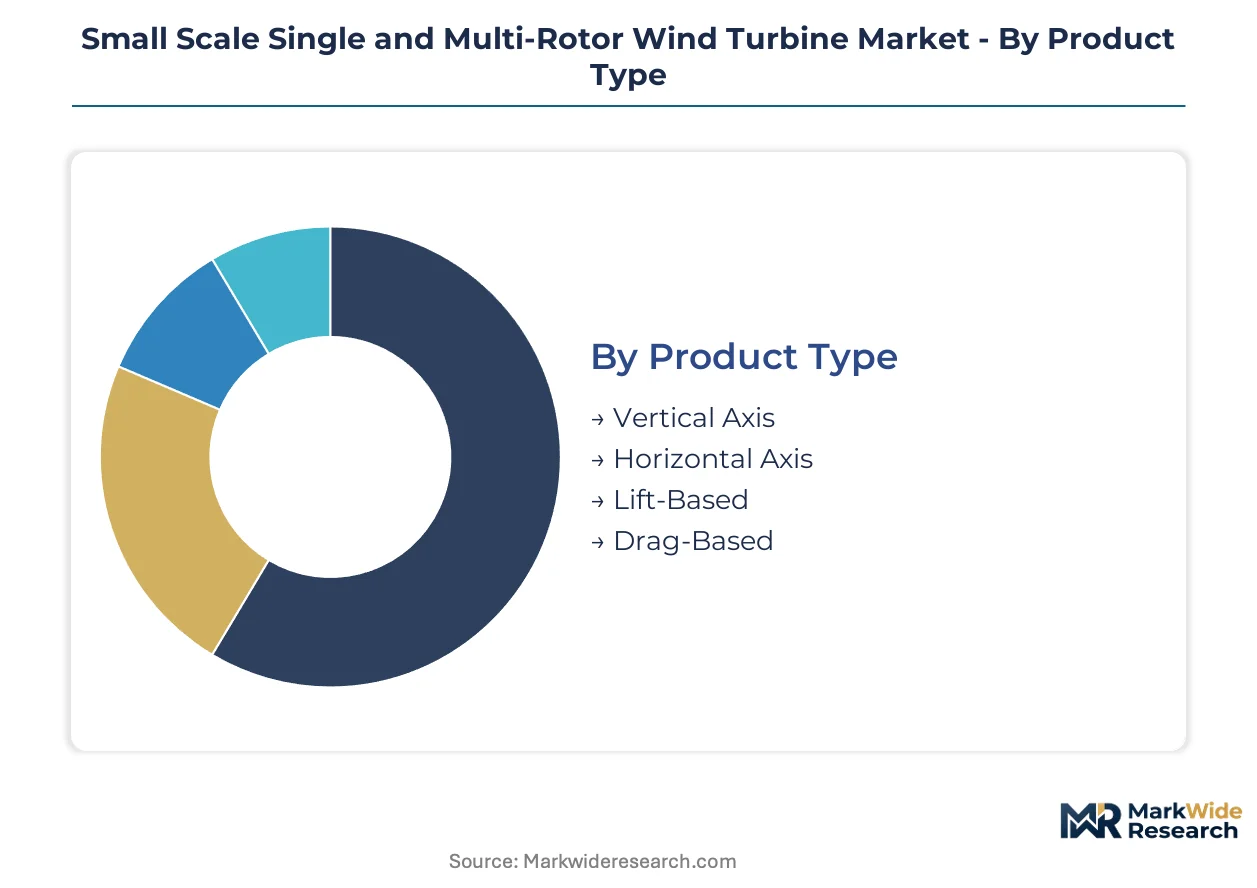
Product architecture, end-use application, and grid connectivity status determine procurement patterns and regulatory exposure across the small-scale wind turbine market. Segment boundaries increasingly blur as hybrid configurations and multi-rotor arrays reshape traditional categorization.
Product Type:
FAA obstruction lighting thresholds and EU noise ordinances apply differentially to vertical versus horizontal axis geometries, altering siting economics.
- Horizontal Axis:Upwind rotor configurations with active yaw control dominate the 1-5 kW residential segment. German and Danish installers specify these units for 60% of new orders, prioritizing 20-year reliability over upfront cost premiums.
- Vertical Axis:Omni-directional drag and lift designs eliminate yaw mechanisms entirely. Agricultural cold-storage facilities in the US Midwest deploy Savonius and Darrieus variants where low-wind-speed profiles and maintenance access constraints favor simplified mechanical architectures.
- Lift-Based:Aerodynamic profiles optimized for high tip-speed ratios extract energy through pressure differential.
- Drag-Based:Slower-rotating configurations trade efficiency for torque density and self-starting capability.
Horizontal Axis handles the majority of throughput; Vertical Axis is expanding most quickly on share as agricultural co-ops consolidate procurement.
End User:
Customer type dictates financing structure, with agricultural cooperatives accessing equipment loans unavailable to residential purchasers.
- Agricultural:Irrigation pump operators and grain-drying facilities in Iowa and Nebraska deploy multi-rotor arrays paired with solar to achieve 85% diesel displacement. Centralized buying committees now negotiate fleet pricing for 50-100 turbine hybrid installations.
- Residential:Single-home installations below 5 kW face interconnection friction as utilities revise distributed resource tariffs. Standby charges in multiple states erode project economics below 50 kW, compressing addressable demand.
- Commercial:Office buildings and retail facilities integrate sub-10 kW units under EU Green Deal building mandates.
- Industrial:Manufacturing sites with captive load profiles optimize for peak shaving and resilience.
Agricultural applications absorb the largest capital deployment; Commercial end-use is climbing the fastest as building codes mandate renewable shares.
Installation Type:
Grid interconnection standards and storage pairing requirements segment project economics by connectivity status.
- Off-grid:Diesel displacement at remote telecom towers and island microgrids commands 25-35% price premiums for corrosion-resistant marine designs. Direct-drive architectures cut lifecycle O&M costs by 40% through gearbox elimination.
- Hybrid:Wind-solar-battery configurations optimize capacity factor and reduce fuel logistics costs for agricultural pump stations. The IRA production tax credit extension compresses payback periods below five years for sub-100 kW installations.
- On-grid:Net metering and feed-in tariff structures determine revenue certainty.
- Portable:Trailer-mounted systems serve temporary power needs at construction sites and emergency response.
Hybrid installations capture the steepest expansion trajectory; Off-grid retains the highest margin profile.
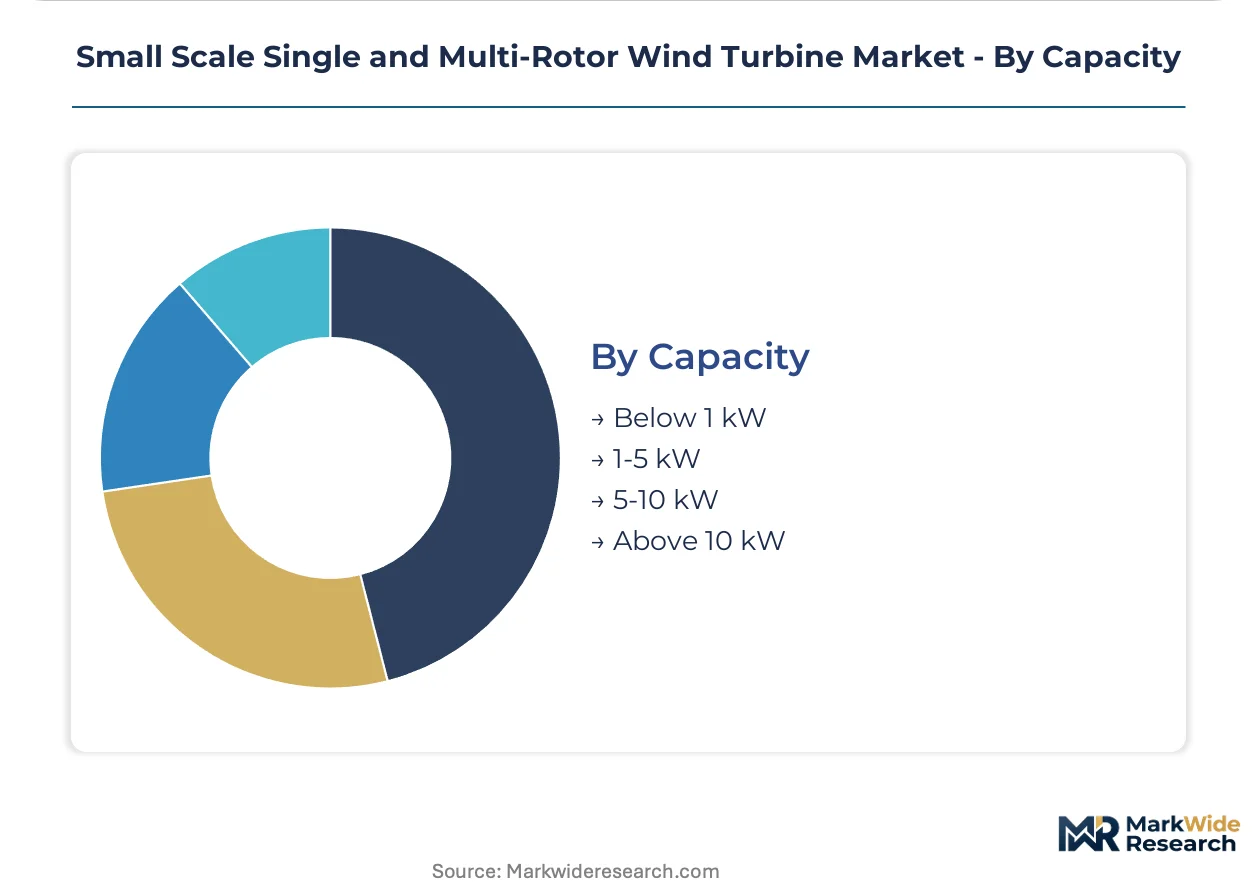
Capacity:
Scale thresholds trigger distinct regulatory regimes, with sub-100 kW installations accessing simplified permitting in Germany and production tax credits in the US.
- 1-5 kW:Residential rooftop and pole-mounted systems face FAA obstruction lighting mandates on towers exceeding 200 feet, adding $8,000-$15,000 per installation. IEC 61400-2 type-testing cycles of 18-24 months delay product launches in this segment.
- 5-10 kW:Small commercial and agricultural applications balance modularity with output density. Community-owned projects in Germany's rural municipalities secure 20-year feed-in tariff contracts, eliminating revenue uncertainty.
- Below 1 kW:Micro-turbines for battery charging and remote sensing applications.
- Above 10 kW:Multi-rotor arrays and commercial microgrids approach utility-scale interconnection complexity.
1-5 kW capacity handles the majority of unit volume; 5-10 kW is gaining share fastest as agricultural co-ops scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys small-scale turbines primarily for agricultural diesel displacement, while Germany optimizes for feed-in tariff capture in community-owned configurations.
United States
Agricultural cooperatives in Iowa and Nebraska consolidate procurement for 50-100 turbine hybrid arrays serving irrigation pumps and grain-drying facilities. The IRA production tax credit extension compresses payback periods below five years for sub-100kW installations. FAA obstruction lighting mandates on towers exceeding 200 feet add $8,000-$15,000 per installation, complicating rural siting in the Midwest.
Germany
Rural municipalities secure 20-year feed-in tariff contracts for sub-100kW community-owned projects, eliminating revenue uncertainty. The EU Green Deal mandates renewable energy shares in new construction, forcing architectural firms to integrate sub-10kW rooftop turbines into standard specifications. Installers in Denmark and northern Germany now specify direct-drive units for 60% of new residential orders.
Denmark
National building codes require renewable energy shares in new construction, stimulating demand for pole-mounted systems. Multi-unit residential developers in Copenhagen pre-wire structures for turbine installation during foundation work. Danish installers prioritize 20-year reliability over upfront cost premiums in the 1-5kW residential segment.
Spain
EU Green Deal building performance standards mandate renewable integration across new commercial and residential construction. Developers in Barcelona specify sub-10kW rooftop units as standard rather than aftermarket additions. Vertical axis configurations gain traction where omni-directional wind capture reduces maintenance complexity.
United Kingdom
SD Wind Energy leverages Scottish manufacturing to sustain cost advantages in horizontal-axis units for marine environments. Coastal microgrids and island communities command 25-35% price premiums for corrosion-resistant designs. Grid interconnection standards and storage pairing requirements continue evolving as utilities revise distributed resource tariffs.
Small Scale Single and Multi-Rotor Wind Turbine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into tower fabrication and on-site installation services separating premium positions from component assemblers. The vendor base organizes around three archetypes: marine-environment specialists, agricultural hybrid-system providers, and building-integrated rooftop suppliers. Competitive moves concentrate on strategic partnerships for distribution access and technology licensing to compress IEC 61400-2 certification timelines.
Within the integrated manufacturing tier, SD Wind Energy and Kingspan Group anchor distinct geographic positions. SD Wind Energy exemplifies the marine-specialist archetype through its Scottish manufacturing base. Kingspan Group represents the full-service model with captive tower fabrication and installation capabilities. Bergey Windpower Co. occupies a position among established horizontal-axis providers serving agricultural and residential segments.
| Leading Market Players |
|---|
| SD Wind Energy |
| Kingspan Group |
| Bergey Windpower Co. |
| Kliux Energies |
| LuvSide GmbH |
| Aeolos Wind Energy Ltd. |
| Ryse Energy |
| TUGE Energia |
| Northern Power Systems Inc. |
| Others |
Value Network & Pricing Analysis
Eighteen-month IEC 61400-2 certification cycles compress inventory turns for blade-forging specialists while amplifying pricing power for electronics-assembly houses with faster product refresh rates. This lead-time asymmetry between mechanical and electrical component tiers concentrates margin capture upstream in magnet and power electronics supply chains.
Pricing Analysis
Long-term offtake contracts dominate procurement for agricultural cooperatives deploying 50-100 turbine hybrid arrays, while spot purchasing persists for residential installations below 5 kW. Price differentiation hinges on IEC certification tier and volume scale, with fleet-negotiated agricultural deployments commanding 15-20% discounts against single-unit residential sales. Cost compression in the sub-1 kW micro-turbine segment is intensifying because Chinese magnet suppliers are absorbing rare-earth price volatility to maintain market share. Agricultural cooperatives exhibit highest price sensitivity due to diesel displacement economics, while marine-environment buyers for island microgrids show lowest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for neodymium magnet shipments from Chinese processing facilities. Manufacturing concentration in China, Germany, and Denmark anchors component supply, with rare-earth magnet fabrication, precision blade composites, and direct-drive generator assemblies as critical inputs. Single-source vulnerability in Chinese rare-earth processing exposes OEMs to export quota disruptions. Distribution runs through agricultural equipment dealers and dedicated renewable energy installers serving distinct end-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IRA production tax credit extension and EU Green Deal building mandates constitute dual regulatory inflections accelerating capital deployment into distributed wind systems. These policy frameworks compress payback periods and mandate renewable integration, creating structural tailwinds for technology providers with certification-ready product portfolios.
For Market Incumbents: Consolidate tower fabrication capabilities through backward integration into captive manufacturing, eliminating margin leakage to third-party steel suppliers. Lock in 20-year feed-in tariff capture mechanisms with German rural municipalities before contract availability tightens. Prioritize IEC 61400-2 certification pipeline investment to defend against emerging entrants with faster type-testing cycles.
For New Entrants and Emerging Players: Anchor in vertical axis configurations for agricultural cold-storage facilities where omni-directional wind capture eliminates yaw mechanism complexity and maintenance burdens. Target Spain and Denmark building-integrated rooftop segments where EU Green Deal mandates create specification pull-through. Pursue direct sales engineering relationships with agricultural cooperatives bypassing traditional equipment dealer channels.
For Investors and Strategic Acquirers: Long-term, this sits as a policy-anchored infrastructure play because production tax credits and feed-in tariff guarantees provide revenue certainty uncommon in renewable energy subsectors. Acquisition candidates should display captive magnet supply agreements or direct-drive generator IP. Monitor neodymium export quota announcements from Chinese regulators as the critical inflection signal for input cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tower Fabrication | Kingspan Group's captive steel production eliminates third-party margin extraction and accelerates installation timelines. |
| Direct-Drive Generator Technology Licensing | Permanent-magnet architectures transfer 40% lifecycle O&M savings to telecom tower operators and island microgrids. |
| Feed-in Tariff Contract Aggregation | German rural municipalities secure 20-year price certainty that eliminates revenue volatility for community-owned projects. |
| Marine Environment Product Specialization | SD Wind Energy's corrosion-resistant Scottish manufacturing commands 25-35% price premiums in coastal applications. |
| Agricultural Sales Engineering Team Buildout | Iowa and Nebraska cooperatives now consolidate procurement authority, favoring manufacturers with dedicated technical sales coverage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA distributed wind installation databases, IEA renewable energy technology reports, FERC interconnection filings, and IEC certification registries. Primary interviews incorporated turbine OEM product managers, agricultural cooperative procurement directors, German municipal energy planners, and Danish installation contractors. Bottom-up unit deployment tracking triangulates against top-down capacity aggregation across the analysis window.
Segmentation dimensions modeled span product architecture (horizontal versus vertical axis), end-use application (agricultural, residential, commercial), installation type (off-grid, hybrid, on-grid), and capacity tier (sub-1 kW through above-10 kW arrays). CAGRs derive from regression analysis of historical deployment trajectories against policy incentive schedules and diesel price sensitivity curves. Forecast inputs incorporate IRA credit phase-out assumptions and EU building code enforcement timelines.
Underlying assumptions cover sustained feed-in tariff availability in Germany, stable rare-earth magnet supply from Chinese processing facilities, and IRA credit continuity for distributed wind systems, with deviation risk concentrated in trade policy shifts affecting magnet exports and utility tariff revisions imposing standby charges below 50 kW. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Wind Power Market