
 Canada Wind Energy Market | 2026-2036
Canada Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Wind Energy Market Analysis
Market Context
Utility procurement is restructuring from single-source power purchase agreements toward multi-source renewable portfolios. Brookfield Renewable Partners leverages its existing hydro-wind hybrid platform to secure long-term contracts across Ontario and Quebec. Boralex anchors its growth strategy in Quebec's community wind segment, while Northland Power Inc. competes through offshore development expertise applied to Great Lakes projects.
Technical Definition and Structural Segments
Canada wind energy encompasses the generation of electricity from kinetic wind resources through horizontal-axis and vertical-axis turbine systems, typically involving rotor diameters exceeding 80 meters and hub heights of 80-120 meters to capture consistent atmospheric flows for grid-connected power delivery. The technology segment splits between mature onshore installations dominating current capacity and nascent offshore development representing future pipeline growth. By end user, utilities command the largest share of contracted capacity while independent power producers capture margin pools through merchant exposure and renewable energy credit monetization.
Regulatory Framework and Outlook
Health Canada conducts electromagnetic field and noise impact assessments under federal environmental legislation, while Environment and Climate Change Canada enforces migratory bird and species-at-risk protections that directly constrain turbine siting and operational protocols. The Canadian Environmental Assessment Agency coordinates provincial-federal jurisdictional overlap for interprovincial transmission-linked projects. Stakeholders must monitor evolving carbon pricing stringency and provincial renewable portfolio standard revisions to anticipate contract renewal economics and green credit valuations.
Market Dynamics
Alberta and Saskatchewan utilities are accelerating wind procurement through competitive auctions that reward lowest-cost renewable generation, compressing developer margins while expanding project pipelines across the Prairie provinces.
Growth Catalysts
- Carbon pricing escalation:Federal carbon pricing mechanisms raise the cost-competitiveness threshold for wind against fossil baseload, incentivizing utility-scale substitution in coal-dependent grids.
- Transmission expansion:Hydro-Québec and provincial Crown corporations are extending high-voltage corridors into wind-rich zones, reducing curtailment risk for remote project sites.
- Corporate renewable procurement:Mining and oil sands operators are contracting direct wind supply to meet Scope 2 emissions targets under sustainability-linked financing covenants.
Market Restraints
- Steel and rare earth input volatility:Turbine tower and permanent magnet supply chains face price pressure from concentrated Chinese processing capacity.
- Interconnection queue congestion:Provincial grid operators in Ontario and Alberta report multi-year backlogs for new generator interconnection studies.
- Species-at-risk habitat restrictions:Environment and Climate Change Canada designates critical habitat zones that exclude turbine placement in southern Saskatchewan grasslands.
Strategic Opportunities
- Offshore Great Lakes development:Ontario's shallow-water sites offer untapped capacity potential with higher capacity factors than onshore Prairie resources.
- Indigenous partnership structures:Equity participation frameworks enable First Nations to capture revenue streams from projects on traditional territories.
- Green hydrogen co-location:Electrolyzer integration at wind farms allows merchant producers to arbitrage power price volatility through molecule sales.
Industry Challenges
- Specialized technician scarcity:Blade repair and high-voltage maintenance skills lag project construction timelines, extending commissioning schedules.
- Aviation radar mitigation costs:Transport Canada mandates turbine-visibility systems near military flight corridors, adding unrecoverable capex to affected sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Wind Energy Market |
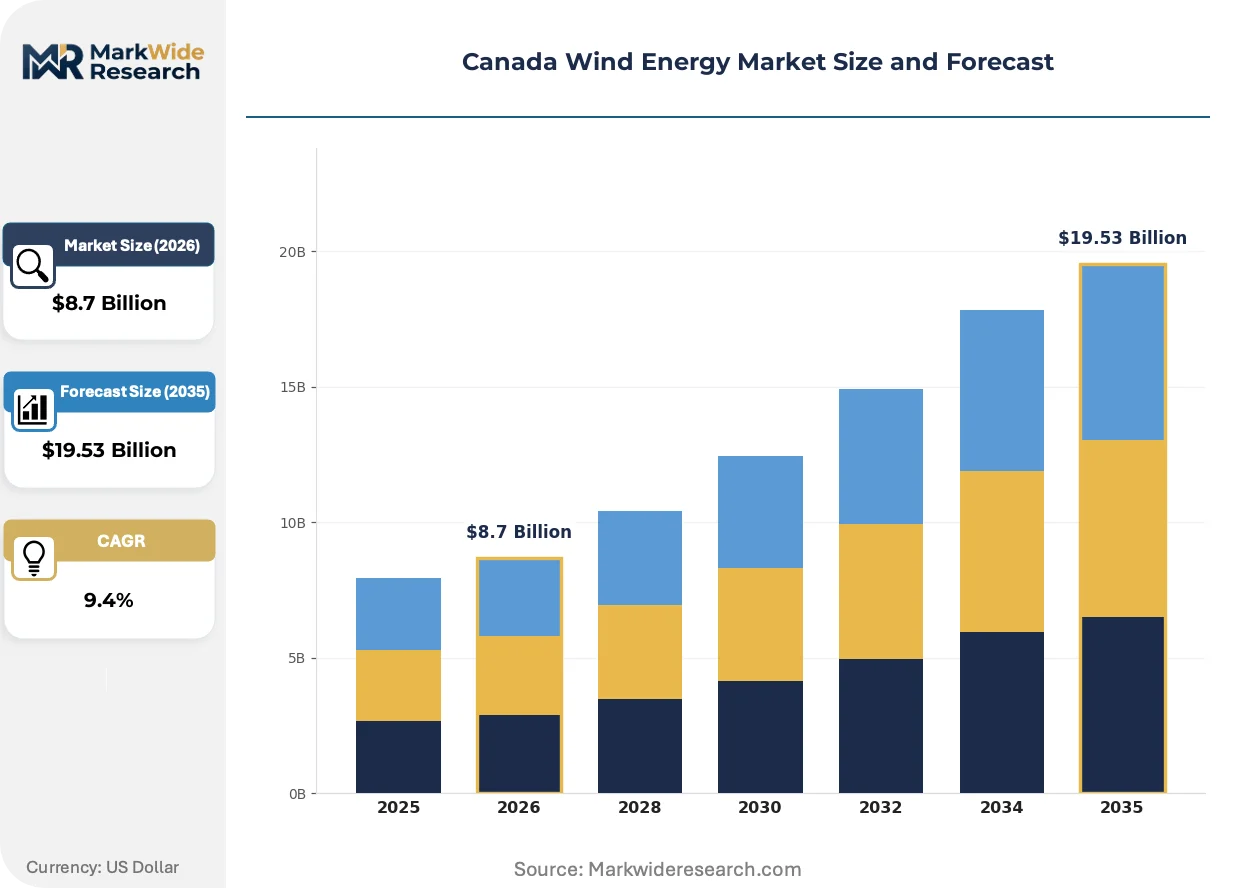
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Independent Power Producers, Government, Industry Component: Turbine, Generator, Blade, Tower Application: Electricity Generation, Power Plants, Hybrid Systems, Others |
| Companies Covered | Brookfield Renewable Partners, Boralex, Siemens Gamesa Renewable Energy, Northland Power Inc., Capital Power Corporation, General Electric Company, TransAlta Corporation, Innergex Renewable Energy, Vestas Wind Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Wind Energy Market Emerging Trajectories
Digitalization of turbine operations and evolving procurement mechanisms are compressing operational expenditure structures while reshaping how developers secure long-term revenue certainty.
Advanced blade monitoring systems using fiber-optic strain sensors and ice detection algorithms are automating operational decision-making at remote Canadian sites. TransAlta and Capital Power are deploying these systems across their Alberta fleets to reduce unplanned maintenance dispatch. The technology is automating condition-based maintenance scheduling, collapsing the traditional time-based inspection cycle from quarterly to event-triggered interventions.
Environment and Climate Change Canada is tightening migratory bird collision mitigation requirements through mandatory radar-activated curtailment protocols. Developers must now install automated detection systems that trigger turbine shutdowns during high-risk migration periods. The policy most affects projects in the Prairie pothole region, where proponents are pre-emptively siting turbines outside major flyway corridors to avoid operational penalties.
Utility buyers are consolidating renewable procurement into multi-technology portfolios rather than single-source wind contracts. Alberta's balancing pool and Saskatchewan Power are requesting bundled wind-solar-storage proposals that shift developer risk onto output guarantees. This restructuring concentrates in provinces with high renewable penetration targets, where utilities seek firm deliverability over pure energy volume.
Canada Wind Energy Market Segmentation
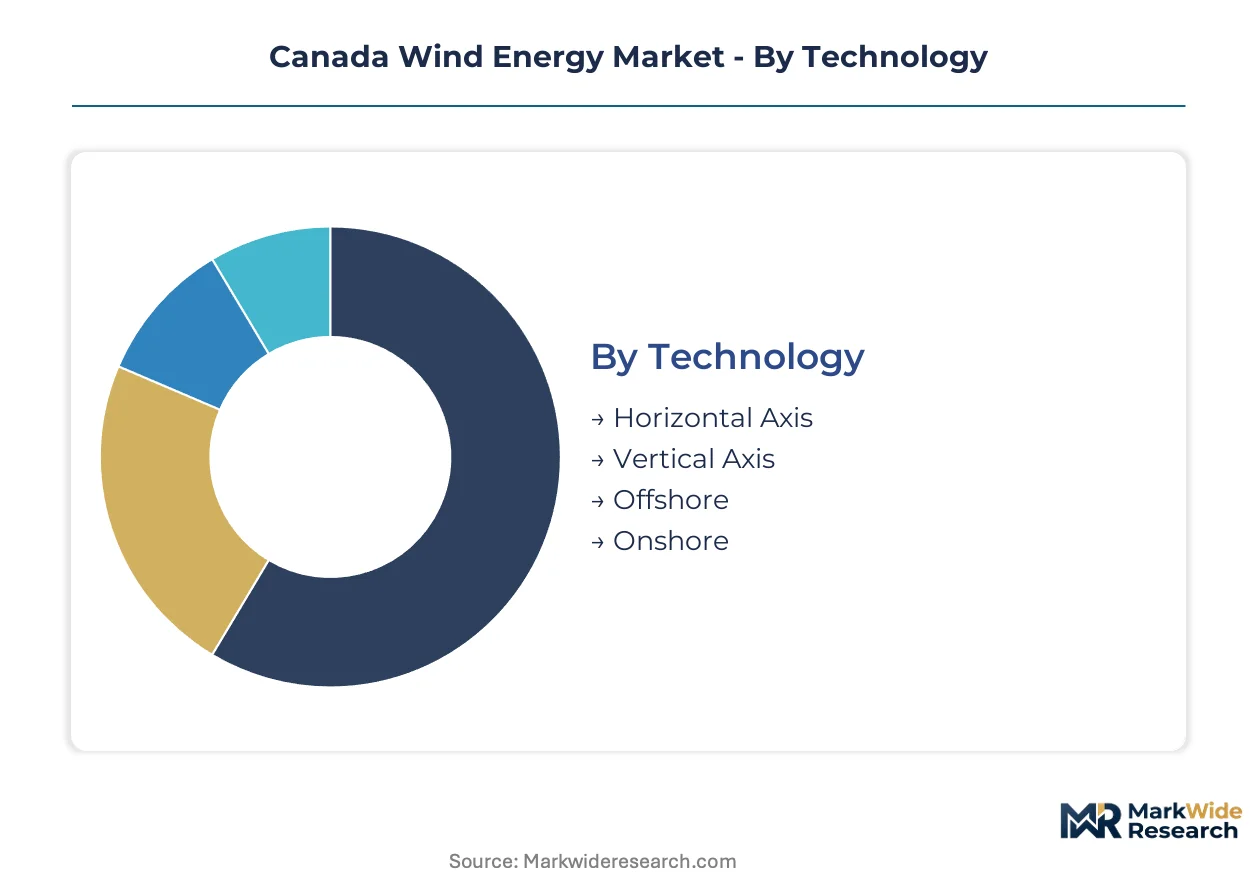
Segmentation in the Canada wind energy market reveals distinct regulatory pathways, procurement patterns, and technical specifications that determine project economics across provincial jurisdictions. Understanding these divides enables developers to align certification requirements with site-specific resource profiles and buyer risk appetites.
Technology:
Health Canada electromagnetic field assessments and Environment and Climate Change Canada species-at-risk protocols apply differentially across turbine configurations, with offshore installations triggering additional federal marine jurisdiction reviews.
- Horizontal Axis:Dominant three-blade upwind designs with rotor diameters exceeding 100 meters capture Prairie wind resources at hub heights of 80-120 meters. Alberta and Saskatchewan utilities specify these configurations for utility-scale procurement auctions due to proven capacity factors and established O&M protocols.
- Onshore:Mature installations account for existing capacity across Ontario, Quebec, and the Prairie provinces, with standardized permitting under provincial environmental assessment frameworks. Transmission interconnection queues in Alberta and Ontario currently constrain new onshore project timelines.
- Vertical Axis:Darrieus and Savonius variants serve distributed generation applications where lower hub heights avoid aviation radar conflicts. Community wind projects in Quebec favor these systems for reduced visual impact and simpler municipal approvals.
- Offshore:Fixed-bottom and floating platform designs targeting Great Lakes sites require Transport Canada navigation safety clearances and federal environmental assessments under the Canadian Environmental Assessment Act.
Leading the category by volume: Onshore. Expanding most quickly: Offshore.
End User:
Procurement risk allocation varies sharply across buyer types, with utilities demanding long-term output guarantees while merchant operators absorb price volatility for margin capture.
- Utilities:Crown corporations and provincial balancing pools structure competitive auctions favoring lowest levelized cost of energy, compressing developer returns while securing 20-25 year contract tenors. Saskatchewan Power and Alberta's balancing pool dominate contracted capacity.
- Independent Power Producers:Merchant developers monetize renewable energy credits and capture wholesale price spreads through Alberta's deregulated market, exposing revenues to carbon pricing trajectory and natural gas price volatility.
- Government:Federal and provincial entities procure wind for remote community diesel displacement and federal facility renewable targets, with Indigenous Services Canada funding on-reserve generation.
- Industry:Mining and oil sands operators contract direct renewable supply to satisfy Scope 2 emissions targets under sustainability-linked credit facilities, with Teck Resources and Suncor executing corporate PPAs.
Utilities command the largest share of contracted megawatts. Independent power producers are climbing the fastest as merchant exposure becomes economically viable under escalating carbon prices.
Component:
Supply chain concentration and domestic content requirements from provincial procurement rules shape component sourcing strategies.
- Turbine:Nacelle assemblies integrating drivetrain, gearbox, and control systems represent the highest-value import, with Vestas and Siemens Gamesa dominating supply to Canadian projects.
- Blade:Fiberglass-reinforced epoxy structures exceeding 70 meters in length face specialized logistics constraints, with LM Wind Power operating a manufacturing facility in Quebec serving regional demand.
- Tower:Steel tubular sections sourced from domestic fabricators in Ontario and Quebec benefit from provincial content preferences in renewable procurement auctions.
- Generator:Permanent magnet synchronous machines depend on rare earth supply chains concentrated in Chinese processing capacity, exposing projects to input price volatility and trade policy risk.
Tower and blade segments lead by domestic manufacturing presence. Generator sourcing faces the steepest supply concentration challenges.
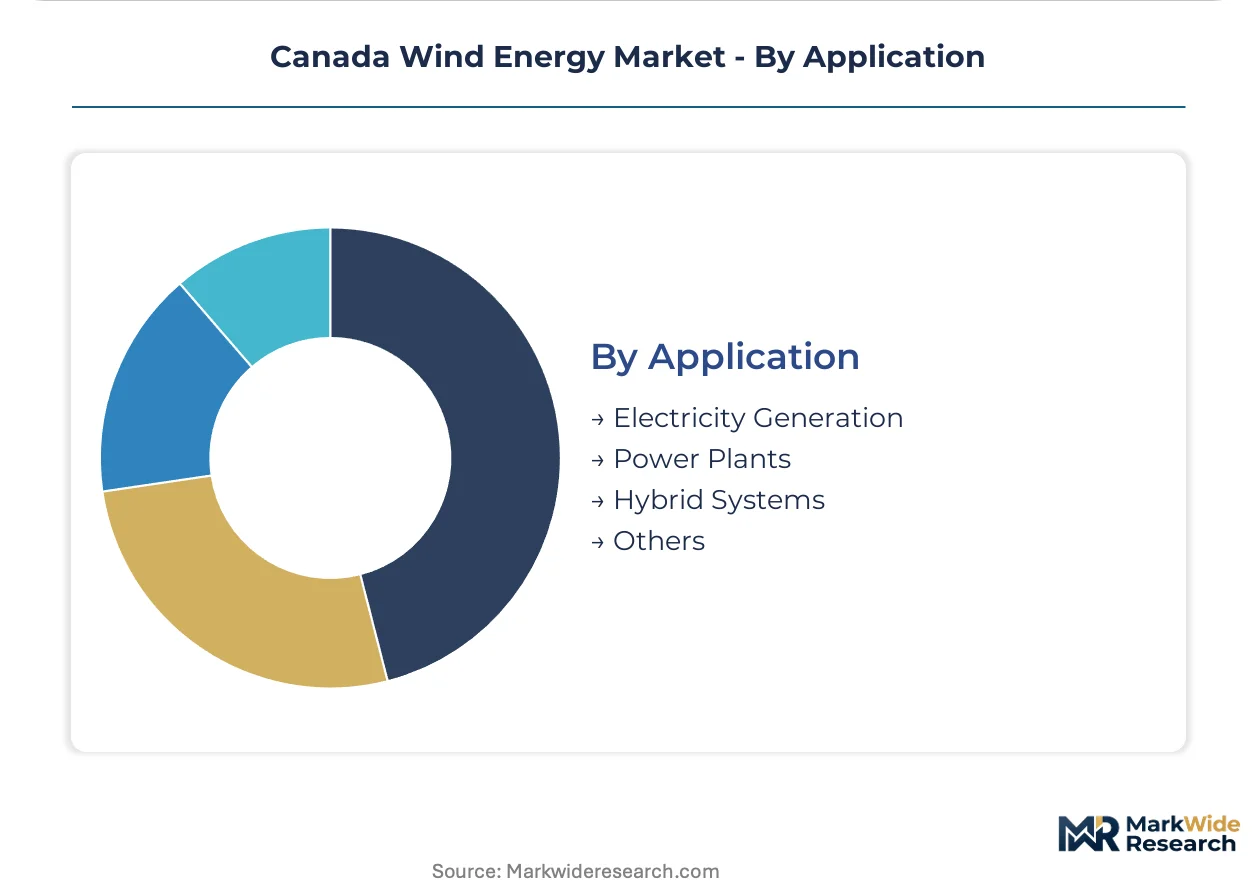
Application:
System integration requirements determine grid connection complexity and revenue stream diversification for project developers.
- Electricity Generation:Grid-connected bulk power supply dominates provincial renewable portfolio standard compliance, with Alberta and Saskatchewan procurement targeting pure wind energy deliveries.
- Hybrid Systems:Wind-solar-battery configurations respond to utility requests for firm deliverability, with TransAlta and Capital Power developing co-located assets to reduce output variability penalties.
- Power Plants:Dedicated generation facilities serving single off-takers through behind-the-meter arrangements, common in remote mining operations lacking grid access.
- Others:Emerging applications including direct air capture co-location and green hydrogen electrolysis integration at Alberta wind farms.
Electricity generation retains dominant volume. Hybrid systems are gaining share fastest as storage economics improve and utilities prioritize dispatchable renewable output.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prairie wind corridors and Great Lakes shorelines anchor provincial development patterns, with resource quality and transmission access determining project economics across Canadian jurisdictions.
Alberta
Alberta's deregized power market attracts merchant developers seeking wholesale price exposure, with the balancing pool structuring competitive renewable auctions. Environment and Climate Change Canada enforces species-at-risk protocols across southern grasslands, constraining siting in critical habitat zones. The Pincher Creek corridor hosts the province's densest turbine concentration, where TransAlta and Capital Power operate utility-scale fleets.
Quebec
Quebec's Crown procurement favors wind-hydro hybrid configurations that leverage existing reservoir flexibility for grid balancing. Health Canada electromagnetic field assessments apply to community-scale projects near populated areas. The Gaspé Peninsula and Matane regions concentrate development activity, where Boralex anchors its community wind partnership model with First Nations equity participation.
Ontario
Ontario's procurement shift toward firm deliverability requirements drives wind-solar-storage bundling in utility solicitations. Transport Canada mandates aviation radar mitigation systems near military flight corridors, adding capex to projects in the Great Lakes basin. The Bruce Peninsula and eastern Lake Erie shorelines host the province's operational capacity, with Northland Power pursuing offshore demonstration permits.
Saskatchewan
Saskatchewan Power's integrated resource planning targets wind penetration to displace coal baseload, with Crown procurement favoring lowest-cost renewable bids. Environment and Climate Change Canada designates critical habitat for migratory birds across the Prairie pothole region, excluding turbine placement in designated zones. The Swift Current and Cypress Hills areas concentrate development, where SaskPower holds interconnection queue priority for approved projects.
Atlantic Canada
Atlantic provincial utilities procure wind for diesel displacement in remote communities and grid-connected renewable targets. Indigenous Services Canada funds on-reserve generation through targeted capital programs. Newfoundland and Labrador's western coast and Nova Scotia's Wentworth Valley host operational projects, where Emera and provincial Crown corporations structure power purchase agreements.
Canada Wind Energy Market Vendor Landscape
Long-term contract origination dominates the current landscape, with developers competing for utility procurement tenors that secure project finance. The market structures around three player tiers: integrated renewable utilities with existing generation portfolios, independent power producers with merchant market exposure, and global turbine OEMs supplying equipment under service agreements. Strategic archetypes include hybrid platform operators leveraging hydro assets for grid services, community wind specialists embedding Indigenous equity structures, and offshore developers positioning for Great Lakes pipeline conversion. Competitive intensity concentrates on auction participation discipline and interconnection queue positioning.
Among integrated Canadian renewable utilities, Brookfield Renewable Partners and Northland Power occupy positions spanning provincial markets and technology configurations. TransAlta Corporation exemplifies the hybrid platform archetype, combining Alberta wind fleets with hydroelectric storage assets to deliver firm capacity. Boralex represents the community wind specialization model, embedding First Nations partnership structures within Quebec project economics. These three players anchor the competitive field, with their divergent geographic and contractual strategies illustrating the market's strategic segmentation.
| Leading Market Players |
|---|
| Brookfield Renewable Partners |
| Boralex |
| Siemens Gamesa Renewable Energy |
| Northland Power Inc. |
| Capital Power Corporation |
| General Electric Company |
| TransAlta Corporation |
| Innergex Renewable Energy |
| Vestas Wind Systems |
| Others |
Supply Flow & Price Mechanics
Specialized wind turbine technician scarcity in southern Alberta and Saskatchewan compresses labor-cost differentials between premium OEM service contracts and independent O&M providers, widening pricing-tier spreads for long-term service agreements.
Pricing Analysis
Warranty bundling distinguishes pricing tiers, with comprehensive 15-year service agreements commanding premiums over unbundled equipment-only sales. Three-tier pricing structure across premium, standard, and economy levels reflects turbine capacity rating, grid-code certification tier, and after-sales coverage depth. Cost compression in the standard tier is intensifying because provincial utilities consolidate procurement into multi-technology portfolios with stringent output guarantees. Merchant independent power producers exhibit highest price sensitivity, while Crown corporations with rate-base recovery mechanisms absorb premium pricing for reliability assurance.
Supply Chain Analysis
Dual-sourcing mandates from Saskatchewan Power and Alberta's balancing pool require developers to qualify multiple turbine suppliers, fragmenting procurement volumes across Vestas, Siemens Gamesa, and GE. Manufacturing concentrates in Denmark, Spain, and China, with nacelle assemblies and blade molds drawing from European engineering centers while steel towers source from Ontario and Quebec fabricators. Rare earth permanent magnet supply rests on Chinese processing capacity, exposing projects to tariff escalation and export restriction risk. Distribution runs through provincial Crown corporation procurement auctions and corporate PPA direct negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interconnection queue congestion across Alberta and Ontario grids functions as the binding capacity constraint, sustaining developer pricing power despite competitive auction pressure.
For Market Incumbents: Anchor hybrid platform positions by accelerating wind-solar-battery co-location at existing sites before transmission access tightens further. Secure interconnection queue priority through early-stage deposits with provincial grid operators. Counter merchant margin erosion from carbon price volatility by expanding contracted capacity with Crown corporations.
For New Entrants and Emerging Players: Capture Indigenous partnership structures in Quebec and Atlantic Canada where equity participation frameworks lower development risk. Target community wind segments with vertical-axis configurations that bypass aviation radar conflicts constraining horizontal-axis sites. Pursue green hydrogen co-location opportunities at Alberta wind farms to arbitrage power price volatility.
For Investors and Strategic Acquirers: The window for entry favors developers with secured interconnection positions and long-term offtake contracts. Evaluate targets through the lens of contracted revenue visibility versus merchant exposure balance. Watch for federal carbon pricing stringency adjustments as the inflection signal for green credit valuation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Long-term offtake contracts with Saskatchewan Power secure project finance and reduce merchant risk exposure. |
| Capacity Buildout | Great Lakes offshore demonstration permits position developers for higher capacity factor resources than Prairie onshore sites. |
| Vertical Integration into Storage | Wind-solar-battery hybrid configurations respond to utility firm deliverability requirements and reduce output variability penalties. |
| Technology Licensing | Advanced blade monitoring systems from fiber-optic sensor providers automate condition-based maintenance and collapse inspection cycles. |
| Green Certification Program | Environment and Climate Change Canada radar-activated curtailment protocols require certified collision mitigation systems for Prairie projects. |
Methodological Framework
Multi-period observation of interconnection queue depths, provincial auction clearing prices, and Crown corporation procurement schedules anchored the trend analysis, supplemented by interviews with utility planning officers, independent power producer development leads, EPC contractors, and grid operators. Secondary validation drew from Canadian Environmental Assessment Agency filings, provincial energy regulator auction results, FERC-equivalent provincial utility commission dockets, and project development tracking databases. Bottom-up project pipeline aggregation and top-down provincial renewable target reconciliation provided cross-verification.
Input-output matrices mapped turbine supply capacity, transmission expansion timelines, and carbon pricing trajectory assumptions to generation capacity and revenue projections across the analysis window. Segmentation dimensions modeled include technology configuration, end-user procurement structure, component sourcing origin, and application integration complexity. CAGRs were derived from compounded annual capacity additions and revenue-per-megawatt trends. Forecast inputs incorporated Health Canada electromagnetic field assessment timelines and Environment and Climate Change Canada species-at-risk designation updates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal carbon pricing stringency revisions and provincial renewable portfolio standard adjustments. Deviation in interconnection queue processing timelines or critical habitat zone expansions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Turbine Tower Market