
 Asia-Pacific Wind Power Market | 2026-2036
Asia-Pacific Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wind Power Market Outlook
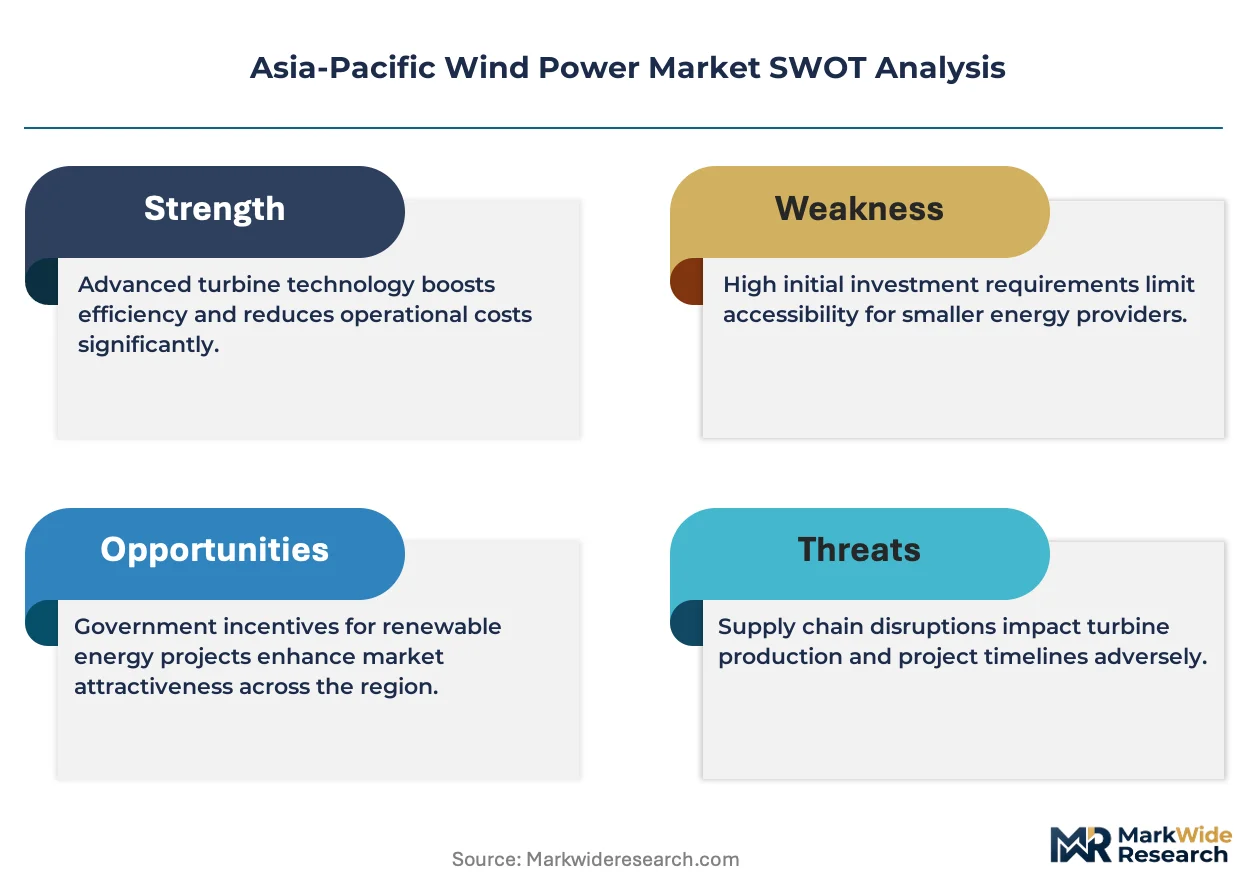
Utility-scale developers are redrawing procurement priorities across the Asia-Pacific Wind Power Market as offshore projects displace onshore dominance in coastal provinces. Vestas Wind Systems AS leverages its turbine platform breadth to anchor contracts across Australian and Japanese waters. China Three Gorges Corporation sustains pipeline depth through captive project development along the Yangtze Delta. Siemens Gamesa Renewable Energy SA differentiates via direct-drive offshore technology leadership in Taiwan and South Korea.
Asia-Pacific wind power encompasses turbine-based electricity generation systems converting kinetic atmospheric energy through rotor blades, gearboxes, and generators into grid-synchronous power, with offshore variants now reaching 15 MW-plus nameplate capacities and floating substructures enabling water depths exceeding 60 meters. Onshore technology retains volume leadership across interior Chinese provinces and Indian highlands, while offshore installations command premium margins due to foundation complexity and subsea cable requirements. Grid-connected utility-scale deployment dominates capital allocation, though hybrid installations pairing wind with battery storage are gaining traction among Japanese and Australian industrial offtakers seeking firm dispatchable output.
China's MIIT enforces turbine efficiency benchmarks and domestic content thresholds that shape supplier qualification, while Australia's national offshore wind regulator and Japan's METI maritime spatial planning jointly determine lease access and grid interconnection sequencing. India's CEA renewable purchase obligations and grid codes mandate interstate transmission upgrades that enable wind-rich states to serve distant load centers. Stakeholders must monitor permitting velocity against fabrication lead times as floating platform supply chains remain concentrated among Korean and Chinese yards.
Market Dynamics
Floating offshore turbine platforms are restructuring capital deployment patterns across coastal Asia-Pacific markets, pulling investment away from established onshore corridors toward deeper-water lease zones where foundation costs and grid interconnection sequencing now determine project viability.
Growth Catalysts
- Japan's METI maritime spatial planning:The framework accelerates lease access in designated offshore zones, compressing permitting timelines for utility-scale developers seeking sites in the Sea of Japan and Pacific approaches.
- Steel-intensive floating substructures:Korean and Chinese fabrication yards are scaling semi-submersible platform output, reducing unit costs for water depths exceeding 60 meters previously inaccessible to fixed-foundation turbines.
- Australian offshore wind zone declarations:Federal declarations in Bass Strait and Pacific waters create bankable site pipelines, attracting institutional capital seeking long-dated renewable offtake contracts.
Market Restraints
- Copper and rare earth magnet cost volatility:Permanent magnet generators rely on neodymium and dysprosium supply concentrated in Chinese processing facilities, exposing turbine OEMs to input price swings that compress margin buffers on fixed-price EPC contracts.
- Subsea cable installation bottlenecks:Specialized vessel availability for high-voltage DC export cables remains concentrated among European and Korean contractors, creating queue risks for Taiwanese and South Korean array connections.
- Grid interconnection sequencing delays:Australia's national offshore wind regulator and state transmission planners operate on mismatched timelines, stranding permitted generation capacity behind constrained onshore substations.
Strategic Opportunities
- Vietnam's unlicensed coastal waters:The absence of formal maritime spatial planning creates first-mover advantages for developers able to secure provincial government memoranda ahead of national framework finalization.
- Wind-plus-battery hybrid configurations:Japanese industrial offtakers are contracting firm dispatchable output, creating integrated project structures that capture capacity payments unavailable to pure generation assets.
- Direct-drive generator technology convergence:Elimination of gearbox maintenance requirements aligns with remote offshore service cost constraints, opening supplier opportunities for permanent magnet and electrically excited synchronous architectures.
Industry Challenges
- Marine construction specialist labor scarcity:Floating platform installation crews and subsea cable jointing technicians require certifications that outpace regional vocational training output, inflating day rates and extending project schedules.
- Type certification timeline compression:Prototype testing protocols for 15 MW-plus turbine platforms demand extended operational data collection periods that conflict with offtake contract commercial operation date commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wind Power Market |
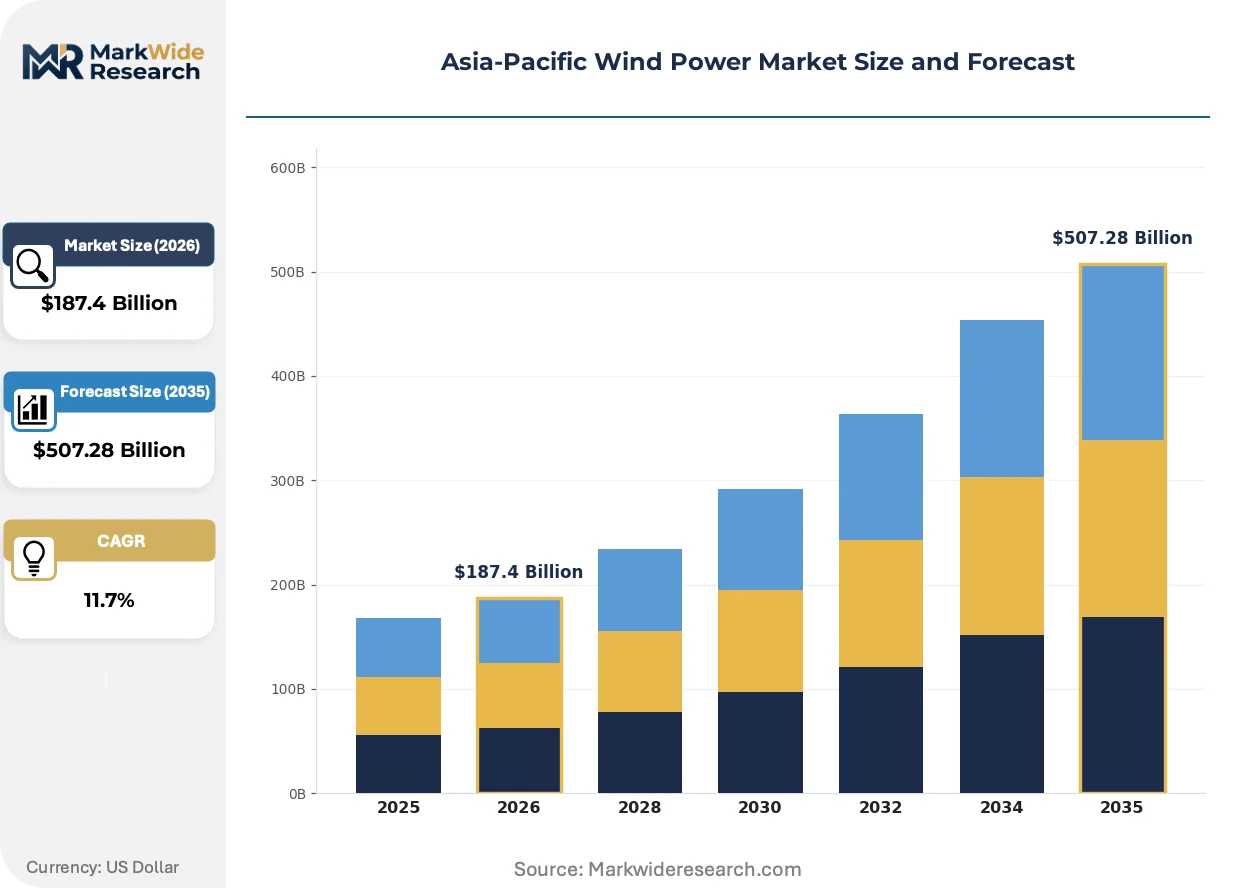
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Horizontal Axis, Vertical Axis Installation Type: Grid-Connected, Off-Grid, Hybrid, Utility Scale End User: Commercial, Industrial, Residential, Government Capacity: Small Scale, Medium Scale, Large Scale, Mega Scale |
| Companies Covered | Nordex SE, State Power Investment Corporation, Vestas Wind Systems AS, Ørsted, China Three Gorges Corporation, Siemens Gamesa Renewable Energy SA, Suzlon Energy Limited, Northland Power Inc., General Electric Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wind Power Market Strategic Shifts
Technology trajectories across the Asia-Pacific wind power sector are converging on larger nameplate capacities and deeper-water deployment, while regulatory frameworks race to match the spatial and grid integration requirements these systems demand.
Direct-drive permanent magnet generators are eliminating gearbox failure modes in offshore turbines rated above 12 MW, reducing maintenance vessel call frequency by 40 percent versus geared architectures. Japanese and Taiwanese developers are specifying these systems for Pacific typhoon-zone installations where accessibility windows remain narrow. This architecture is displacing conventional medium-speed geared drivetrains from premium offshore procurement specifications.
Australia's national offshore wind regulator introduced consolidated environmental assessment pathways in 2023, collapsing previously sequential federal and state approval processes into parallel review streams. The reform compresses permitting timelines from 54 to 36 months for projects in declared zones. Victorian and New South Wales lease rounds are attracting bids from European and Asian consortia previously deterred by jurisdictional complexity.
Corporate power purchase agreements are supplanting traditional utility offtake as the dominant revenue contracting mechanism for new capacity, particularly among Australian mining operations and Japanese semiconductor fabs seeking 24/7 renewable claims. Developers are structuring merchant-exposed tails behind 10-15 year corporate contracts to optimize project finance coverage ratios. This pattern concentrates in Queensland's renewable energy zones and Kyushu's industrial corridor.
Asia-Pacific Wind Power Market Segmentation
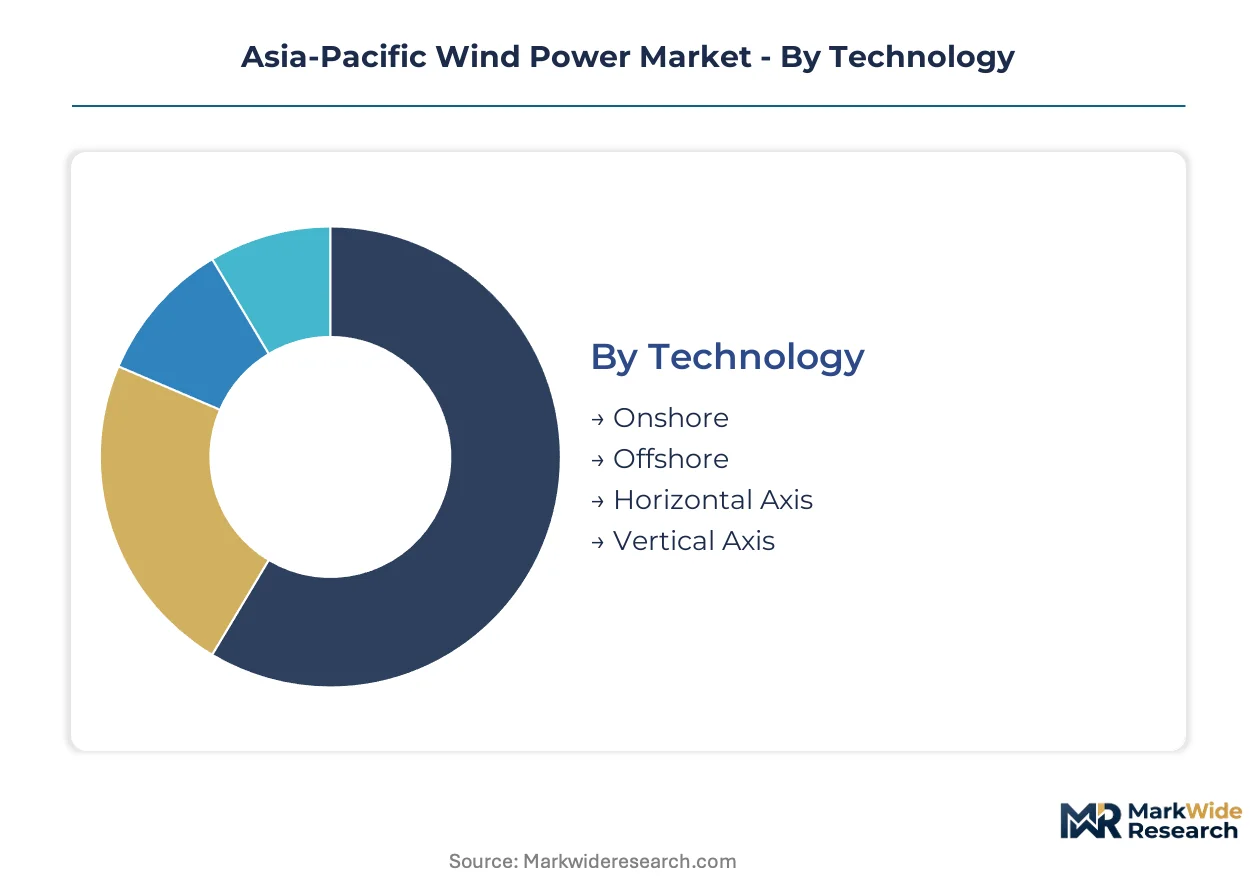
Segmentation across the Asia-Pacific Wind Power Market reveals divergent procurement patterns between coastal offshore zones and interior onshore corridors. Technology choice and installation scale determine which channels—utility offtake, corporate PPAs, or captive industrial supply—absorb capacity additions.
Technology:
Channel flows split sharply between established onshore supply chains serving provincial grids and emerging offshore procurement through maritime EPC consortia.
- Onshore:Horizontal-axis turbines with steel tubular towers and concrete foundations dominate procurement across China's interior provinces and India's Western Ghats. Grid-connected utility-scale projects in Shandong and Rajasthan concentrate demand through state-owned power distributors.
- Offshore:Fixed-foundation and floating platforms in 8-15 MW configurations command premium EPC margins through specialized marine construction channels. Taiwan Strait and Bass Strait developments route through international consortia pairing European turbine OEMs with Korean fabrication yards.
- Horizontal Axis:Three-blade upwind configurations with variable pitch control capture virtually all utility-scale procurement across the region.
- Vertical Axis:Darrieus and H-rotor designs serve niche distributed applications in remote Japanese islands and Australian pastoral stations beyond grid reach.
Onshore technology dominates installed base. Offshore is where expansion concentrates.
Installation Type:
Cost tier stratification separates capital-intensive utility-scale developments from modular distributed systems serving price-sensitive industrial offtakers.
- Grid-Connected:High-voltage transmission-linked installations above 50 MW aggregate capacity feed provincial and national dispatch pools. China's MIIT efficiency benchmarks and India's CEA renewable purchase obligations channel procurement through state-backed transmission companies.
- Hybrid:Wind-plus-battery or wind-plus-solar configurations command integrated EPC premiums from Japanese semiconductor fabs and Australian mining operations seeking firm dispatchable output. Corporate PPA structures reward guaranteed availability over pure generation volume.
- Off-Grid:Diesel displacement systems serve Indonesian archipelago communities and Philippine island provinces where submarine cable economics fail.
- Utility Scale:Single-site developments exceeding 100 MW concentrate capital deployment in China's eastern seaboard renewable energy zones.
Grid-connected capacity holds the deepest project pipeline. Hybrid configurations are climbing the fastest as industrial offtakers prioritize dispatch certainty.
End User:
Volume concentration tracks manufacturing density and electrification intensity across the region's industrial belts.
- Industrial:Steel, aluminum, and semiconductor operations in Kyushu, Queensland, and Jiangsu contract dedicated renewable supply through 10-15 year corporate PPAs. Firm output requirements drive wind-plus-storage procurement premiums.
- Commercial:Data centers and logistics facilities in Singapore and Sydney seek 24/7 renewable claims for sustainability reporting, accepting merchant-exposed pricing tails behind contracted volumes.
- Government:State-owned power utilities and defense installations procure through regulated tariff mechanisms in China, India, and Vietnam.
- Residential:Distributed rooftop and community wind serves high-income households in Australian coastal zones and Japanese mountain communities.
Industrial offtake commands the steepest expansion trajectory. Government procurement anchors legacy installed base.
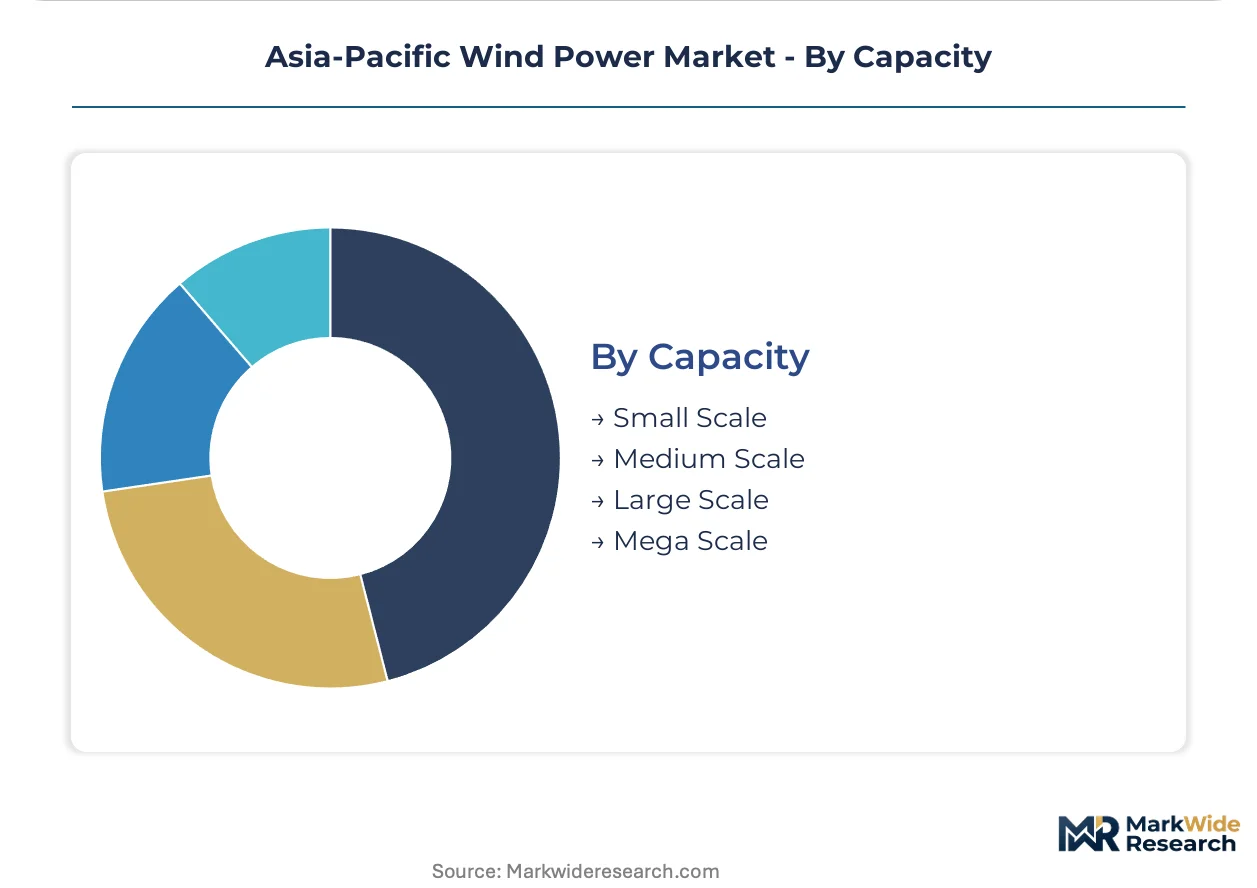
Capacity:
Scale thresholds determine fabrication sourcing, with mega-scale projects triggering dedicated component supply chains.
- Large Scale:Individual turbines rated 3-8 MW and project capacities of 50-200 MW constitute the procurement sweet spot for Chinese and Indian utility-scale deployment. Domestic nacelle assembly and blade manufacturing capture value chain margin.
- Mega Scale:500 MW-plus developments in Australia's declared offshore zones and China's coastal provinces require dedicated vessel charters and port infrastructure. Korean and Chinese fabrication yards compete for floating platform supply.
- Medium Scale:10-50 MW projects serve provincial distribution companies in Thailand and Vietnam with standardized turbine configurations.
- Small Scale:Sub-1 MW units address remote agricultural and pastoral applications across Mongolia and Central Asian republics.
Large-scale capacity dominates current deployment. Mega-scale projects concentrate future capital commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zhangjiakou grid interconnection hub underwrites China's transmission backbone for wind-rich northern provinces. Japan's Hokkaido- Honshu HVDC link enables island generation to serve Tokyo load centers. Australia's Project EnergyConnect stitches eastern seaboard renewable zones into a unified national market.
China
Provincial renewable energy zones in Inner Mongolia and Gansu drive turbine procurement volumes exceeding 50 GW annually. MIIT efficiency benchmarks and domestic content thresholds shape supplier qualification through mandatory nacelle assembly localization. The Yangtze Delta corridor concentrates offshore fabrication at Nantong and Yancheng ports where state-owned developers anchor floating platform supply chains.
Japan
Industrial offtakers in Kyushu's semiconductor corridor contract firm dispatchable output through wind-plus-battery hybrids. METI maritime spatial planning compresses permitting timelines for Pacific and Sea of Japan lease zones. Chiba and Akita prefectures host the deepest project pipelines as typhoon-resistant turbine specifications mature.
Australia
Mining operations in Queensland's Bowen Basin and Pilbara iron ore districts procure dedicated renewable supply through 15-year corporate PPAs. The national offshore wind regulator's consolidated environmental assessment pathways collapsed federal-state approval timelines from 54 to 36 months. Bass Strait and Pacific declared zones attract European and Asian consortia to Victorian and New South Wales lease rounds.
South Korea
Heavy industrial clusters in Ulsan and Yeosu drive demand for utility-scale offshore capacity to meet corporate renewable targets. MFDS maritime safety coordination and MOTIE energy planning jointly determine lease access sequencing. Southwest Jeolla province hosts the densest array of floating platform fabrication yards competing for Taiwan Strait export contracts.
India
Wind-rich states in Gujarat and Tamil Nadu serve distant load centers through CEA-mandated interstate transmission upgrades. Renewable purchase obligations channel procurement through state-backed distribution companies. The Western Ghats and Kutch peninsula concentrate onshore deployment where domestic blade manufacturing captures value chain margin.
Asia-Pacific Wind Power Market Competitive Environment
Listed leaders compete with private specialists across capital access and project development velocity in a market consolidating around state-backed utility-scale deployment. The vendor base stratifies into three tiers: integrated European turbine OEMs, Chinese state-owned energy conglomerates with captive EPC capabilities, and specialized offshore marine construction firms. Competitive positioning hardens through floating platform technology licensing and backward integration into nacelle component supply.
Among European-listed turbine manufacturers, Vestas Wind Systems AS and Siemens Gamesa Renewable Energy SA exemplify the integrated technology archetype spanning onshore and offshore configurations. State Power Investment Corporation and China Three Gorges Corporation occupy positions within the state-owned developer tier leveraging captive project pipelines and domestic fabrication access. Ørsted represents the pure-play offshore specialist model concentrated on maritime EPC execution and long-dated offtake contracting.
| Leading Market Players |
|---|
| Nordex SE |
| State Power Investment Corporation |
| Vestas Wind Systems AS |
| Ørsted |
| China Three Gorges Corporation |
| Siemens Gamesa Renewable Energy SA |
| Suzlon Energy Limited |
| Northland Power Inc. |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month floating platform fabrication lead times concentrate pricing power among Korean and Chinese yards, compressing margin buffers for European turbine OEMs bidding fixed-price EPC contracts while amplifying buyer leverage for state-backed developers with multi-project order pipelines.
Pricing Analysis
Volume-discount tiering structures separate mega-scale offshore developments exceeding 500 MW from provincial utility-scale procurement. Premium pricing attaches to typhoon-resistant direct-drive configurations with integrated battery storage, while standard onshore turbines face cost compression from domestic Chinese blade manufacturing scale. Australian mining offtakers exhibit lowest price sensitivity due to 24/7 renewable compliance mandates, whereas Vietnamese provincial distributors remain highly price-sensitive given unlicensed regulatory frameworks.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port congestion amplify landed costs for European nacelle components destined for Taiwan Strait projects. Supply concentrates in China for rare earth magnet processing, South Korea for semi-submersible platform fabrication, and Japan for precision gearbox components. Neodymium, dysprosium, and high-grade electrical steel constitute critical input dependencies. Single-source vulnerability runs through Chinese rare earth refining capacity. Distribution runs through maritime EPC consortia pairing turbine OEMs with specialized marine construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Australian mining consortia and Japanese semiconductor fabs contracting firm dispatchable output, fragmenting traditional utility offtake dominance and forcing developers toward hybrid wind-plus-battery configurations.
For Market Incumbents: Compound floating platform technology licensing advantages through exclusive partnerships with Korean fabrication yards, securing fabrication slots against emerging European pure-play offshore specialists. Deepen backward integration into permanent magnet generator component supply to offset rare earth price volatility. Prioritize certification investment for 15 MW-plus typhoon-resistant architectures targeting Pacific lease zones. For New Entrants and Emerging Players: Offshore service vessel availability gaps present white-space opportunities where incumbent turbine OEMs under-serve maintenance logistics. Target Vietnam's unlicensed coastal waters through provincial government memoranda ahead of national maritime spatial planning finalization. Enter through floating platform installation subcontracting relationships with established EPC consortia lacking marine construction crew capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mega-scale offshore developments exceeding 500 MW, elevating balance-sheet requirements and favoring state-backed or deep-pocketed sponsors. Long-term viability over the coming decade hinges on securing bankable offtake through corporate PPAs rather than merchant-exposed merchant tails. Monitor Australian national offshore wind regulator lease round participation rates as inflection indicator for institutional capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Technology Licensing | Secures fabrication access at Korean and Chinese yards for water depths exceeding 60 meters. |
| Wind-Plus-Battery Hybrid Development | Captures capacity payments from Japanese semiconductor fabs seeking firm dispatchable output. |
| Corporate PPA Contracting | Replaces traditional utility offtake for Australian mining operations in Queensland's renewable zones. |
| Permanent Magnet Supply Integration | Reduces exposure to Chinese neodymium and dysprosium processing price volatility. |
| Typhoon-Resistant Certification Investment | Unlocks Pacific lease zone access under METI maritime spatial planning frameworks. |
Study Parameters
The analysis maps onshore utility-scale, offshore fixed-foundation, and floating platform sub-sectors, each validated through interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators. Primary fieldwork combined with secondary validation from IEA reports, FERC filings, project development databases, and customs trade data. Bottom-up capacity addition modeling triangulated against top-down investment flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology type, installation scale, end-use sector, and regional regulatory framework. CAGRs derived from installed base growth rates, capacity factor assumptions, and capital cost learning curves. Forecast inputs incorporated floating platform fabrication lead times and subsea cable installation vessel availability constraints.
Material uncertainties — commodity price volatility in rare earth magnets, permitting velocity against fabrication timelines, grid interconnection sequencing mismatches — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory framework stability and offshore wind zone declaration timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market