
 Japan Wind Energy Market | 2026-2036
Japan Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Wind Energy Market Outlook
METI's revised offshore wind auction framework is restructuring the cost-of-entry calculus for developers bidding into Japan's territorial waters. Sumitomo Corporation leverages its port infrastructure and maritime logistics networks to secure staging advantages for floating turbine projects. Eurus Energy Holdings Corporation anchors its pipeline through early mover leases in northern waters. Vestas AS competes on turbine platform adaptability for typhoon-prone conditions.
Wind energy captures kinetic atmospheric flow through aerodynamic rotor blades connected to electromechanical drivetrains, converting mechanical rotation into grid-synchronous electricity at typical outputs ranging from sub-megawatt distributed units to 15 MW offshore machines. The technology serves baseload displacement, corporate power purchase obligations, and island grid stabilization across Japan's archipelago geography. Offshore turbines command premium capital allocation as floating foundation maturation unlocks deeper-water sites previously inaccessible to fixed-bottom designs. Horizontal axis configurations dominate utility-scale deployment, while vertical axis formats occupy niche rooftop and distributed commercial applications where omnidirectional wind capture offsets lower peak efficiency.
METI's General Maritime Area Act coordinates with JIS standards and the Ports and Harbors Act to streamline seabed leasing, turbine certification, and heavy-lift vessel access for offshore construction windows. These frameworks shape demand by mandating domestic content thresholds and environmental impact protocols that filter participant eligibility. Stakeholders must monitor auction round dynamics and foundation technology cost curves to time capital deployment across Japan's phased offshore zone openings.
Market Dynamics
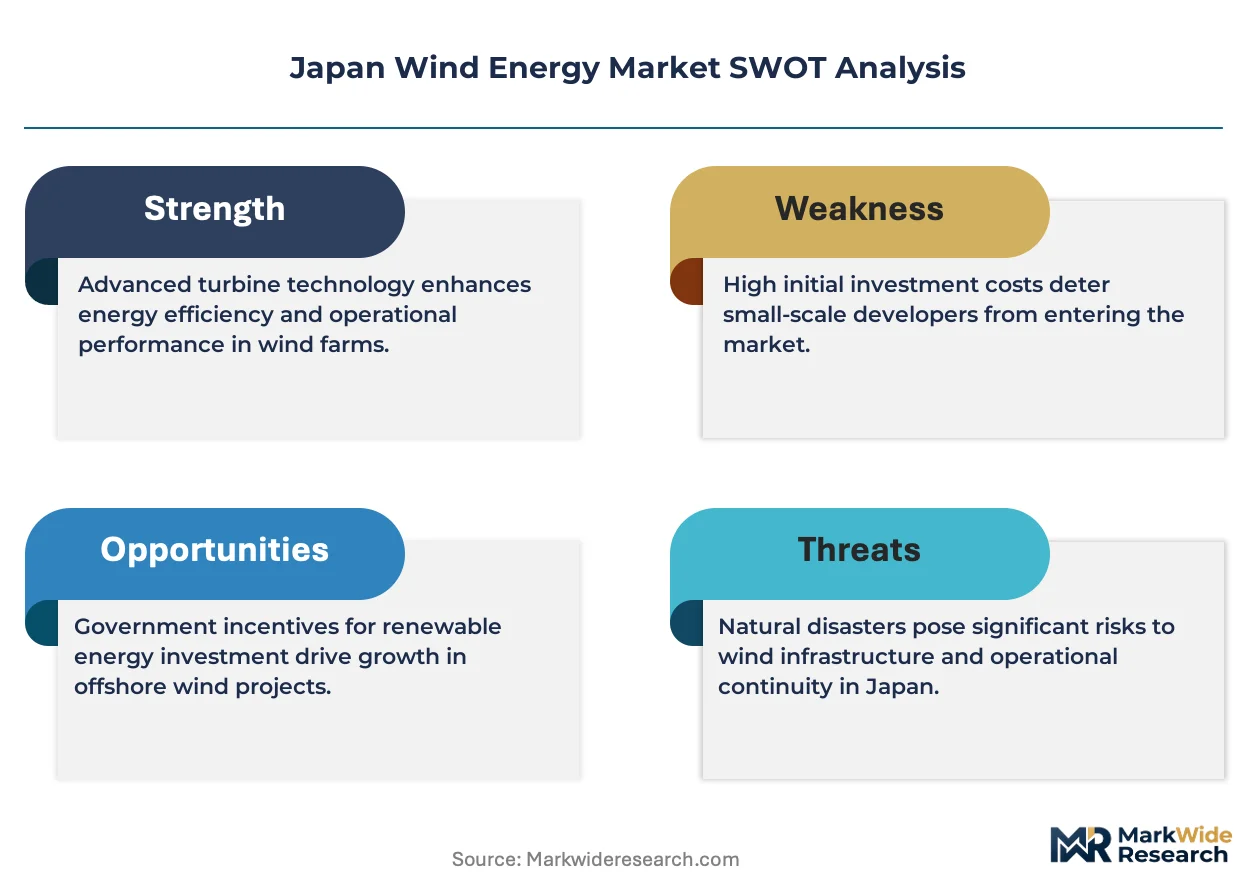
METI's feed-in tariff recalibration is compressing project returns and forcing developers toward larger-scale offshore clusters where foundation economies offset declining tariff rates.
Growth Catalysts
- Floating Foundation Maturation:Semi-submersible and tension-leg platforms unlock depths beyond 60 meters, expanding viable seabed acreage off Hokkaido's Pacific coast.
- Corporate PPA Obligations:RE100 commitments from Japanese manufacturers and data center operators create offtake certainty for merchant-exposed projects.
- General Maritime Area Act:Streamlined seabed leasing procedures reduce permitting timelines and clarify environmental review thresholds for zone developers.
Market Restraints
- Heavy-Lift Vessel Scarcity:Japan's domestic jack-up fleet remains insufficient for simultaneous multi-site construction, creating bottlenecks during narrow weather windows.
- Grid Interconnection Queues:Transmission upgrades in Kyushu and Tohoku lag project completion schedules, forcing operational curtailment or costly storage co-location.
- Steel and Rare Earth Volatility:NdFeB magnet supply concentration and plate steel pricing erode turbine margin assumptions across fixed-bottom and floating designs.
Strategic Opportunities
- Deepwater Zones off Aomori:Untapped Pacific trenches offer consistent wind resources with lower fishing conflict density than shallower Seto Inland Sea alternatives.
- Green Hydrogen Co-Location:Electrolyzer-turbine integration at port-adjacent sites enables ammonia export corridors to Korean and Taiwanese industrial buyers.
- Typhoon-Resilient Platform Export:Japanese engineering expertise in extreme-weather floating designs positions domestic yards for Taiwan and Philippines project supply.
Industry Challenges
- Maritime Construction Skills Gap:Specialized welders, cable installers, and dynamic positioning vessel operators command premium wages and extended recruitment cycles.
- JIS Certification Timelines:Turbine type approval and component testing protocols extend equipment qualification periods, delaying commercial operation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Wind Energy Market |
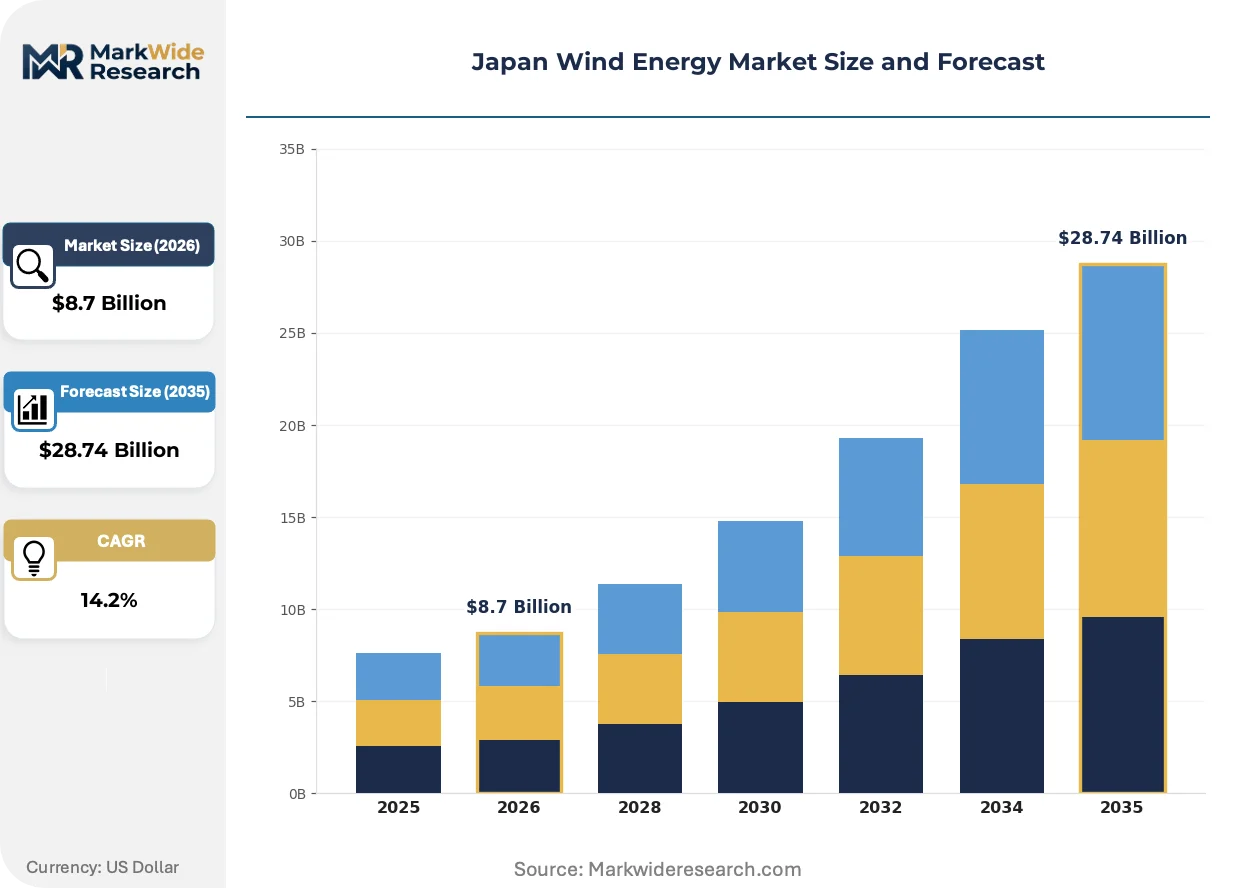
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Turbines, Offshore Turbines, Hybrid Systems, Small Wind Systems Technology: Horizontal Axis, Vertical Axis, Ducted Wind Turbines, Floating Turbines End User: Utilities, Commercial, Residential, Industrial Installation: Fixed, Floating, Barge-based, Rooftop |
| Companies Covered | Japan Renewable Energy Co. Ltd, Sumitomo Corporation, Siemens Gamesa Renewable Energy, Synera Renewable Energy Co., Ltd., Eurus Energy Holdings Corporation, Vestas AS, Marubeni Corporation, TEPCO Holdings, MHI Vestas Japan Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Wind Energy Market Strategic Shifts
Foundation technology convergence and auction mechanism redesign are compressing developer margins while unlocking deeper-water territories previously excluded from commercial viability.
Semi-submersible floating platforms are unifying ballast-stability engineering with modular assembly sequences, enabling port-side turbine integration before wet-tow deployment. Japanese port authorities in Kitakyushu and Muroran are adapting heavy-lift quays for this workflow. The approach is compressing offshore construction seasons from twelve-month windows to six-week campaigns, reducing weather-risk contingency reserves.
METI's revised auction framework introduces dual-parameter bidding combining strike prices with domestic content commitments, restructuring developer consortium formation. The mechanism favors integrated port-turbine-foundation bids over pure generation plays. Northern prefectures with established steel and shipbuilding infrastructure capture disproportionate allocation in early rounds.
Utility buyers are consolidating offtake negotiations through joint procurement vehicles, displacing bilateral developer-utility contracting. Regional transmission operators in Hokkaido Electric Power and Kyushu Electric Power coordinate standardized PPA terms and grid access sequencing. The shift concentrates counterparty risk assessment within centralized buyer committees, extending due diligence periods but reducing transaction costs for repeat participants.
Japan Wind Energy Market Segmentation
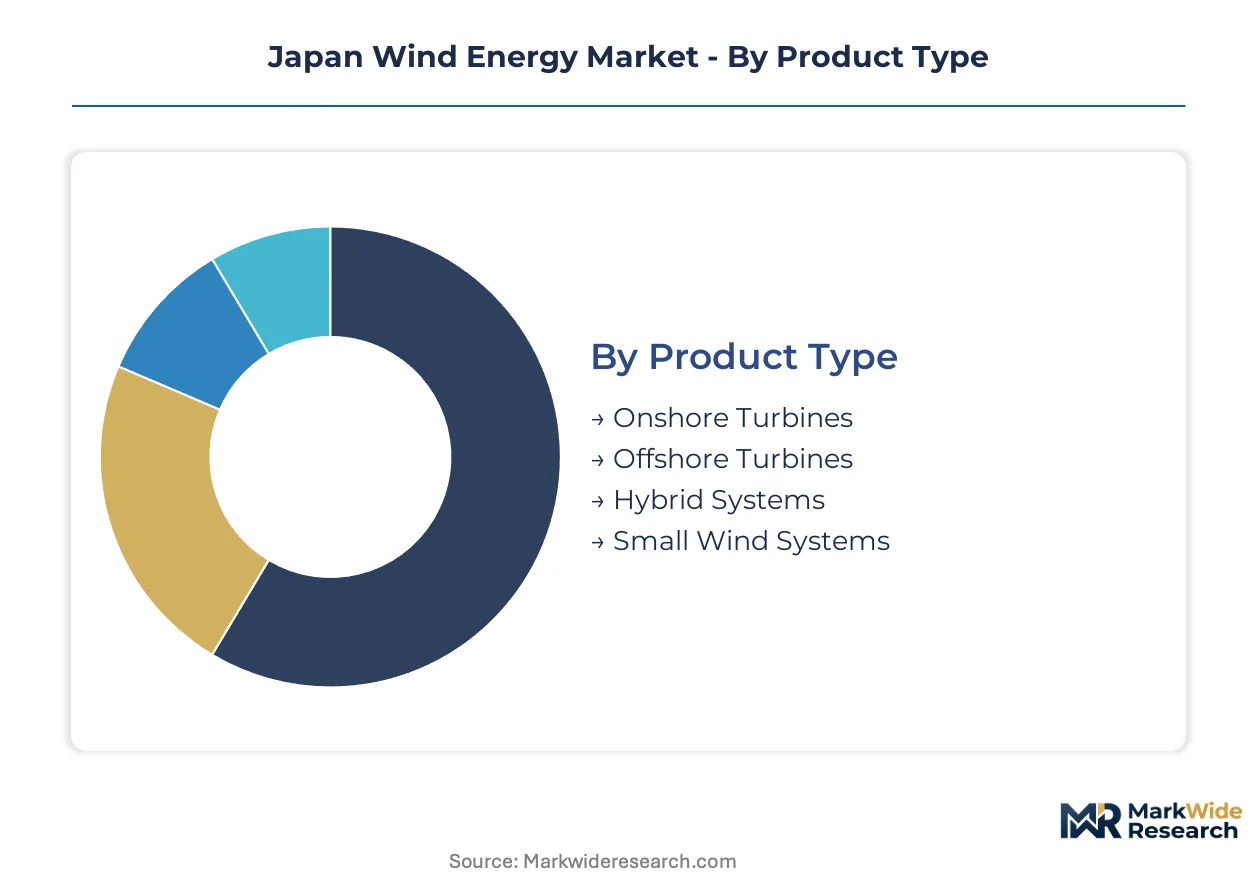
Segmentation in Japan's wind energy market reveals distinct capital intensity profiles, technology maturity curves, and regulatory exposure across product architectures and installation environments. Understanding these divides allows developers to align project pipelines with METI auction mechanics and regional grid constraints.
Product Type:
Capital intensity varies sharply across product categories, with offshore installations demanding foundation and vessel outlays that dwarf onshore equivalents by multiples.
- Offshore Turbines:Multi-megawatt machines mounted on fixed or floating substructures in territorial waters beyond 12 nautical miles. METI's General Maritime Area Act zones concentrate demand off Hokkaido's Pacific coast and Kyushu's western waters, where fishing conflict density remains manageable.
- Onshore Turbines:Land-based horizontal-axis units typically sited in mountainous corridors of Tohoku and Hokkaido. Grid interconnection queues in northern prefectures constrain deployment velocity despite lower permitting complexity.
- Hybrid Systems:Integrated wind-solar or wind-storage configurations co-located at substation nodes. These units command premium EPC contracts from island utilities seeking frequency stabilization.
- Small Wind Systems:Sub-100kW distributed units for agricultural and remote commercial loads. Rural Hokkaido municipalities deploy these for off-grid irrigation and disaster resilience.
Offshore turbines absorb the bulk of installed capacity; hybrid systems are expanding most quickly as storage economics improve.
Technology:
Technology selection tracks water depth, wind shear profiles, and typhoon exposure across Japan's archipelago geography.
- Floating Turbines:Semi-submersible and tension-leg platforms enabling deployment in Pacific trenches exceeding 60-meter depths. Aomori Prefecture's untapped deepwater zones drive prototype commissioning from domestic shipyards.
- Horizontal Axis:Conventional upwind rotor configurations dominating utility-scale deployment. Vestas and domestic OEMs optimize blade pitch control for extreme gust conditions in East Asian typhoon corridors.
- Vertical Axis:Omnidirectional capture formats suited to turbulent urban wind regimes. Niche applications include port facility lighting and distributed commercial rooftop arrays in Osaka Bay industrial zones.
- Ducted Wind Turbines:Shrouded rotor designs accelerating airflow through venturi enclosures. These units occupy demonstration projects at Kitakyushu port facilities testing maritime durability.
Horizontal axis machines retain dominant share; floating platforms are gaining share fastest as deeper-water zones open to commercial leasing.
End User:
End-user segmentation maps to offtake contract structures, with utility buyers consolidating procurement through joint vehicles while corporate PPAs displace traditional bilateral arrangements.
- Utilities:Regional transmission operators including Hokkaido Electric Power and Kyushu Electric Power procuring capacity through METI-coordinated auctions. These buyers standardize grid access sequencing and curtailment protocols.
- Industrial:Steel, chemical, and data center operators fulfilling RE100 commitments through direct offtake. Manufacturing clusters in Kitakyushu and Muroran anchor demand for baseload-displacement capacity.
- Commercial:Retail, logistics, and corporate facility operators seeking behind-the-meter generation. Urban constraints limit viable siting to rooftop and small-turbine formats.
- Residential:Single-home and agricultural deployments in rural prefectures. Subsidized feed-in tariffs previously drove uptake; declining rates now constrain segment economics.
Utility offtake commands the largest share of pipeline capacity; industrial buyers are scaling fastest as corporate renewable obligations harden.
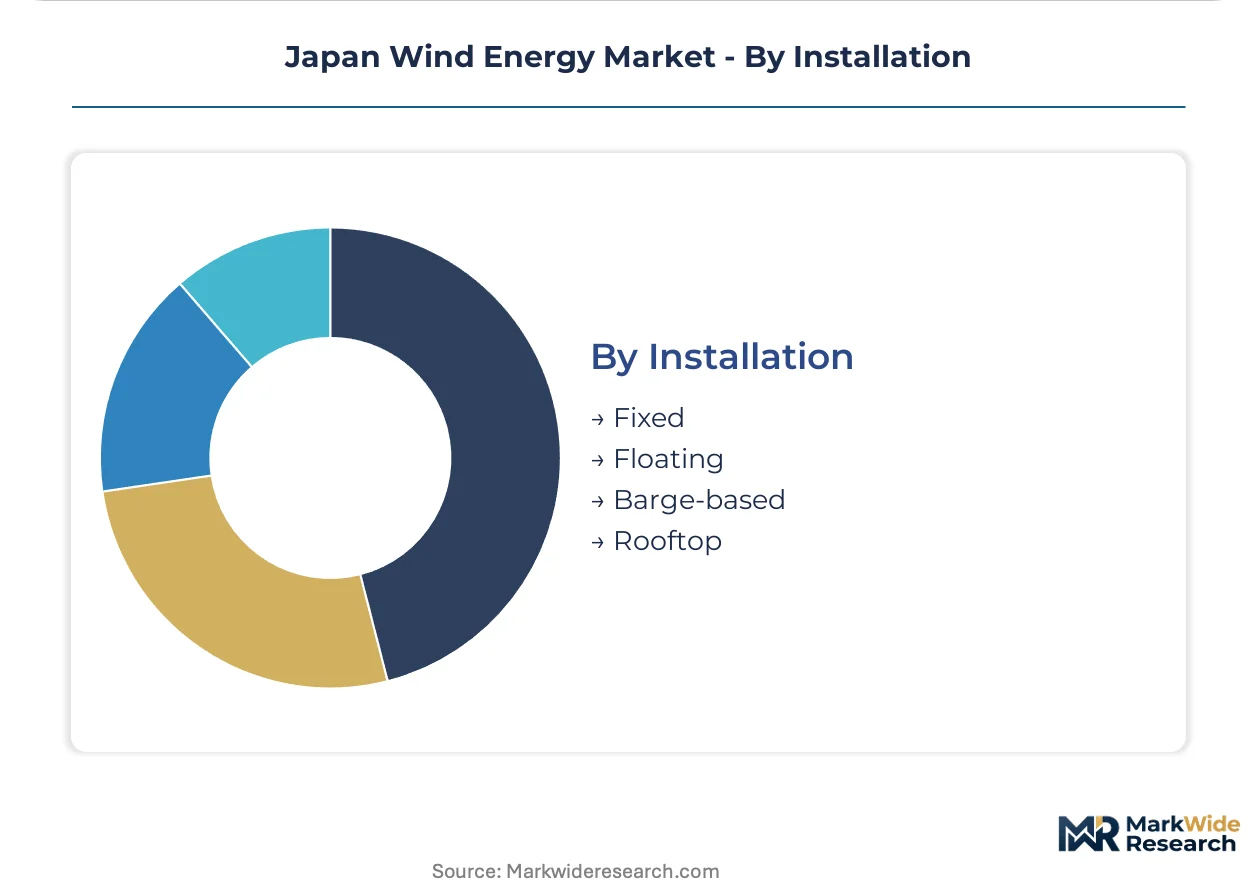
Installation:
Installation method determines vessel requirements, construction seasonality, and foundation supply chain exposure.
- Floating:Wet-tow deployment of integrated turbine-foundation assemblies from adapted heavy-lift quays. Port authorities in Muroran and Kitakyushu are expanding crane capacity for this workflow.
- Fixed:Monopile and jacket foundations in shallower waters under 50 meters. These structures dominate early offshore zones but face fishing conflict density in Seto Inland Sea areas.
- Barge-based:Temporary platform installations for demonstration and maintenance access. Limited commercial deployment outside research consortia.
- Rooftop:Urban-integrated small turbines on commercial and industrial buildings. Vertical axis formats predominate given omnidirectional wind capture in built environments.
Fixed foundations retain dominant deployment share; floating installations are climbing the fastest as deepwater zones progress through METI permitting stages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's National Strategic Special Zones for renewable energy development concentrate offshore wind investment around designated port clusters and maritime industrial corridors. METI coordinates zone-specific permitting accelerations that compress environmental review timelines for pre-qualified seabed areas.
Hokkaido
Pacific coastline wind resources and existing steel fabrication infrastructure attract floating foundation assembly investments. METI's General Maritime Area Act designates northern waters as priority zones for commercial leasing rounds. Port authorities in Muroran adapt heavy-lift quays for integrated turbine-foundation staging.
Kyushu
Western waters offer reduced typhoon exposure compared to Pacific-facing coastlines, lowering insurance and resilience engineering costs. Kyushu Electric Power coordinates standardized grid access sequencing for utility-scale projects. Kitakyushu industrial clusters supply monopile and jacket foundation components for fixed-bottom installations.
Tohoku
Aomori Prefecture's deepwater Pacific trenches exceed 60-meter depths suitable for semi-submersible platform deployment. The prefecture's fishing cooperative agreements reduce maritime use conflicts compared to Seto Inland Sea alternatives. Domestic shipyards in Akita and Iwate test tension-leg platform prototypes for serial production.
Kansai
Osaka Bay industrial zones host vertical axis turbine demonstrations for port facility and distributed commercial applications. The region's manufacturing base supplies power electronics and converter systems for grid interconnection. Hyogo Prefecture's steel mills provide specialized plate grades for typhoon-resistant tower structures.
Japan Wind Energy Market Competitive Environment
European turbine manufacturers anchor the technology supply tier; Japanese trading houses and domestic energy specialists hold project development and maritime logistics positions. Market structure consolidates around integrated consortiums combining foreign equipment suppliers with local construction and offtake partners. Three archetypes dominate: trading house-led developers leveraging port infrastructure, independent power producers securing early seabed leases, and European OEMs adapting platforms for extreme weather conditions. Competitive moves center on auction consortium formation and floating foundation technology licensing.
Among trading house-led developers, Sumitomo Corporation and Marubeni Corporation exemplify the integrated port-infrastructure archetype, while Eurus Energy Holdings Corporation occupies a position within the independent power producer tier focused on northern water lease accumulation. These entities represent distinct approaches to METI auction participation, with some emphasizing domestic content compliance and others prioritizing technology transfer partnerships.
| Leading Market Players |
|---|
| Japan Renewable Energy Co. Ltd |
| Sumitomo Corporation |
| Siemens Gamesa Renewable Energy |
| Synera Renewable Energy Co., Ltd. |
| Eurus Energy Holdings Corporation |
| Vestas AS |
| Marubeni Corporation |
| TEPCO Holdings |
| MHI Vestas Japan Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Utility-led joint procurement vehicles concentrate offtake negotiation power and compress developer margins through standardized strike-price benchmarks across METI auction rounds. This buyer concentration forces tiered pricing stratification across premium typhoon-resilient platforms, standard fixed-bottom configurations, and economy-grade refurbished turbines.
Pricing Analysis
Short lead-time premiums dominate auction dynamics as developers bid accelerated commercial operation dates to capture earlier tariff windows. Price differentiation rests on domestic content certification tiers and foundation technology complexity, with floating platforms commanding substantial premiums over fixed-bottom alternatives. Cost compression in standard fixed-bottom segments is intensifying because of steel plate volatility and jack-up vessel day-rate escalation. Industrial offtakers demonstrate lowest price sensitivity due to RE100 compliance mandates, while residential distributed systems face acute margin pressure from declining feed-in tariffs.
Supply Chain Analysis
METI's domestic content mandates reshape sourcing toward Japanese steel fabrication and maritime engineering clusters. Component supply draws from China for NdFeB magnets, South Korea for power electronics, and domestic shipyards for floating substructures. Single-source vulnerability concentrates in heavy-lift vessel availability during narrow weather windows. Distribution runs through port-adjacent staging facilities at Muroran and Kitakyushu before wet-tow deployment to offshore zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's wind energy market constitutes a vertical-integration race where port infrastructure control and foundation manufacturing capability determine auction competitiveness. Players are pursuing upstream captive supply of steel plate and maritime construction assets.
For Market Incumbents: Deepen integration into floating foundation manufacturing through partnerships with Aomori and Iwate shipyards to secure domestic content compliance advantages. Lock in long-term heavy-lift vessel charters before competitor procurement crowds the limited jack-up fleet. METI's revised auction mechanics favor integrated bids combining port, turbine, and foundation assets.
For New Entrants and Emerging Players: Semi-submersible platform engineering expertise offers a technology-first wedge into the underserved deepwater zones off Aomori's Pacific trenches. Target fishing cooperative agreements in northern prefectures where maritime use conflicts remain manageable. Pursue licensing arrangements with European OEMs for typhoon-adapted turbine platforms rather than greenfield R&D.
For Investors and Strategic Acquirers: The window for entry favors port infrastructure operators with heavy-lift quay capacity and established steel fabrication relationships. Long-term viability hinges on exposure to METI's phased zone openings rather than speculative early-stage development. Monitor JIS certification timeline announcements as the critical inflection signal for equipment qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Manufacturing Scale-Up | Captive production at Muroran and Akita shipyards secures domestic content thresholds for METI auction compliance. |
| Heavy-Lift Vessel Long-Term Charter | Locked jack-up capacity through narrow construction windows eliminates weather-risk contingency reserves. |
| Green Hydrogen Electrolyzer Co-Location | Port-adjacent ammonia export corridors tap Korean and Taiwanese industrial buyer demand. |
| Typhoon-Resilient Platform Technology Licensing | Engineering exports to Taiwan and Philippines projects monetize extreme-weather design expertise. |
| Utility Joint Procurement Vehicle Participation | Standardized PPA terms through Hokkaido Electric and Kyushu Electric reduce transaction friction for repeat developers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. METI auction documentation, JIS certification databases, and port authority infrastructure disclosures provided project-level validation. Bottom-up capacity aggregation across designated offshore zones reconciled with top-down macroeconomic demand projections.
Data-stream reconciliation across installation forecasts, tariff regime assumptions, and supply chain capacity models shaped the analytical framework across the projection horizon. Segmentation dimensions spanned foundation technology, water depth tiers, end-user contract structures, and regional grid interconnection status. CAGRs derived from auction round velocity, floating platform cost curves, and corporate PPA obligation growth trajectories. Vessel availability constraints and steel pricing volatility fed directly into margin compression modeling.
Several conditions sit outside the modeled scope, including abrupt METI policy reversals, catastrophic typhoon damage to operational assets, and geopolitical disruption of rare earth magnet supply chains. Forecasts reflect documented assumptions regarding auction participation rates and domestic content threshold evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Energy Foundation Market