
 Offshore Wind Anchoring Market | 2026-2036
Offshore Wind Anchoring Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Wind Anchoring Market Analytics
Specialized marine geotechnical engineering talent is bifurcating the competitive landscape as floating wind projects outpace qualified installation crews. Vryhof Anchors B.V. leverages decades of North Sea mooring expertise to dominate drag anchor supply for pre-commercial floating arrays. SBM Offshore N.V. anchors its position through integrated engineering-procurement-construction capabilities spanning anchor design through platform hookup. NOV Inc. competes by controlling critical pile-driving and dynamic positioning equipment that underpins installation method selection.
Offshore wind anchoring comprises engineered mooring systems that secure turbine foundations to seabed substrates through mechanical embedment, suction, or gravity-based resistance, typically rated for holding capacities exceeding 5,000 kN in water depths surpassing 60 meters. These systems prevent station-keeping failure under combined wave, wind, and current loading across operational lifetimes exceeding 25 years. Drag anchors and suction anchors lead procurement volumes for floating foundation deployments, with suction anchors capturing premium margin pools due to proprietary installation tooling and geotechnical customization requirements. Jacket foundations sustain demand for pile anchors in transitional water depths, while monopile bottom-founded systems in shallower zones represent a mature, price-competitive segment.
DNV certification standards, the EU Green Deal sustainability benchmarks, and the F-Gas Regulation governing installation vessel emissions collectively shape product specifications and market access conditions for anchor suppliers. Germany's Federal Maritime and Hydrographic Agency and Norway's Petroleum Safety Authority enforce site-specific holding-capacity verification that extends project timelines but filters substandard equipment. Stakeholders must monitor evolving lease stipulations in emerging basins where regulatory precedent remains unsettled.
Market Dynamics
Floating foundation deployment in water depths exceeding 60 meters is compressing traditional bottom-fixed economics and forcing anchor suppliers to reengineer holding-capacity verification protocols for unconsolidated seabed substrates.
Growth Catalysts
- EU Green Deal auction mechanisms:Germany, France, and Denmark now mandate fatigue-performance certification that filters out substandard suppliers and creates procurement pull for DNV-certified anchor systems.
- Suction anchor tooling specialization:Proprietary installation equipment for geotechnically customized suction anchors commands premium positioning in Celtic Sea and North Sea pre-commercial arrays.
- Deep-water lease concentration:Scotland, Norway, and Portugal lease areas now require specialized drag and suction anchor systems, concentrating demand among qualified marine geotechnical engineering providers.
Market Restraints
- Specialized steel alloy input costs:High-tensile mooring chain and anchor shank materials face price volatility tied to nickel and chromium supply concentration in specific mining jurisdictions.
- Installation vessel bottleneck:Dynamic positioning vessel availability constraints in the North Sea extend project timelines and compress contractor margins.
- Monopile substitution in shallower zones:Bottom-fixed turbine foundations in sub-60-meter depths anchor procurement to mature, price-competitive pile segments with limited margin expansion.
Strategic Opportunities
- Portuguese floating wind pipeline:Emerging lease rounds off the Iberian coast lack established anchor installation precedent, creating first-mover positioning for certified suppliers.
- F-Gas Regulation vessel retrofit incentives:EU installation fleet decarbonization mandates accelerate demand for low-emission dynamic positioning systems integrated with anchor handling.
- Digital twin mooring monitoring:Convergence of subsea sensor networks with predictive maintenance software creates recurring revenue attachment to hardware sales.
Industry Challenges
- Marine geotechnical engineer scarcity:Qualified installation crews capable of suction anchor deployment in complex seabed conditions remain concentrated among a handful of North Sea contractors.
- Site-specific holding-capacity verification:Germany's Federal Maritime and Hydrographic Agency and Norway's Petroleum Safety Authority extend certification timelines through mandatory field testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Wind Anchoring Market |
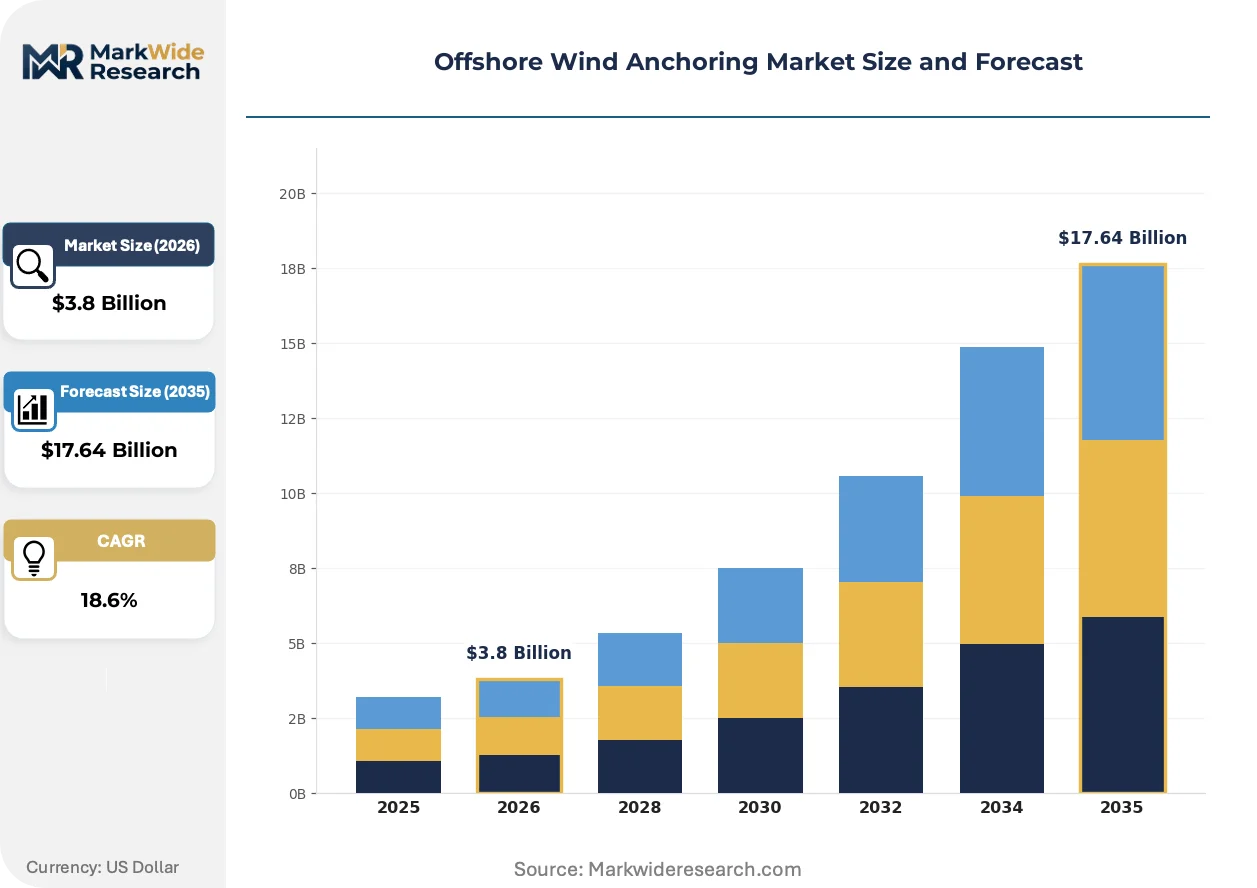
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Anchor Type: Drag Anchor, Suction Anchor, Pile Anchor, Gravity Anchor Foundation Type: Monopile, Jacket, Floating, Tripod Installation Method: Bottom-Founded, Float-Out, Dynamic Positioning, Pile Driving End User: Utilities, Project Developers, EPC Contractors, Government Entities |
| Companies Covered | Vryhof Anchors B.V., SBM Offshore N.V., Delmar Systems, Inc., Bluewater Energy Services B.V., NOV Inc., BW Offshore Limited, Trelleborg Marine & Infrastructure, Offspring International Limited, Cavotec SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Wind Anchoring Market Evolving Landscape
Anchor system design is bifurcating between standardized drag configurations for early floating arrays and fully customized suction systems for commercial-scale deployment, reshaping supplier R&D allocation and installation partnerships.
Modular suction anchor designs with interchangeable skirt configurations are fragmenting procurement patterns across project phases. Early-stage developers in the Celtic Sea favor rental tooling arrangements that reduce upfront capital exposure. This fragmentation compresses traditional equipment ownership models and forces anchor suppliers to build fleet-leasing capabilities alongside manufacturing.
The F-Gas Regulation governing installation vessel emissions is tightening charter specifications across EU member states. Vessel operators now face retrofit deadlines or replacement requirements that cascade into anchor handling equipment specifications. German and Danish project developers are responding by embedding emissions thresholds directly into marine construction tender documents.
Long-term service agreements are displacing transactional anchor procurement in floating wind tenders. Project developers in Scottish waters now require 25-year mooring integrity monitoring bundled with initial hardware supply. This contractual evolution concentrates vendor selection among suppliers with subsea inspection capabilities and compresses pure-play manufacturing margins.
Offshore Wind Anchoring Market Segmentation
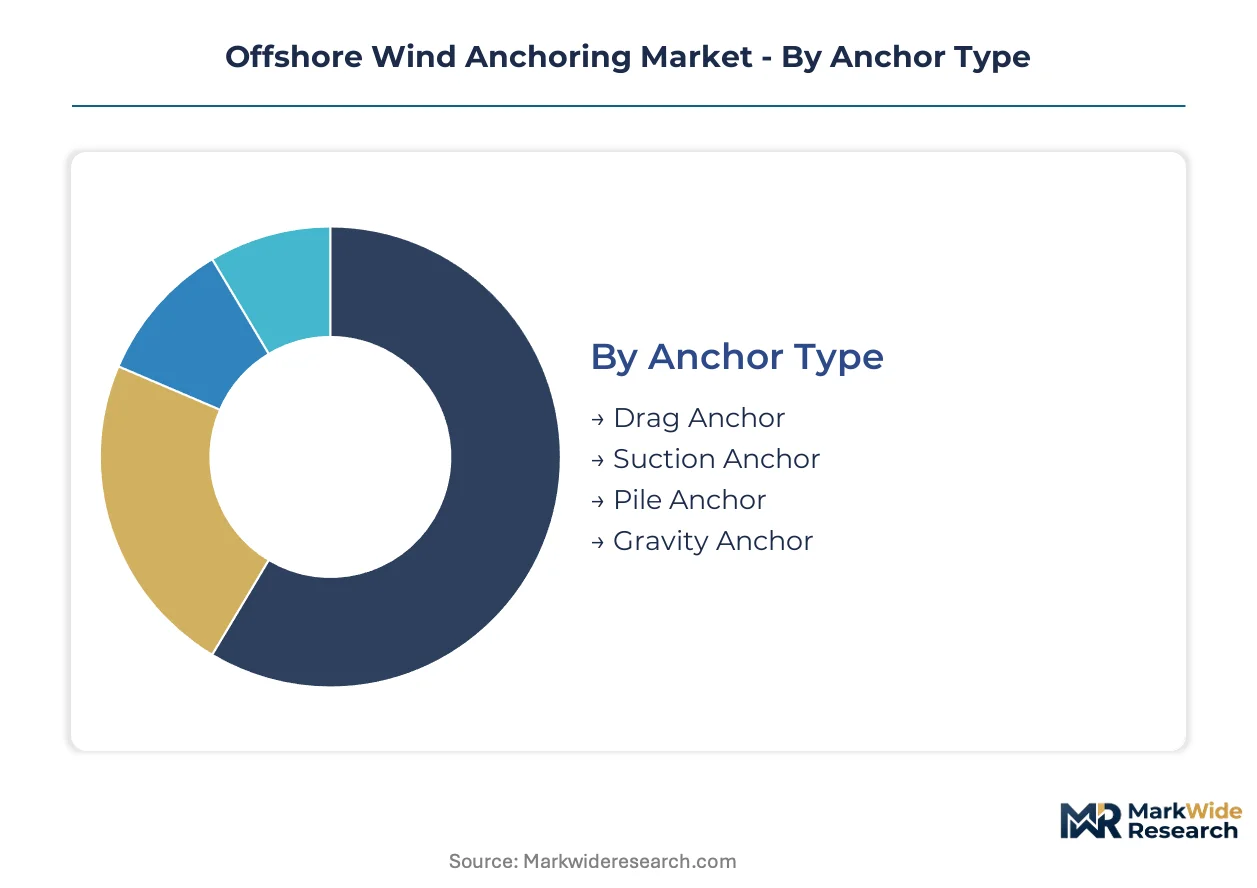
Anchor procurement patterns diverge sharply across water depth, foundation architecture, and installation methodology. Each segmentation axis reveals distinct margin pools, certification requirements, and supplier qualification barriers that reshape competitive positioning.
Anchor Type:
Drag anchors dominate North Sea export volumes to Scottish and Norwegian lease areas, while suction anchors concentrate in domestic Celtic Sea pre-commercial arrays. Gravity anchors remain confined to near-shore Iberian projects with limited cross-border procurement.
- Drag Anchor:Steel fluke-and-shank assemblies embed through seabed penetration under mooring line tension. Scottish floating wind developers in the Hywind lease areas specify DNV-certified drag configurations rated beyond 5,000 kN holding capacity.
- Suction Anchor:Cylindrical steel caissons achieve embedment through pressure differential and controlled water evacuation. Norwegian deep-water projects off the southwest coast command premium pricing for geotechnically customized skirt configurations with proprietary installation tooling.
- Pile Anchor:Driven tubular steel sections secure jacket foundations in transitional depths.
- Gravity Anchor:Concrete or steel mass systems rely on deadweight resistance without embedment.
Drag anchors command the established base. The steepest expansion runs through suction anchors.
Foundation Type:
Cost tier separation drives procurement segmentation, with floating foundations commanding engineering premiums and monopile systems locked in price-competitive mature supply chains.
- Floating:Semi-submersible and spar platforms in water depths exceeding 60 meters require multi-point mooring arrays with mixed anchor typologies. Portuguese Atlantic lease rounds lack installation precedent, creating first-mover qualification windows.
- Monopile:Single steel tubes driven into seabed substrates dominate sub-50-meter depths. German BSH certification mandates compress margins through standardized procurement specifications.
- Jacket:Lattice steel structures in 40-60 meter depths sustain pile anchor demand.
- Tripod:Three-legged foundation configurations occupy niche transitional applications.
Monopile systems anchor the volume base. Floating platforms generate the steepest margin expansion trajectory.
Installation Method:
Application-specific vessel requirements fragment contractor capabilities, with dynamic positioning and pile driving demanding distinct equipment ownership models.
- Dynamic Positioning:Computer-controlled thruster systems maintain vessel station during anchor deployment in harsh weather windows. EU F-Gas Regulation retrofit deadlines accelerate charter specifications for low-emission DP-2 and DP-3 class vessels in German and Danish tenders.
- Pile Driving:Hydraulic or vibratory hammers embed tubular anchors for jacket foundations. North Sea vessel bottlenecks extend project timelines and concentrate contractor margins among fleet owners with integrated hammer systems.
- Bottom-Founded:Self-installing platforms eliminate heavy-lift vessel requirements.
- Float-Out:Tow-to-site deployment reduces offshore construction exposure.
Pile driving commands the installed base. Dynamic positioning systems are climbing the fastest through decarbonization-driven fleet renewal.
End User:
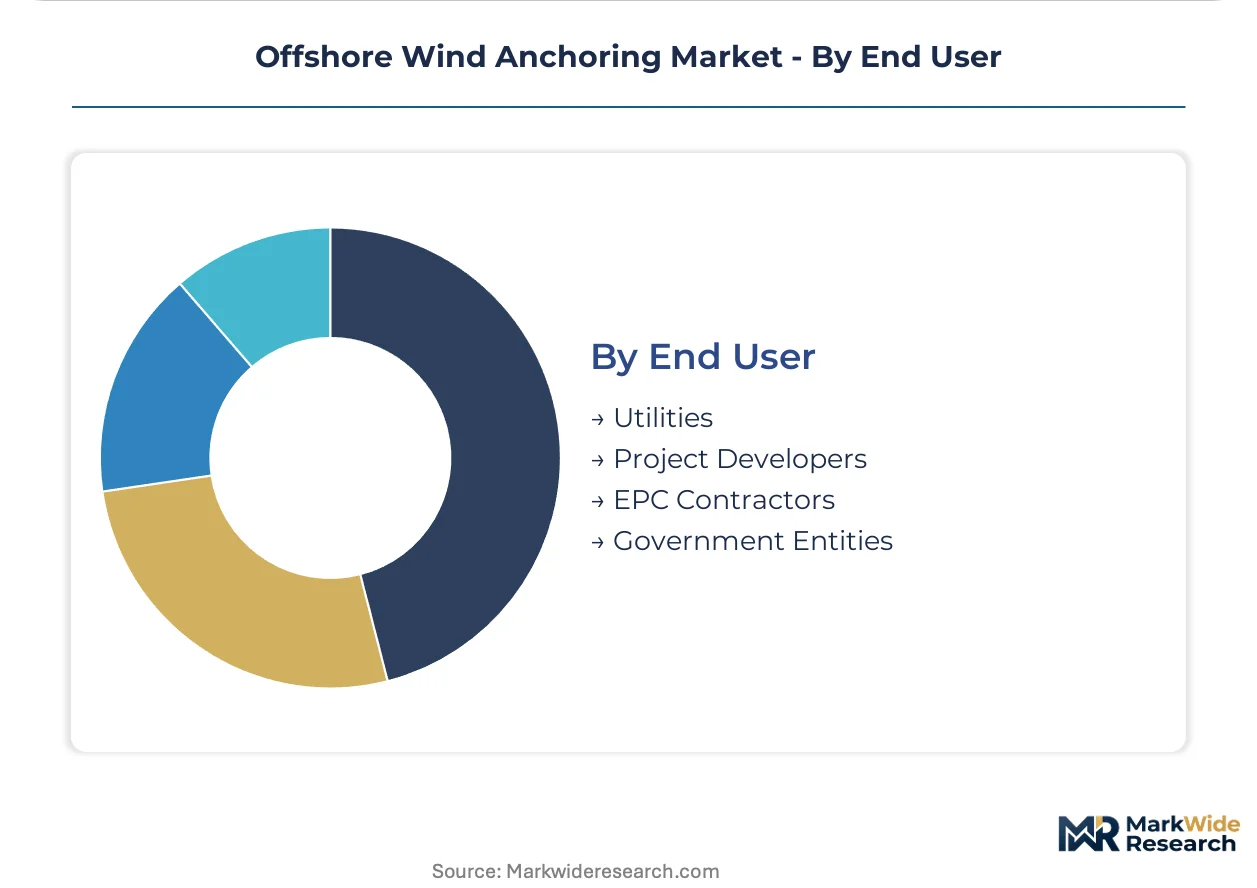
Customer type determines contracting structure, with utilities favoring long-term service agreements and EPC contractors optimizing for installation risk transfer.
- Project Developers:Independent power producers and joint ventures control floating wind lease allocations. Scottish developers now bundle 25-year mooring integrity monitoring with initial hardware procurement, compressing pure-play manufacturing margins.
- EPC Contractors:Integrated engineering-procurement-construction firms anchor supply chain decisions through turnkey risk absorption. Norwegian PSA verification requirements extend their project timelines but filter substandard equipment.
- Utilities:Vertically integrated power generators with balance-sheet capacity.
- Government Entities:State-owned enterprises and national oil company diversifications.
EPC contractors anchor procurement volumes. Project developers are gaining share fastest through direct lease control and long-term service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European regulatory gravity, with Germany's Federal Maritime and Hydrographic Agency and Norway's Petroleum Safety Authority setting certification baselines that cascade across adjacent markets. Floating wind lease concentration in the North Sea and Celtic Sea concentrates anchor procurement among qualified marine geotechnical engineering providers.
Germany
Offshore wind auction mechanisms now mandate fatigue-performance certification that filters substandard anchor suppliers. The Federal Maritime and Hydrographic Agency enforces site-specific holding-capacity verification through mandatory field testing protocols. Project developers in the German Bight coordinate drag anchor procurement for transitional water depths alongside North Sea floating array pilots.
Norway
Deep-water lease areas off the southwest coast command premium pricing for geotechnically customized suction anchors. The Petroleum Safety Authority extends certification timelines through rigorous embedment verification requirements. Stavanger-based engineering clusters anchor suction anchor tooling specialization for pre-commercial floating wind arrays.
United Kingdom
Scottish floating wind developers in the Hywind lease areas specify DNV-certified drag configurations rated beyond 5,000 kN holding capacity. Crown Estate Scotland lease stipulations now require 25-year mooring integrity monitoring bundled with initial hardware procurement. Aberdeen marine engineering corridors concentrate installation crew capabilities for Celtic Sea pre-commercial deployments.
Portugal
Atlantic floating wind pipeline expansion lacks established anchor installation precedent, creating first-mover qualification windows for certified suppliers. National energy transition programs accelerate lease round issuance off the Iberian coast. Viana do Castelo port infrastructure anchors emerging fabrication and assembly capabilities for floating foundation mooring systems.
France
Offshore wind auction mechanisms align with EU Green Deal sustainability benchmarks for anchor holding capacity and fatigue performance. The country's national maritime regulator enforces certification requirements that mirror German and Danish precedents. Saint-Nazaire industrial zones concentrate jacket foundation pile anchor demand for transitional depth projects in the Bay of Biscay.
Offshore Wind Anchoring Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with engineering-procurement-construction capabilities separating premium positioning from pure-play manufacturing. The competitive terrain fragments across anchor typology specialization, installation methodology control, and subsea monitoring service bundling. Three archetypes dominate: integrated EPC firms with turnkey risk absorption, specialist anchor fabricators with proprietary tooling, and equipment lessors with fleet-leasing capabilities. M&A activity concentrates on installation vessel access and digital twin mooring monitoring technology licensing.
Among Netherlands-based mooring specialists, Vryhof Anchors B.V. and Bluewater Energy Services B.V. exemplify the specialist fabricator archetype with decades of North Sea deployment heritage. SBM Offshore N.V. occupies a position within the integrated EPC tier, representing turnkey engineering-procurement-construction capabilities spanning anchor design through platform hookup. NOV Inc. anchors the equipment control archetype, sitting within the supplier base that underpins installation method selection through critical pile-driving and dynamic positioning equipment.
| Leading Market Players |
|---|
| Vryhof Anchors B.V. |
| SBM Offshore N.V. |
| Delmar Systems, Inc. |
| Bluewater Energy Services B.V. |
| NOV Inc. |
| BW Offshore Limited |
| Trelleborg Marine & Infrastructure |
| Offspring International Limited |
| Cavotec SA |
| Others |
Value Network & Pricing Analysis
DNV certification standards gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while anchoring premium positioning for holders of fatigue-performance credentials in German and Norwegian tenders. Buyers face tiered procurement economics where geotechnically customized suction anchors command substantial engineering premiums over standardized drag configurations.
Pricing Analysis
North Sea procurement runs 15-25% above Iberian project economics due to BSH and PSA verification mandates. Three-tier pricing structure separates DNV-certified premium systems from standard commercial-grade anchors and economy pile configurations for transitional depths. Cost compression in the monopile segment is intensifying because of mature supply chain saturation in sub-50-meter zones. Independent power producers exhibit highest price sensitivity, while integrated utilities absorb engineering premiums for bundled 25-year monitoring contracts.
Supply Chain Analysis
Strait of Hormuz transit exposure for high-tensile alloy feedstock anchors European fabrication costs to nickel and chromium sourcing volatility from Indonesian and South African mining jurisdictions. Manufacturing gravity centers on Netherlands-based engineering clusters, Norwegian west-coast fabrication yards, and emerging Portuguese port infrastructure at Viana do Castelo. Mooring chain production draws from specialized steel mills in Belgium and Germany. Single-source vulnerability concentrates in proprietary suction anchor installation tooling held by a handful of North Sea contractors. Distribution runs through EPC contractor procurement desks and direct utility tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified marine geotechnical engineers capable of suction anchor deployment in complex seabed conditions remain concentrated among Stavanger and Aberdeen corridor contractors, creating bottlenecks that reshape competitive entry economics. Incumbents must defend positioning through controlled capability access, while new entrants face qualification timeline barriers.
For Market Incumbents: Secure anchor handling vessel access through long-term charter agreements or fleet acquisition to lock out emerging competitors facing DP-2 and DP-3 availability constraints. Deepen backward integration into high-tensile alloy supply through offtake agreements with Belgian and German specialty steel mills, insulating against nickel price volatility that threatens margin stability in drag anchor production. For New Entrants and Emerging Players: Mooring integrity monitoring services represent an under-served layer where incumbents focus on hardware margins. Target Portuguese Atlantic lease rounds lacking established installation precedent, where first-mover qualification windows remain open for certified suppliers. Enter through digital twin partnerships with sensor network providers, positioning for recurring revenue attachment rather than capital-intensive fabrication. For Investors and Strategic Acquirers: EU F-Gas Regulation retrofit deadlines reshape the acquisition landscape toward vessel operators with low-emission DP capabilities and anchor handling integration. Five-to-ten year viability favors suppliers with bundled engineering-procurement-construction-service capabilities over pure-play manufacturing. Watch German BSH and Norwegian PSA certification timeline extensions as the signal for qualification barrier tightening that concentrates vendor selection.| Strategic Initiative | Industry Significance |
|---|---|
| Anchor Handling Vessel Acquisition | DP-2 and DP-3 fleet control locks out competitors in German and Danish tender rounds. |
| Digital Twin Technology Licensing | Subsea sensor network integration creates 25-year recurring revenue attachment to hardware. |
| Portuguese Port Infrastructure Partnership | Viana do Castelo fabrication access anchors first-mover positioning in Atlantic lease rounds. |
| High-Tensile Alloy Backward Integration | Belgian and German steel mill offtake agreements insulate against nickel supply volatility. |
| DNV Fatigue-Performance Certification Investment | EU Green Deal auction compliance filters substandard suppliers from premium procurement pools. |
Research Methodology
Cross-validation between primary interviews with floating wind project developers, EPC contractor procurement leads, marine geotechnical engineering directors, and installation vessel operators anchors the qualitative findings. Secondary validation draws from DNV certification registries, BSH project approval databases, Crown Estate Scotland lease documentation, and EU F-Gas Regulation implementation notices. Bottom-up anchor procurement volume estimates triangulate against top-down floating wind capacity projections across the analysis window.
Sensitivity analysis around steel alloy price trajectories, vessel charter rate assumptions, and certification timeline scenarios frames the projection horizon. Segmentation modeling spans anchor typology, foundation architecture, installation methodology, water depth tier, and end-user contracting structure. CAGRs derive from compound growth mechanics applied to verified baseline procurement volumes. Industry-specific inputs include geotechnical survey density requirements, mooring line configuration standards, and evolving PSA verification protocols.
Forecasts assume regulatory continuity in German BSH, Norwegian PSA, and EU F-Gas regimes; material policy shifts would require re-modeling of certification timeline and vessel emission assumptions. Practitioners should keep alternative scenarios live as floating wind lease stipulations in emerging Portuguese and Celtic Sea basins evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Brazil Wind Energy Market