
 United Kingdom Renewable Energy Market | 2026-2036
United Kingdom Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Renewable Energy Market Analytics
MCS certification for heat pump installers is redrawing contractor eligibility across residential retrofit programmes. EDF Energy leverages its nuclear baseload position to balance intermittent renewable output on the national grid. ScottishPower Renewables anchors its growth in Scottish offshore zones with seabed leases from Crown Estate Scotland. Ørsted A/S dominates floating wind demonstration projects through its Dogger Bank joint venture stakes.
United Kingdom renewable energy encompasses electricity and heat generation from naturally replenishing sources including solar irradiance, wind kinetic energy, organic biomass feedstocks, and hydrological flow, with offshore wind turbines now scaling to 15 MW rated capacity and 220-metre rotor diameters for maximum yield per foundation. The primary purpose is decarbonising power supply while reducing import dependency on volatile natural gas markets. Offshore wind claims the deepest margin pools due to CfD strike price competition and capital intensity barriers, while photovoltaics on rooftop installations penetrates fastest among residential end users facing retail tariff spikes. Anaerobic digestion occupies a niche structural position in rural agricultural waste-to-energy circuits with limited scalability but stable feed-in tariff remnants.
Ofgem enforces price controls and network access codes that shape generator revenue streams and connection queue priorities. The Low Carbon Contracts Company administers CfD allocation rounds that determine which technologies secure fifteen-year revenue certainty. BEIS legacy frameworks and DESNZ successor policies govern renewable obligation certificate transitions. Stakeholders must monitor seabed leasing cadence from Crown Estate bodies and devolved administrations to anticipate pipeline timing and spatial constraints.
Market Dynamics
The Contracts for Difference auction mechanism is compressing developer margins while concentrating project ownership among capital-heavy utilities capable of absorbing construction risk on 15 MW offshore turbines.
Growth Catalysts
- CfD Allocation Rounds:The Low Carbon Contracts Company's competitive auction process guarantees fifteen-year revenue streams, de-risking offshore wind investments for institutional capital.
- Seabed Lease Expansion:Crown Estate Scotland's leasing cadence in Scottish and Welsh waters is unlocking gigawatt-scale development zones previously constrained by spatial planning.
- Heat Pump Retrofit Mandates:MCS certification requirements for installers are professionalising residential decarbonisation supply chains and redirecting contractor capacity toward electrification.
Market Restraints
- Grid Connection Queues:Ofgem's network access codes create multi-year interconnection backlogs that delay project energisation regardless of construction completion.
- Foundation Steel Costs:Monopile and jacket substructure fabrication concentrates in specialised North Sea yards with limited throughput elasticity.
- Skills Pipeline Gaps:HV cable installation and offshore commissioning expertise resides with a narrow contractor base, constraining simultaneous project execution.
Strategic Opportunities
- Floating Wind Demonstration:Dogger Bank joint ventures are validating semi-submersible platform economics for water depths exceeding sixty metres.
- Balancing Service Contracts:EDF Energy's nuclear baseload position creates arbitrage opportunities for renewable developers offering frequency response.
- Anaerobic Digestion Clustering:Agricultural waste-to-energy circuits in rural English counties exploit stable feed-in tariff remnants while biomethane injection expands.
Industry Challenges
- MCS Certification Bottlenecks:Heat pump installer accreditation timelines lag deployment targets, throttling residential retrofit throughput.
- Intermittency Balancing Costs:National Grid ESO's constraint payments to gas peakers erode renewable project netbacks during low-wind periods.
- Devolved Policy Friction:DESNZ successor frameworks and Scottish Government energy strategies create divergent consenting timelines across territorial waters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Renewable Energy Market |
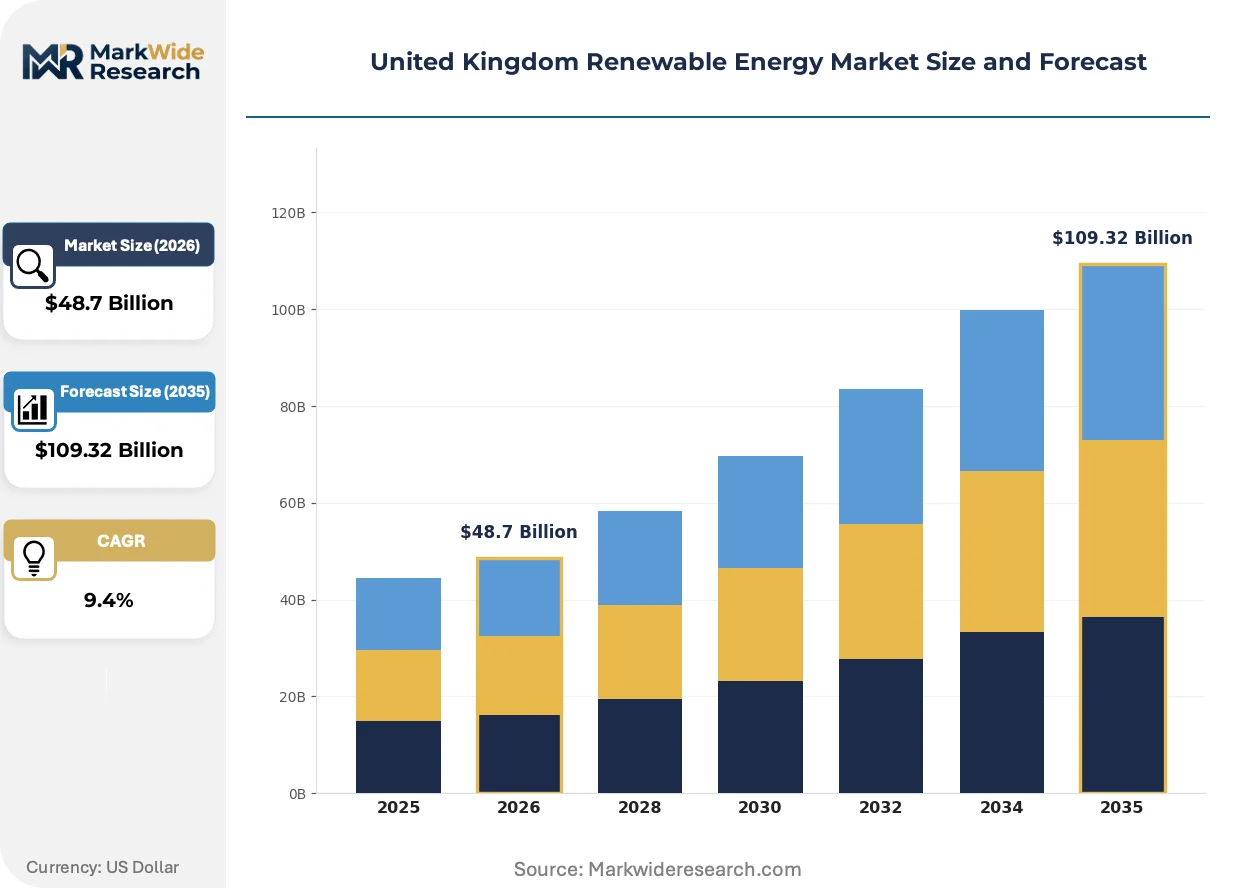
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydropower Technology: Photovoltaics, Offshore Wind, Onshore Wind, Anaerobic Digestion End User: Residential, Commercial, Industrial, Government Installation Type: Ground-Mounted, Rooftop, Floating, Building-Integrated |
| Companies Covered | Octopus Energy Ltd., EDF Energy, SSE, ScottishPower Renewables, Ørsted A/S, Greencoat UK Wind, Drax Group PLC, RES Group Ltd., Ecotricity Group Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Renewable Energy Market Evolving Landscape
Offshore wind turbine scaling is forcing supply chain reconfiguration while auction-based procurement compresses technology differentiation toward cost-out engineering.
Turbine scaling is bifurcating the offshore wind supply chain between 15 MW+ direct-drive machines for Round 4 CfD sites and smaller geared units for extension projects. ScottishPower Renewables and Ørsted joint ventures are exclusively specifying 220-metre rotor diameters for new seabed leases, marginalising sub-12 MW original equipment. This bifurcation is squeezing mid-scale turbine manufacturers from the UK project pipeline entirely.
DESNZ successor policies are accelerating the Renewable Obligation Certificate transition toward CfD-only support, eliminating grandfathered subsidy routes for biomass and onshore wind. The Low Carbon Contracts Company's administrative migration is forcing legacy generators into merchant exposure or early decommissioning. Offshore wind captures the residual policy certainty, while anaerobic digestion operators face feed-in tariff cliff edges without replacement mechanisms.
Corporate power purchase agreements are displacing utility-offtake as the primary demand channel for new renewable capacity. Data centre operators and hydrogen electrolyser projects in Teesside and Humberside are contracting directly with Scottish offshore clusters, bypassing supplier obligation schemes. This bilateral contracting concentrates in English industrial zones with grid upgrade commitments, leaving Welsh and Northern Irish projects dependent on regulated tariff routes.
United Kingdom Renewable Energy Market Segmentation
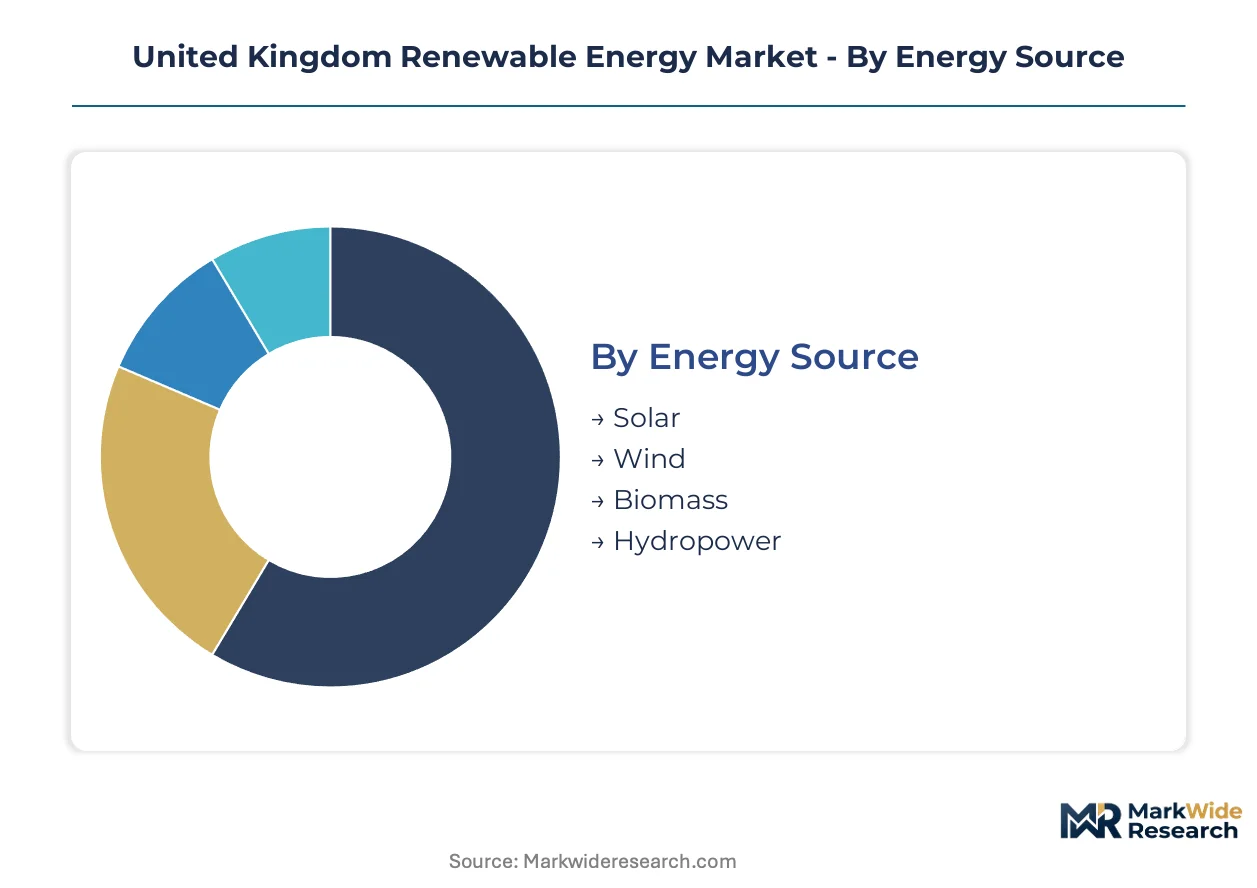
Segmentation in the United Kingdom renewable energy market reveals how CfD allocation rounds and Ofgem network codes concentrate capital flows across technologies and installation types. Understanding these divisions exposes where institutional investors deploy long-dated infrastructure capital versus where merchant risk persists.
Energy Source:
Ofgem's grid access codes and the Low Carbon Contracts Company's auction mechanisms differentiate revenue certainty across generation types, concentrating institutional capital toward sources with fifteen-year strike price guarantees.
- Wind:Kinetic energy conversion through 15 MW offshore turbines with 220-metre rotor diameters dominates CfD allocation rounds. Scottish and Welsh coastal waters absorb the bulk of new capacity as Crown Estate Scotland accelerates seabed leasing cadence.
- Solar:Photovoltaic irradiance capture scales fastest among residential end users facing retail tariff spikes. Rooftop installations penetrate suburban markets where MCS-certified installers redirect contractor capacity toward electrification retrofits.
- Biomass:Organic feedstock combustion faces Renewable Obligation Certificate transition cliffs without replacement mechanisms. Legacy generators confront merchant exposure or early decommissioning as DESNZ successor policies eliminate grandfathered subsidy routes.
- Hydropower:Hydrological flow conversion occupies mature run-of-river positions with limited new capacity. Environmental consenting constraints restrict greenfield development to small-scale pumped storage augmentation.
Wind handles the majority of throughput; Solar is the fastest mover on share.
Technology:
Capital intensity barriers and construction risk absorption capabilities determine which technologies concentrate ownership among utilities versus fragmented developer bases.
- Offshore Wind:Monopile and jacket substructure fabrication in specialised North Sea yards supports 15 MW+ direct-drive machines. Dogger Bank joint ventures validate semi-submersible platforms for water depths exceeding sixty metres.
- Photovoltaics:Silicon wafer assemblies on rooftop and ground-mounted configurations bypass supplier obligation schemes through corporate power purchase agreements. Data centre operators in Teesside contract directly with installation clusters.
- Onshore Wind:Geared turbine units for extension projects face planning consent friction in England while Scottish upland zones absorb residual development. Smaller rotor diameters marginalise this technology from CfD competition.
- Anaerobic Digestion:Agricultural waste-to-energy circuits in rural English counties exploit stable feed-in tariff remnants. Biomethane injection expands as biomethane-to-grid connections professionalise.
Offshore Wind captures the deepest margin pools; Photovoltaics shows the steepest expansion trajectory among new capacity additions.
End User:
Retail tariff exposure and balancing service requirements segment demand channels between regulated utility offtake and bilateral corporate contracting.
- Industrial:Hydrogen electrolyser projects in Humberside and Teesside anchor direct procurement from Scottish offshore clusters. Grid upgrade commitments in English industrial zones enable bypass of supplier obligation schemes.
- Residential:Heat pump retrofit mandates through MCS certification requirements professionalise decarbonisation supply chains. Installer accreditation timelines lag deployment targets, throttling throughput.
- Commercial:Data centre operators and corporate facilities contract renewable capacity through power purchase agreements. Frequency response arbitrage opportunities emerge for developers offering balancing services.
- Government:Public sector procurement aggregates demand through framework agreements with regulated tariff routes. Welsh and Northern Irish projects remain dependent on these channels absent grid upgrade commitments.
Industrial end users command the largest contract volumes; Residential retrofits are climbing the fastest on policy mandate intensity.
Installation Type:
Spatial planning constraints and foundation engineering economics determine where turbine scaling bifurcates supply chain configurations.
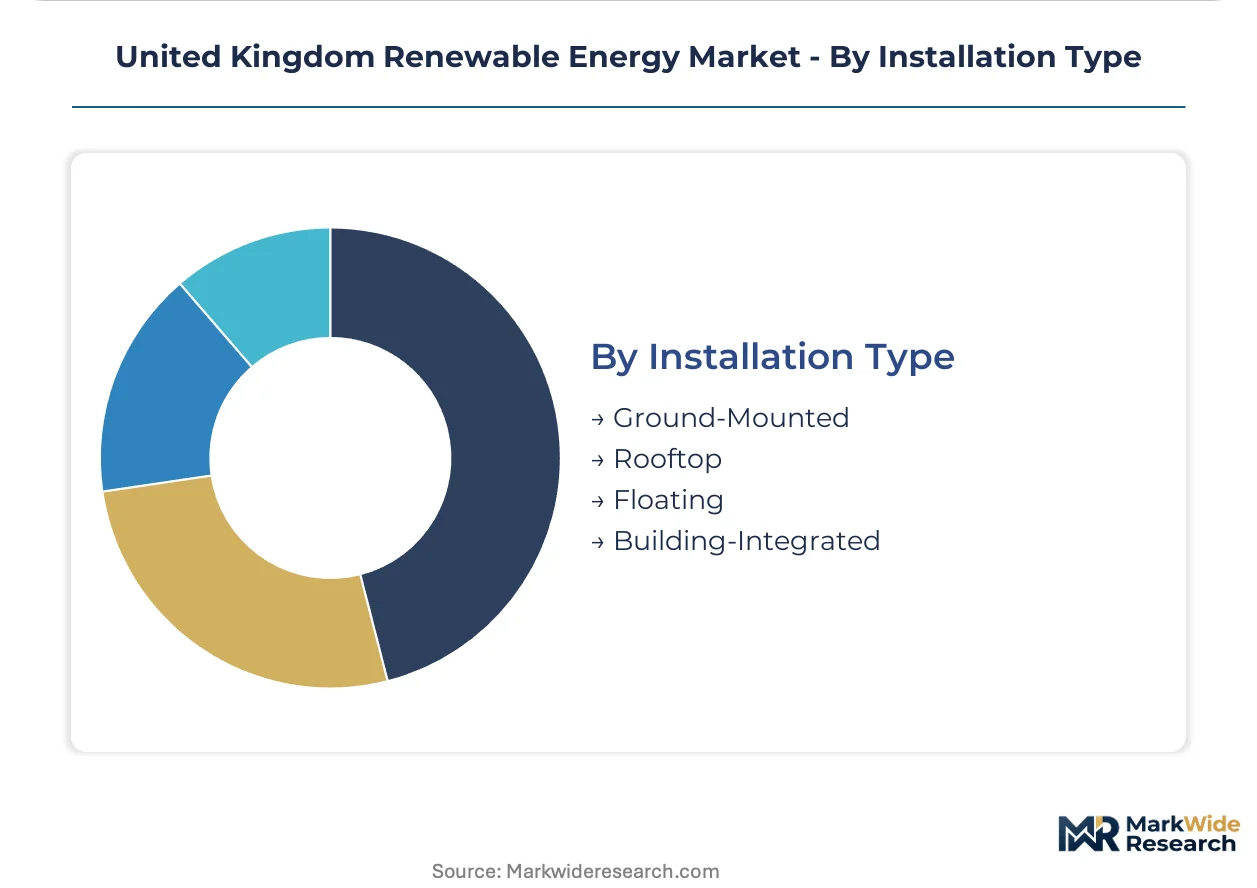
- Ground-Mounted:Terrestrial foundation systems for utility-scale solar and onshore wind concentrate in English agricultural land and Scottish upland zones. Planning consent timelines vary across devolved administration boundaries.
- Rooftop:Building-applied photovoltaic assemblies penetrate fastest among suburban residential and commercial estate segments. MCS certification requirements for installers redirect contractor eligibility across retrofit programmes.
- Floating:Semi-submersible platforms for offshore wind validate economics in water depths exceeding sixty metres. Ørsted joint ventures at Dogger Bank anchor demonstration project pipelines.
- Building-Integrated:Façade-embedded photovoltaic systems occupy niche architectural applications with premium cost structures. Limited scalability restricts this installation type to flagship commercial developments.
Ground-Mounted configurations handle the majority of utility-scale throughput; Floating installations are gaining share fastest on seabed lease expansion into deeper waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Western HVDC Link underwrites Scotland's role as the dominant generation zone, transmitting offshore wind output to English demand centers. National Grid's network reinforcement programme determines which sub-regions secure grid connection priority.
Scotland
Crown Estate Scotland's seabed leasing cadence unlocks gigawatt-scale offshore zones in Moray Firth and Firth of Forth. The Scottish Government's energy strategy diverges from DESNZ frameworks on consenting timelines. Aberdeen anchors floating wind demonstration clusters where semi-submersible platforms validate deep-water economics.
Wales
Celtic Sea lease rounds attract floating wind developers targeting water depths exceeding sixty metres. The Welsh Government's marine planning regime imposes spatial constraints on tidal stream co-location. Holyhead and Milford Haven concentrate port infrastructure investment for turbine component staging.
England North
Dogger Bank joint ventures anchor the world's largest offshore wind construction programme. Ofgem's network access codes prioritize grid connections for Teesside hydrogen electrolyser clusters. Hull and Grimsby host operations bases for 15 MW turbine maintenance fleets.
England South
London Array extension projects face aviation radar and shipping lane spatial conflicts. The Low Carbon Contracts Company's CfD allocation rounds concentrate capital toward eastern seabed zones rather than southern waters. Southampton and Portsmouth compete for floating wind port infrastructure investment.
Northern Ireland
Moyle Interconnector capacity constraints limit renewable export to Great Britain. The Utility Regulator's network price controls delay onshore wind grid reinforcement in western counties. Belfast Harbour concentrates tidal stream demonstration projects with limited scalability.
United Kingdom Renewable Energy Market Competitive Landscape
Listed leaders compete with private specialists across capital absorption capacity, with utilities trading equity market access against private capital's long-dated infrastructure patience. The market structure concentrates project ownership among capital-heavy entities capable of underwriting construction risk on 15 MW offshore turbines. Three archetypes dominate: integrated utilities with nuclear baseload positions, renewable pure-plays with CfD auction specialization, and infrastructure funds holding operational assets for yield. Competitive moves center on seabed lease accumulation and grid connection queue positioning.
Within the integrated utility tier, EDF Energy exemplifies baseload-balancing arbitrage strategies, while ScottishPower Renewables anchors Scottish offshore expansion through Crown Estate Scotland relationships. Ørsted A/S occupies the pure-play position, validating floating wind economics through Dogger Bank joint venture stakes. These three entities represent distinct capital deployment models: regulated utility balance sheets, devolved administration partnerships, and Danish state-backed international expansion.
| Leading Market Players |
|---|
| Octopus Energy Ltd. |
| EDF Energy |
| SSE |
| ScottishPower Renewables |
| Ørsted A/S |
| Greencoat UK Wind |
| Drax Group PLC |
| RES Group Ltd. |
| Ecotricity Group Ltd. |
| Others |
Value Network & Pricing Analysis
Direct-drive generator substitution for geared drivetrains in 15 MW offshore turbines simultaneously concentrates supply geography around Danish and German component specialists and compresses pricing economics through standardised platform architectures. This technology shift eliminates mid-scale turbine suppliers from CfD auction competition while anchoring premium pricing power with integrated utilities capable of absorbing construction risk.
Pricing Analysis
Volume-discount tiering structures separate CfD-backed offtake contracts from merchant exposure arrangements, with strike price competition driving cost-out engineering across Round 4 auction rounds. Price differentiation hinges on construction completion guarantees and grid connection queue priority secured through Ofgem's network access codes. Pricing pressure intensifies in merchant-exposed biomass and onshore wind segments as Renewable Obligation Certificate transitions eliminate grandfathered subsidies. Industrial hydrogen electrolyser projects in Teesside demonstrate lowest price sensitivity due to direct procurement bypass of supplier obligation schemes.
Supply Chain Analysis
Denmark and Germany anchor nacelle assembly and direct-drive generator fabrication, while South Korea and China dominate monopile steel supply and high-voltage cable manufacturing. Rare earth magnet dependencies for permanent magnet generators draw from Chinese processing concentration, creating single-source vulnerability for turbine drivetrain components. Supply chain risk concentrates in specialised North Sea foundation yards with limited throughput elasticity for jacket and monopile substructures. Distribution runs through EPC contractor consortia that stage components at Aberdeen, Hull, and Grimsby port facilities prior to offshore installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom renewable energy market constitutes high-growth infrastructure disruption underwritten by CfD auction mechanism maturation and 15 MW turbine scaling that eliminates fragmented developer participation.
For Market Incumbents: Shield operational asset portfolios from merchant price exposure through CfD re-contracting at prevailing strike prices before Renewable Obligation Certificate cliffs accelerate. Consolidate seabed lease positions in Scottish waters through Crown Estate Scotland relationship deepening, as floating wind demonstration projects validate deep-water economics and attract institutional capital rotation. Prioritise vertical integration into HV cable installation capabilities to capture margin pools currently leaking to narrow contractor bases. For New Entrants and Emerging Players: Heat pump installer accreditation bottlenecks present service-layer gaps where MCS certification capacity expansion unlocks residential retrofit throughput constrained by professionalised supply chains. Target Welsh Celtic Sea lease rounds for floating wind joint venture entry, where water depth economics exceed sixty metres and devolved marine planning creates spatial differentiation from saturated Scottish zones. Pursue corporate power purchase agreement origination for data centre operators in English industrial zones as bilateral contracting displaces regulated utility offtake. For Investors and Strategic Acquirers: Secondary-cycle assets sit with infrastructure funds holding operational offshore wind farms with CfD contracts approaching re-contracting windows. Long-dated infrastructure viability extends across the analysis window for assets with secured grid connection and seabed lease tenure, while merchant-exposed biomass generators face stranded asset risk. Monitor Low Carbon Contracts Company allocation round strike price trajectories as inflection indicators for developer margin compression and institutional capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Accumulation | Crown Estate Scotland leasing cadence determines pipeline timing for gigawatt-scale offshore zones in Moray Firth. |
| CfD Auction Specialisation | Strike price competition expertise separates capital-heavy utilities from construction risk-averse developers. |
| Floating Wind Demonstration | Dogger Bank joint ventures validate semi-submersible platform economics for water depths exceeding sixty metres. |
| Grid Connection Queue Positioning | Ofgem network access code priority accelerates project energisation regardless of construction completion status. |
| Balancing Service Contracting | Frequency response arbitrage opportunities emerge for renewable developers offering National Grid ESO services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DESNZ policy frameworks, Crown Estate Scotland leasing registers, and Low Carbon Contracts Company auction disclosures. Primary interviews engaged utility planning officers, independent power producer project developers, EPC contractors, and grid operators across Scottish, Welsh, and English development zones. Bottom-up project pipeline aggregation triangulates against top-down regulatory capacity targets without reliance on single-source disclosures.
Segmentation dimensions modeled span energy source, technology type, end user category, and installation configuration across the projection horizon. Analytical frameworks incorporate CfD strike price trajectories, seabed lease cadence, and grid reinforcement commitment schedules. CAGRs derive from capacity addition forecasts weighted by capital intensity and construction timeline distributions specific to offshore wind, solar photovoltaic, and anaerobic digestion pathways.
Underlying assumptions cover CfD auction participation rates, foundation steel cost stability, and HV cable installation contractor availability, with deviation risk concentrated in Ofgem network access queue prioritisation shifts and devolved administration consenting timeline divergence. Recalibration cycles align with material shifts in Low Carbon Contracts Company allocation round schedules and Crown Estate seabed leasing announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Offshore Wind Tower Market