
 Asia-Pacific Wind Power Equipment Market | 2026-2036
Asia-Pacific Wind Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wind Power Equipment Market Outlook
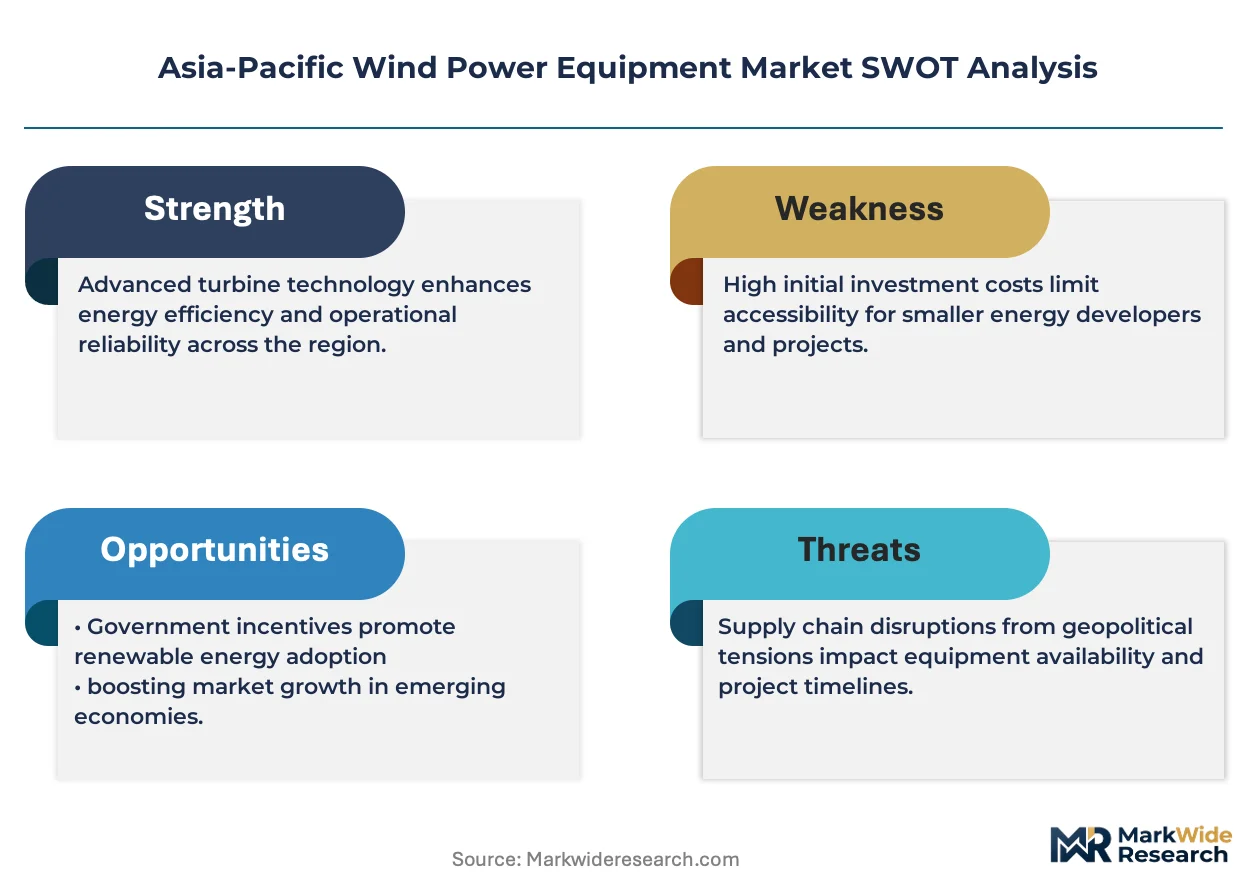
Project finance through construction-to-term loan structures is narrowing the field of turbine suppliers that can underwrite multi-gigawatt offshore arrays. Xinjiang Goldwind Science & Technology Co., Ltd. anchors its competitiveness through captive blade manufacturing and rare-earth magnet supply chains. Siemens Gamesa Renewable Energy S.A. differentiates via geared drivetrain architectures optimized for typhoon-class wind regimes. MingYang Smart Energy leverages semi-submersible floating platform designs to access deeper waters beyond fixed-foundation limits.
Asia-Pacific wind power equipment encompasses the integrated machinery, structural components, and control systems that convert kinetic wind energy into grid-synchronous electrical output, with modern turbines rated between 5 MW and 18 MW and rotor diameters exceeding 220 meters for offshore configurations. The primary industrial purpose centers on delivering baseload-competitive renewable generation to utility-scale grids and industrial offtakers. Turbines and blades capture the dominant share of capital expenditure, while floating wind technology represents the fastest-expanding technology segment as Japan and South Korea advance demonstration projects in waters exceeding 60 meters depth. Control systems concentrate margin pools due to embedded power electronics and predictive maintenance software.
China's MIIT enforces GB standards for turbine structural integrity and grid-code compliance, while Japan's METI administers feed-in tariff qualification and sea-use licensing for offshore developments. Australia's CEA coordinates interconnection standards across state-level transmission networks, creating fragmented but deepening regulatory density. Stakeholders must monitor how floating foundation certification protocols evolve across multiple national maritime authorities, as these rules will determine which technology suppliers can bid into the next wave of deepwater auctions.
Market Dynamics
The Asia-Pacific wind power equipment market is undergoing a structural reconfiguration as floating foundation technology unlocks deeper water sites previously inaccessible to fixed-bottom turbines, forcing suppliers to retool manufacturing footprints and certification capabilities.
Growth Catalysts
- Japan's feed-in tariff regime:METI's offshore wind qualification framework guarantees long-term offtake prices, de-risking capital deployment for developers targeting waters beyond 60 meters depth.
- Coal port conversion:Jiangsu and Guangdong provincial authorities are repurposing retired thermal fueling infrastructure into turbine staging hubs, slashing logistics costs for 15+ MW nacelle assemblies.
- Rare-earth magnet supply security:China's domestic heavy rare-earth processing capacity anchors permanent magnet generator production, insulating regional turbine OEMs from import dependency.
Market Restraints
- Steel alloy input volatility:Specialized high-grade plate for monopile jackets faces price swings tied to nickel and molybdenum spot markets, compressing EPC margin certainty.
- Korean fabrication bottleneck:Heavy-lift vessel construction concentrates in three Hyundai and Samsung yards, creating queuing delays for floating platform hull delivery.
- Grid-code fragmentation:Australia's CEA coordinates interconnection standards across five state networks, forcing turbine suppliers to maintain multiple converter software variants.
Strategic Opportunities
- Vietnam's offshore licensing pipeline:The national power regulator's tightened grid-connection standards favor developers with integrated nacelle-blade-tower capabilities, filtering out pure traders.
- Hybrid wind-hydrogen offtake:Japanese industrial consortia are contracting dedicated renewable supply for electrolyzer clusters, creating anchor demand beyond merchant power markets.
- Semi-submersible platform standardization:Convergence of classification society rules across Japan's Nippon Kaiji Kyokai and South Korea's KR is enabling modular floater designs portable across licensing jurisdictions.
Industry Challenges
- Marine warranty surveyor scarcity:Certified inspectors for floating foundation tow-out and hook-up operations number fewer than 40 across the entire region, throttling project commissioning cadence.
- Legacy SCADA integration:Retrofitting predictive maintenance algorithms onto turbines with 10+ year-old control architectures requires custom firmware bridges that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wind Power Equipment Market |
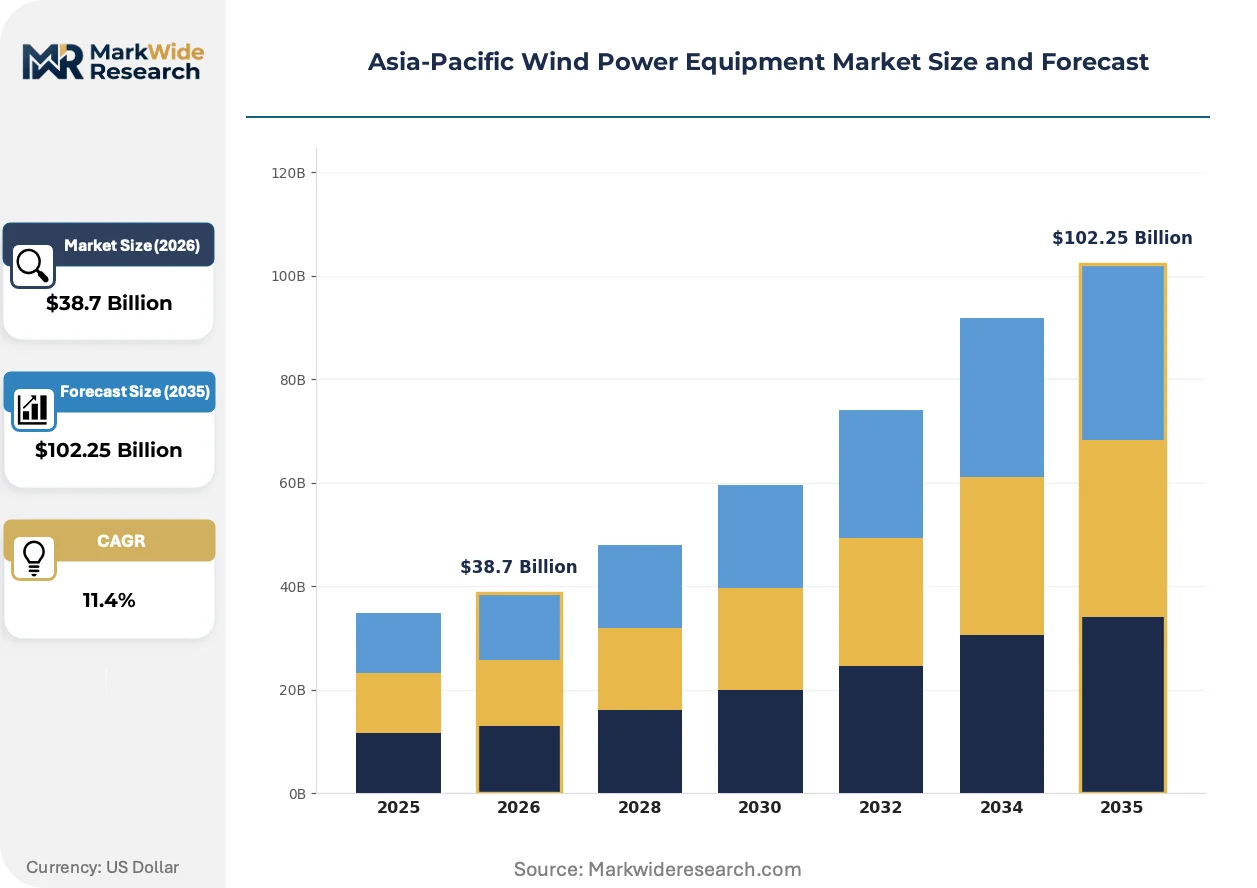
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Blades, Gearboxes, Control Systems Application: Onshore, Offshore, Utility Scale, Distributed Generation Technology: Horizontal Axis, Vertical Axis, Hybrid Systems, Floating Wind End User: Developers, Utilities, Independent Power Producers, Government Entities |
| Companies Covered | Envision Group, Xinjiang Goldwind Science & Technology Co., Ltd., Sany Heavy Industry Co., Ltd., Siemens Gamesa Renewable Energy S.A., General Electric Company, MingYang Smart Energy, Vestas Wind Systems AS, Suzlon Energy Limited, INOX Wind Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wind Power Equipment Market Strategic Shifts
Digital twin technology is compressing design-validation cycles while regulatory pressure on grid stability is forcing tighter integration between turbine power electronics and transmission operator control rooms.
Blade health monitoring via embedded fiber-optic strain sensors is digitizing O&M scheduling across offshore fleets. Japanese and Korean operators deploying 12+ MW turbines are retrofitting existing installations with continuous structural load tracking, enabling condition-based replacement rather than calendar-driven blade swaps and extending asset life beyond original design assumptions.
China's MIIT is enforcing updated GB standards for low-voltage ride-through and frequency response, compelling turbine OEMs to redesign converter control algorithms. The regulations mandate sub-150 millisecond grid fault response times, pushing suppliers toward silicon carbide power modules that reduce switching losses while meeting the tighter technical specifications.
Utility offtakers in Australia are unbundling turbine supply from long-term service agreements, forcing OEMs to compete on capital cost alone while third-party service providers capture aftermarket revenue. Queensland and Victoria state-owned generators are leading this procurement split, creating a two-tier supplier landscape where pure manufacturers face margin pressure independent of operational performance guarantees.
Asia-Pacific Wind Power Equipment Market Segmentation
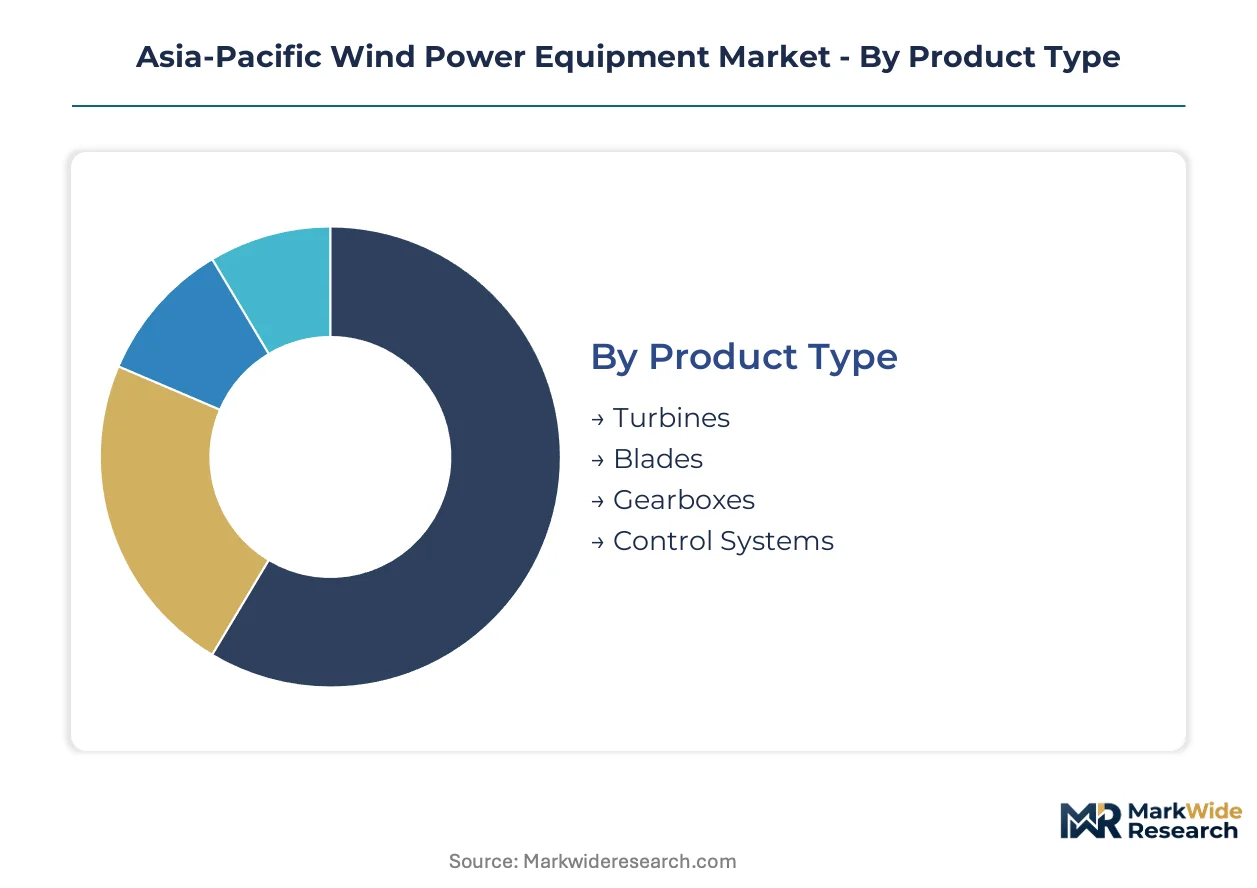
Segmentation reveals how capital flows concentrate in the Asia-Pacific wind power equipment market. Equipment mix varies sharply between mature onshore provinces and emerging offshore licensing zones, while technology selection tracks water depth and grid-connection standards.
Product Type:
Mature turbine and blade manufacturing anchors the heavy equipment segment, while emerging control system technologies are capturing expanding margin pools through embedded power electronics.
- Turbines:Nacelle assemblies rated 5 MW to 18 MW integrate generators, drivetrains, and yaw systems. Procurement concentrates along China's eastern seaboard where Jiangsu and Guangdong provincial authorities are converting retired coal ports into staging hubs for 15+ MW offshore units.
- Blades:Composite structures exceeding 100 meters in length for offshore configurations demand specialized resin infusion and carbon fiber layup. Xinjiang Goldwind Science & Technology Co., Ltd. maintains competitiveness through captive blade manufacturing that insulates against supply disruption.
- Gearboxes:Geared drivetrain architectures dominate typhoon-class wind regimes, with planetary and helical stages transmitting rotor torque to generator speed.
- Control Systems:Embedded power electronics and predictive maintenance software concentrate margin pools, with China's MIIT enforcing GB standards for low-voltage ride-through and sub-150 millisecond grid fault response.
Turbines retain volume leadership; control systems hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive offshore arrays from distributed generation deployments targeting industrial offtakers and rural electrification.
- Onshore:Fixed-bottom turbines in wind-rich corridors feed utility-scale grids. Deployment concentrates in China's northern provinces and Australia's southeastern transmission networks where land availability and grid capacity align.
- Offshore:Fixed-foundation arrays in waters under 60 meters depth dominate current procurement, with floating wind technology representing the fastest-expanding technology segment as Japan and South Korea advance demonstration projects.
- Utility Scale:Multi-gigawatt arrays require construction-to-term loan structures that narrow the field of turbine suppliers capable of underwriting project finance.
- Distributed Generation:Smaller turbines serving industrial offtakers and rural electrification bypass transmission congestion in Australia's fragmented state-level networks.
Onshore installations retain volume leadership; offshore applications hold the steepest expansion curve.
Technology:
Volume concentration favors horizontal axis designs, while customer type differentiation emerges between utility-scale horizontal deployments and specialized vertical axis applications.
- Horizontal Axis:Upwind rotor configurations dominate utility-scale procurement, with pitch control and variable-speed operation optimizing energy capture across wind speed distributions.
- Vertical Axis:Darrieus and Savonius designs serve niche distributed generation applications where omnidirectional wind capture reduces yaw system complexity.
- Hybrid Systems:Integrated wind-solar or wind-storage configurations address grid stability requirements under China's MIIT frequency response mandates.
- Floating Wind:Semi-submersible and tension-leg platform designs unlock waters exceeding 60 meters depth, with MingYang Smart Energy leveraging semi-submersible floating platform designs to access deeper waters beyond fixed-foundation limits.
Horizontal axis technology retains volume leadership; floating wind holds the steepest expansion curve.
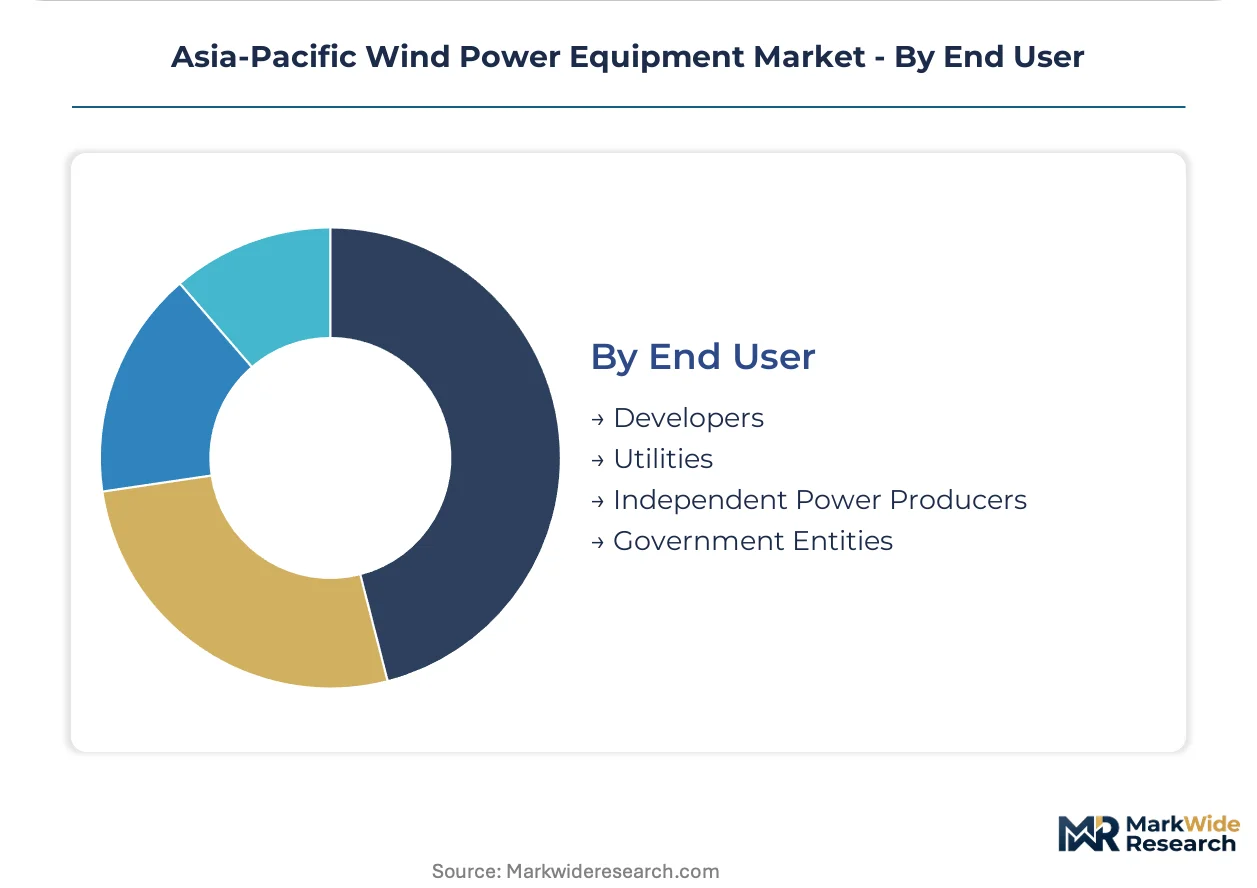
End User:
Supply concentration clusters around developers and utilities with balance-sheet capacity to underwrite long-dated renewable assets, while government entities shape procurement through licensing and tariff mechanisms.
- Developers:Project sponsors bidding into Vietnam's offshore licensing pipeline face tightened grid-connection standards that favor integrated nacelle-blade-tower capabilities.
- Utilities:Queensland and Victoria state-owned generators in Australia are unbundling turbine supply from long-term service agreements, forcing OEMs to compete on capital cost alone.
- Independent Power Producers:Merchant power developers capture revenue through power purchase agreements and spot market exposure, with hybrid wind-hydrogen offtake creating anchor demand beyond merchant markets.
- Government Entities:Public procurement drives rural electrification and strategic energy security projects, with Japan's METI feed-in tariff regime guaranteeing long-term offtake prices for offshore developments.
Utilities retain volume leadership; independent power producers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances across the Asia-Pacific wind power equipment market tilt toward surplus in China and deficit in Japan and South Korea, with Vietnam and Australia occupying intermediate positions shaped by domestic manufacturing scale and offshore development timelines.
China
Jiangsu and Guangdong provinces drive procurement of 15+ MW nacelle assemblies through converted coal port infrastructure. MIIT enforces updated GB standards for low-voltage ride-through and sub-150 millisecond grid fault response, compelling converter redesigns. The Yangtze River Delta anchors blade manufacturing clusters where captive rare-earth magnet supply chains insulate producers from import dependency.
Japan
METI's feed-in tariff regime guarantees long-term offtake prices for floating wind developments beyond 60 meters depth. The Kanto region concentrates project development activity, while Kyushu hosts demonstration arrays testing semi-submersible platform designs. Classification society protocols from Nippon Kaiji Kyokai shape certification requirements for deepwater deployments.
South Korea
Heavy-lift vessel construction concentrates in Hyundai and Samsung yards serving floating platform hull demand. KR certification rules converge with Japanese standards to enable modular floater portability. The Busan-Ulsan industrial corridor faces queuing delays as fabrication capacity strains against project commissioning timelines.
Vietnam
The national power regulator's tightened grid-connection standards favor developers with integrated nacelle-blade-tower capabilities. Southern coastal provinces attract procurement scaling as offshore licensing advances. Pure trading intermediaries face filtering pressure under technical qualification requirements.
Australia
Queensland and Victoria state-owned generators unbundle turbine supply from long-term service agreements, forcing capital-cost-only competition. CEA coordinates interconnection standards across five state networks, fragmenting converter software requirements. The southeastern transmission corridor hosts utility-scale deployment concentration.
Asia-Pacific Wind Power Equipment Market Competitive Environment
On the supply side, the industry is consolidating around turbine OEMs capable of underwriting multi-gigawatt offshore arrays through construction-to-term loan structures. Three archetypes dominate: vertically integrated Chinese manufacturers with captive component supply, European specialists in geared drivetrain architectures for typhoon regimes, and emerging players in semi-submersible floating platforms. Competitive moves center on backward integration into blade manufacturing and strategic partnerships for floating foundation certification.
Among China-based fabricators, Xinjiang Goldwind Science & Technology Co., Ltd. and MingYang Smart Energy occupy positions defined by upstream control over critical supply chains. Siemens Gamesa Renewable Energy S.A. represents the European specialist archetype in regional competition. These three exemplify divergent strategic postures: captive magnet supply versus floating platform specialization versus geared drivetrain optimization.
| Leading Market Players |
|---|
| Envision Group |
| Xinjiang Goldwind Science & Technology Co., Ltd. |
| Sany Heavy Industry Co., Ltd. |
| Siemens Gamesa Renewable Energy S.A. |
| General Electric Company |
| MingYang Smart Energy |
| Vestas Wind Systems AS |
| Suzlon Energy Limited |
| INOX Wind Limited |
| Others |
Value Chain & Pricing Dynamics
China's heavy rare-earth processing concentration anchors permanent magnet generator production, feeding margin pools downstream into nacelle assemblies where captive supply chains insulate OEMs from import dependency and price volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels. Price differentiation tracks certification grade against Nippon Kaiji Kyokai and KR standards, alongside volume scale for multi-gigawatt arrays. Pricing pressure stems from Australia's unbundling of turbine supply from service agreements, forcing capital-cost-only competition. State-owned generators in Queensland and Victoria exhibit highest price sensitivity, while Japanese developers under METI feed-in tariff guarantees show lowest.
Supply Chain Analysis
Export controls on high-grade steel alloys and silicon carbide power modules limit technology flows into regional converter manufacturing. Geographic supply concentration centers on China for rare-earth magnets and blade composites, South Korea for heavy-lift vessel hulls, and Japan for precision drivetrain components. Raw material dependencies include nickel-molybdenum plate for monopiles, carbon fiber for blades, and heavy rare-earth elements for generators. Single-source vulnerability concentrates in Korean fabrication yards. Distribution runs through converted coal port staging hubs along China's eastern seaboard.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating wind technology sits at early-cycle expansion, with Japan and South Korea demonstration projects in waters exceeding 60 meters depth accelerating commercialization timelines beyond fixed-foundation saturation.
For Market Incumbents: Pre-empt margin compression by securing captive blade manufacturing capacity and locking rare-earth magnet supply agreements before feedstock competition intensifies. Invest in Nippon Kaiji Kyokai and KR dual certification for semi-submersible platforms to maintain bidding eligibility across Japanese and Korean licensing rounds. Defensive consolidation into floating foundation engineering capabilities counters pure-play floater entrants. For New Entrants and Emerging Players: Pursue Vietnam's offshore licensing pipeline where tightened grid-connection standards filter out pure traders and favor integrated nacelle-blade-tower suppliers. Target hybrid wind-hydrogen offtake contracts with Japanese industrial consortia as the most penetrable demand segment beyond merchant power markets. Lead with marine warranty surveyor training partnerships to overcome commissioning bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European turbine specialists lacking floating platform capabilities. Five-to-ten year viability hinges on conversion from fixed-bottom to deepwater technology portfolios. Acquisition targets include semi-submersible engineering boutiques with dual Japan-Korea certification progress. Watch floating foundation tow-out inspector training pipeline expansion as inflection indicator for project commissioning cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Certification Investment | Dual Nippon Kaiji Kyokai and KR approval unlocks bidding across Japanese and Korean deepwater auctions. |
| Coal Port Staging Hub Conversion | Jiangsu and Guangdong provincial infrastructure repurposing slashes logistics costs for 15+ MW nacelle assemblies. |
| Rare-Earth Magnet Supply Agreement | Captive heavy rare-earth processing access insulates turbine OEMs from China's export quota volatility. |
| Marine Warranty Surveyor Training Program | Expanding certified inspector pools beyond 40 regional practitioners accelerates floating foundation commissioning timelines. |
| Hybrid Wind-Hydrogen Power Purchase Agreement | Japanese electrolyzer cluster offtake creates anchor demand beyond merchant electricity market exposure. |
Study Parameters
Cross-validation between utility planning officer interviews and IEA project development databases anchors the qualitative findings. Primary fieldwork engaged EPC contractors, IPP project developers, grid operators, and aftermarket service heads across China, Japan, South Korea, Vietnam, and Australia. Secondary sources include MIIT GB standard filings, METI feed-in tariff qualification records, FERC-equivalent interconnection dockets, and customs trade data for turbine component flows. Bottom-up installation forecasts triangulate against top-down utility procurement pipeline aggregates.
Calibration against historical capacity addition trajectories and announced project development timelines shapes the analytical framework across the projection horizon. Segmentation dimensions encompass turbine rating tier, foundation type, water depth class, grid-connection standard, and regional regulatory cluster. CAGRs derive from compound growth path modeling anchored to disclosed project finance commitments and licensing round schedules. Forecast inputs incorporate steel alloy price indices and heavy-lift vessel delivery queue estimates.
Sensitivities concentrate around floating foundation certification timeline delays, rare-earth export quota adjustments, and Korean yard fabrication bottlenecks. Forecasts embed assumptions regarding METI tariff continuity and Vietnam's grid-code enforcement intensity. Cross-checking against IEA renewable capacity outlooks and project finance database tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Market