
 Global Wind Power Equipment Market | 2026-2036
Global Wind Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind Power Equipment Market Foresight
Long-term service agreements and predictive maintenance software is shifting revenue models from pure hardware sales to lifecycle contracts across the wind power equipment value chain. Siemens Gamesa Renewable Energy leverages its offshore service footprint to secure multi-decade turbine availability contracts. Goldwind anchors its position through direct-drive technology leadership and captive generator production. Vestas competes on blade manufacturing scale and digital fleet optimization platforms.
Wind power equipment encompasses the integrated mechanical and electrical systems that convert kinetic wind energy into grid-synchronous electricity, including rotor assemblies exceeding 220 meters in diameter, pitch control systems, and power converters rated for medium-voltage collection. Utility-scale installations dominate absolute capacity additions, while offshore wind farms represent the fastest-growing application segment due to higher capacity factors and seabed leasing expansion. Direct drive technology is displacing geared architectures in offshore deployments, where reduced mechanical complexity lowers maintenance costs for remote marine environments.
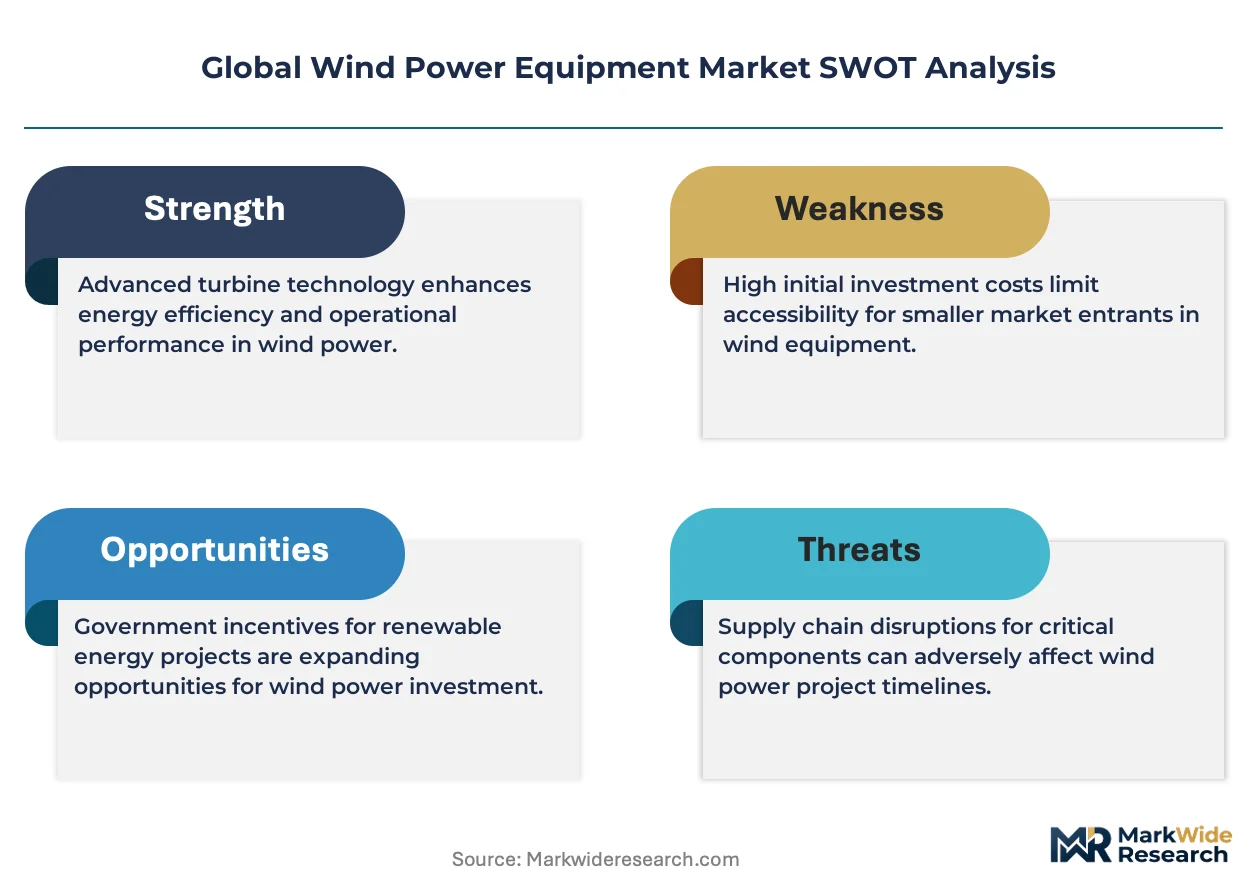
The EU Green Deal and F-Gas Regulation constrain refrigerant and insulation material choices in European turbine manufacturing, while China's GB standards and dual carbon goals enforce domestic content thresholds and carbon intensity benchmarks for equipment certification. The US FAA and Coast Guard coordinate on offshore turbine airspace and navigation lighting requirements. Stakeholders must monitor evolving grid interconnection standards and local content rules as procurement shifts toward integrated energy storage and green hydrogen co-location projects.
Market Dynamics
Direct drive technology is displacing geared drivetrains across offshore installations, compressing maintenance schedules and reshaping supplier qualification criteria for nacelle assembly partners.
Growth Catalysts
- EU Green Deal carbon intensity benchmarks:Equipment certification now requires lifecycle emissions disclosure, pulling demand toward manufacturers with vertically integrated generator production.
- China's dual carbon goals:Domestic content thresholds in GB standards enforce local blade and tower sourcing, consolidating procurement around state-backed turbine developers.
- Offshore seabed leasing expansion:Germany, the United States, and Taiwan are auctioning marine zones with grid connection guarantees, accelerating procurement of 15MW-plus turbine systems.
Market Restraints
- Rare earth magnet supply concentration:Neodymium processing concentrates in China, exposing direct drive manufacturers to export quota volatility and forced technology transfer requirements.
- F-Gas Regulation refrigerant constraints:The EU's phasedown of hydrofluorocarbons limits cooling system options for power converters, extending qualification timelines for European turbine deployments.
- Geared architecture lock-in:Existing onshore fleets in the United States and India carry sunk capital in gearbox maintenance infrastructure, slowing adoption of direct drive repowering.
Strategic Opportunities
- Green hydrogen co-location projects:Denmark and the Netherlands are mandating electrolyzer-ready grid connections at offshore wind zones, creating bundled equipment procurement for turbine-to-hydrogen systems.
- Predictive maintenance software penetration:Uncontracted aftermarket service revenue in aging European and Chinese fleets represents addressable white space for digital fleet optimization platforms.
- India's repowering mandate:Sub-megawatt turbine replacements below 2MW capacity trigger accelerated depreciation, opening retrofit demand for control system and blade upgrades.
Industry Challenges
- Composite blade recycling infrastructure gap:Thermoset resin disposal lacks scaled thermal or chemical processing capacity, exposing manufacturers to extended producer responsibility liabilities in Germany and the Netherlands.
- Medium-voltage power converter certification backlog:Grid code harmonization between FERC interconnection standards and EU network codes delays type testing, compressing project commissioning windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind Power Equipment Market |
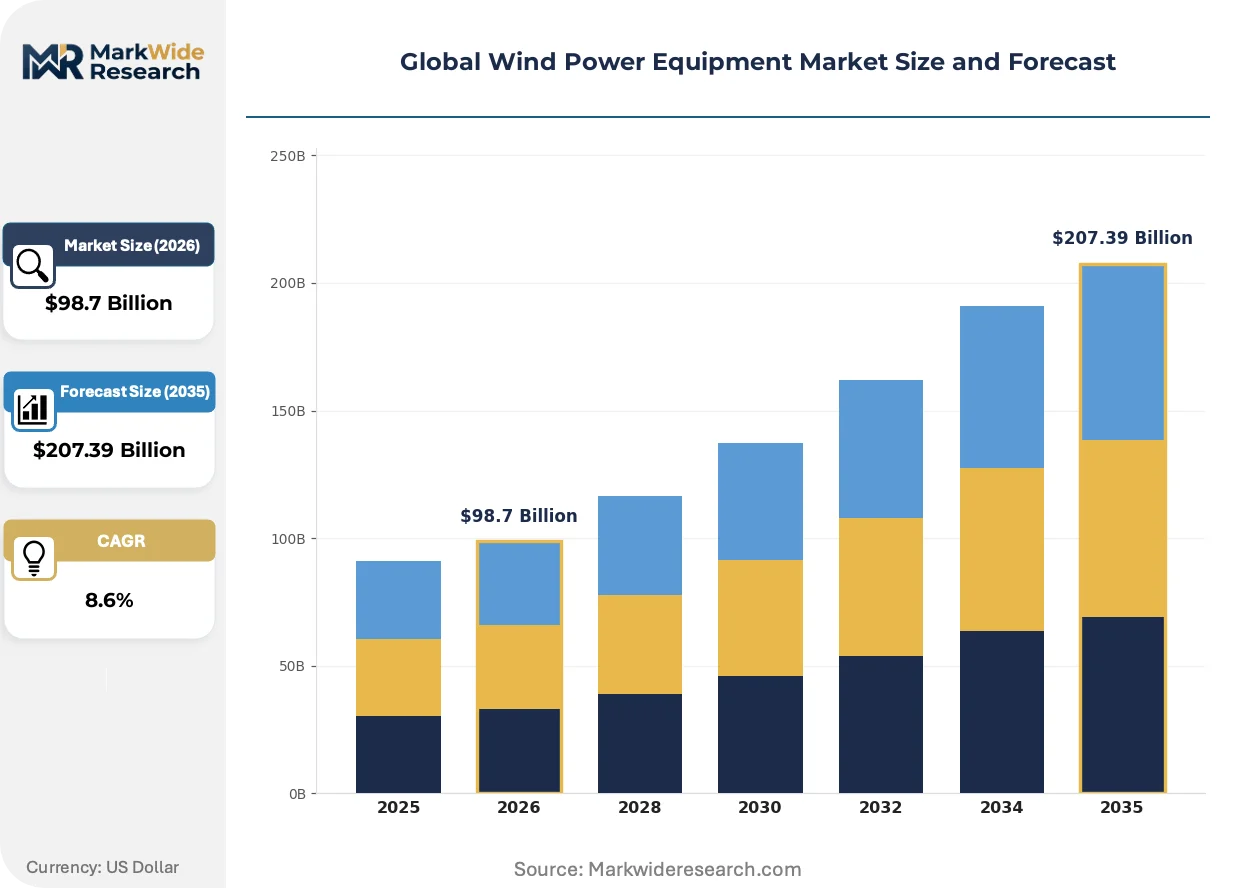
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $207.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wind Turbines, Gearboxes, Blades, Generators, Controllers Technology: Direct Drive, Variable Speed, Fixed Speed, Doubly-Fed Induction Generator, Synchronous Generator Application: Utility Scale, Distributed Generation, Offshore Wind Farms, Remote Power Supply End User: Independent Power Producers, Energy Service Companies, Grid Operators, Renewable Project Developers |
| Companies Covered | Mingyang Smart Energy, Siemens Gamesa Renewable Energy, Goldwind, GE Renewable Energy, Suzlon Energy, Envision Energy, Vestas, Nordex SE, Windey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind Power Equipment Market Shifts & Advancements
Scale escalation in rotor diameter and nacelle mass is forcing concurrent innovation in installation vessels, port infrastructure, and segmented blade logistics. Three developments are compressing deployment timelines and redrawing competitive boundaries.
Hybrid concrete-steel tower designs are expanding into hub heights above 160 meters for low-wind-speed sites in Germany and the United States. Developers in the American Midwest and Northern Europe are specifying these configurations to access higher shear wind profiles. The technology is expanding into markets previously dominated by tubular steel, compressing levelized cost thresholds for onshore projects below traditional steel economics.
The EU F-Gas Regulation's phasedown schedule is forcing refrigerant transitions in converter cooling systems. Manufacturers must qualify hydrofluoroolefin alternatives or water-glycol architectures, extending type certification cycles by 12-18 months. Offshore turbine platforms with sealed nacelle environments face the steepest redesign requirements, with Danish and German developers front-loading procurement to beat 2027 quota reductions.
Power purchase agreement structures now embed turbine availability guarantees rather than equipment warranties alone. European offshore developers are unbundling long-term service from initial capital contracts, selecting specialist providers on predictive algorithm performance. Danish and UK procurement teams are driving this shift, compressing margins for manufacturers without captive service platforms.
Global Wind Power Equipment Market Segmentation
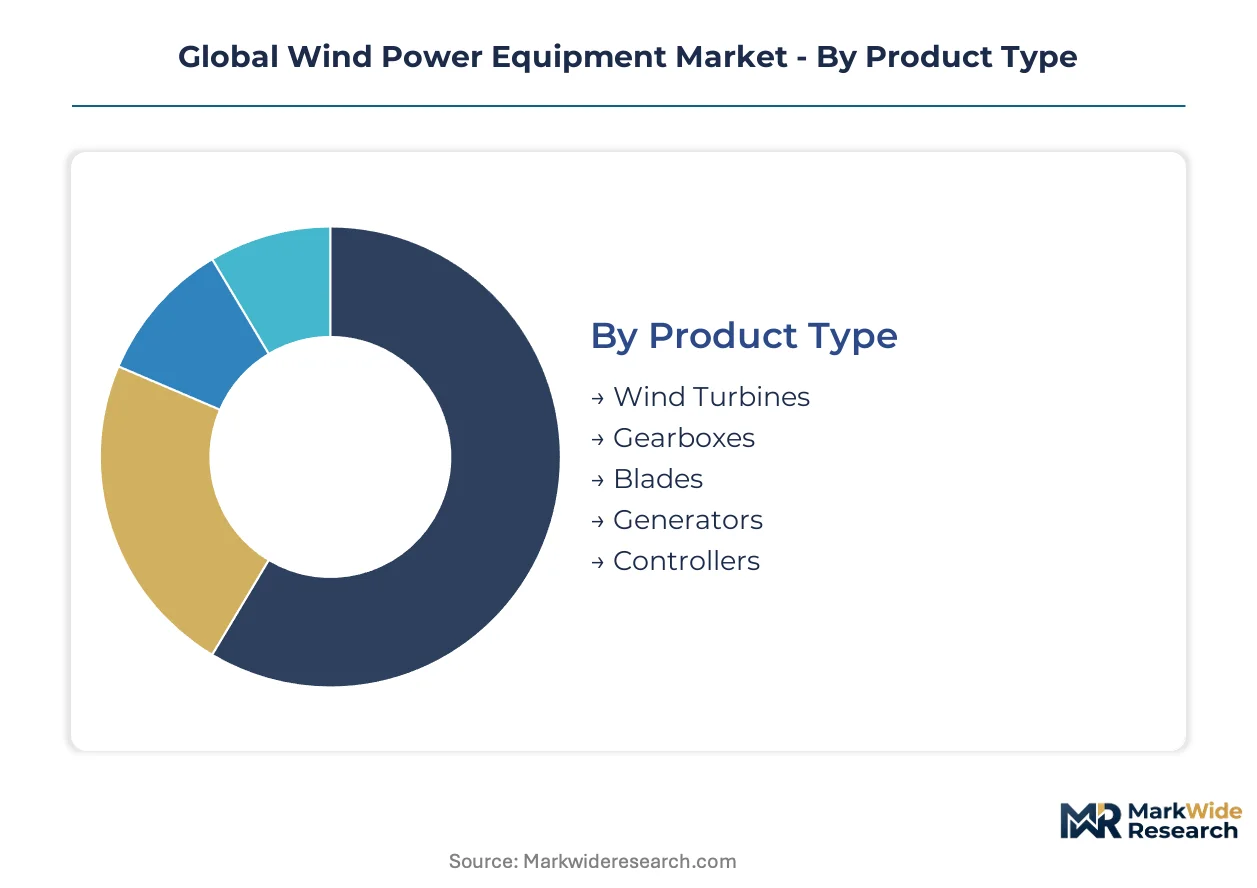
Equipment segmentation in wind power reveals divergent replacement cycles across mechanical and electrical subsystems. Turbine repowering decisions cascade through component procurement, with blade and drivetrain upgrades outpacing full nacelle replacements in mature markets.
Product Type:
Upgrade cycles vary sharply by subsystem, with rotating components requiring earlier intervention than static infrastructure.
- Wind Turbines:Complete nacelle assemblies integrate rotor, drivetrain, and power conversion in single-source procurement. Offshore developers in Germany and Taiwan are specifying 15MW-plus units with integrated condition monitoring, compressing installation vessel demand.
- Gearboxes:Geared drivetrains dominate existing onshore fleets in the United States and India, where sunk maintenance infrastructure slows direct-drive conversion. Repowering economics favor gearbox rebuilds over full architecture swaps below 2MW nameplate capacity.
- Blades:Thermoset composite construction faces end-of-life processing constraints under extended producer responsibility rules in Germany and the Netherlands.
- Generators:Permanent magnet synchronous designs concentrate neodymium supply risk in Chinese processing corridors.
- Controllers:Pitch and power electronics integrate grid-forming capabilities for weak-network connections in remote Australian and Brazilian installations.
Wind turbines sit at the top of the volume ranking, with blades climbing the fastest amid repowering mandates and recycling liability exposure.
Technology:
Technology choice locks in decades-long maintenance economics, with offshore salt exposure accelerating architecture transitions.
- Direct Drive:Elimination of gearbox components reduces mechanical failure points in marine environments. Goldwind and Siemens Gamesa dominate offshore procurement with permanent magnet generators, though rare earth processing concentration in China creates supply vulnerability.
- Variable Speed:Power electronics enable maximum power point tracking across fluctuating wind regimes. Full-converter architectures qualify for grid codes in Germany and Denmark requiring fault-ride-through capability.
- Fixed Speed:Simplified induction generator designs persist in small-scale Indian and Brazilian installations where capital constraints outweigh efficiency losses.
- Doubly-Fed Induction Generator:Partial-scale converters balance cost and control flexibility in onshore repowering projects.
- Synchronous Generator:Grid-forming variants enable black-start capability for islanded microgrids in remote Canadian and Australian deployments.
Direct drive technology commands premium positioning in offshore procurement, while variable speed systems gain share fastest in grid-code tightening markets.
Application:
Application segmentation tracks divergent customer risk profiles, from merchant exposure to regulated offtake.
- Utility Scale:Centralized procurement by state-backed developers in China and independent power producers in the United States drives volume concentration. Projects exceed 100MW nameplate capacity with dedicated substations and transmission buildout.
- Offshore Wind Farms:Higher capacity factors and seabed leasing scarcity in the North Sea and Taiwan Strait justify capital intensity. Installation vessel bottlenecks compress project timelines for German and United States lease rounds.
- Distributed Generation:Behind-the-meter installations serve industrial load centers in India and Brazil with avoided transmission charges.
- Remote Power Supply:Diesel displacement drives demand for hybrid wind-battery systems in Canadian Arctic and Australian mining camps.
Utility scale deployment anchors absolute capacity additions, with offshore wind farms expanding most quickly on seabed auction acceleration.
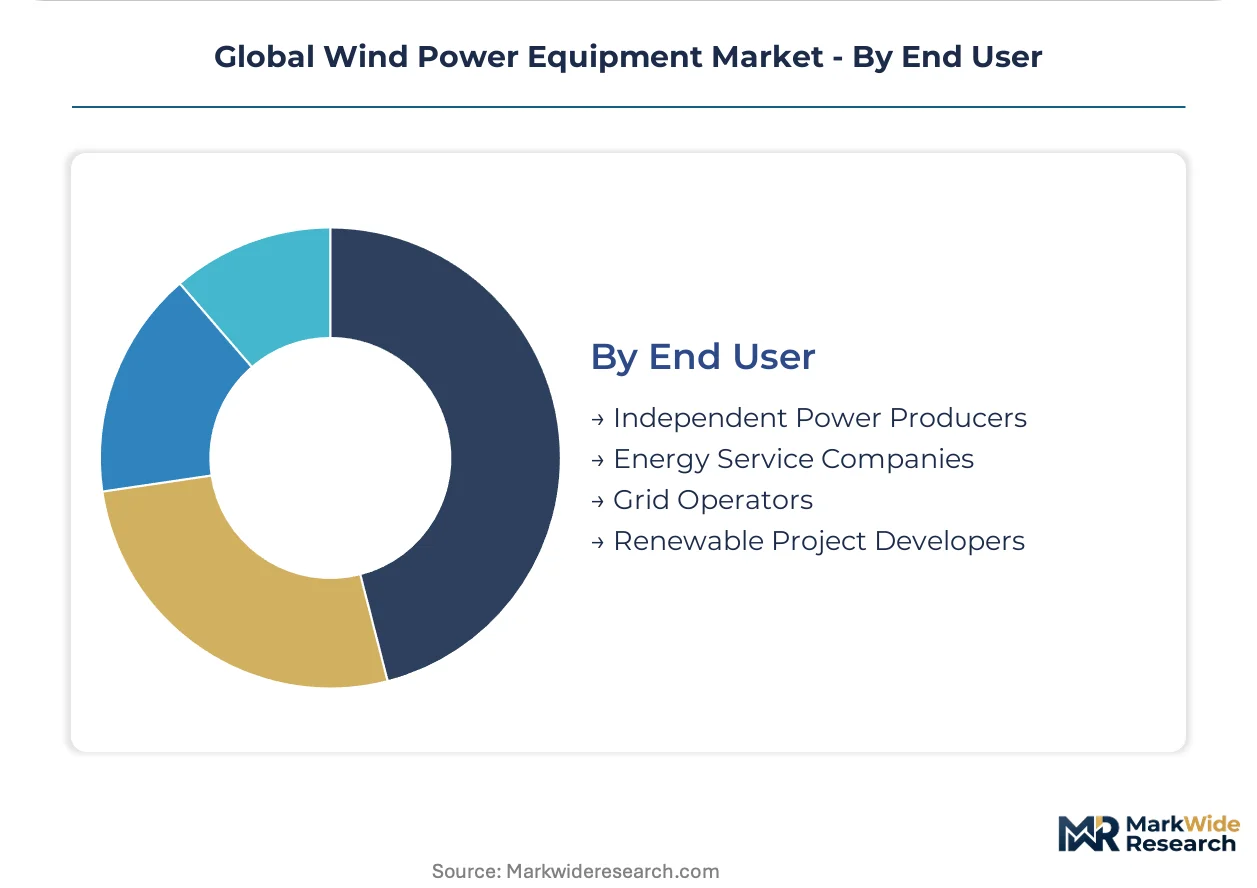
End User:
End-user structure determines procurement sophistication, from standardized equipment tenders to integrated service contracts.
- Independent Power Producers:Merchant risk exposure drives equipment selection toward highest capacity factor configurations. IPPs in the United States and Spain negotiate turbine availability guarantees separate from capital contracts.
- Renewable Project Developers:Greenfield specialists bundle development rights with equipment procurement in China's state-backed auction system and India's wind-solar hybrid mandates.
- Grid Operators:Transmission utilities in Germany and Denmark specify grid-forming capabilities and synthetic inertia provision in connection agreements.
- Energy Service Companies:Performance contracting models shift operational risk to equipment suppliers in Brazilian and Mexican distributed generation markets.
Independent power producers dominate procurement volume, with renewable project developers gaining share fastest on auction pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling turbine manufacturing capacity toward jurisdictions with streamlined certification pathways and domestic content incentives. Cost-of-compliance gaps between the EU F-Gas phasedown and China's GB standards are accelerating localization decisions for converter and cooling subsystem suppliers.
China
State-backed developers under the dual carbon goals are consolidating procurement around 15MW-plus offshore units. GB standards enforce local blade and tower sourcing thresholds, tightening supplier qualification. The Yangtze River Delta cluster hosts nacelle assembly lines scaling for Taiwan Strait lease rounds.
Germany
North Sea seabed auctions with grid connection guarantees are compressing installation vessel demand for 220-meter rotor systems. The EU F-Gas Regulation limits converter cooling options, extending type certification cycles. The Port of Cuxhaven anchors blade logistics for hybrid concrete-steel tower deployments.
United States
Atlantic Coast lease rounds are accelerating procurement of direct-drive architectures despite rare earth supply exposure. The FAA coordinates with the Coast Guard on turbine airspace lighting requirements. The Gulf Coast fabrication corridor is scaling jacket foundation production for floating platform pilots.
India
Sub-2MW repowering mandates trigger accelerated depreciation for control system and blade retrofits. CEA grid codes are tightening fault-ride-through requirements for variable speed systems. The Gujarat coastline concentrates turbine assembly for wind-solar hybrid auction pipelines.
Denmark
Electrolyzer-ready grid connections at offshore zones are bundling turbine-to-hydrogen equipment procurement. National regulators mandate synthetic inertia provision in connection agreements. The Port of Esbjerg hosts installation vessel marshalling for North German lease support.
Global Wind Power Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators capturing premium positioning in offshore procurement while component fabricators serve repowering retrofit demand. The vendor base concentrates around three strategic archetypes: state-backed champions with captive supply chains, European incumbents with multi-decade service platforms, and emerging Asian specialists scaling for export qualification. Dominant competitive moves include backward integration into generator and blade production, plus geographic licensing partnerships to satisfy local content rules.
Among the state-backed tier, Mingyang Smart Energy and Goldwind occupy positions shaped by domestic auction consolidation and vertical control over rare earth magnet supply. Siemens Gamesa Renewable Energy exemplifies the European incumbent archetype, anchoring multi-decade service contract penetration in North Sea offshore zones. Vestas represents the scale-driven specialist model, with blade manufacturing footprint and digital fleet optimization platforms shaping competitive differentiation in mature European and American markets.
| Leading Market Players |
|---|
| Mingyang Smart Energy |
| Siemens Gamesa Renewable Energy |
| Goldwind |
| GE Renewable Energy |
| Suzlon Energy |
| Envision Energy |
| Vestas |
| Nordex SE |
| Windey |
| Others |
Supply & Pricing Matrix
Captive generator production by Goldwind and Mingyang anchors pricing power through upstream control over rare earth magnet supply, while European turbine OEMs absorb cost premiums from F-Gas Regulation compliance and segmented blade logistics.
Pricing Analysis
Direct-to-IPP contract structures compress distributor margins in utility-scale procurement, with availability-guarantee bundling separating premium service-integrated vendors from standard equipment-only tiers. Price differentiation hinges on IEC 61400 certification tier and captive blade manufacturing scale. Cost compression in onshore repowering intensifies as Indian developers exploit accelerated depreciation for sub-2MW retrofits. Merchant IPPs in Spain and the United States exhibit highest price sensitivity; offshore developers in Germany and Taiwan prioritize availability performance over capital cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing corridors, where export quota volatility exposes direct-drive manufacturers to forced technology transfer requirements. Component sourcing concentrates in China, Germany, and Denmark for nacelle assembly, with thermoset resin feedstocks and medium-voltage IGBT modules as critical dependencies. Tariff exposure on steel tower sections threatens cost structures for US Gulf Coast fabrication. Distribution runs through state-backed developers in China, independent power producers in the United States, and EPC-led procurement in European offshore zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance software penetration and green hydrogen co-location bundling, where electrolyzer-ready grid connections in Denmark and the Netherlands justify premium equipment positioning.
For Market Incumbents: Acquire predictive maintenance algorithm platforms to capture uncontracted aftermarket revenue in aging European and Chinese fleets. Siemens Gamesa and Vestas must defend against Goldwind's rare earth supply chain control by securing alternative magnet sourcing from Australian or Vietnamese processing corridors. Certification investment in IEC 61400-1 Edition 4 compliance anchors premium positioning as grid codes tighten fault-ride-through requirements. For New Entrants and Emerging Players: Begin with India's sub-2MW repowering mandate, where accelerated depreciation triggers control system and blade retrofit demand without full nacelle replacement competition. Target distributed generation in Brazilian industrial load centers, where avoided transmission charges justify behind-the-meter procurement. Specialist aftermarket service platforms offer the most penetrable entry angle against incumbent multi-decade contracts. For Investors and Strategic Acquirers: Roll-up economics work for digital fleet optimization specialists because fragmented European and Chinese aging fleets lack integrated predictive maintenance coverage. Long-term viability centers on software-enabled service revenue streams decoupled from hardware shipment cycles. Watch for F-Gas Regulation quota reductions compressing commissioning windows as the inflection signal for cooling subsystem acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Generator Production | Goldwind's captive rare earth supply insulates against Chinese export quota volatility. |
| Predictive Maintenance Platform Acquisition | Vestas leverages digital fleet optimization to secure uncontracted European aftermarket revenue. |
| Electrolyzer-Ready Grid Connection Certification | Danish developers bundle turbine-to-hydrogen procurement at North Sea offshore zones. |
| Hybrid Concrete-Steel Tower Manufacturing Scale-Up | German and American Midwest projects access higher shear wind profiles above 160 meters. |
| Blade Recycling Infrastructure Partnership | Extended producer responsibility rules in Germany and Netherlands demand thermoset resin processing capacity. |
Research Methodology
Bottom-up IPP procurement modeling reconciled against top-down turbine shipment tracking forms the analytical core. Primary interviews with utility planning officers, offshore project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Triangulation across bottom-up installation capacity builds and top-down manufacturer revenue segmentation ensures statistical integrity.
Input-output matrices map turbine component demand through drivetrain architecture, rotor diameter class, and grid connection voltage tier across the projection horizon. Segmentation dimensions span product type, technology choice, application scale, and end-user procurement sophistication. CAGRs derive from logistic diffusion curves fitted to seabed lease auction pipelines and repowering replacement cycles. Forecast inputs include installation vessel availability constraints and rare earth magnet supply quota trajectories.
Caveats apply where F-Gas Regulation phasedown acceleration or Chinese dual carbon goal enforcement could materially shift the outlook. Forecasts reflect assumptions on grid code harmonization timelines and electrolyzer co-location mandate adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market