
 West Africa Cement Market | 2026-2036
West Africa Cement Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Cement Market Intelligence
Market Context with Strategic Players
Direct-to-builder distribution is narrowing as bulk procurement contracts capture larger project volumes across the region. Dangote Cement leverages its integrated clinker kilns in Obajana and Ibese to sustain price leadership in Nigerian markets. HeidelbergCement anchors supply networks in Ghana and Togo through coastal grinding terminals. BUA Cement competes aggressively in northern Nigeria with newer production assets and expanded rail logistics.
Technical Definition and Structural Segments
West Africa cement comprises hydraulic binding powders manufactured from limestone, clay, and gypsum calcination, typically achieving compressive strengths of 32.5 to 52.5 MPa under regional standards adapted from EN 197-1. Its primary commercial purpose lies in producing concrete for structural load-bearing elements, masonry mortars, and stabilization layers in road bases across tropical climates with high humidity and saline exposure. Blended cement occupies the dominant volume position due to lower clinker ratios and compliance with emerging carbon intensity benchmarks. Infrastructure projects represent the fastest-expanding end user segment, driven by multilateral development bank financing for transnational highway corridors and port modernization.
Regulatory Framework and Forward Outlook
Nigeria's Standards Organisation of Nigeria enforces cement quality grades through mandatory NIS 444 certification, while Ghana's Ghana Standards Authority regulates limestone content and bag labeling under GS 1118. The Economic Community of West African States Trade Liberalization Scheme shapes cross-border tariff structures, creating uneven market access between member states with diverging local content enforcement. Stakeholders must monitor how ECOWAS harmonization protocols and national clinker import restrictions reshape competitive boundaries across coastal and Sahelian markets.
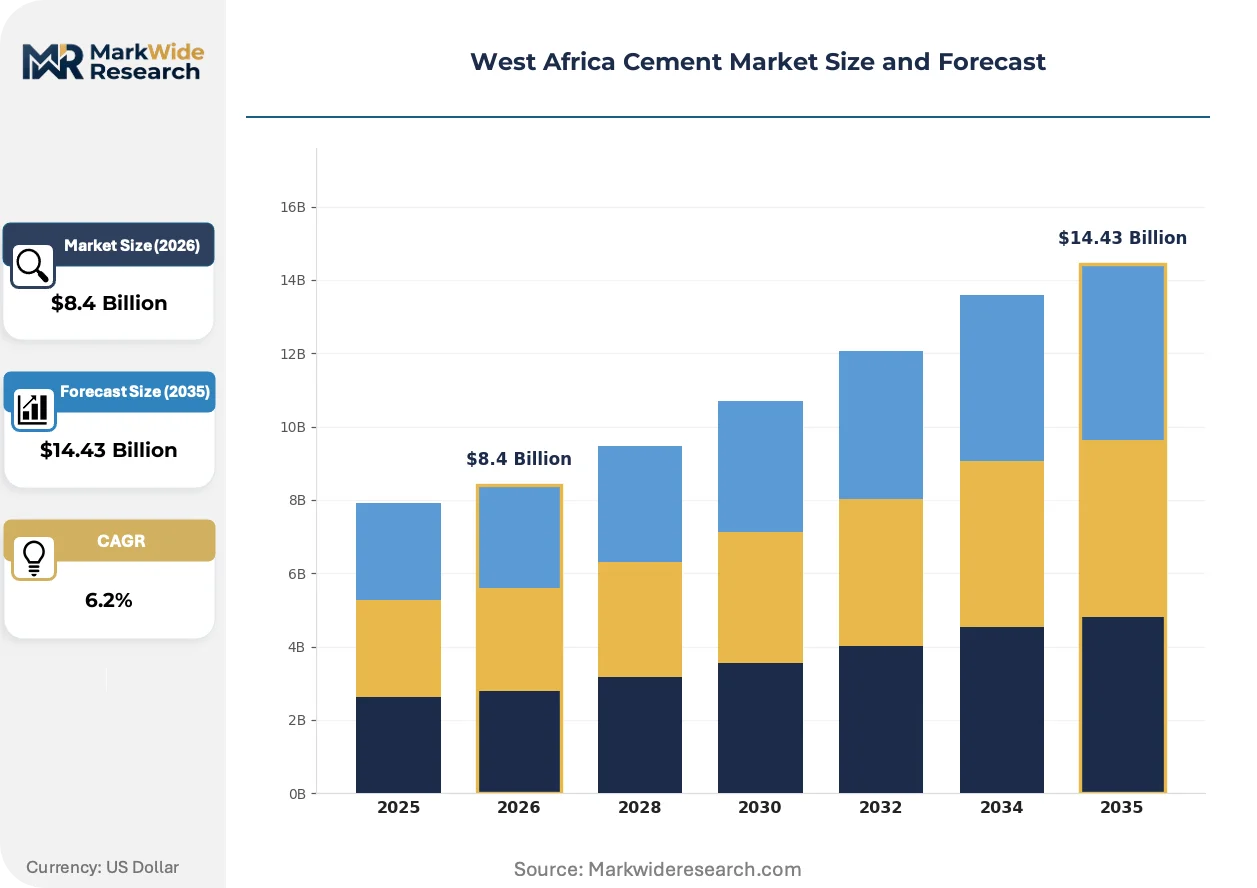
Market Dynamics
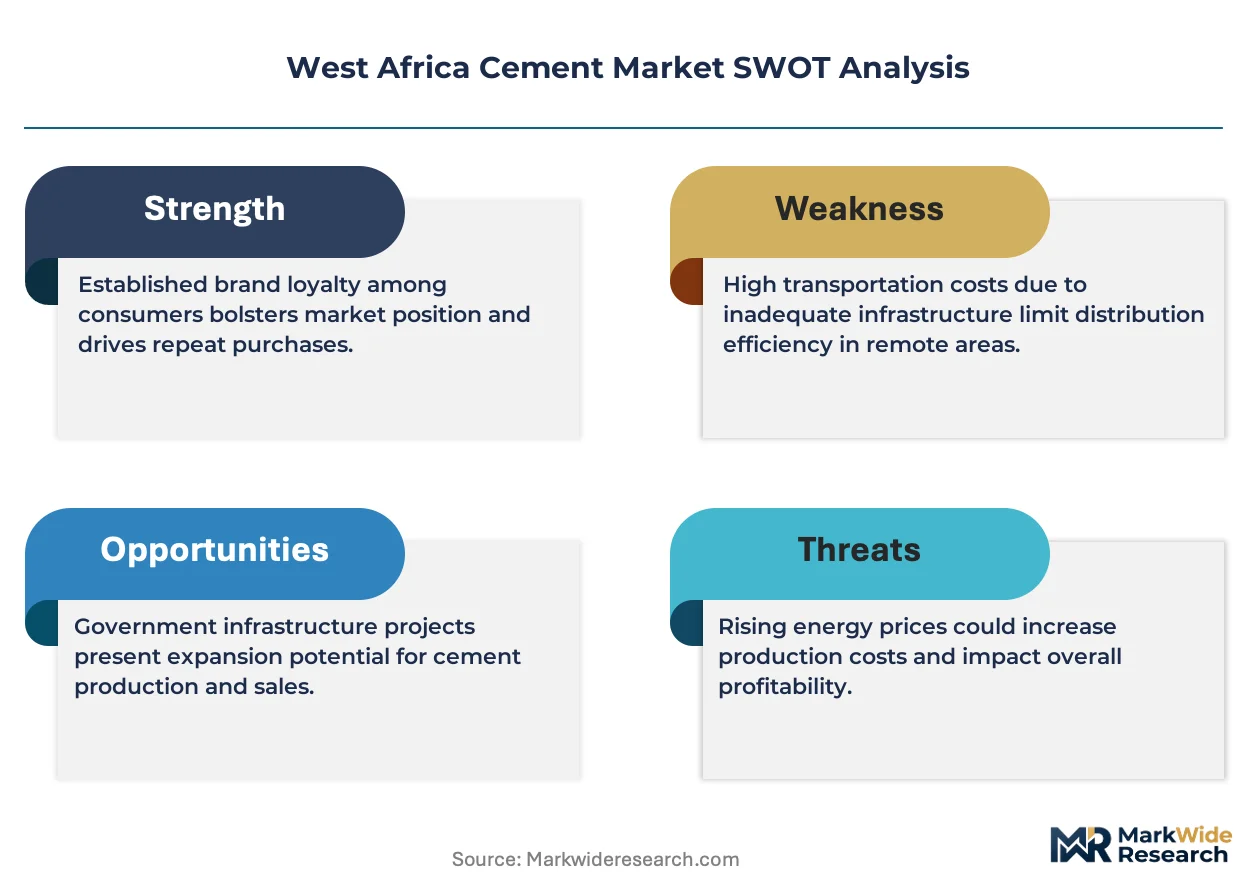
Clinker import restrictions under Nigeria's local content mandates are forcing producers to reconfigure supply architectures around domestic kiln capacity, tightening feedstock security while elevating capital requirements for new entrants.
Growth Catalysts
- ECOWAS Trade Liberalization Scheme:Cross-border tariff harmonization is unlocking volume flows between member states, enabling producers to arbitrage coastal grinding capacity against inland demand clusters.
- Transnational highway corridors:Multilateral development bank financing for the Abidjan-Lagos corridor and Dakar-Bamako axis is absorbing bulk cement volumes for concrete pavement and bridge substructures.
- Limestone calcination with alternative fuels:Biomass co-firing in rotary kilns is reducing carbon intensity while satisfying emerging green procurement criteria from infrastructure tender boards.
Market Restraints
- Diesel price volatility:Haulage costs consume substantial delivered cement pricing, with fleet operators exposed to pump price spikes that compress distributor margins.
- Clinker supply concentration:Integrated producers with captive limestone quarries control critical upstream inputs, limiting grinding-only competitors to import-dependent feedstock strategies.
- Blended cement performance ceiling:Extended setting times and lower early strength in high-slag formulations restrict adoption for precast and fast-track construction schedules.
Strategic Opportunities
- Sahelian belt urbanization:Secondary cities in Burkina Faso and Niger present underpenetrated demand nodes where bagged cement distribution networks remain underdeveloped relative to coastal markets.
- Rail-served inland terminals:New narrow-gauge freight connections between Lagos and northern Nigeria are enabling bulk-to-bag conversion facilities that bypass road congestion.
- Carbon border adjustment readiness:Producers investing in kiln electrification and CCS retrofits will capture preferential offtake from ECOWAS infrastructure projects with embedded emissions criteria.
Industry Challenges
- Kiln process engineering expertise:Shortages of pyrometallurgy specialists and refractory maintenance crews delay commissioning timelines for new production lines.
- NIS 444 certification bottlenecks:Standards Organisation of Nigeria testing backlogs extend product approval cycles, freezing inventory release for export-bound volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Cement Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland, Blended Cement, Rapid Hardening, White Cement End User: Residential Construction, Commercial Construction, Industrial Facilities, Infrastructure Projects Distribution Channel: Direct Sales, Wholesale Distributors, Retail Outlets, Online Platforms Application: Building, Road Construction, Bridges, Precast Concrete |
| Companies Covered | HeidelbergCement, Vicat, Dangote Cement, CIMFASO, Cimenterie du Benin, BUA Cement, WACEM, Société des Ciments d’Onigbolo, Lafarge Africa, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Cement Market Strategic Shifts & Innovations
Digital logistics platforms and alternative fuel substitution are compressing cost structures while regulatory pressure on embodied carbon is reshaping product formulation strategies across the value chain.
Calcined clay activation is hybridizing traditional clinker chemistry with pozzolanic reactivity, enabling 50% clinker factor reductions without sacrificing 28-day compressive performance. Infrastructure contractors in Ghana and Côte d'Ivoire are specifying LC3 blends for marine exposure applications. This formulation shift is compressing demand for imported clinker while elevating kaolin quarry development in Guinea and Senegal.
Nigeria's Ministry of Mines and Steel Development is tightening limestone mining lease compliance, mandating environmental impact assessments and community development agreements for new quarry permits. This regulatory friction is extending greenfield project timelines by 18-24 months. Integrated producers with grandfathered extraction rights are consolidating buffer reserves while challengers face elevated jurisdictional risk in the Niger Delta and Ogun State belts.
Bulk procurement contracts are displacing traditional bagged distribution for large infrastructure consortia, with project developers negotiating direct-offtake agreements that bypass regional distributors. This channel compression is most visible in the Lagos-Ibadan corridor, where cement terminals now dedicate dedicated silo capacity to single-project customers rather than maintaining fungible merchant inventories.
West Africa Cement Market Segmentation
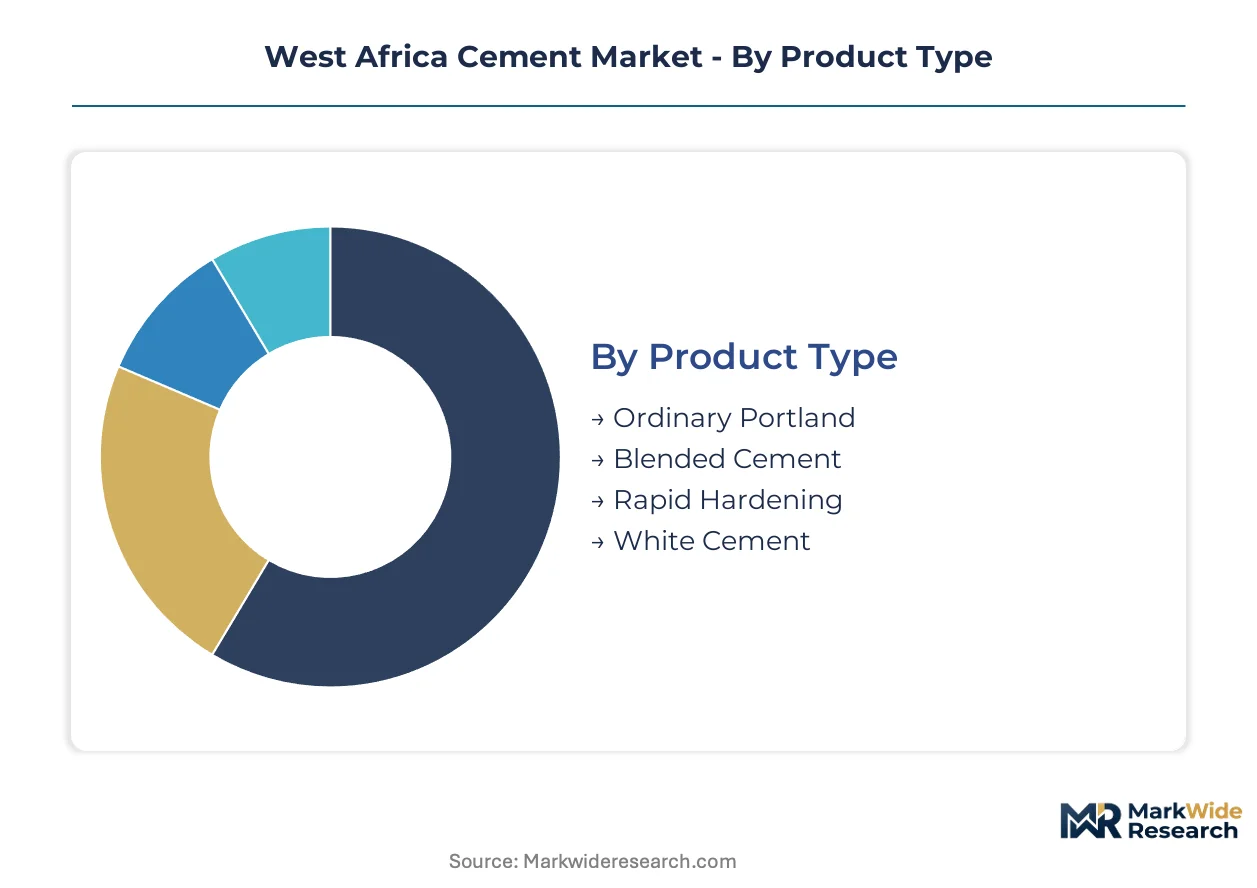
West Africa cement producers configure product portfolios and channel strategies around divergent construction cycles, from rapid-hardening formulations for precast yards to bulk logistics for highway consortia. Segmentation discipline determines working capital intensity and margin capture across bagged retail and project-direct volumes.
Product Type:
After-sales service intensity varies sharply across cement chemistries, with blended formulations demanding technical support for mix design optimization while commodity-grade products require minimal post-sale engagement.
- Blended Cement:Combines clinker with pozzolanic extenders such as fly ash or calcined clay, achieving 32.5-42.5 MPa strengths under NIS 444 standards. Demand concentrates in Ghana's coastal infrastructure belt, where marine exposure specifications and carbon procurement criteria from multilateral lenders accelerate specification shifts away from pure Portland.
- Ordinary Portland:Maintains 100% clinker basis with rapid early strength development, serving precast manufacturers and fast-track commercial slabs in Lagos-Ibadan corridor projects. Nigerian contractors specify OPC for structural elements requiring 28-day formwork stripping cycles.
- Rapid Hardening:High C3S clinker chemistry delivers 3-day strengths exceeding standard 28-day benchmarks; precast yards in Abidjan and Lomé specify for accelerated mold turnover.
- White Cement:Low-iron raw meal selection produces decorative architectural finishes; limited kilns in Senegal and Côte d'Ivoire serve premium retail channels.
By volume, Blended Cement leads. By growth pace, Rapid Hardening is ahead.
End User:
Margin profiles diverge across customer categories, with infrastructure consortia extracting volume discounts that compress returns while residential builders accept bagged premiums for distribution convenience.
- Infrastructure Projects:Multilateral development bank financing for ECOWAS highway corridors and port modernization absorbs bulk cement volumes under direct-offtake contracts. Concrete pavement specifications in the Abidjan-Lagos axis require 52.5 MPa formulations with extended slump retention.
- Residential Construction:Individual homebuilders and small contractors drive bagged cement consumption through retail distributors across Nigeria's northern cities and Burkina Faso's secondary towns. Urbanization in Niger's Niamey corridor sustains 32.5 grade demand for masonry and plastering applications.
- Commercial Construction:Office and retail developments in Accra and Dakar specify 42.5 MPa concrete for high-rise structural frames.
- Industrial Facilities:Manufacturing plant foundations and warehouse slabs in Togo's Lomé port zone require sulfate-resistant formulations.
Infrastructure Projects command the largest single-project volumes. Residential Construction shows the steepest expansion trajectory across unit transaction counts.
Distribution Channel:
Channel selection determines inventory risk allocation, with direct sales transferring storage obligations to project developers while wholesale networks absorb seasonal demand fluctuations.
- Direct Sales:Bulk procurement contracts between producers and infrastructure consortia bypass distributor markups, dedicating silo capacity to single-project customers in Nigeria's Lagos-Ibadan corridor.
- Wholesale Distributors:Regional aggregators consolidate bagged volumes for redistribution to smaller contractors across Ghana's Ashanti region and northern Nigeria.
- Retail Outlets:Corner stores and building material markets serve individual homeowners with 50kg bag purchases in Burkina Faso and Niger's underpenetrated Sahelian markets.
- Online Platforms:Emerging digital procurement channels in Lagos and Accra aggregate contractor demand for scheduled delivery coordination.
Direct Sales capture the highest revenue per ton. Online Platforms are climbing the fastest as logistics digitization spreads.
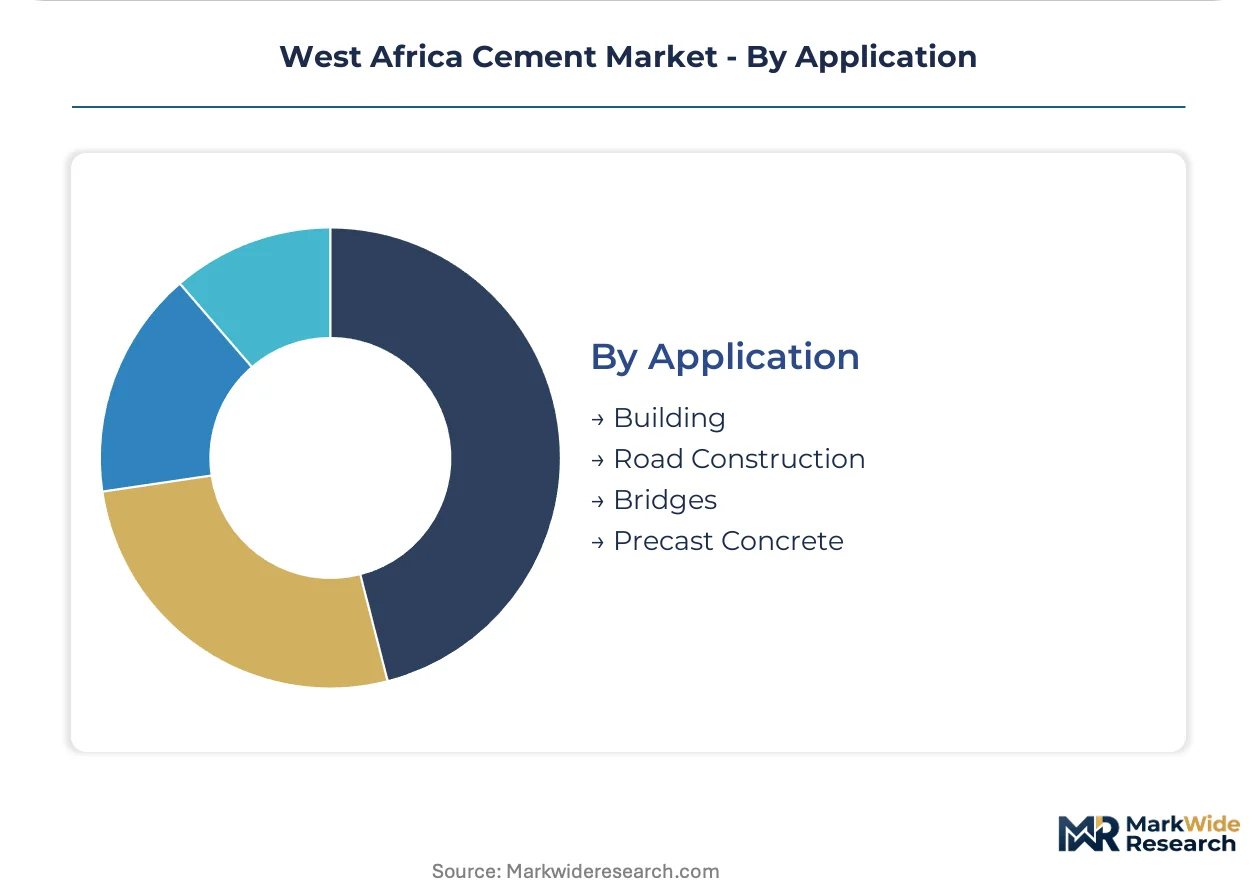
Application:
Application-specific formulations require tailored technical support, with road base stabilization demanding different binder chemistry than precast structural elements.
- Road Construction:Soil-cement stabilization and concrete pavement layers for ECOWAS transnational highways consume bulk volumes across Côte d'Ivoire's Abidjan-Treichville axis and Ghana's Tema motorway extensions.
- Building:Structural frames, masonry mortars, and plastering applications in Nigeria's residential and commercial verticals absorb blended and ordinary Portland grades.
- Bridges:Marine exposure specifications for lagoon crossings in Lagos and coastal Ghana require sulfate-resistant formulations with extended durability warranties.
- Precast Concrete:Factory-cast beams, pipes, and drainage channels in Togo and Benin demand rapid-hardening chemistry for accelerated curing cycles.
Building dominates absolute tonnage. Road Construction is gaining share fastest from multilateral infrastructure financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Abidjan-Lagos Corridor underwrites West Africa's cement demand gravity, with multilateral development bank financing for highway concrete pavement and bridge substructures absorbing bulk volumes across coastal states. This transnational infrastructure asset anchors regional trade flows and construction material procurement patterns.
Nigeria
Federal highway rehabilitation and Lagos-Ibadan industrial zone expansion drive Nigerian cement consumption. The Standards Organisation of Nigeria enforces NIS 444 certification for quality grades, tightening compliance timelines for new product releases. Obajana and Ibese host integrated clinker kilns that supply the southwestern corridor's structural concrete demand.
Ghana
Tema port modernization and Accra commercial high-rise construction absorb blended and ordinary Portland grades. Ghana Standards Authority regulates limestone content and bag labeling under GS 1118, mandating disclosure of pozzolanic extender ratios. The Tema motorway extension corridor concentrates bulk procurement contracts for infrastructure consortia.
Côte d'Ivoire
Abidjan-Treichville axis road construction and lagoon bridge projects specify marine exposure formulations. The country's national standards body adapts EN 197-1 benchmarks for tropical humidity and saline exposure conditions. Precast yards in Abidjan and Lomé specify rapid-hardening chemistry for accelerated mold turnover cycles.
Senegal
Dakar-Bamako highway axis development and coastal urbanization sustain bagged and bulk cement flows. Environmental impact assessment mandates for limestone mining leases extend greenfield project timelines. Kaolin quarry development in the Senegal-Guinea border region feeds calcined clay activation for LC3 blend production.
Burkina Faso
Niamey corridor urbanization and secondary city construction drive 32.5 grade demand for masonry applications. ECOWAS Trade Liberalization Scheme tariff structures create uneven market access relative to coastal member states. Ouagadougou's underpenetrated distribution networks present expansion opportunities for bagged cement retail channels.
West Africa Cement Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with captive feedstock or grinding-only configurations. West Africa's cement sector consolidates around integrated producers with limestone quarry control and coastal grinding terminal operators serving import-dependent markets. Three archetypes dominate: kiln-integrated multinationals with regional quarry networks, domestic champions with federal supply contracts, and coastal grinders arbitraging clinker imports against inland demand. Competitive moves concentrate on rail-served inland terminal development and alternative fuel kiln retrofits for carbon intensity compliance.
Among Nigeria-based integrated producers, Dangote Cement and BUA Cement exemplify the domestic champion archetype with federal infrastructure contract positioning. HeidelbergCement anchors the multinational platform tier with coastal grinding networks. These three names represent the competitive core around which regional supply architectures reconfigure under local content mandates and clinker import restrictions.
| Leading Market Players |
|---|
| HeidelbergCement |
| Vicat |
| Dangote Cement |
| CIMFASO |
| Cimenterie du Benin |
| BUA Cement |
| WACEM |
| Société des Ciments d'Onigbolo |
| Lafarge Africa |
| Others |
Cost & Logistics Intelligence
Obajana's integrated clinker kilns anchor Nigerian supply capacity, concentrating upstream control among producers with captive limestone reserves and compressing margin capture for import-dependent grinding-only competitors across the Lagos-Ibadan corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs West Africa cement transactions. Price differentiation rests on volume scale and certification grade under NIS 444 standards, with bulk infrastructure offtake commanding steepest discounts. Cost compression in bagged retail channels is intensifying because diesel haulage volatility erodes distributor margins. Residential builders in northern Nigeria exhibit highest price sensitivity, while multilateral-financed highway consortia leverage procurement scale for preferential terms.
Supply Chain Analysis
Tariff exposure between Nigeria and Benin Republic dominates cross-border supply risk under uneven ECOWAS local content enforcement. Geographic supply concentrates in Nigeria, Ghana, and Senegal, with integrated kilns in Ogun State and grinding terminals in Tema feeding regional flows. Raw material dependencies center on limestone, gypsum, and pozzolanic extenders from kaolin quarries in Guinea. Distribution runs through bulk-to-bag inland terminals and project-direct silo arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
West Africa cement sits in early-cycle expansion as ECOWAS infrastructure financing accelerates specification shifts toward lower-carbon blended formulations and bulk procurement channels.
For Market Incumbents: Build captive limestone reserve moats by securing grandfathered mining leases before Nigeria's Ministry of Mines tightens environmental compliance timelines. Expand rail-served inland terminal capacity to bypass road congestion and defend against grinding-only entrants arbitraging coastal clinker imports. Prioritize alternative fuel kiln retrofits to capture green procurement criteria from multilateral development bank tenders.
For New Entrants and Emerging Players: Secondary cities in Burkina Faso and Niger's Sahelian belt represent the most penetrable entry point, with underdeveloped bagged distribution networks and minimal integrated producer presence. Target precast concrete yards in Lomé and Cotonou demanding rapid-hardening formulations with accelerated curing specifications. Establish wholesale distributor partnerships rather than competing for bulk infrastructure contracts where incumbents hold federal supply relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a resource-anchored infrastructure play because limestone quarry control and ECOWAS trade corridor positioning compound competitive durability. Acquisition targets should display integrated kiln assets with grandfathered extraction rights in Nigeria's Ogun State or coastal grinding terminals with rail connectivity. Monitor clinker import restriction enforcement intensity as the signal for margin compression among non-integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Kiln Retrofit | Biomass co-firing reduces carbon intensity for NIS 444-compliant green procurement tenders. |
| Rail-Served Inland Terminal Development | Bulk-to-bag conversion facilities bypass Lagos-Ibadan road congestion and diesel price volatility. |
| Calcined Clay Activation Investment | LC3 blend production compresses clinker import dependence while satisfying marine exposure specifications. |
| Limestone Reserve Consolidation | Grandfathered mining leases in Niger Delta and Ogun State belts extend greenfield project timelines for challengers. |
| Direct-Offtake Contract Structuring | Infrastructure consortia bypass distributor markups, dedicating silo capacity to single-project customers. |
Research Approach
Operator-level perspectives from plant managers, procurement leads at downstream construction consortia, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, SEC filings of listed producers, and Standards Organisation of Nigeria certification records. Bottom-up volume modeling and top-down macroeconomic triangulation ensured cross-verification of demand estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product chemistry, end-user category, distribution channel, and application type. CAGRs derived from historical trajectory analysis and forward-looking capacity commissioning schedules. Industry-specific inputs included kiln utilization rates, alternative fuel substitution ratios, and ECOWAS cross-border tariff implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in diesel pricing, multilateral development bank lending volumes, or Nigerian local content enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory, technological, or feedstock security developments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Earthen Plasters Market
Building Materials
Shotcrete Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Glass Facade Market
Building Materials
Block Paving Market
Building Materials
Blended Cement Market
Building Materials
Concrete Admixtures Market
Building Materials
North America Architectural Coatings Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Global White Cement Market
Building Materials
Granite Market
Building Materials
South Africa White Cement Market
Building Materials
Sanded Grout Market