
 Rapid Strength Concrete Market | 2026-2036
Rapid Strength Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Strength Concrete Market Analysis
Infrastructure project timelines are compressing globally, and the contractor base is pivoting toward mixes that achieve structural load-bearing capacity within hours rather than days. BASF SE leverages its admixture chemistry portfolio to dominate high-performance formulations for airport runway repairs. Heidelberg Materials anchors European supply through its integrated cement-admixture distribution network. Sika AG specializes in shrinkage-compensated systems that reduce post-placement cracking risk in cold-weather pours.
Rapid strength concrete achieves compressive strengths exceeding 20 MPa within 24 hours through accelerated cement hydration, often employing calcium aluminate cements or alkali-activated supplementary cementitious materials. Its primary purpose is minimizing downtime in transportation infrastructure, industrial floor slabs, and precast yard operations where schedule compression carries penalty cost exposure. Ready-mix delivery captures the largest volume share as batch-plant quality control ensures consistent early-strength performance, while precast applications represent the fastest-growing segment due to factory-controlled curing environments that optimize high-early-strength admixture dosing. Self-consolidating rapid strength variants command premium positioning where congested reinforcement or complex form geometries eliminate mechanical compaction.
ASTM C928 governs shrinkage-compensating concrete specifications in the United States, while EN 206 in Europe defines strength class requirements and durability exposure categories that rapid strength formulations must satisfy for structural acceptance. The EPA's National Emission Standards for Hazardous Air Pollutants from Portland cement manufacturing indirectly shapes admixture innovation by pressuring clinker factor reduction in high-early-strength blends. Stakeholders must monitor evolving lifecycle assessment methodologies, as carbon intensity metrics for accelerated curing processes increasingly influence public procurement scoring and private ESG commitments.
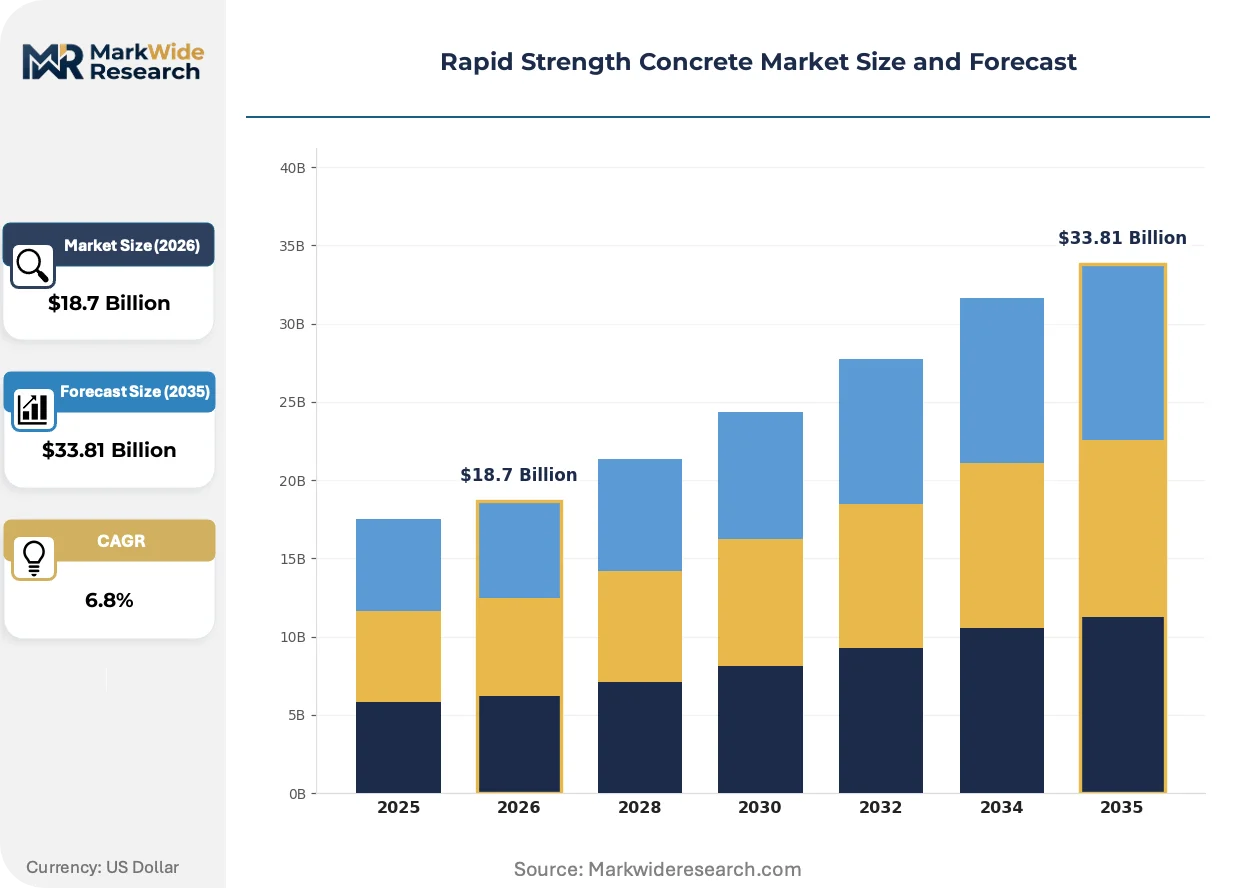
Market Dynamics
Schedule compression in transportation infrastructure is forcing contractors to accept accelerated curing specifications that trade material cost premiums against liquidated damages exposure from lane closure overruns.
Growth Catalysts
- Highway rehabilitation mandates:North American state DOTs are embedding 24-hour opening-strength requirements into bridge deck replacement contracts, eliminating conventional concrete from bidding eligibility.
- EN 206 durability exposure categories:European structural acceptance standards for carbonation resistance and chloride ingress are tightening, pushing asset owners toward certified rapid strength formulations with documented performance envelopes.
- Calcium aluminate cement chemistry:Advances in CA cement blending ratios are extending placement windows while preserving early strength development, expanding viable ambient temperature ranges for field pours.
Market Restraints
- Specialty cement supply concentration:European calcium aluminate production clusters in France and Germany, creating freight cost penalties for contractors in peripheral markets.
- Alkali-silica reaction susceptibility:High-early-strength blends with elevated alkali content face restricted use in aggregates with reactive silica, limiting application in certain geologies.
- Portland cement clinker factor floor:EPA National Emission Standards for Hazardous Air Pollutants impose compliance costs that compress margins on high-volume rapid strength formulations.
Strategic Opportunities
- Airfield pavement maintenance:FAA specifications for rapid runway repair materials are tightening turnaround windows, creating specification-driven demand for ultra-high-early-strength systems.
- Carbon capture curing integration:CO2 injection during accelerated hydration is consolidating with rapid strength chemistry to produce carbon-negative concrete with commercial-grade early performance.
- Modular precast yard automation:Factory-controlled curing environments enable precise admixture dosing that field conditions cannot replicate, shifting volume toward captive precast production.
Industry Challenges
- Thermal cracking control:Managing heat-of-hydration peaks in mass placements requires real-time temperature monitoring capabilities that many ready-mix operations lack.
- CSA cement handling protocols:Calcium sulfoaluminate cements demand strict moisture exclusion during storage and transport, complicating supply chain configuration for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Strength Concrete Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast, Ready-Mix, High-Performance, Self-Consolidating Application: Infrastructure, Residential, Commercial, Industrial Delivery Mode: On-Site, Off-Site, Centralized, Mobile End User: Contractors, Builders, Government Agencies, Engineers |
| Companies Covered | BASF SE, Heidelberg Materials, Holcim Ltd., Fosroc Inc., CRH plc, CEMEX S.A.B. de C.V., Sika AG, Mapei Corporation, LafargeHolcim Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Strength Concrete Market Emerging Trajectories
Admixture chemistry and curing control systems are converging to compress strength development timelines while maintaining placement workability, reshaping contractor expectations for acceptable downtime windows.
Shrinkage-compensated rapid strength concrete is consolidating specification share in jointless industrial floor slabs. Warehouse developers in the US Sun Belt are specifying these systems to eliminate saw-cut contraction joints that disrupt automated guided vehicle operations. The technology is consolidating competitive positioning among flooring specialists who can warranty crack-free performance under accelerated curing protocols.
The EU Construction Products Regulation's tightened performance certification requirements for structural repair materials are forcing admixture suppliers to submit extended durability test data. German bridge authorities now require documented carbonation depth progression at 50-year design life as a condition of material approval. Precast producers with in-house testing capabilities are capturing specification advantage through faster certification turnaround.
Contractors are bundling material supply with placement quality guarantees, transferring performance risk from asset owners to ready-mix suppliers. Municipal procurement in California and Texas now evaluates bids on total lane closure duration rather than material unit cost. This behavior is concentrating award share among integrated suppliers with in-house paving crews and real-time strength monitoring capabilities.
Rapid Strength Concrete Market Segmentation
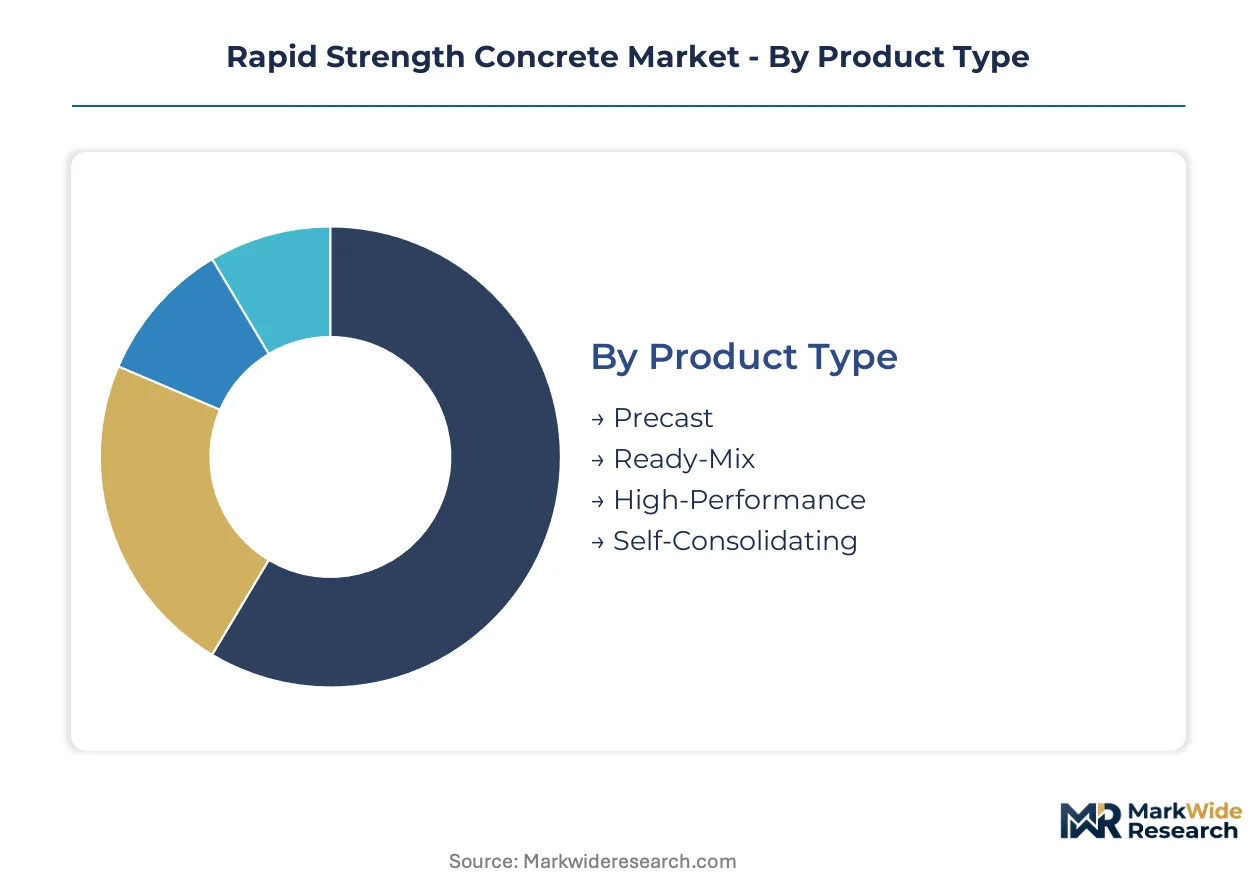
Rapid strength concrete procurement varies sharply by how the material integrates into project workflows. Standalone ready-mix delivery dominates highway rehabilitation, while embedded precast systems capture factory-automated production lines. Understanding these integration patterns reveals where margin pools concentrate and which segments face displacement risk from curing technology advances.
Product Type:
Integration depth separates segments that ship as finished systems from those requiring field assembly and quality control.
- Ready-Mix:Batch-plant controlled formulations with calibrated admixture dosing ensure consistent early-strength performance for transportation infrastructure. Highway rehabilitation contracts across Germany, France, and the United States specify ready-mix delivery to minimize field variability exposure.
- Precast:Factory-cured elements achieve optimal hydration control through captive curing environments that field conditions cannot replicate. Automated precast yards in Germany's industrial corridor are shifting volume toward this segment as specification tolerances tighten.
- High-Performance:Specialized blends for structural repair applications with documented durability envelopes.
- Self-Consolidating:Fluid mixes eliminating mechanical compaction for congested reinforcement geometries.
Ready-mix leads volumes today; precast is gaining share fastest.
Application:
Cost tier segmentation reveals which project types absorb material premiums versus those constrained by budget ceilings.
- Infrastructure:Bridge deck replacements and runway repairs accept 40-60% cost premiums to compress lane closure windows. State DOTs in California and Texas now evaluate bids on total closure duration rather than unit material cost.
- Industrial:Warehouse flooring specifications prioritize shrinkage-compensated systems to eliminate saw-cut joints that disrupt automated guided vehicle operations. Sun Belt developers in the United States are consolidating procurement around warranty-backed crack-free performance.
- Commercial:Mixed-use developments with tight construction schedules.
- Residential:Limited penetration due to cost sensitivity and schedule flexibility.
Infrastructure commands premium pricing; industrial applications show steepest expansion trajectory.
Delivery Mode:
Supply concentration patterns determine which delivery configurations achieve viable economics in peripheral markets.
- On-Site:Mobile batch plants positioned adjacent to major highway corridors enable just-in-time placement without transport time penalties. This configuration dominates North American interstate rehabilitation corridors.
- Centralized:Hub-and-spoke distribution from calcium aluminate cement production clusters in France and Germany creates freight cost penalties for contractors in Spain, Italy, and Eastern European markets.
- Off-Site:Precast yard production with controlled curing environments.
- Mobile:Portable mixing units for remote airfield repairs and emergency infrastructure response.
Centralized delivery anchors European supply; on-site configurations are climbing the fastest in North America.
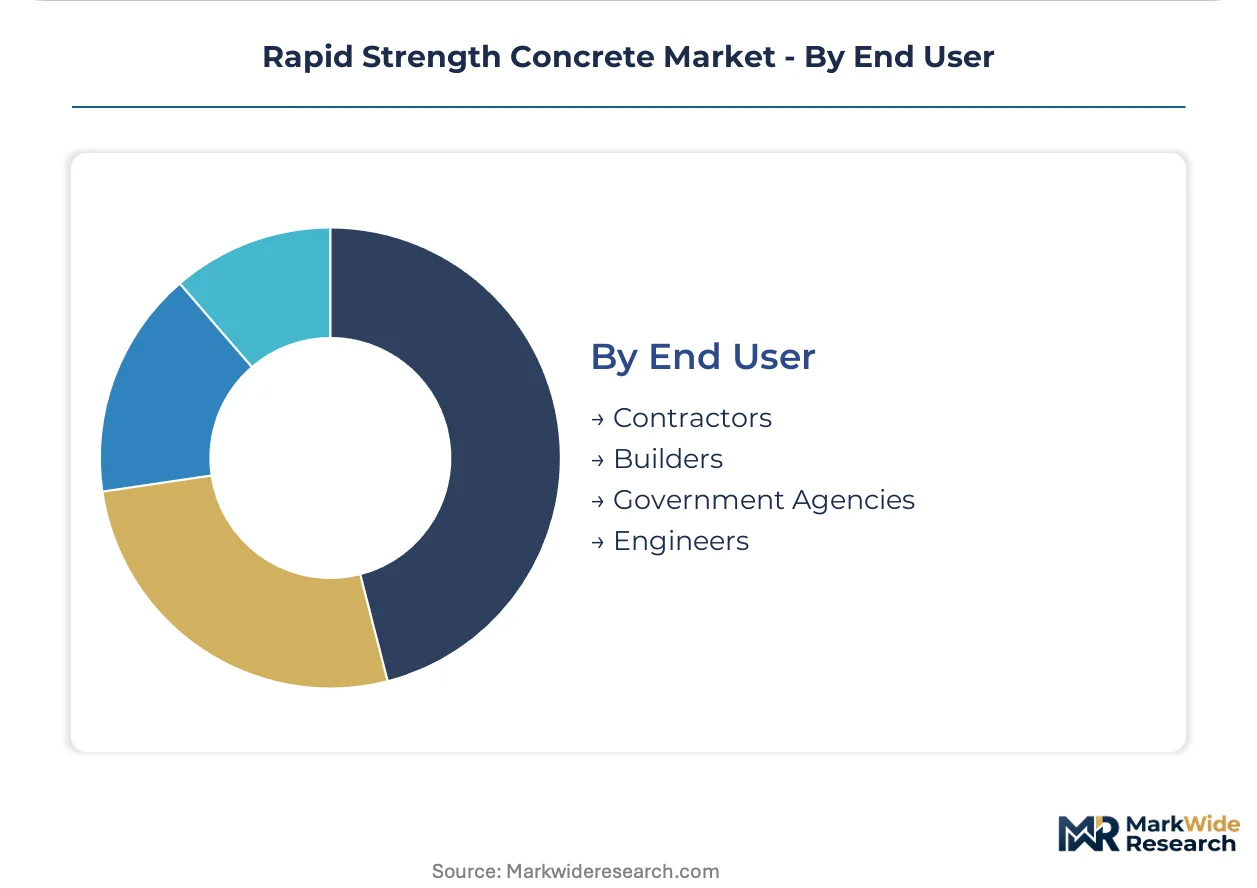
End User:
Customer type segmentation exposes where performance risk transfer is reshaping procurement behavior.
- Contractors:Integrated paving crews with real-time strength monitoring capabilities are capturing municipal award share as California and Texas shift to outcome-based bidding. These firms bundle material supply with placement quality guarantees.
- Government Agencies:State DOTs and bridge authorities now require documented carbonation depth progression at 50-year design life as a condition of material approval under EU Construction Products Regulation tightening.
- Builders:Commercial developers with schedule compression exposure.
- Engineers:Specification authors influencing material selection through performance-based design standards.
Contractors lead procurement volumes today; government agencies are expanding specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping calcium aluminate cement sourcing as producers migrate toward jurisdictions with streamlined environmental permitting. Compliance cost gaps between France and peripheral EU markets are redistributing supply chain configurations.
United States
State DOTs in California and Texas now mandate 24-hour opening-strength specifications for bridge deck replacements. The EPA's National Emission Standards for Hazardous Air Pollutants from Portland cement manufacturing imposes clinker factor constraints that elevate admixture innovation budgets. Mobile batch plants positioned along interstate rehabilitation corridors in the Southwest enable just-in-time placement without transport time penalties.
Germany
Aging bridge inventories in the industrial corridor demand accelerated curing solutions that minimize traffic disruption. The EU Construction Products Regulation's tightened performance certification requirements force admixture suppliers to submit extended durability test data. Precast producers in Baden-Württemberg leverage in-house testing capabilities to capture specification advantage through faster certification turnaround.
France
Calcium aluminate production clusters concentrate near legacy cement manufacturing sites, creating freight cost penalties for contractors in peripheral markets. EN 206 durability exposure categories for carbonation resistance and chloride ingress push asset owners toward certified rapid strength formulations. Lyon-based specialty cement distributors are expanding storage infrastructure to meet cold-weather pour demand.
China
Dual carbon goals under MEE oversight are pressuring clinker factor reduction in high-early-strength blends. The Yangtze River Delta's transportation infrastructure buildout compresses project timelines, forcing contractors toward mixes achieving structural load-bearing capacity within hours. Shanghai municipal procurement now evaluates bids on total construction duration rather than material unit cost.
United Arab Emirates
Airfield pavement maintenance specifications for rapid runway repair materials are tightening turnaround windows under Dubai Aviation Engineering Projects oversight. The country's national construction regulator is embedding lifecycle assessment methodologies into public procurement scoring. Abu Dhabi-based developers are specifying shrinkage-compensated systems for warehouse flooring to eliminate saw-cut joints disrupting automated guided vehicle operations.
Rapid Strength Concrete Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated cement-admixture networks capturing highway rehabilitation awards while independent flooring specialists dominate industrial slab warranties. The vendor base concentrates around three strategic archetypes: chemistry-led multinationals with admixture portfolios, integrated building materials conglomerates with captive cement supply, and regional specialists with shrinkage-compensated system expertise. M&A activity targets precast yard automation capabilities, while capacity expansion focuses on calcium aluminate cement blending facilities near transportation corridors.
Within the chemistry-led tier, BASF SE and Sika AG exemplify multinational positioning anchored by admixture formulation depth. Heidelberg Materials occupies a position representing integrated supply chain control from clinker production through ready-mix distribution. These three companies illustrate how competitive advantage consolidates around either proprietary chemical intellectual property or backward integration into cement manufacturing.
| Leading Market Players |
|---|
| BASF SE |
| Heidelberg Materials |
| Holcim Ltd. |
| Fosroc Inc. |
| CRH plc |
| CEMEX S.A.B. de C.V. |
| Sika AG |
| Mapei Corporation |
| LafargeHolcim Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into calcium aluminate cement production anchors pricing power for European suppliers serving Germany's industrial corridor, while peripheral market contractors absorb freight cost penalties that compress their bid competitiveness against integrated rivals.
Pricing Analysis
Distributor margin layers in rapid strength concrete typically capture 12-18 points between calcium aluminate cement producers and end-use contractors, though integrated suppliers bypass this layer entirely. Three-tier pricing structure across premium certified, standard grade, and economy blended tiers separates highway rehabilitation specifications from industrial flooring and minor repair applications. Cost compression in the economy tier is intensifying because EPA clinker factor constraints elevate admixture input costs. Municipal DOT procurement teams show lowest price sensitivity, while residential developers remain largely priced out of rapid strength categories.
Supply Chain Analysis
Single-source vulnerability sits with French and German calcium aluminate production clusters that feed formulated concrete supply across Western Europe. Manufacturing draws from specialty cement kilns, high-early-strength admixture chemical plants, and regional aggregate quarries. Tariff exposure on Chinese-sourced supplementary cementitious materials threatens margin stability for blenders dependent on slag and fly ash imports. Distribution runs through batch-plant networks positioned along interstate corridors in North America and hub-and-spoke configurations radiating from Lyon and Heidelberg in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rapid strength concrete has shifted to a late-cycle quality story as infrastructure owners prioritize documented 50-year durability envelopes over material unit cost, concentrating award share among certified suppliers with in-house testing capabilities.
For Market Incumbents: Hedge against alkali-silica reaction liability by securing aggregate testing partnerships in geologies with reactive silica exposure, and anchor position through captive calcium aluminate supply agreements that lock in raw material cost stability against freight volatility from French production clusters.
For New Entrants and Emerging Players: Regional precast yard operators represent the most penetrable channel partner type for specialty admixture suppliers lacking batch-plant scale, particularly in Spain and Italy where centralized European supply creates service gaps. Target automated flooring contractors in the US Sun Belt with shrinkage-compensated system warranties that bundled incumbents cannot match for speed of technical response.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap precast yard automation specialists because specification tightening under EU Construction Products Regulation fragments certification timelines and rewards in-house testing scale. The 5-10 year viability window favors targets with captive curing environments and documented carbonation depth progression data. Monitor FAA specification revisions for rapid runway repair materials as the signal indicating inflection toward ultra-high-early-strength system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcium Aluminate Supply | Heidelberg Materials and integrated cement conglomerates secure raw material cost stability against freight penalties from French production clusters. |
| Carbon Capture Curing Technology Deployment | CO2 injection during accelerated hydration enables carbon-negative concrete positioning for ESG-scored public procurement in California and Texas. |
| Precast Yard Automation Investment | Factory-controlled curing environments optimize high-early-strength admixture dosing that field conditions cannot replicate for specification advantage. |
| Extended Durability Certification Investment | German bridge authorities now require documented 50-year carbonation depth progression as mandatory condition for material approval. |
| Mobile Batch Plant Network Expansion | On-site mixing configurations along interstate rehabilitation corridors eliminate transport time penalties and capture outcome-based DOT bidding. |
Methodological Framework
Bottom-up infrastructure project modeling reconciled against top-down calcium aluminate cement production tracking forms the analytical core of this study. Primary interviews with state DOT specification engineers, ready-mix plant managers, precast yard operations directors, and specialty cement procurement leads were validated against secondary sources including EPA National Emission Standards compliance filings, EN 206 durability test databases, FAA material specification updates, and EU Construction Products Regulation certification registries.
Input-output matrices map calcium aluminate cement production volumes through formulation tiers, application segments spanning highway rehabilitation and industrial flooring, and delivery mode configurations across centralized, on-site, and precast yard channels. CAGRs were derived from regression analysis of historical project award data and specification adoption curves across the projection horizon. Forecast inputs include EN 206 exposure category tightening schedules and FAA rapid runway repair specification revision timelines.
Revisions become necessary when EPA emission standard enforcement intensity shifts, calcium aluminate production capacity relocates to jurisdictions with streamlined permitting, or lifecycle assessment methodologies alter public procurement scoring weights. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Basalt Rock Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Qatar Facade Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Blind Bolts Market
Building Materials
Spain Cement Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Steel Products Market
Building Materials
Dry Mix Mortar Market
Building Materials
Natural Stone Market
Building Materials
Cement Market
Building Materials
Global FRP Rebar Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Masonry Cement Market