
 Middle-East and Africa Buildings and Construction Sheets Market | 2026-2036
Middle-East and Africa Buildings and Construction Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Buildings and Construction Sheets Market Foresight
Skilled metal-fabrication labor availability is bifurcating the Middle-East and Africa Buildings and Construction Sheets Market into premium-specification and cost-driven supply tiers. Al Shafar Steel Engineering leverages its UAE fabrication base to anchor large-format steel roofing contracts across Gulf states. Palram Industries Ltd specializes in polycarbonate and PVC sheet systems for daylighting applications, differentiating through thermal-performance engineering. Clotan Steel competes aggressively on galvanized coil throughput, sustaining price competitiveness in South African residential rollout programs.
Buildings and construction sheets are flat or profiled planar materials manufactured from metal alloys, thermoplastics, glass, or fiber-reinforced composites, typically supplied in standardized widths from millimeters to several meters and engineered to provide weather protection, structural enclosure, or thermal insulation in built environments. Metal sheets dominate current specification volumes across the region's industrial and institutional verticals due to durability and ease of on-site forming. Plastic sheet demand, particularly PVC and polycarbonate variants, is expanding fastest in commercial greenhouse and skylight segments where translucency and weight reduction matter. Composite sheets occupy a narrower but higher-margin niche in architecturally specified facade systems where thermal bridging constraints apply.
South Africa's National Regulator for Compulsory Specifications enforces SANS fire-performance standards that directly determine which sheet compositions qualify for high-rise installation, while Gulf states apply civil defense and municipality-specific facade-engineering guidelines that vary between Dubai, Riyadh, and Doha. The UAE's Ministry of Industry and Advanced Technology is aligning local product certification with broader GCC standardization frameworks, tightening market access for uncertified imports. Stakeholders must monitor how divergent national certification timelines affect inventory positioning and cross-border project logistics across this multi-jurisdiction region.
Market Dynamics
Saudi Arabia's giga-project pipeline is compressing specification timelines and forcing rapid qualification of new cladding systems. Developers now demand metal-composite hybrid sheets that satisfy both aesthetic and thermal-performance criteria within compressed procurement windows.
Growth Catalysts
- SANS fire-performance standards:South Africa's updated building codes mandate higher fire-resistance ratings for high-rise applications, directly expanding specification volumes for certified metal sheet systems in Johannesburg and Cape Town residential towers.
- Daylighting engineering:Commercial greenhouse operators across Morocco and Egypt specify polycarbonate sheet systems with engineered thermal barriers, displacing glass in controlled-environment agriculture.
- GCC residential-commercial mixed-use concentration:Dubai and Riyadh developers bundle cladding procurement across multi-tower phases, creating volume anchors that justify dedicated regional sheet fabrication capacity.
Market Restraints
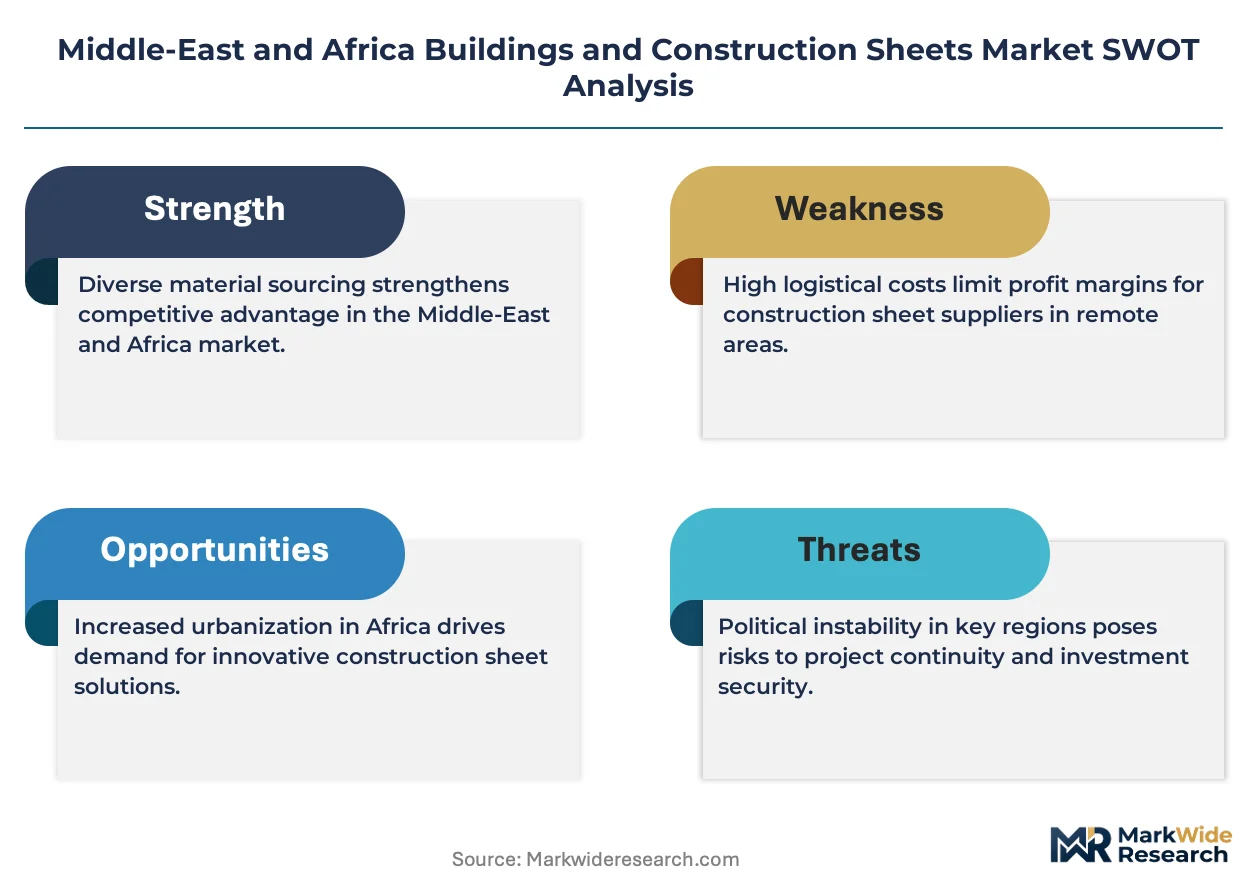
- Galvanized steel coil price volatility:Input cost swings tied to global zinc and iron ore markets compress margin predictability for South African residential rollout programs.
- UAE-UAE fabrication concentration:Large-format steel roofing capacity clusters in Dubai and Sharjah, exposing Gulf projects to single-point logistics disruption during port congestion events.
- Thermal bridging limitations:Conventional metal sheets without composite backing fail to meet facade-engineering guidelines in Doha's civil defense codes, restricting pure-metal specification in Qatari high-rises.
Strategic Opportunities
- Nigerian commercial real estate:Lagos and Abuja mixed-use developments remain underpenetrated by certified cladding suppliers, creating first-mover positioning for SANS-compliant sheet systems.
- Photovoltaic-integrated roofing:Building-integrated solar manufacturers in the UAE seek lightweight substrate partnerships with polycarbonate sheet producers for BIPV facade applications.
- MOHAP product certification alignment:The UAE's Ministry of Industry and Advanced Technology is streamlining cross-GCC recognition protocols, reducing duplicate testing costs for sheet exporters targeting Saudi and Qatari projects simultaneously.
Industry Challenges
- Skilled metal-fabrication labor scarcity:TIG welding and CNC forming expertise concentrates in Dubai and Johannesburg, forcing project delays in secondary Gulf and African markets.
- Multi-jurisdiction certification timelines:Divergent municipality-specific facade-engineering guidelines between Riyadh, Doha, and Dubai require parallel testing tracks that fragment inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Buildings and Construction Sheets Market |
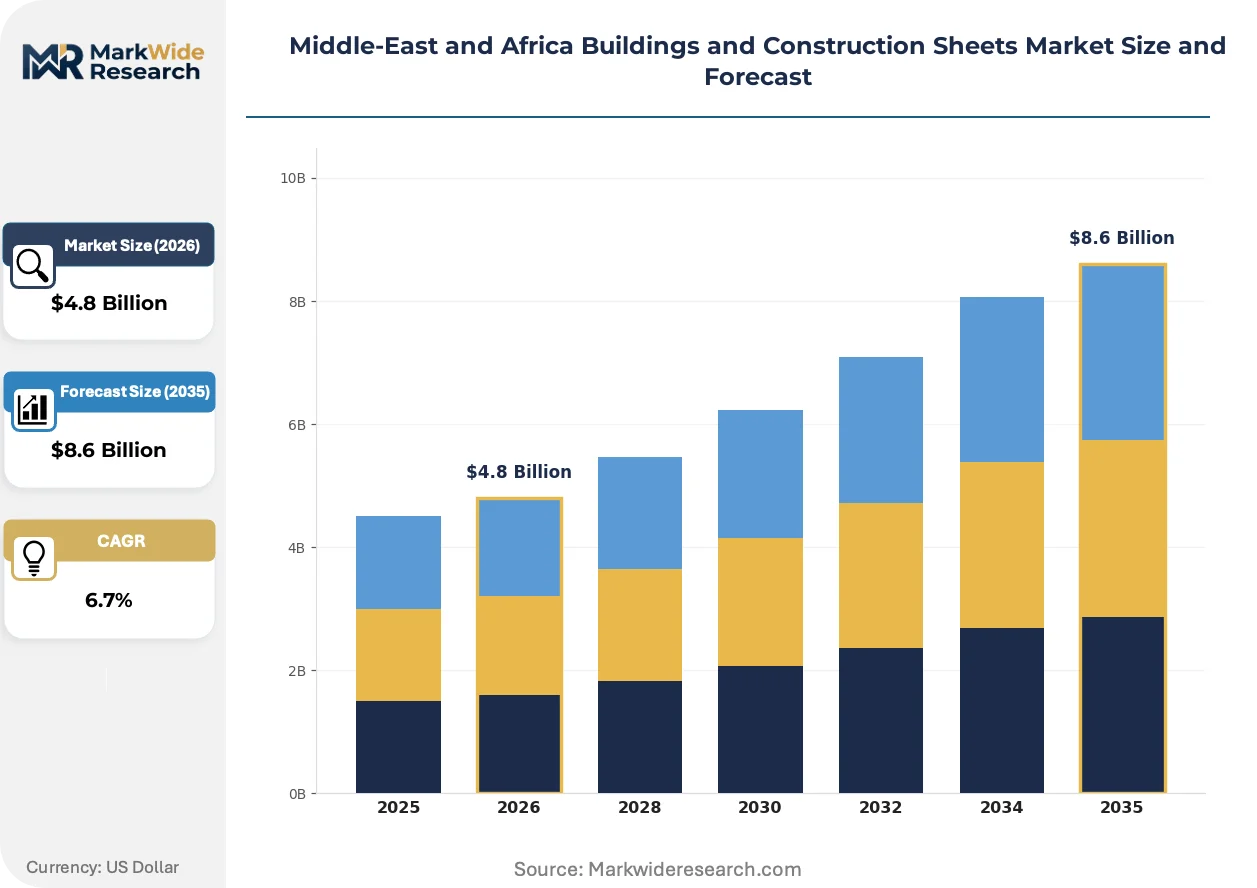
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Sheets, Plastic Sheets, Glass Sheets, Composite Sheets Application: Residential, Commercial, Industrial, Institutional Material: Aluminum, PVC, Fiberglass, Steel Thickness: Thin, Medium, Thick, Ultra-Thick |
| Companies Covered | Al Shafar Steel Engineering, Corrugated Sheet Ltd, Palram Industries Ltd, Safintra Rwanda Ltd, Ampa Plastics Group Pvt Ltd, Youngman, Gautruss Pty Ltd, Clotan Steel, Algoa Steel & Roofing, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Buildings and Construction Sheets Market Shifts & Advancements
Active specification is rotating toward engineered composite systems that resolve thermal-performance constraints without sacrificing architectural flexibility. Material science advances and procurement model compression are jointly reshaping supplier positioning.
Insulated metal panel technology is fragmenting traditional single-skin sheet specification across Saudi giga-projects. NEOM and Red Sea Project developers specify sandwich-panel systems with integrated mineral wool cores that eliminate secondary insulation trades. This convergence is compressing project schedules and displacing conventional built-up roofing assemblies in Riyadh commercial towers.
SANS 10400-T fire-performance amendments are tightening combustibility thresholds for external wall cladding in South African high-rises above three stories. Johannesburg developers now pre-qualify sheet suppliers based on SANS test reports before tender release, compressing the vendor pool. Cape Town architectural practices specify A1-rated metal composite materials that satisfy both SANS and insurance underwriter requirements simultaneously.
Developer procurement teams now bundle cladding, glazing, and waterproofing into single-package tenders managed by main contractors rather than direct sheet supplier engagement. This consolidation is compressing distributor margins in Dubai and forcing regional stockists to add value through cut-to-size and logistics services. Saudi giga-project procurement offices mandate this bundled approach to reduce interface risk across facade trades.
Middle-East and Africa Buildings and Construction Sheets Market Segmentation
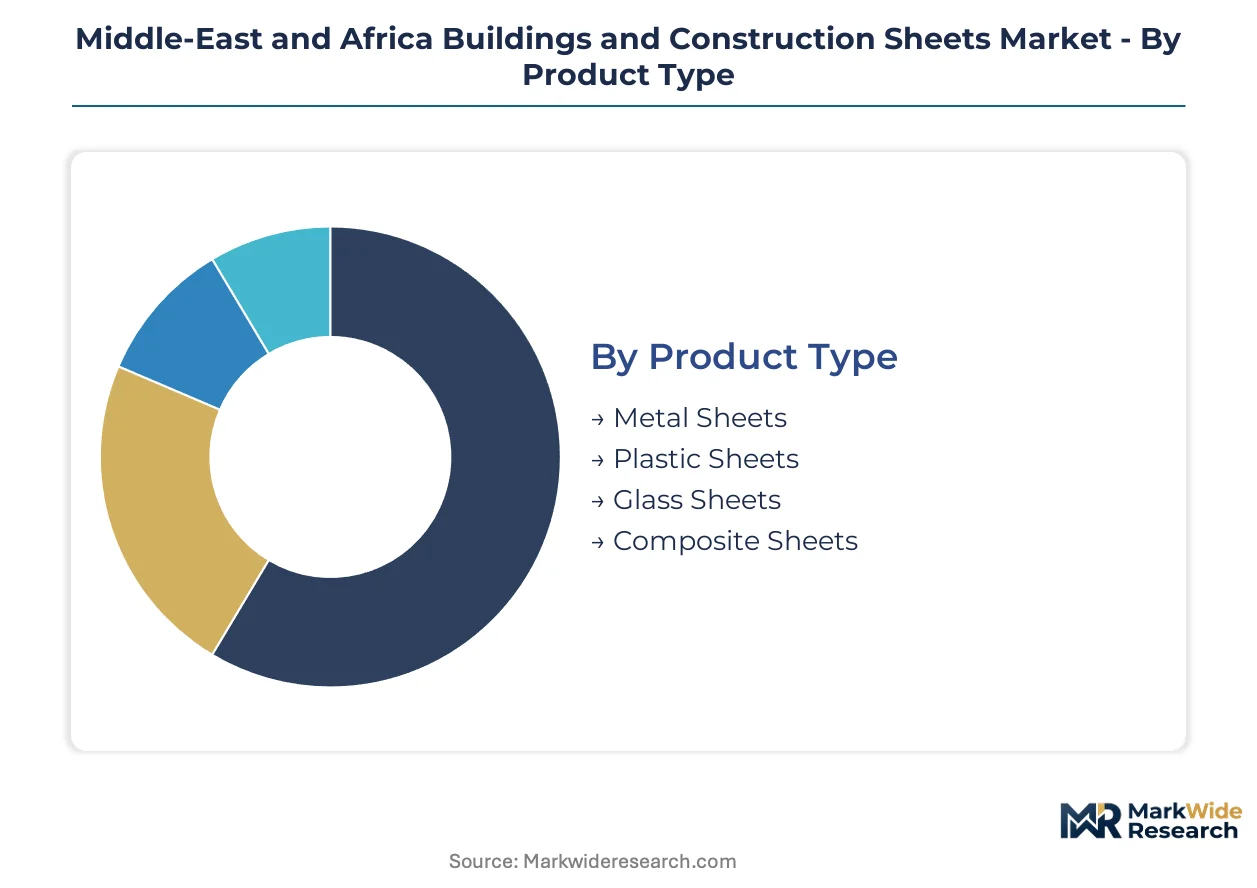
Construction sheet procurement across the Middle-East and Africa follows divergent specification logics: Gulf states prioritize thermal-performance engineering for high-rise facades, while African markets emphasize cost-optimized residential rollout programs. Understanding how product categories map to these distinct demand centers enables suppliers to align fabrication capacity with qualified project pipelines.
Product Type:
Metal sheets dominate Saudi and UAE export flows, while plastic and glass variants serve more localized daylighting and controlled-environment agriculture clusters.
- Metal Sheets:Aluminum and steel alloys engineered for structural enclosure and weather protection anchor industrial and high-rise specification across Gulf Cooperation Council states. Saudi giga-projects compress procurement timelines for these systems, forcing rapid qualification of hybrid metal-composite configurations that satisfy both aesthetic and thermal-performance criteria.
- Plastic Sheets:Polycarbonate and PVC formulations deliver translucency with weight reduction for commercial greenhouse and skylight applications. Moroccan and Egyptian operators specify these systems with engineered thermal barriers, displacing glass in controlled-environment agriculture where capital efficiency matters.
- Glass Sheets:Tempered and laminated variants retain specification in premium commercial facades where optical clarity is non-negotiable. Johannesburg and Cape Town developers source these through specialized glazing contractors rather than sheet distributors.
- Composite Sheets:Fiber-reinforced and metal-faced sandwich panels occupy architecturally specified niches where thermal bridging constraints apply. Doha's civil defense codes restrict pure-metal specification in high-rises, expanding qualified demand for these engineered systems.
Metal sheets hold the largest share; momentum sits with composite sheets as facade-engineering guidelines tighten across Gulf states.
Application:
Procurement concentration varies sharply: residential-commercial mixed-use developments bundle cladding across multi-tower phases, while industrial and institutional verticals specify through separate maintenance and capital budget channels.
- Residential:South African rollout programs drive galvanized coil throughput for single-family and low-rise housing, with SANS fire-performance standards determining supplier qualification for high-rise towers above three stories.
- Commercial:Dubai and Riyadh mixed-use developments create volume anchors that justify dedicated regional fabrication capacity. Procurement teams bundle cladding, glazing, and waterproofing into single-package tenders managed by main contractors.
- Industrial:Warehouse and logistics facility construction across Jeddah and Dammam specifies single-skin metal roofing for cost efficiency. These projects tolerate longer lead times than commercial facades.
- Institutional:Hospital and university construction in Abuja and Lagos remains underpenetrated by certified cladding suppliers, creating first-mover positioning for SANS-compliant sheet systems.
Commercial applications command premium pricing; institutional represents the steepest expansion trajectory as African healthcare and education infrastructure investment accelerates.
Material:
Input cost volatility and certification complexity stratify the supplier base: aluminum and steel producers navigate zinc and iron ore price swings, while PVC and fiberglass specialists compete on formulation consistency.
- Aluminum:Lightweight corrosion resistance suits coastal high-rise facades in Dubai and Doha. Pre-coated coil products reduce on-site finishing requirements and accelerate installation schedules.
- PVC:Rigid and flexible formulations serve interior lining and exterior weatherboard applications. Egyptian manufacturers leverage domestic petrochemical feedstock for cost-competitive regional supply.
- Fiberglass:Reinforced polymer sheets deliver chemical resistance for industrial process environments and coastal corrosion zones. Specification concentrates in Saudi Aramco and ADNOC facility maintenance programs.
- Steel:Galvanized and pre-painted coil dominates South African residential programs and Gulf industrial roofing. Price volatility in global zinc markets compresses margin predictability for stockist-distributors.
Steel maintains volume leadership; aluminum is gaining share fastest as architectural specification gravitates toward lightweight facade systems.
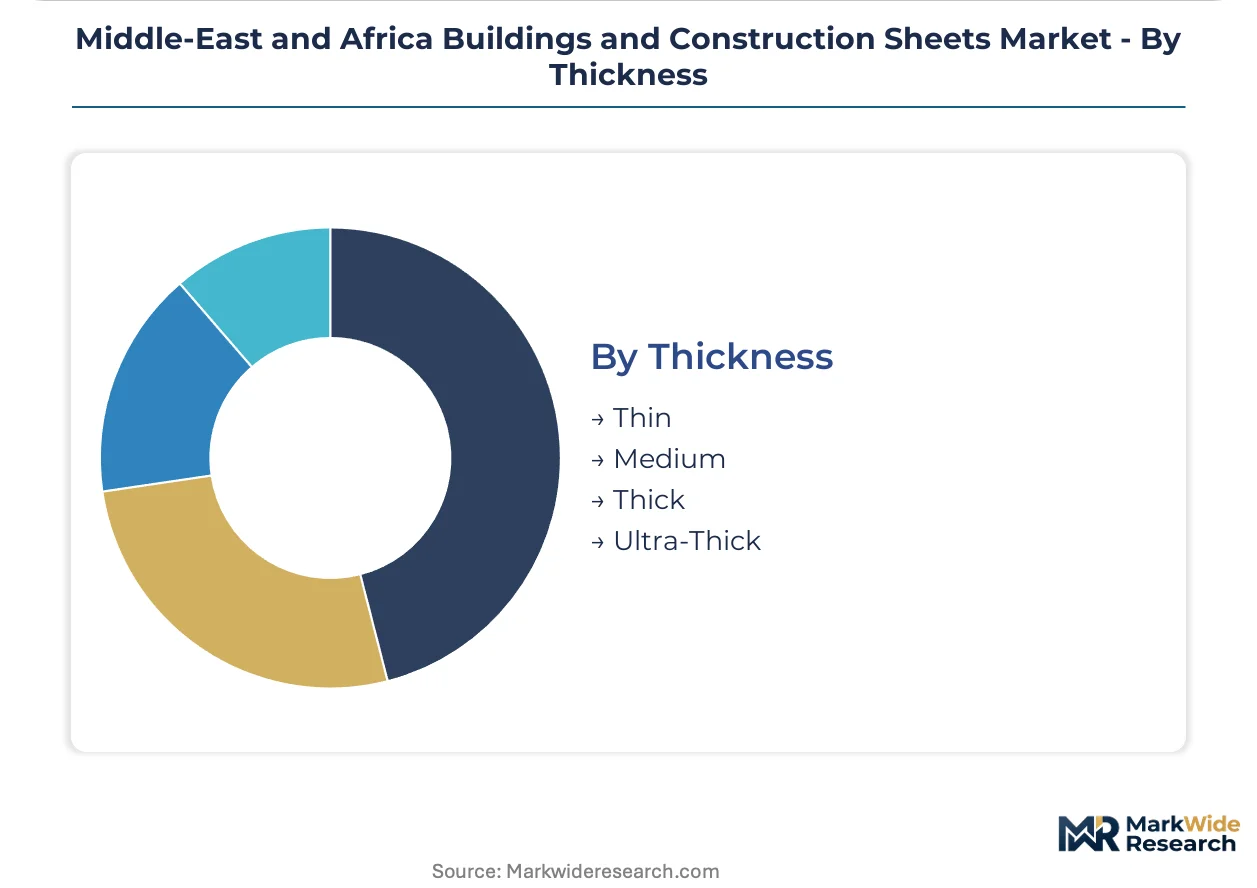
Thickness:
Fabrication capability and logistics economics concentrate supply: thin and medium gauges ship efficiently from UAE mills, while thick and ultra-thick systems require localized forming capacity.
- Thin:Sub-millimeter gauges serve interior partition and ceiling applications where structural load is minimal. These products move through distributor stock-and-defer models.
- Medium:One-to-three millimeter specifications balance span capability with weight for standard commercial roofing. Dubai and Sharjah fabrication clusters concentrate capacity for these gauges.
- Thick:Structural decking and blast-resistant facade applications require four-to-eight millimeter material. Saudi giga-projects specify these through direct mill relationships rather than stockists.
- Ultra-Thick:Specialized industrial flooring and ballistic protection systems exceed standard forming equipment limits. Supply concentrates in European and East Asian export channels.
Medium thickness commands the deepest project pipeline; ultra-thick remains the narrowest segment with highest margin per ton.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in UAE fabrication clusters while South African residential programs absorb margin pressure from zinc input volatility. This asymmetry shapes inventory positioning and cross-border logistics strategies across the region.
United Arab Emirates
Dubai and Sharjah anchor large-format steel roofing fabrication for Gulf-wide export. MOHAP certification alignment with broader GCC frameworks tightens market access for uncertified imports. The Jebel Ali corridor concentrates medium-gauge forming capacity serving Saudi giga-project procurement offices.
Saudi Arabia
NEOM and Red Sea Project developers compress specification timelines for hybrid metal-composite cladding systems. Civil defense and municipality-specific facade guidelines in Riyadh vary from Doha and Dubai standards. Eastern Province industrial zones supply single-skin metal roofing for warehouse construction with longer lead-time tolerance.
South Africa
Johannesburg and Cape Town residential towers drive certified metal sheet demand under SANS 10400-T fire-performance amendments. The National Regulator for Compulsory Specifications enforces combustibility thresholds above three stories. Gauteng fabrication clusters concentrate TIG welding expertise for high-rise pre-qualification.
Nigeria
Lagos and Abuja mixed-use developments remain underpenetrated by certified cladding suppliers. Federal Ministry of Works and Housing building codes lack harmonization with SANS or GCC standards. Port Harcourt industrial zones import medium-gauge coil through Lagos port corridors facing congestion exposure.
Morocco
Commercial greenhouse operators specify polycarbonate sheet systems with engineered thermal barriers for controlled-environment agriculture. The country's national construction regulator applies facade-performance standards distinct from Gulf or South African frameworks. Casablanca-Rabat corridor distributors serve daylighting demand displacing glass in horticultural applications.
Middle-East and Africa Buildings and Construction Sheets Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa Buildings and Construction Sheets Market. Premium-specification suppliers concentrate fabrication expertise in Dubai and Johannesburg, while coil-throughput competitors anchor South African residential programs. Three archetypes dominate: integrated steel fabricators with GCC-wide logistics networks, polycarbonate specialists with thermal-performance engineering capabilities, and galvanized coil stockists competing on price in volume rollout markets. Competitive moves center on bundled procurement packaging and cross-GCC certification streamlining to reduce duplicate testing costs.
Among UAE-based fabricators, Al Shafar Steel Engineering occupies a position representing integrated steel fabrication archetypes with Gulf-wide contract anchoring. Palram Industries Ltd exemplifies the technology-specialist tier through its polycarbonate and PVC sheet focus. Clotan Steel sits within the cost-competitive South African tier, representing galvanized coil throughput positioning in residential rollout programs. These three anchors illustrate how geographic specialization and capability differentiation stratify competitive positioning across premium and volume market segments.
| Leading Market Players |
|---|
| Al Shafar Steel Engineering |
| Corrugated Sheet Ltd |
| Palram Industries Ltd |
| Safintra Rwanda Ltd |
| Ampa Plastics Group Pvt Ltd |
| Youngman |
| Gautruss Pty Ltd |
| Clotan Steel |
| Algoa Steel & Roofing |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for medium-gauge steel coil from Dubai mills concentrate pricing power among UAE-based fabricators serving Saudi giga-projects, while South African residential programs absorb margin compression from zinc input volatility. This inventory-to-pricing linkage stratifies the Middle-East and Africa Buildings and Construction Sheets Market into premium-specification and cost-driven supply tiers.
Pricing Analysis
Price spreads between Gulf Cooperation Council and South African markets reflect divergent input cost structures and certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates SANS-compliant metal composite systems from galvanized coil stock and uncertified imports. Pricing pressure stems from global zinc and iron ore volatility compressing margins for South African residential rollouts. Institutional buyers in Nigerian mixed-use developments show highest price sensitivity, while Saudi giga-project procurement offices prioritize thermal-performance compliance over unit cost.
Supply Chain Analysis
Port congestion at Jebel Ali and Lagos corridors elevates inbound logistics costs for medium-gauge coil shipments from East Asian export mills. Supply concentrates in the UAE, South Africa, and Egypt, with fabrication clusters in Dubai and Sharjah anchoring Gulf-wide distribution. Raw material dependencies center on galvanized steel coil, aluminum pre-coated products, and polycarbonate resin feedstock. Single-source vulnerability exists for TIG welding and CNC forming expertise concentrated in Johannesburg and Dubai. Distribution runs through main contractor bundled procurement channels displacing direct sheet supplier engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa Buildings and Construction Sheets Market demands substitution defense as insulated metal panel technology fragments traditional single-skin sheet specification across Saudi giga-projects.
For Market Incumbents: Shield specification position by accelerating SANS and MOHAP certification alignment to reduce duplicate testing costs across GCC jurisdictions, and anchor capacity expansion in Sharjah fabrication clusters to capture bundled procurement volumes from Riyadh and Dubai developers. Insulated metal panel displacement of built-up roofing assemblies represents the core substitution threat requiring thermal-performance engineering investment. For New Entrants and Emerging Players: Cut-to-size logistics services and rapid qualification support for compressed Saudi procurement timelines open white-space positioning where incumbents under-serve. Target Nigerian institutional construction in Abuja and Lagos, where certified cladding suppliers remain scarce and federal building codes lack harmonization with SANS or GCC standards. Lead with SANS-compliant sheet system pre-qualification to differentiate against uncertified imports. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because bundled procurement consolidation across Gulf mixed-use developments favors scaled fabricators with cross-border logistics networks. Acquisition targets should display MOHAP certification and established main contractor relationships. Watch for MOHAP-GCC standardization protocol finalization as the inflection signal accelerating cross-border volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-GCC Certification Streamlining | MOHAP alignment with Saudi and Qatari standards reduces duplicate testing costs for sheet exporters. |
| Insulated Metal Panel Capacity Buildout | NEOM and Red Sea Project procurement offices specify sandwich-panel systems eliminating secondary insulation trades. |
| Backward Integration into Coil Supply | Captive galvanized steel supply buffers South African stockists against zinc price volatility. |
| Cut-to-Size Logistics Services | Distributor margin compression forces value-added fabrication and just-in-time delivery capabilities. |
| Photovoltaic-Integrated Roofing Partnerships | UAE building-integrated solar manufacturers seek lightweight polycarbonate substrate collaborations. |
Research Methodology
Initial hypotheses were tested against primary input from facade engineering consultants, procurement directors at Saudi giga-project developers, South African stockist-distributors, and UAE-based fabrication plant managers, and refined through secondary validation against customs/trade data, SANS regulatory filings, MOHAP certification registries, and GCC construction project databases. Bottom-up project pipeline enumeration triangulated with top-down regional construction spend estimates to anchor volume assumptions.
Variance decomposition across product type, application, material, thickness, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro construction indicators. Forecast inputs included Saudi giga-project procurement timeline compression, SANS 10400-T amendment implementation schedules, and polycarbonate greenhouse specification trends in Moroccan controlled-environment agriculture.
Forecasts assume regulatory continuity in UAE MOHAP, Saudi civil defense, and South African NRCS regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ductile Iron Pipe Market
Building Materials
GRC Cladding Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Granite Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
North America Engineered Stone Market
Building Materials
Italy Facade Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Drywall Joint Tape Market
Building Materials
Fiber Cement Market
Building Materials
Iron and Steel Slag Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Global FRP Rebar Market
Building Materials
US Contract Glazing Market
Building Materials
Composite Rebar Market
Building Materials
Composite Decking and Railing Market