
 Hydraulic Chainsaw Market | 2026-2036
Hydraulic Chainsaw Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Chainsaw Market Foresight
Equipment leasing and rental financing is fragmenting the competitive landscape for hydraulic chainsaws, allowing mid-sized contractors to access industrial-grade cutting tools without capital-intensive purchases. STANLEY leverages its infrastructure rental partnerships to sustain North American channel dominance. TOOLGAL anchors its position through in-house production of diamond-chain systems for demolition applications. CS Unitec competes via specialized underwater and hazardous-environment hydraulic saws for marine and nuclear decommissioning contracts.
A hydraulic chainsaw converts pressurized fluid energy from an external power unit—typically operating at 140–210 bar—into reciprocating chain motion through a hydraulic motor, enabling continuous cutting without direct engine exposure to debris or ignition sources. Its primary industrial purpose centers on timber felling, concrete demolition, and emergency rescue operations where pneumatic or combustion-powered alternatives face operational constraints. Heavy-Duty product configurations command the widest margin pools due to extended duty cycles in professional forestry and demolition settings. The Emergency Services end-user segment registers the fastest structural expansion as urban search-and-rescue teams standardize on hydraulic extrication and cutting toolsets. Battery-Powered technology within the broader chainsaw category is displacing entry hydraulic units in landscaping maintenance, though hydraulic systems retain irreplaceable torque advantages in primary timber processing.
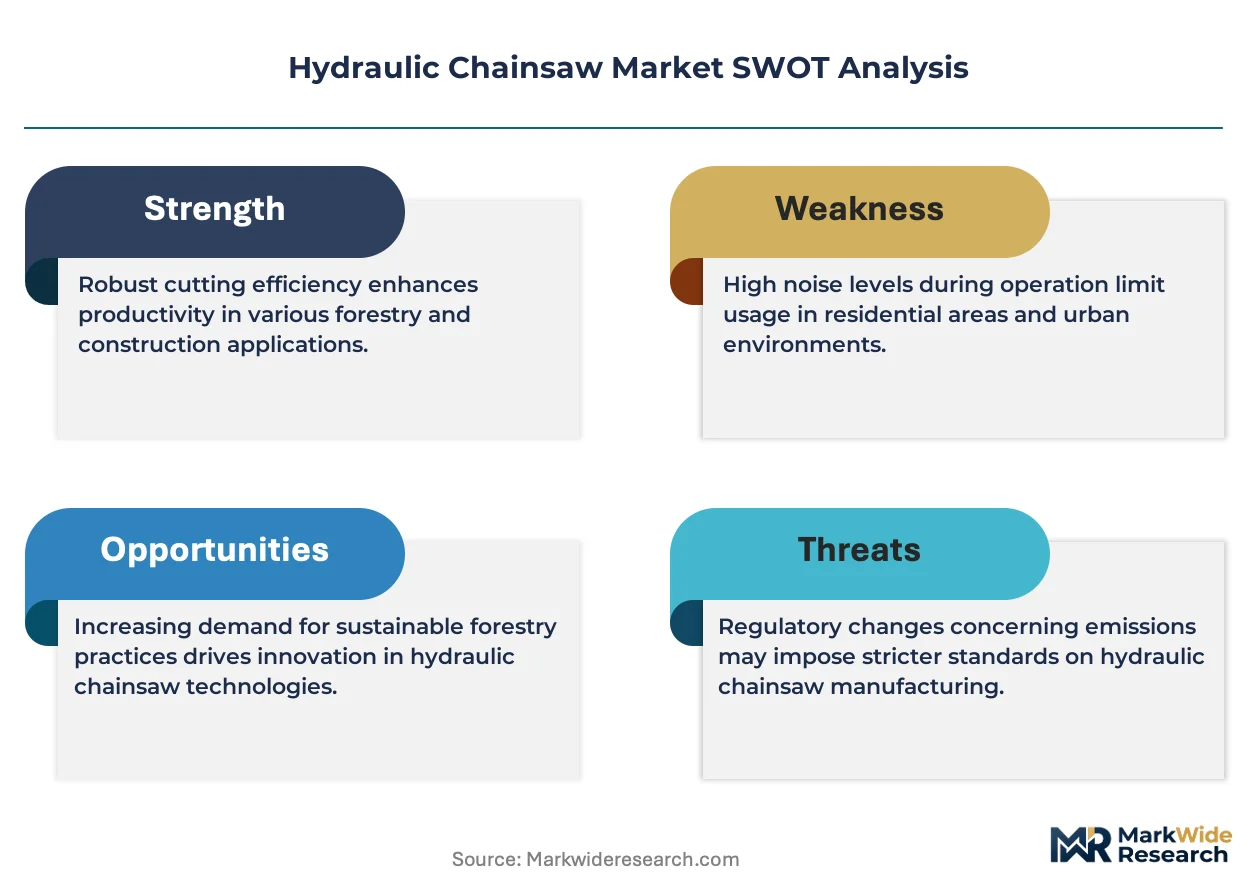
OSHA chain brake and kickback protection standards shape product design requirements for US commercial operators, while EPA small-engine emission regulations constrain combustion alternatives and indirectly bolster hydraulic system competitiveness. The EU Machinery Directive and CE marking requirements govern European market access, with REACH compliance adding material traceability obligations for hydraulic fluid compatibility. Stakeholders must monitor how evolving urban wildfire mitigation budgets redirect procurement between municipal emergency services and traditional forestry agencies.
Market Dynamics
Equipment leasing programs are fragmenting ownership patterns across forestry and demolition verticals, converting capital expenditures into operational line items and eroding traditional distributor lock-in.
Growth Catalysts
- EPA small-engine emission rules:Tightening combustion restrictions in the US are redirecting procurement toward hydraulic systems that bypass direct exhaust regulations entirely.
- Urban search-and-rescue standardization:Emergency services agencies are mandating hydraulic extrication toolsets, creating dedicated specification pipelines for certified cutting equipment.
- Precision timber harvesting in Germany:Selective felling requirements are sustaining premium hydraulic tool demand where torque precision outweighs speed metrics.
Market Restraints
- Hydraulic fluid compatibility costs:REACH material traceability obligations in Europe are extending compliance timelines and raising formulation validation expenses for fluid suppliers.
- Battery-powered substitution in landscaping:Lithium-ion chainsaws are capturing maintenance-scale applications where duty cycles remain below hydraulic break-even thresholds.
- Power unit dependency:External hydraulic power pack requirements create tethering constraints that limit mobility in remote felling operations without established infrastructure.
Strategic Opportunities
- Underwater cutting expansion:Marine salvage and offshore decommissioning contracts are opening specialized application zones where pneumatic and combustion systems face ignition barriers.
- Rental channel consolidation:Infrastructure equipment lessors are building dedicated hydraulic cutting categories, creating captive demand streams outside traditional dealer networks.
- EU Machinery Directive alignment:CE marking harmonization is enabling single-certification market access across multiple European jurisdictions for compliant manufacturers.
Industry Challenges
- Hydraulic technician scarcity:Specialized maintenance skills for high-pressure seal systems and motor diagnostics are concentrating in legacy forestry equipment hubs, constraining service network expansion.
- OSHA chain brake certification timelines:Kickback protection validation protocols are extending product launch cycles for new entrants seeking commercial operator approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Chainsaw Market |
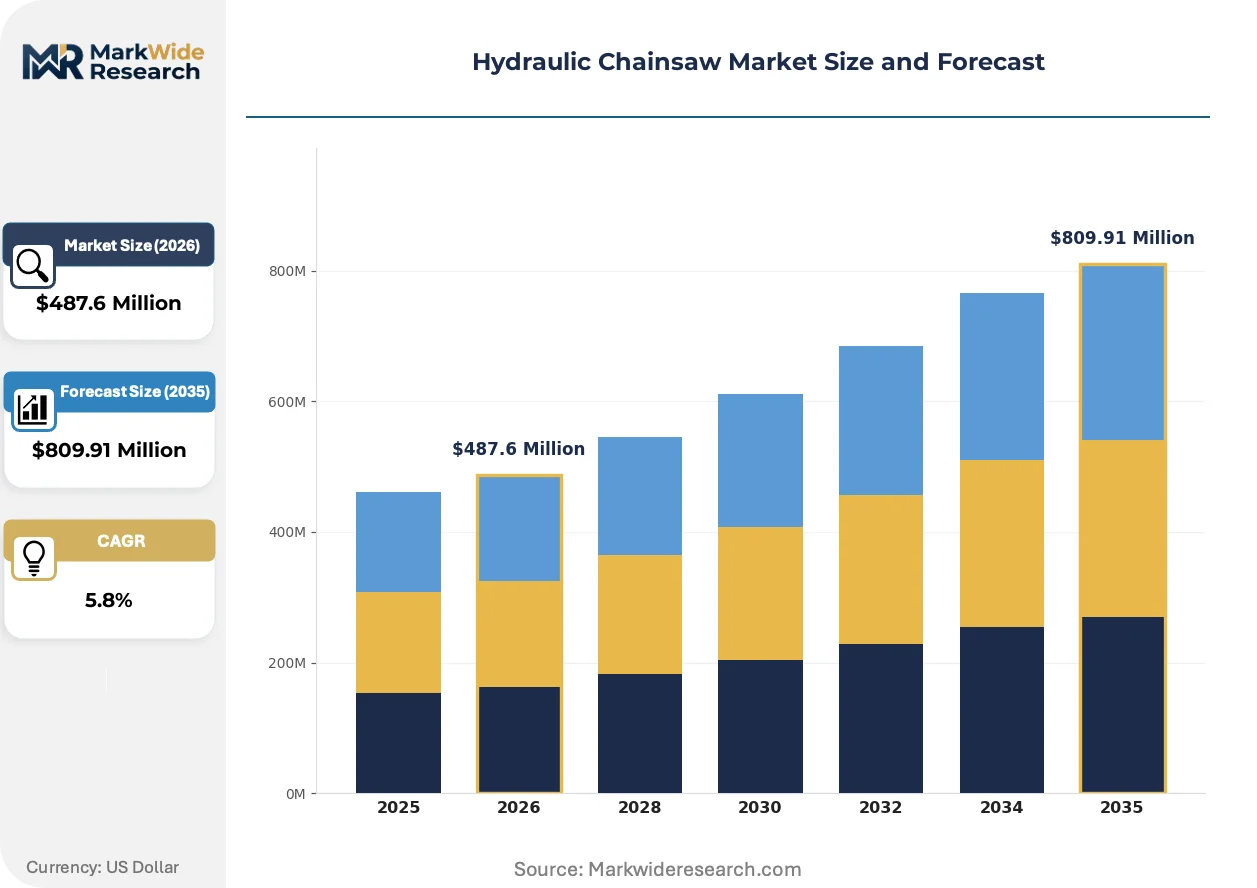
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Heavy-Duty, Multi-Function End User: Construction, Forestry, Landscaping, Emergency Services Technology: Electric, Hydraulic, Battery-Powered, Pneumatic Application: Tree Cutting, Demolition, Timber Processing, Rescue Operations |
| Companies Covered | USSaws, TOOLGAL, PAWACKER, Spitznas Maschinenfabrik GmbH, Maruzen Kogyo, STANLEY, CS Unitec, Weiping, Zondar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Chainsaw Market Shifts & Advancements
Diamond-chain cutting systems are compressing equipment lifecycle economics across concrete demolition, while regulatory pressure on combustion alternatives accelerates hydraulic specification in emission-sensitive zones.
Composite guide bar materials are collapsing weight-to-rigidity ratios in professional-grade hydraulic chainsaws. Forestry contractors operating extended shifts are adopting carbon-fiber reinforced bars to reduce operator fatigue without sacrificing cutting stability. The resulting demand compression for traditional steel-bar replacements is restructuring aftermarket parts revenue models toward premium consumables.
REACH compliance is mandating hydraulic fluid formulation disclosures across European supply chains. Equipment OEMs are demanding certified compatibility documentation from fluid suppliers before warranty authorization. German and Austrian forestry operators are experiencing the most acute documentation burden, with some contractors consolidating purchases around pre-approved fluid brands to simplify audit trails.
After-sales service unbundling is separating maintenance contracts from equipment sales in North American rental channels. Independent service providers are capturing hydraulic motor rebuild work that previously flowed through manufacturer-authorized networks. Pacific Northwest contractors are driving this fragmentation fastest, where equipment lessors prioritize turnaround speed over brand-aligned service continuity.
Hydraulic Chainsaw Market Segmentation
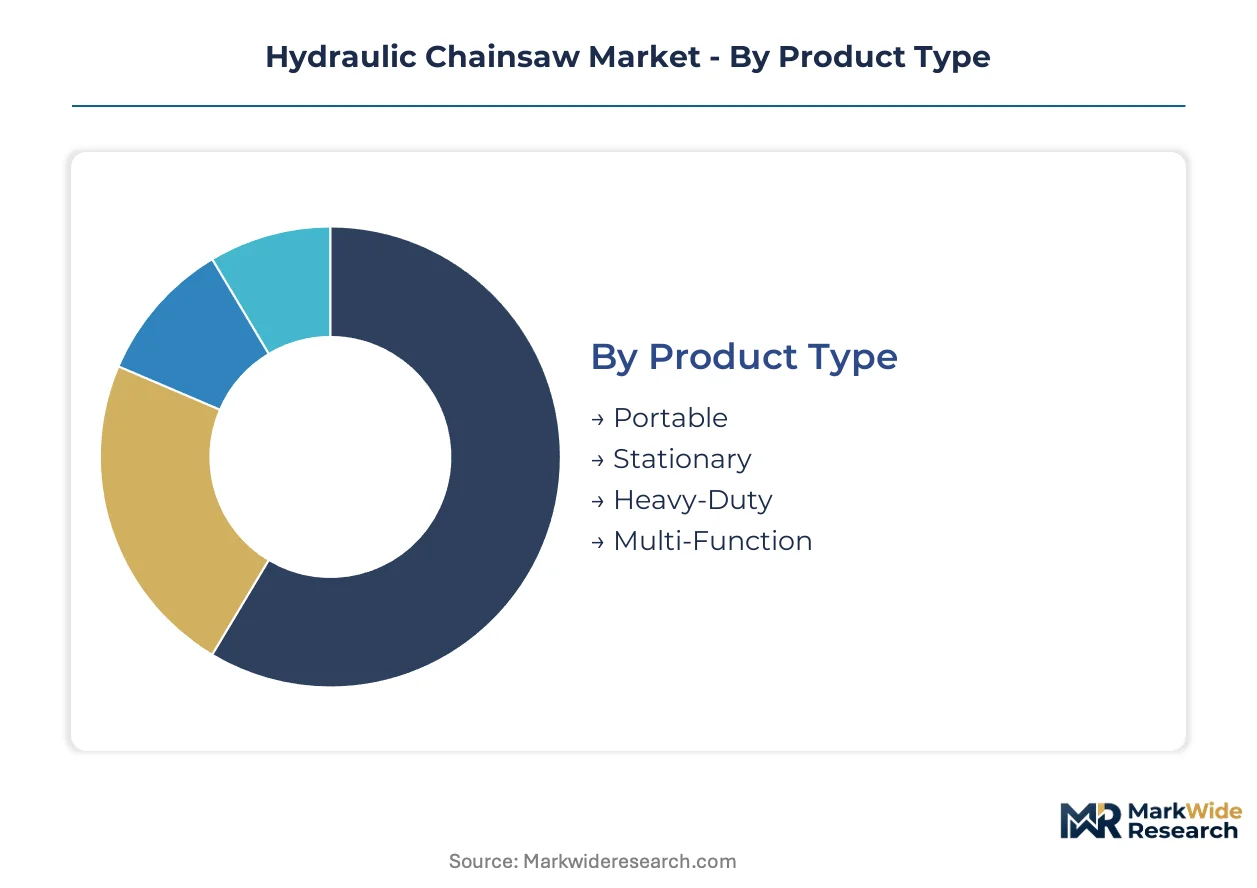
Segmentation in hydraulic chainsaws reveals how torque requirements, duty cycles, and regulatory exposure split demand across radically different user economics. Contractors select configurations based on whether they need tethered continuous power or intermittent cutting mobility.
Product Type:
Mature configurations dominate revenue, while emerging multi-function platforms are capturing specification share in integrated tool fleets.
- Heavy-Duty:Built around reinforced drive systems and extended guide bars exceeding 90 centimeters, these units handle primary timber felling and industrial demolition where duty cycles run 8+ hours. German precision harvesting operations specify these configurations for selective cutting where torque stability outweighs portability concerns.
- Portable:Compact motor housings and reduced bar lengths under 50 centimeters suit maintenance crews and utility line clearance. Pacific Northwest leasing programs are expanding access to these units for mid-sized contractors avoiding capital-intensive purchases.
- Stationary:Fixed-mount hydraulic heads integrated into processing lines handle mill-scale timber bucking and dimensional cutting.
- Multi-Function:Modular power heads accepting chainsaw, circular saw, and core drill attachments are gaining traction in urban search-and-rescue standardization.
Heavy-Duty handles the majority of throughput; Multi-Function is climbing the fastest on share.
End User:
Customer type determines whether procurement flows through rental channels, municipal specification, or direct OEM negotiation.
- Emergency Services:Urban search-and-rescue teams and technical rescue units mandate hydraulic extrication toolsets under NFPA and equivalent standards. These agencies prioritize interoperability with existing power units over standalone performance metrics.
- Forestry:Professional timber harvesting contractors operating in Germany and the Pacific Northwest drive premium hydraulic specification where emission regulations constrain combustion alternatives.
- Construction:Demolition contractors cutting reinforced concrete and structural steel specify diamond-chain systems for extended wear resistance.
- Landscaping:Maintenance-scale operators are migrating toward battery-powered alternatives where duty cycles remain below hydraulic break-even thresholds.
Forestry commands the widest installed base; Emergency Services is expanding most quickly on specification mandates.
Technology:
Power source selection hinges on emission exposure, ignition risk, and tethering constraints rather than raw cutting speed.
- Hydraulic:External power unit dependency delivers continuous torque without combustion exhaust, dominating underwater cutting and confined-space demolition where ignition barriers exclude alternatives.
- Battery-Powered:Lithium-ion systems are displacing entry hydraulic units in landscaping and light maintenance, though torque limitations exclude primary timber processing.
- Electric:Corded configurations serve fixed industrial installations with reliable grid access.
- Pneumatic:Compressed-air systems retain niche positions in explosive atmosphere zones where hydraulic fluid leaks pose contamination risks.
Hydraulic retains dominance in heavy-cycle applications; Battery-Powered is gaining share fastest in sub-professional segments.
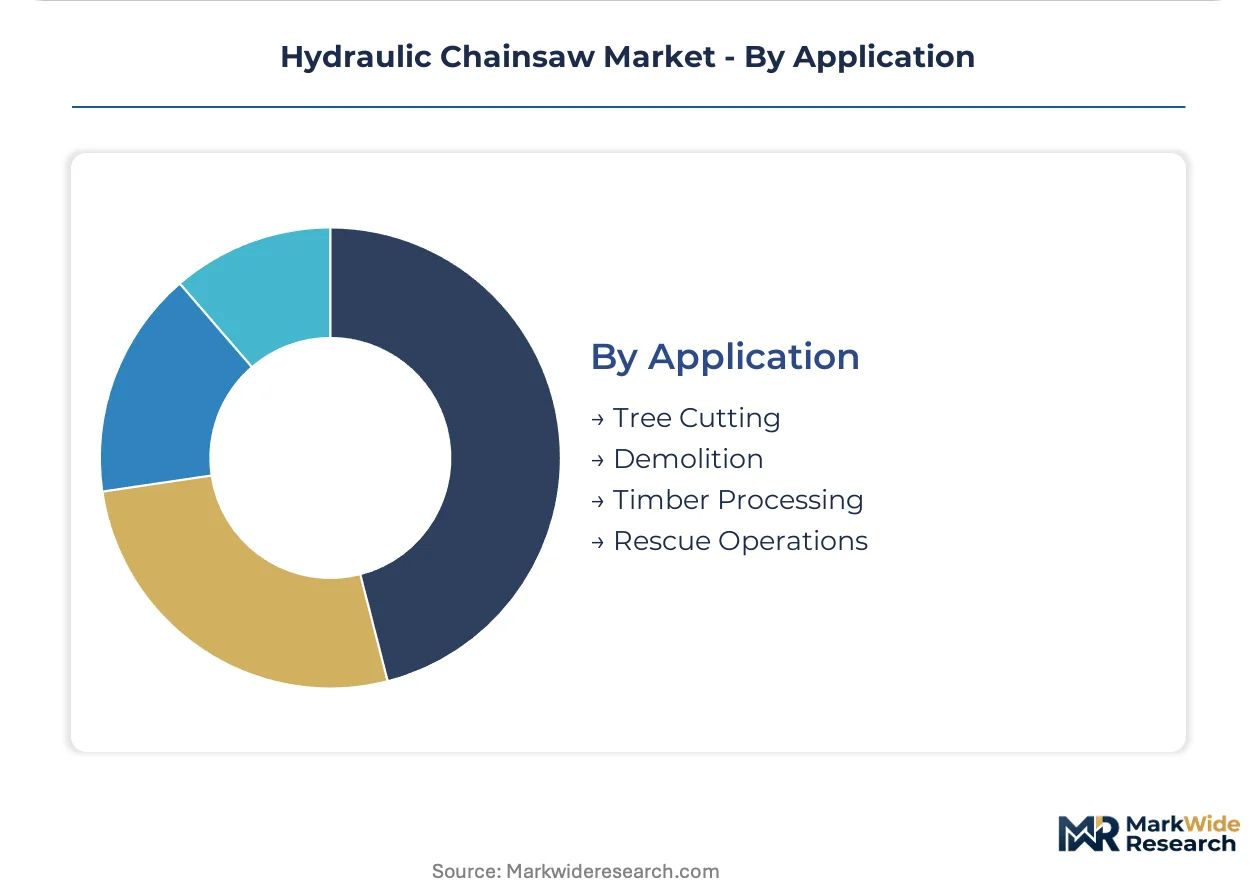
Application:
Use case dictates bar length, chain type, and safety certification requirements.
- Demolition:Diamond-embedded chains and specialized guide bar materials handle reinforced concrete, masonry, and structural steel cutting where abrasive wear destroys standard chains within hours.
- Rescue Operations:Vehicle extrication and structural collapse response demand rapid deployment with kickback protection meeting OSHA chain brake standards.
- Timber Processing:Sawmill bucking and dimensional cutting favor stationary hydraulic heads integrated into processing lines.
- Tree Cutting:Arborist and utility clearance work is fragmenting between hydraulic systems for large-diameter felling and battery alternatives for limb maintenance.
Demolition generates the highest consumables revenue per machine hour; Rescue Operations is the steepest expansion trajectory on urban emergency preparedness budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in hydraulic chainsaw equipment tilt toward manufacturing surplus in Germany and Japan against raw timber economies in Canada and Brazil. Equipment leasing networks in the Pacific Northwest now source premium units from German fabricators. Precision harvesting requirements in Bavaria sustain outbound shipment volumes to North American forestry contractors.
United States
OSHA chain brake certification mandates drive specification upgrades across commercial logging fleets. The EPA small-engine emission rules redirect procurement toward hydraulic systems in California and Washington State. Pacific Northwest equipment lessors aggregate demand for mid-sized contractors avoiding capital purchases.
Germany
Selective felling regulations under the EU Machinery Directive sustain premium hydraulic tool demand in precision timber operations. REACH compliance adds material traceability burdens for hydraulic fluid formulations. Bavarian forestry equipment clusters around Munich and Nuremberg export certified systems to Austrian and Swiss operators.
Canada
Health Canada workplace safety standards align with provincial logging regulations in British Columbia and Alberta. Federal wildfire mitigation budgets redirect municipal procurement toward emergency services hydraulic extrication kits. Vancouver Island contractors lease German-built heavy-duty units for coastal old-growth harvesting.
Japan
METI industrial equipment standards govern hydraulic system certification for domestic and export markets. Domestic timber harvesting constraints concentrate demand in marine salvage and nuclear decommissioning applications. Osaka-based fabricators supply underwater cutting systems to Southeast Asian offshore operators.
Brazil
ANVISA industrial safety protocols shape equipment import requirements for Amazon basin logging concessions. Federal environmental licensing delays constrain formal sector equipment deployment. São Paulo equipment distributors serve demolition contractors cutting reinforced concrete in urban renewal zones.
Hydraulic Chainsaw Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the hydraulic chainsaw competitive structure. The vendor base splits between diversified industrial tool conglomerates and focused cutting equipment fabricators. Three archetypes dominate: infrastructure rental partners, diamond-chain system producers, and hazardous-environment specialists. Consolidation pressure runs through rental channel expansion; differentiation concentrates on fluid compatibility documentation and aftermarket service unbundling.
Among the named fabricators, TOOLGAL exemplifies the component-integrated archetype through captive diamond-chain production. CS Unitec occupies the hazardous-environment specialist position serving marine and nuclear decommissioning applications. STANLEY represents the diversified industrial platform leveraging rental infrastructure partnerships for North American channel access. These three anchors illustrate how competitive positioning fragments across equipment integration depth rather than geographic coverage alone.
| Leading Market Players |
|---|
| USSaws |
| TOOLGAL |
| PAWACKER |
| Spitznas Maschinenfabrik GmbH |
| Maruzen Kogyo |
| STANLEY |
| CS Unitec |
| Weiping |
| Zondar |
| Others |
Supply & Pricing Matrix
Single-source dependency on German precision hydraulic motor fabricators determines both premium-to-economy pricing spreads and the geographic clustering of certified supply chains. Equipment OEMs face extended qualification timelines when diversifying beyond Bavarian and Stuttgart production hubs, compressing margin flexibility for mid-tier competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on CE certification grade and aftermarket service bundling, with fully warranted heavy-duty configurations commanding substantial premiums over bare-tool portable units. Cost compression in the economy tier intensifies because battery-powered alternatives capture landscaping maintenance volumes. Municipal emergency services procurement teams exhibit the lowest price sensitivity due to NFPA interoperability mandates, while Pacific Northwest leasing aggregators drive hard volume negotiations.
Supply Chain Analysis
Export control regimes on high-pressure hydraulic seal technologies limit component flows from Japanese and German fabricators to non-certified assemblers. Manufacturing concentrates in Germany, Japan, and the United States, with specialized diamond-chain production drawing from Israeli and Belgian superabrasive suppliers. Single-source vulnerability concentrates in precision-machined motor housings from Stuttgart-area machine shops. Distribution runs through infrastructure equipment lessors and authorized dealer networks, with rental channel consolidation fragmenting traditional OEM-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rental channel consolidation among Pacific Northwest equipment lessors has shifted procurement leverage toward volume aggregators, compressing traditional distributor margins and forcing OEMs to restructure channel economics.
For Market Incumbents: Insulate premium positioning through captive diamond-chain production and REACH-compliant fluid certification programs. Battery-powered substitution in landscaping maintenance threatens entry-hydraulic volumes; backward integration into superabrasive supply secures demolition segment profitability. Channel control through exclusive rental partnerships in Germany and Washington State defends against price-led competition. For New Entrants and Emerging Players: Build out underwater cutting specialization for marine salvage and nuclear decommissioning contracts where ignition barriers exclude combustion alternatives. The most penetrable white-space sits in Southeast Asian offshore decommissioning, served by Osaka-based fabricators but underserved by Western competitors. A certification-first go-to-market angle targeting METI and EU Machinery Directive alignment accelerates market access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component-integrated specialists over pure-play distributors. Long-term viability across the next decade hinges on fluid compatibility documentation capabilities and aftermarket service network density. Acquisition targets should display captive diamond-chain or high-pressure seal production. The signal to watch is municipal wildfire mitigation budget redirection between emergency services and forestry agencies.| Strategic Initiative | Industry Significance |
|---|---|
| Diamond-Chain Production Integration | Captive superabrasive supply secures demolition segment margins against consumables price volatility. |
| REACH Fluid Certification Program | Pre-approved hydraulic fluid documentation simplifies German and Austrian contractor audit compliance. |
| Underwater Cutting System Development | Marine salvage contracts from Southeast Asian offshore operators bypass competitive forestry saturation. |
| Rental Channel Partnership Expansion | Pacific Northwest equipment lessors aggregate mid-sized contractor demand outside traditional dealer networks. |
| Multi-Function Power Head Platform | Urban search-and-rescue standardization creates specification lock-in through NFPA interoperability requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment manufacturer filings, and EU Machinery Directive certification databases. Interviews with maintenance directors at Pacific Northwest forestry contractors, OEM procurement teams in Bavaria, and aftermarket service heads in North American rental channels informed demand-side assumptions. Bottom-up unit shipment estimates triangulate against top-down revenue aggregation across product type and end-user segments.
Forecast inputs include hydraulic power unit deployment rates, EPA small-engine emission rule stringency trajectories, and municipal emergency services budget allocations. The analytical framework models product type, end user, technology, and application dimensions across the projection horizon. CAGRs derive from segment-level volume growth and average selling price evolution. Industry-specific inputs incorporate REACH compliance timeline extensions and diamond-chain replacement cycle compression.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by battery-powered chainsaw manufacturers would shift outcomes. Material shifts in OSHA chain brake certification timelines or EU Machinery Directive enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market