
 North America Architectural Coatings Market | 2026-2036
North America Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Architectural Coatings Market Analytics
Midwestern alkyd resin production is rebalancing after feedstock volatility disrupted supply schedules through late 2024. PPG Industries sustains broad distribution across big-box retail and pro-paint channels. The Sherwin-Williams Company dominates the contractor-direct segment with company-owned store density. RPM International anchors its position through specialty niche brands with concentrated industrial overlap.
Architectural coatings are liquid or powder formulations applied to building substrates for protection, decoration, or both, typically comprising binders, pigments, solvents or water carriers, and functional additives at solids contents ranging from 30% to 60% by volume. Waterborne acrylic technology leads volume share due to VOC compliance flexibility and application ease across temperature ranges. Interior paint competes on scrub-cycle durability and low-odor certification, while exterior paint margins concentrate in elastomeric and self-cleaning formulations. New construction demand tracks housing starts closely, but renovation application offers steadier cash flow through economic cycles.
The EPA regulates volatile organic compound content under 40 CFR Part 59, pushing manufacturers toward waterborne and zero-VOC formulations. California's South Coast Air Quality Management District enforces stricter limits than federal baselines, creating a dual-track compliance environment. OSHA's hazard communication standards govern installer safety training and product labeling. Stakeholders must monitor state-level low-VOC rulemaking beyond federal floors, as regional air districts increasingly dictate permissible chemistries.
Market Dynamics
The EPA's Lead Renovation, Repair and Painting Rule is compressing contractor certification timelines while accelerating waterborne formulation substitution across the United States and Canada. This regulatory pressure is restructuring distribution relationships and reformulation priorities simultaneously.
Growth Catalysts
- Sun Belt Migration:Population inflow into Texas, Florida, and Arizona is generating sustained new housing starts and exterior coating demand that outpaces national renovation cycles.
- 40 CFR Part 59:Federal VOC ceilings are forcing solventborne alkyd displacement and expanding qualified waterborne acrylic capacity across manufacturer portfolios.
- Elastomeric Formulations:Self-cleaning and crack-bridging exterior technologies are capturing premium renovation spending in hurricane-prone coastal counties.
Market Restraints
- Midwestern Feedstock Volatility:Propylene and acrylic acid supply disruptions through late 2024 have compressed alkyd resin production margins and extended lead times for solventborne specialty lines.
- California SCAQMD Divergence:South Coast Air Quality Management District rules run stricter than federal baselines, forcing dual-track inventory and compliance cost duplication for national distributors.
- DIY Channel Erosion:Big-box retail paint volume is losing ground to contractor-direct procurement as homeowner renovation frequency moderates post-pandemic.
Strategic Opportunities
- Canadian Low-VOC Acceleration:Health Canada and provincial regulators are tightening architectural coating limits, creating first-mover advantage for EPA-compliant US formulations with zero-VOC certification.
- Energy-Efficient Exterior Upgrades:Cool roof and solar-reflective wall coating specifications are penetrating municipal building codes in Texas and Arizona ahead of federal mandate.
- Pro-Paint Channel Consolidation:Independent distributor networks are accepting exclusive supply arrangements with manufacturers offering certified installer training and inventory financing.
Industry Challenges
- EPA RRP Certification Bottleneck:Contractor training capacity constraints are extending project start timelines and forcing smaller painting operations into informal labor arrangements.
- Legacy Solventborne Equipment Stranding:Capital invested in high-pressure airless systems for oil-based formulations faces accelerated obsolescence as waterborne viscosity requirements diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Architectural Coatings Market |
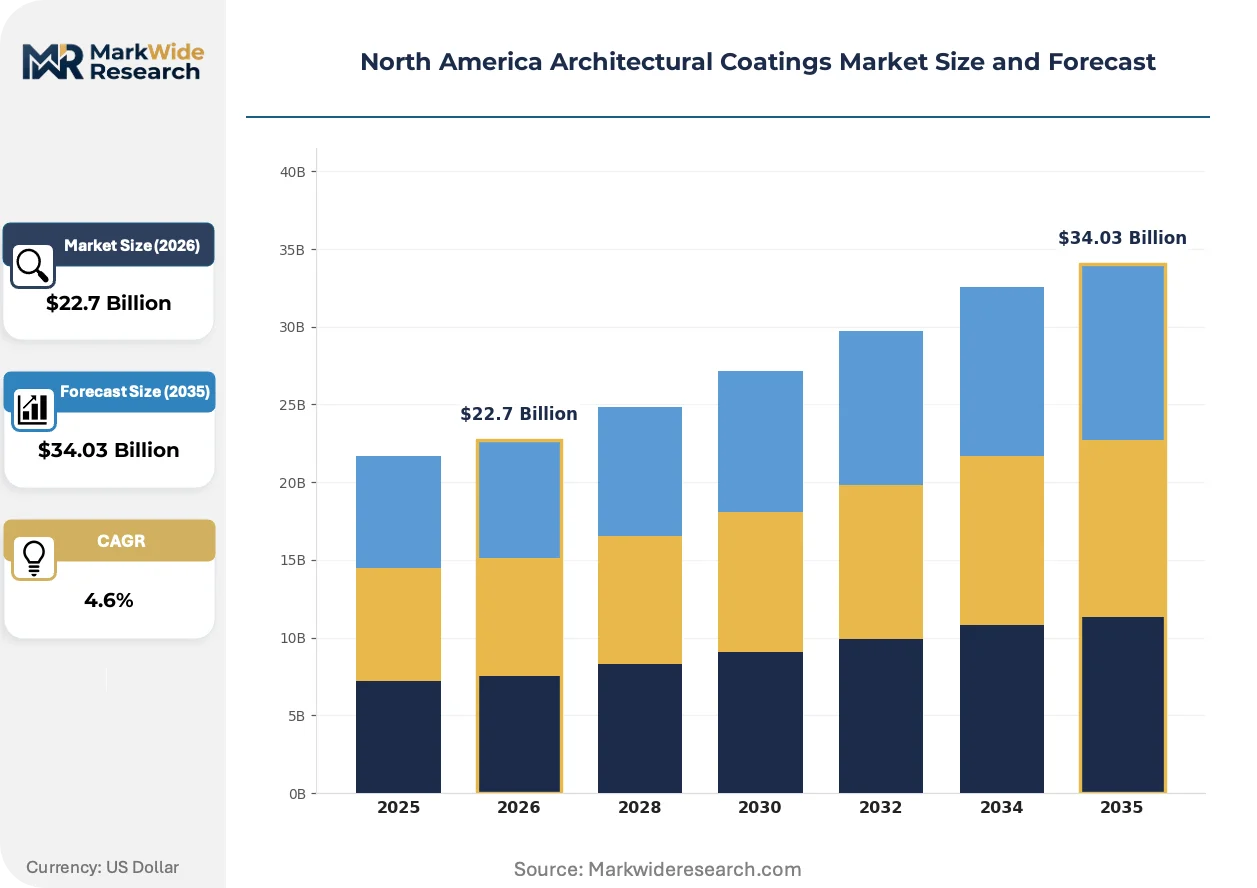
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $34.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior Paint, Interior Paint, Primers, Stains Technology: Acrylic, Alkyd, Waterborne, Solvent-Based End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Public Infrastructure Application: New Construction, Renovation, Maintenance, Decorative |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., RPM International Inc., Masco Corporation, Benjamin Moore & Co., Axalta Coating Systems, Akzo Nobel N.V., BASF SE, Valspar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Architectural Coatings Market Evolving Landscape
Waterborne acrylic technology is compressing formulation diversity while expanding application temperature windows. Regulatory pressure and performance convergence are eliminating marginal chemistries and reshaping R&D allocation.
Self-cleaning photocatalytic titanium dioxide is consolidating exterior premium positioning. Large multifamily developers in Florida and Texas are specifying these formulations for facade maintenance cost reduction. The technology is consolidating mid-tier elastomeric share by bundling aesthetic durability with HVAC load reduction claims.
California's SCAQMD Rule 1113 amendments are extending VOC restrictions to specialty coatings previously exempt under federal floors. Manufacturers serving the Los Angeles Basin must maintain separate inventory SKUs or reformulate nationally to the stricter standard. The contractor-direct segment is absorbing compliance cost through price escalation rather than SKU proliferation.
Certification-driven contractor selection is displacing brand-loyal homeowner purchasing. Property management firms in Arizona and Nevada are pre-qualifying painters based on EPA RRP documentation and manufacturer warranty eligibility. This shift concentrates volume with certified installers and weakens retail brand equity as a selection criterion.
North America Architectural Coatings Market Segmentation
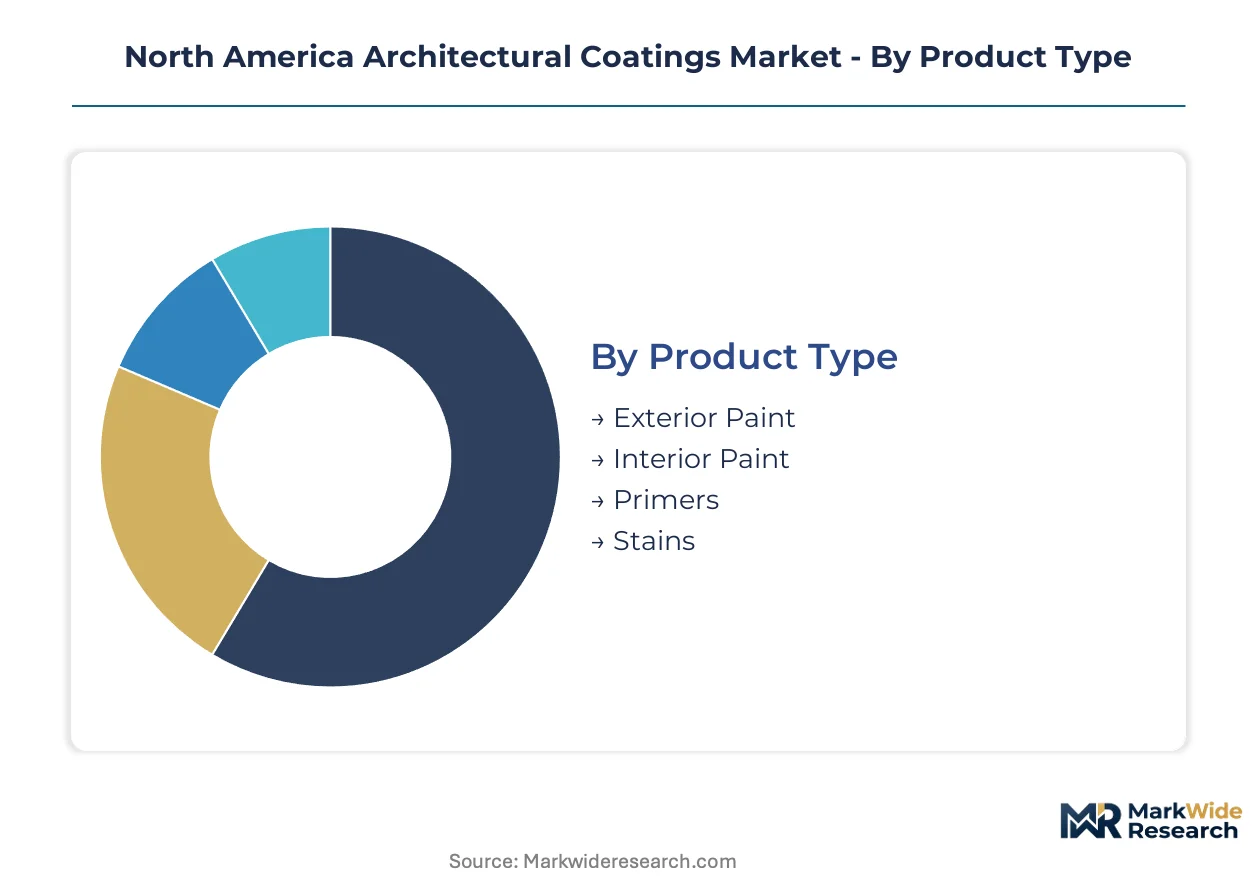
Architectural coatings buyers prioritize performance specifications that align with substrate conditions, regulatory compliance, and labor economics. Segmentation reveals how formulation choices cascade through contractor certification requirements, inventory financing structures, and warranty eligibility. The report examines four dimensions that collectively determine procurement patterns across the United States and Canada.
Product Type:
Buyer decisions hinge on substrate exposure severity and recoating frequency, with exterior durability commanding premium formulation investment.
- Exterior Paint:Elastomeric acrylic formulations with crack-bridging capabilities dominate hurricane-prone coastal counties in Florida and Texas. Cool-pigment technologies specified under Arizona and Nevada municipal codes are displacing conventional white coatings in multifamily developments. Sun Belt migration sustains volume concentration here.
- Interior Paint:Low-odor zero-VOC acrylics lead specification for occupied renovation work under EPA RRP compliance timelines. Scrub-cycle durability ratings above 5,000 cycles differentiate premium grades in commercial property management procurement. Demand concentrates in urban renovation corridors with tenant turnover pressure.
- Primers:Stain-blocking acrylic formulations anchor warranty eligibility for contractor-direct programs across Sherwin-Williams and PPG distribution networks.
- Stains:Waterborne alkyd hybrids capture exterior wood deck maintenance spending in Pacific Northwest and Northeast climate zones with moisture exposure cycles.
Exterior paint leads on scale; interior paint leads on momentum as renovation frequency stabilizes post-pandemic.
Technology:
Regulatory ceiling compression under 40 CFR Part 59 and California SCAQMD Rule 1113 is eliminating solventborne capacity from national portfolios.
- Acrylic:Waterborne emulsion polymers with glass transition temperatures optimized for -10°C to 40°C application windows dominate contractor specifications. Texas and Arizona exterior projects specify 100% acrylic binders for UV resistance and chalking resistance over 10-year warranty periods. The technology captures premium positioning through elastomeric and self-cleaning extensions.
- Alkyd:Solventborne formulations retain niche in industrial maintenance and specialty trim applications where hardness and block resistance outweigh VOC compliance costs. Midwestern propylene feedstock volatility through late 2024 compressed margins and extended lead times for remaining production capacity.
- Waterborne:Low-VOC acrylic and urethane hybrids are displacing solventborne alkyd in commercial metal cladding specifications across Ontario and British Columbia under Health Canada tightening.
- Solvent-Based:High-solids alkyd and epoxy formulations concentrate in industrial facilities with chemical exposure requirements exempt from residential VOC ceilings.
Waterborne technology climbs the fastest on regulatory displacement; acrylic maintains the steepest expansion trajectory on performance convergence.
End User:
Procurement authority fragmentation distinguishes residential renovation from commercial specification-driven purchasing.
- Residential Buildings:Single-family renovation dominates volume through contractor-direct channels with EPA RRP certification requirements. Property management firms in Arizona and Nevada pre-qualify installers based on documentation compliance, concentrating volume with certified operations.
- Commercial Buildings:Multifamily developers in Texas and Florida specify photocatalytic self-cleaning formulations for facade maintenance cost reduction. Cool roof and solar-reflective wall coatings penetrate municipal building codes ahead of federal mandate.
- Industrial Facilities:Chemical resistance and abrasion specifications sustain solventborne epoxy demand in maintenance applications exempt from residential VOC rules.
- Public Infrastructure:Federal and state procurement specifications under Buy American provisions favor domestic manufacturing capacity for bridge and highway coating programs.
Residential buildings anchor volume concentration; commercial buildings gain share fastest on Sun Belt construction intensity.
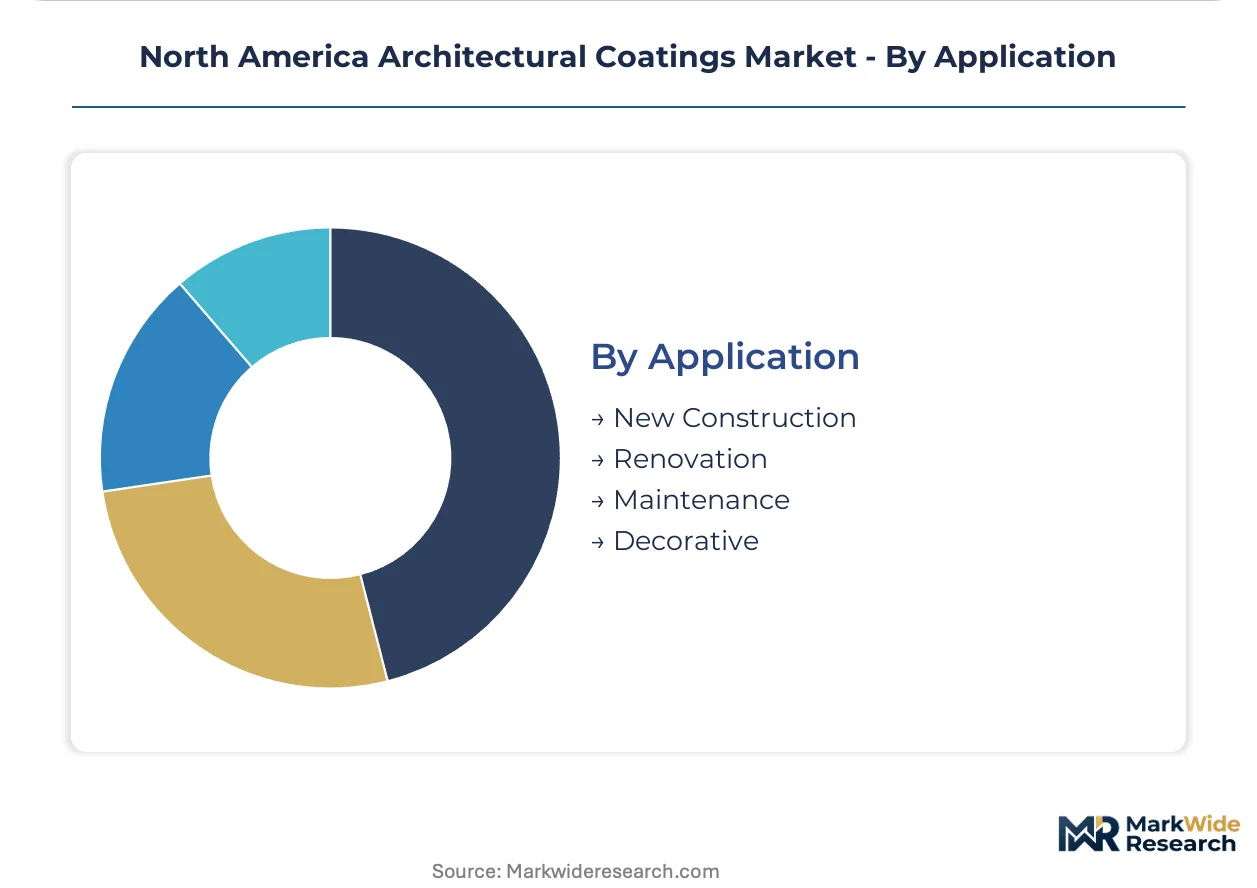
Application:
Demand cyclicality separates new construction volatility from renovation cash flow stability.
- New Construction:Housing starts in Texas, Florida, and Arizona outpace national averages on population migration, concentrating exterior coating demand in Sun Belt metropolitan statistical areas.
- Renovation:Energy-efficient exterior upgrade specifications for cool roof and solar-reflective wall coatings generate steadier procurement through economic cycles than ground-up construction.
- Maintenance:Industrial facility recoating schedules tied to asset life cycles sustain solventborne specialty demand outside residential regulatory scope.
- Decorative:Faux finish and specialty effect coatings concentrate in high-end residential segments with designer-specified aesthetic requirements.
Renovation application leads on margin stability; new construction leads on volume amplitude through housing cycle peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between federal and state-level VOC ceilings is redistributing production capacity toward jurisdictions with compliance cost advantages. Manufacturers are consolidating waterborne formulation assets in states with stable regulatory baselines while maintaining solventborne specialty capacity in exempt industrial zones.
United States
Sun Belt migration into Texas, Florida, and Arizona sustains exterior coating demand above national renovation averages. EPA's 40 CFR Part 59 and the Lead Renovation, Repair and Painting Rule compress contractor certification timelines and accelerate waterborne substitution. Houston and Dallas-Fort Worth metropolitan areas concentrate new housing starts and pro-paint channel distribution density.
Canada
Health Canada and provincial regulators are tightening architectural coating VOC limits ahead of US federal baselines, creating first-mover advantage for zero-VOC certified formulations. Ontario and British Columbia lead specification adoption for low-VOC acrylic and urethane hybrids in commercial metal cladding. Toronto and Vancouver anchor distributor consolidation toward EPA-compliant US suppliers.
Mexico
Nearshoring of manufacturing capacity is expanding industrial maintenance coating demand in Nuevo León and Baja California. Mexican environmental regulations under SEMARNAT lag US EPA ceilings, sustaining solventborne alkyd consumption in cross-border production facilities. Monterrey and Tijuana industrial corridors concentrate automotive and appliance OEM coating specifications.
California
South Coast Air Quality Management District Rule 1113 amendments enforce VOC restrictions stricter than federal floors, forcing dual-track inventory management. Los Angeles Basin contractors absorb compliance costs through price escalation rather than SKU proliferation. San Diego and Orange County multifamily developers specify photocatalytic self-cleaning formulations for facade maintenance reduction.
Southwest Region
Arizona and Nevada municipal codes are incorporating cool roof and solar-reflective wall coating specifications ahead of federal mandate. Phoenix and Las Vegas property management firms pre-qualify painters based on EPA RRP documentation, concentrating volume with certified installer networks. Energy-efficient exterior upgrade specifications generate steadier procurement through economic cycles than ground-up construction.
North America Architectural Coatings Market Competitive Landscape
United States producers anchor the contractor-direct tier; Canadian and Mexican specialists hold regional distribution niches. The market structure concentrates around three to four integrated manufacturers with company-owned store networks, while specialty players occupy industrial maintenance and niche formulation segments. Strategic archetypes include full-line waterborne specialists, solventborne niche retainers, and pro-channel integrators with certification training infrastructure. Competitive moves center on exclusive distributor arrangements with inventory financing terms and certified installer program expansion.
Among US-based integrated manufacturers, The Sherwin-Williams Company, PPG Industries, and RPM International exemplify contrasting channel strategies. The Sherwin-Williams Company occupies a position emphasizing company-owned store density and contractor-direct relationships. PPG Industries represents the big-box retail and pro-paint dual-channel archetype. RPM International anchors the specialty niche brand portfolio with concentrated industrial overlap. These three structures illustrate how scale, channel control, and segment focus differentiate competitive positioning without requiring identical resource allocation.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| RPM International Inc. |
| Masco Corporation |
| Benjamin Moore & Co. |
| Axalta Coating Systems |
| Akzo Nobel N.V. |
| BASF SE |
| Valspar Corporation |
| Others |
Value Network & Pricing Analysis
Captive resin production by integrated manufacturers anchors supply position and pricing power across the North American architectural coatings landscape. Sherwin-Williams and PPG Industries control acrylic emulsion polymer capacity in-house, insulating margin structures from Midwestern propylene feedstock volatility that disrupted independent alkyd suppliers through late 2024.
Pricing Analysis
Distributor margin compression runs through the pro-paint channel as contractor-direct procurement displaces big-box retail volume. Three-tier pricing structure across premium elastomeric, standard acrylic, and economy vinyl-acrylic levels stratifies by scrub-cycle durability and VOC certification grade. Pricing pressure stems from EPA RRP compliance cost absorption rather than raw material deflation. Residential renovation contractors exhibit highest price sensitivity; multifamily developers in Texas and Florida show lowest sensitivity due to lifecycle cost framing.
Supply Chain Analysis
Single-source vulnerability sits with Midwestern propylene derivative production for solventborne alkyd resins. Acrylic acid and titanium dioxide feedstocks draw from US Gulf Coast petrochemical complexes, Chinese pigment processing, and Canadian specialty chemical intermediates. Tariff exposure on Chinese titanium dioxide concentrates risk in photocatalytic self-cleaning formulations. Distribution runs through company-owned store networks for contractor-direct volume, with independent distributors handling commercial specification projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America architectural coatings market functions as a geographic-arbitrage play between EPA-compliant US formulations and tightening Canadian provincial standards, with Health Canada VOC limits running ahead of federal baselines and creating first-mover rent for zero-VOC certified suppliers.
For Market Incumbents: Hedge against California SCAQMD Rule 1113 divergence by reformulating nationally to stricter standards rather than maintaining dual-track SKUs. Channel control through certified installer programs represents the priority lever against independent distributor consolidation. Backward integration into acrylic emulsion polymer capacity insulates margin structures from propylene feedstock volatility. For New Entrants and Emerging Players: Specialty wood coating contractors in the Pacific Northwest represent an underserved buyer archetype with moisture-exposure specification needs unmet by national waterborne portfolios. Health Canada-compliant zero-VOC formulations for Ontario commercial metal cladding offer the most penetrable regulatory entry point. A go-to-market angle anchored through regional distributor exclusive supply arrangements with inventory financing terms bypasses incumbent company-owned store density. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA RRP certification bottlenecks strand smaller painting operations and concentrate volume with scaled installer networks. The five-to-ten year viability window favors manufacturers with captive resin production and pro-channel certification infrastructure. Acquisition target archetypes include regional waterborne specialists with Health Canada registration and independent distributors with contractor financing capabilities. The signal to watch is municipal cool roof code adoption velocity in Arizona and Nevada as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Capacity | Captive resin production insulates margins from Midwestern propylene volatility. |
| Health Canada Zero-VOC Certification Investment | First-mover positioning captures Ontario and British Columbia specification demand. |
| Certified Installer Program Expansion | EPA RRP documentation requirements concentrate volume with trained contractor networks. |
| Independent Distributor Exclusive Arrangements | Inventory financing terms secure shelf space against incumbent company-owned stores. |
| Photocatalytic Self-Cleaning Formulation Development | Titanium dioxide bundling captures Florida and Texas multifamily facade specifications. |
Research Methodology
Multiple input streams — primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors; secondary validation through customs and trade data, American Coatings Association reports, and SEC 10-K filings; and bottom-up and top-down triangulation — were reconciled to construct market estimates. Primary fieldwork captured formulation specification trends, inventory financing structures, and contractor certification program economics across the United States and Canada.
Data-stream reconciliation anchored volume and value outputs across product type, technology, end user, and application dimensions over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs incorporated housing starts correlation, EPA regulatory timeline assumptions, and propylene feedstock price elasticity parameters specific to acrylic emulsion polymer production economics.
Underlying measurement precision varies by segment; waterborne acrylic and contractor-direct channels carry tighter precision than solventborne specialty and DIY retail. Forecasts reflect documented assumptions about regulatory enforcement intensity and migration-driven housing demand. Raw material price volatility and state-level VOC rulemaking acceleration represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Construction Ornamental Stone Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Foam Bricks Market
Building Materials
Geocells Market
Building Materials
Natural Stone Slab Market
Building Materials
Global Pozzolan Market
Building Materials
Plaster Accelerator Market
Building Materials
Europe Cement Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Concrete Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Recycled Construction Aggregates Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Pre-Fabricated Glass Block Market