
 Global White Cement Market | 2026-2036
Global White Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Global White Cement Market Foresight
The EU Green Deal is restructuring material selection protocols across European construction, compelling architects and contractors to specify low-clinker white cement variants for facade and decorative applications. Cementir Holding leverages its Danish kiln assets to sustain premium-grade output for Nordic restoration projects. Çimsa Çimento Sanayi anchors Turkey's export position through specialized maritime logistics to Mediterranean markets. JK Cement dominates India's northern belt with captive limestone reserves optimized for high-whiteness clinker production.
White cement is a hydraulic binder manufactured from iron-free limestone and kaolin clay, fired at controlled temperatures to achieve reflectance values exceeding 80 percent on the L-scale, primarily specified where aesthetic finish and color consistency override structural load requirements. Hydraulic white cement leads volume flows due to its versatility across architectural concrete and precast elements, while sulfate resistant cement commands margin premiums in coastal and chemically exposed environments. Dry process manufacturing concentrates capacity among large-scale operators, whereas wet process lines persist where raw material moisture or legacy infrastructure limits conversion economics.
EMA's construction product standards, India's BIS certification mandates, and China's GB building material codes collectively enforce whiteness thresholds and compressive strength minimums that filter subscale producers from specification channels. REACH compliance in Europe and India's PLI scheme for building materials are tightening entry barriers while redirecting investment toward kiln efficiency upgrades. Stakeholders must monitor regulatory divergence between carbon border mechanisms and domestic content incentives as these frameworks reshape competitive access across major demand centers.
Market Dynamics
EU Green Deal embodied carbon benchmarks are restructuring procurement protocols across European construction, compelling specification-grade white cement adoption for facade and decorative applications where aesthetic performance overrides structural load requirements.
Growth Catalysts
- EU Green Deal Carbon Benchmarks:Embodied carbon thresholds in European construction procurement are mandating low-clinker white cement variants for premium facade applications.
- India Infrastructure Monument Specification:Landmark urban developments and heritage restoration projects in India specify high-whiteness clinker for aesthetic consistency.
- Decorative Plaster Uptake:Luxury residential and commercial facade segments are driving specification-grade demand for architectural finish consistency.
Market Restraints
- Iron-Free Limestone Scarcity:Captive reserves of high-purity raw material concentrate in select geographies, constraining new entrant supply security.
- Kiln Energy Intensity:Controlled firing temperatures for L-scale reflectance above 80 percent impose fuel cost volatility exposure on producers.
- Portland Grey Substitution:Standard grey cement with surface coatings competes on cost for non-structural decorative applications.
Strategic Opportunities
- India PLI Scheme for Building Materials:Domestic content incentives are redirecting investment toward kiln efficiency upgrades and captive limestone development.
- Sulfate Resistant Coastal Applications:Chemically exposed environments in Mediterranean maritime construction command margin premiums for specialized formulations.
- Nordic Restoration Project Pipelines:Heritage conservation mandates in Denmark, Sweden, and Norway sustain premium-grade output requirements.
Industry Challenges
- REACH Compliance Complexity:European chemical registration timelines extend certification cycles for imported clinker additives and processing aids.
- Dry Process Conversion Economics:Legacy wet process lines face stranded asset risk where raw material moisture or infrastructure limits kiln modernization.
- Whiteness Consistency Control:Batch-to-batch L-scale reflectance variation requires skilled kiln operation and quality assurance functions in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global White Cement Market |
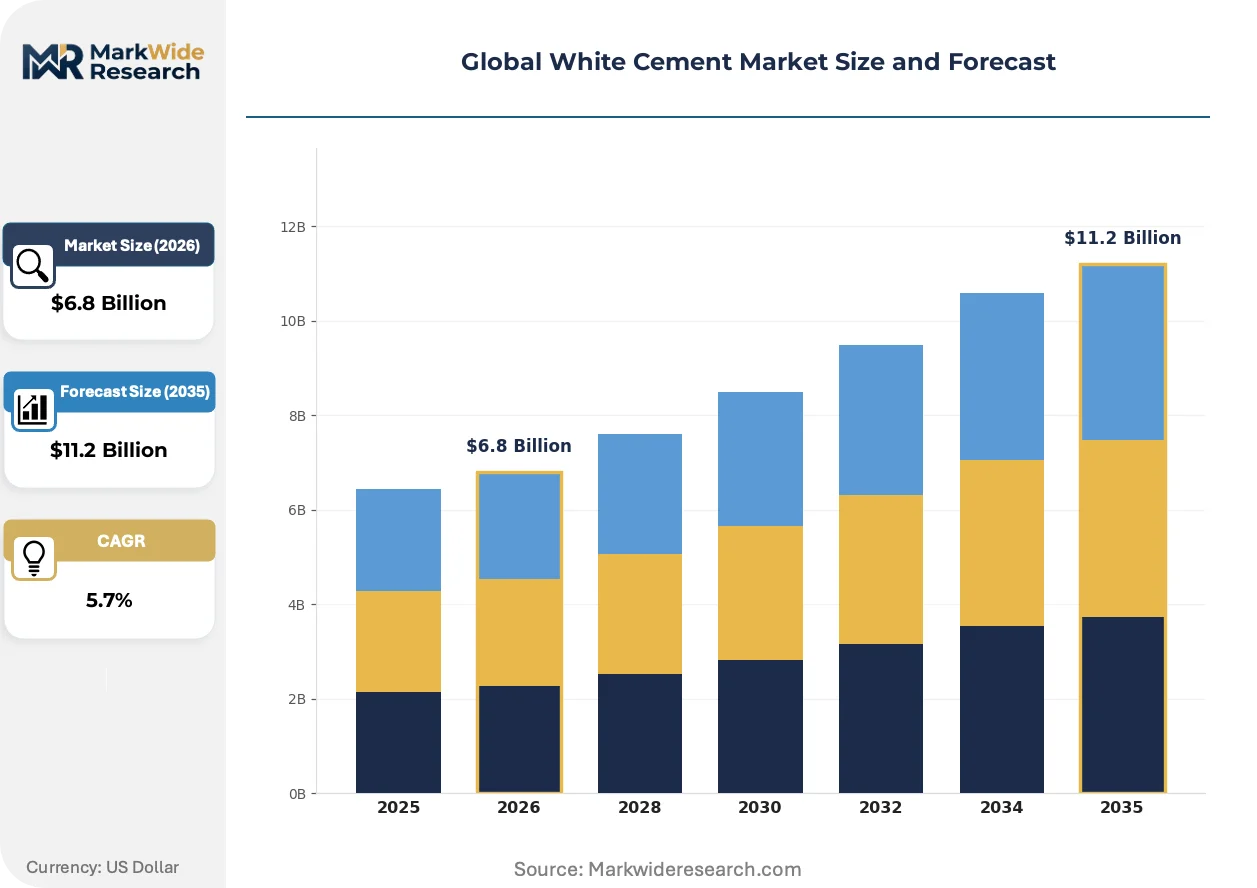
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic White Cement, Oil Well White Cement, Special White Cement, Sulfate Resistant Cement Application: Architectural Concrete, Decorative Plaster, Tile Grouting, Waterproofing Compounds, Flooring, Precast Concrete Production Process: Wet Process, Dry Process, Semi-Dry Process, Rotary Kiln Process End User: Construction Contractors, Precast Manufacturers, Infrastructure Developers, Industrial Fabricators |
| Companies Covered | Cementir Holding, JK Cement, Çimsa Çimento Sanayi, Cemex, Aalborg Portland, UltraTech Cement, Heidelberg Materials, Federal White Cement, Adana Çimento Sanayii, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global White Cement Market Shifts & Advancements
Carbon accounting integration is reshaping material specification workflows, with digital traceability systems now standard for embodied carbon verification in premium construction procurement channels.
Calcined clay activation technology is integrating with white cement production to reduce clinker factors while maintaining L-scale reflectance thresholds. Nordic producers are adopting these hybrid binders for restoration projects with strict heritage compliance requirements. The structural consequence is compressing carbon intensity benchmarks without sacrificing aesthetic performance specifications.
REACH authorization procedures for chromium VI reduction are tightening formulation standards across European decorative applications. Manufacturers are reformulating grinding aids and processing additives to maintain workability while eliminating restricted substances. Wet cast precast elements and architectural concrete segments face the steepest compliance timelines and are accelerating alternative additive qualification programs.
Architects and contractors are consolidating specification authority through centralized procurement platforms that enforce certified product databases. Traditional distributor networks face disintermediation pressure as digital tendering systems mandate direct mill certification uploads. This consolidation is most visible in German and French commercial facade projects where general contractors now require batch-level carbon disclosure as a standard contract term.
Global White Cement Market Segmentation
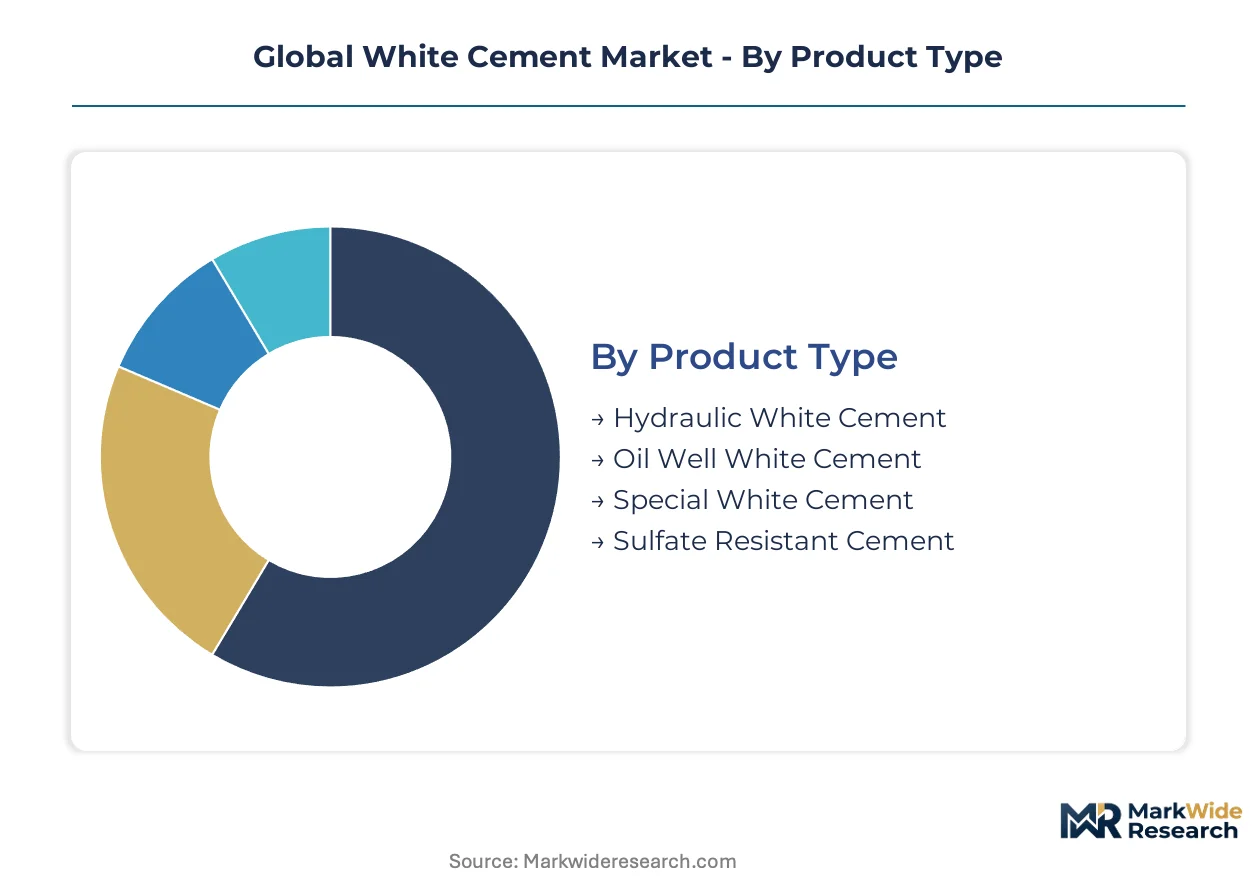
White cement's specification-grade positioning creates distinct value tiers across product formulations, with production process economics and end-user procurement authority determining margin capture. Segmentation reveals where captive raw material advantages convert to pricing power versus commoditized volume plays.
Product Type:
Volume leadership sits with versatile formulations while premium margins concentrate in chemically resistant variants engineered for harsh exposure environments.
- Hydraulic White Cement:Manufactured from iron-free limestone and kaolin clay fired at controlled temperatures to achieve L-scale reflectance above 80 percent. Demand concentrates in India's northern belt where infrastructure developers specify this grade for landmark monuments and premium urban developments requiring aesthetic finish consistency.
- Sulfate Resistant Cement:Formulated with reduced tricalcium aluminate content to withstand chemically aggressive environments. Mediterranean maritime construction commands margin premiums for this specialized formulation, with Turkey's export position anchoring supply through dedicated maritime logistics networks.
- Oil Well White Cement:Engineered for geothermal and oilfield casing applications requiring controlled setting times and high early strength.
- Special White Cement:Custom-blended formulations for heritage restoration and artistic applications where batch-to-batch color matching is critical.
Today's leader: Hydraulic White Cement. Tomorrow's challenger: Sulfate Resistant Cement.
Application:
Facade aesthetics drive specification authority while structural precast applications scale through contractor procurement consolidation.
- Decorative Plaster:Luxury residential and commercial facade segments specify this application for architectural finish consistency. EU Green Deal embodied carbon benchmarks are mandating low-clinker variants for premium European construction procurement.
- Architectural Concrete:Precast elements and cast-in-place structural components requiring color uniformity across large surface areas. Nordic restoration projects in Denmark, Sweden, and Norway sustain premium-grade output requirements through heritage conservation mandates.
- Tile Grouting:Joint filling applications where whiteness matching enhances ceramic and natural stone installations.
- Waterproofing Compounds:Membrane systems and protective coatings for basements, terraces, and submerged structures.
- Flooring:Terrazzo, stamped concrete, and polished cementitious finishes for commercial and institutional interiors.
- Precast Concrete:Factory-cast cladding panels, balustrades, and ornamental elements requiring surface quality control.
Decorative plaster captures current margin premiums; architectural concrete offers the steepest expansion trajectory as digital tendering systems mandate batch-level carbon disclosure.
Production Process:
Energy intensity separates scalable dry process operators from legacy wet process lines facing stranded asset risk.
- Dry Process:Dominates capacity among large-scale operators due to thermal efficiency and clinker quality control. India's PLI scheme for building materials redirects investment toward kiln efficiency upgrades in this process category.
- Wet Process:Persists where raw material moisture or legacy infrastructure limits conversion economics, particularly in regions with high limestone moisture content.
- Semi-Dry Process:Intermediate technology blending wet grinding with dry kiln feeding for specific raw material conditions.
- Rotary Kiln Process:Traditional firing technology with precise temperature control for L-scale reflectance achievement.
Dry process holds installed capacity dominance; semi-dry process gains share fastest where raw material variability constrains full conversion.
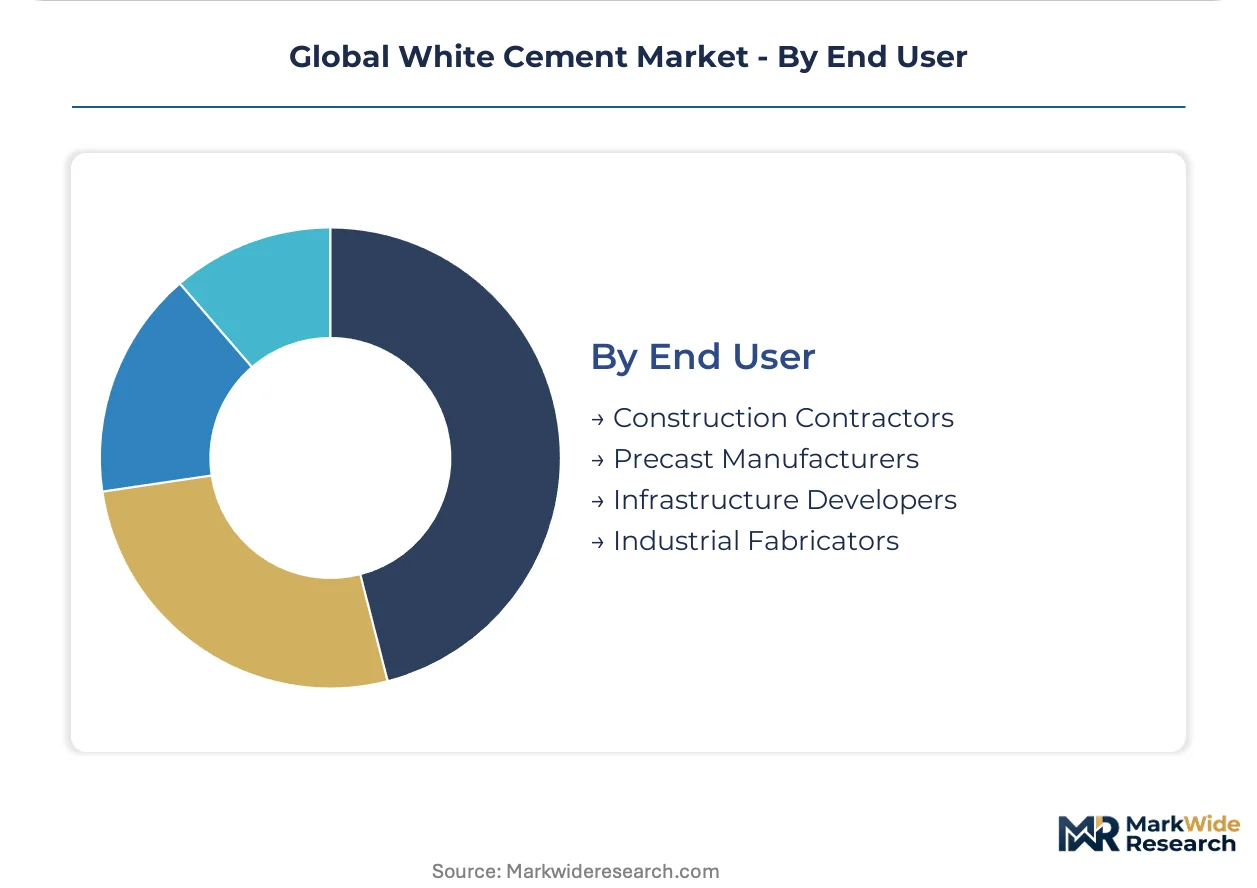
End User:
Procurement authority concentrates with general contractors enforcing certified product databases, disintermediating traditional distributor networks.
- Construction Contractors:German and French commercial facade projects now require batch-level carbon disclosure as standard contract terms, consolidating specification authority through centralized procurement platforms.
- Infrastructure Developers:Indian landmark urban developments specify high-whiteness clinker for aesthetic consistency in monument and premium public space construction.
- Precast Manufacturers:Factory-based producers of standardized elements facing REACH compliance timelines for chromium VI reduction in European decorative applications.
- Industrial Fabricators:Specialized producers of chemical-resistant linings and high-performance mortars for industrial process environments.
Construction contractors control current specification flows; infrastructure developers are gaining procurement leverage through domestic content incentive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
White cement production originated in Denmark during the early twentieth century, with Aalborg Portland pioneering the controlled-firing techniques that established the industry's technical foundation. This Scandinavian heritage continues to influence quality standards across European decorative applications.
Denmark
Heritage restoration mandates in Copenhagen and Aarhus sustain demand for premium-grade white cement with strict L-scale reflectance thresholds. The EU Green Deal's embodied carbon benchmarks compel specification of low-clinker variants in public procurement. Nordic producers leverage legacy kiln assets to supply conservation projects across Scandinavia.
Turkey
Mediterranean maritime construction commands margin premiums for sulfate-resistant formulations in coastal environments. Dedicated maritime logistics networks anchor export supply to North African and Southern European markets. The Izmir industrial corridor concentrates calcined clay activation capacity for hybrid binder production.
India
Landmark monument specifications in Delhi, Jaipur, and Chandigarh drive high-whiteness clinker demand for aesthetic consistency. The PLI scheme for building materials redirects investment toward kiln efficiency upgrades and captive limestone development. Rajasthan's captive reserves dominate northern belt production.
Germany
Commercial facade projects in Berlin and Munich now require batch-level carbon disclosure as standard contract terms. REACH authorization procedures for chromium VI reduction accelerate alternative additive qualification programs. The Rhine-Ruhr industrial region concentrates precast manufacturing facing compliance timelines.
United Arab Emirates
Premium urban developments in Dubai and Abu Dhabi specify white cement for architectural finish consistency in luxury residential towers. The country's national building material codes enforce whiteness thresholds that filter subscale producers. Jebel Ali's logistics infrastructure supports Gulf Cooperation Council re-export flows.
Global White Cement Market Competitive Landscape
Capital-heavy producers compete with asset-light traders across distinct value capture tiers. The vendor base concentrates among integrated cement groups with captive limestone reserves and multi-kiln configurations. Three strategic archetypes dominate: Nordic heritage specialists with restoration-grade capabilities, Mediterranean exporters leveraging maritime logistics, and Indian integrated players with northern belt quarry control. Capacity expansion and calcined clay technology licensing represent the dominant competitive moves reshaping carbon intensity benchmarks.
Within the heritage specialist tier, Aalborg Portland and Cementir Holding occupy positions defined by century-old technical lineage and Danish kiln assets. Among Mediterranean exporters, Çimsa Çimento Sanayi exemplifies the maritime-logistics-dependent archetype serving coastal construction markets. At the scale-driven end, JK Cement anchors the Indian integrated model with captive Rajasthan limestone reserves optimized for high-whiteness output.
| Leading Market Players |
|---|
| Cementir Holding |
| JK Cement |
| Çimsa Çimento Sanayi |
| Cemex |
| Aalborg Portland |
| UltraTech Cement |
| Heidelberg Materials |
| Federal White Cement |
| Adana Çimento Sanayii |
| Others |
Supply & Pricing Matrix
Infrastructure developers in India and general contractors across Germany and France concentrate procurement authority through centralized platforms, anchoring a contract-based long-term offtake model where specification-grade volumes command premiums tied to L-scale reflectance certification.
Pricing Analysis
Three-tier pricing structure across specification-grade, standard architectural, and economy decorative levels stratifies the market, with quality grade and REACH compliance certification tier as primary differentiation drivers. Cost compression in economy tiers is intensifying because grey cement with surface coatings competes aggressively for non-structural applications. Precast manufacturers facing chromium VI reduction timelines exhibit highest price sensitivity, while heritage restoration contractors in Nordic markets demonstrate lowest sensitivity due to irreplaceable aesthetic requirements.
Supply Chain Analysis
India's PLI scheme for building materials and domestic content mandates across European public procurement are reshaping sourcing patterns toward captive limestone development and localized kiln networks. Production gravity centers on India, Turkey, and Denmark, with iron-free limestone, kaolin clay, and calcined clay activators as critical input dependencies. Single-source vulnerability concentrates in Rajasthan's captive reserves for high-whiteness clinker. Distribution runs through project-direct mill certification channels that disintermediate traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global White Cement Market functions as a stable compounder where regulatory carbon benchmarks in European construction procurement generate steady specification-grade demand expansion.
For Market Incumbents: To counter stranded asset risk in legacy wet process lines, Cementir Holding and Aalborg Portland should accelerate calcined clay licensing partnerships for hybrid binder production, while Çimsa Çimento Sanayi expands maritime logistics capacity to defend Mediterranean export corridors against emerging Turkish competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian decorative plaster applications offers the most penetrable white-space target, with sulfate-resistant coastal formulations for Mediterranean maritime construction as secondary entry angle, leveraging project-direct digital tendering platforms to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Integrated cement groups with captive limestone reserves and multi-kiln configurations are the most active acquirer in this space, signaling sustained appetite for scale-driven consolidation. Long-term viability across the analysis window favors targets with calcined clay activation capabilities and Nordic restoration-grade certification. Kiln efficiency upgrade completion rates serve as the critical inflection indicator for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Technology Licensing | Reduces clinker factors for EU Green Deal compliance without sacrificing L-scale reflectance thresholds. |
| Captive Limestone Reserve Development | Secures iron-free raw material supply security against scarcity constraints in Rajasthan and Anatolia. |
| Maritime Logistics Network Expansion | Strengthens Turkey's export position for sulfate-resistant formulations to North African coastal projects. |
| Kiln Efficiency Upgrade Investment | Redirects PLI scheme incentives toward dry process conversion and thermal efficiency improvements. |
| Digital Procurement Platform Integration | Enables batch-level carbon disclosure required by German and French general contractor contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cement plant managers, procurement leads at infrastructure developers, architectural specification consultants, and distribution channel partners with secondary validation from BIS certification databases, EU ETS emissions registries, and customs trade flows. Bottom-up clinker production estimates triangulated against top-down construction spend allocations.
Segment-weighting applied product type, application, production process, and end-user procurement authority dimensions across the modeling period, with CAGRs derived from regression analysis against construction output indices and embodied carbon policy implementation timelines. Whiteness threshold compliance rates and calcined clay adoption curves served as industry-specific forecast inputs.
Caveats apply where EU carbon border mechanism expansion or India's PLI scheme revision could materially shift the outlook, as forecasts reflect assumptions about regulatory enforcement continuity and limestone reserve depletion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United States White Cement Market
Building Materials
Iron and Steel Slag Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Ireland Cement Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
GCC Concealed Cistern Market
Building Materials
India Concealed Cistern Market
Building Materials
Qatar Facade Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Blind Bolts Market
Building Materials
Fireproof Cladding Market
Building Materials
Polymer Concrete Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Cement Board Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Sanded Grout Market