
 North America Residential Water Heater Market | 2026-2036
North America Residential Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Water Heater Market Analysis
The gap between single-family homeowners and multi-family developers is collapsing as a demand determinant, with individual households now commanding premium product configurations and faster replacement timelines. Rheem anchors its position through captive distribution networks spanning wholesale plumbing channels across the United States. Bradford White differentiates via exclusive professional-installer relationships that lock out retail DIY access. Navien specializes in condensing tankless platforms that extract thermal efficiency gains from natural gas infrastructure.
North America residential water heaters are pressurized vessels designed to store or instantaneously heat potable water for domestic use, operating at typical set points between 120°F and 140°F with tank constructions employing glass-lined steel or stainless steel alloys to resist corrosion. Heat pump water heaters capture the fastest-expanding product type segment as federal tax credits under the Inflation Reduction Act subsidize electrification retrofits. Natural gas retains dominant share in the fuel type split across colder northern climates where heat pump performance degrades, though propane gains traction in rural installations beyond municipal gas grids. Indoor installation types command margin premiums due to venting complexity and space-constrained replacement scenarios in existing basements and utility closets.
The US Department of Energy enforces minimum energy factor ratings under NAECA, while Canada's Natural Resources Canada administers the EnerGuide labeling program that shapes cross-border product certification requirements. EPA refrigerant phase-down rules under the AIM Act are forcing manufacturers to redesign heat pump water heater compressor circuits around lower-global-warming-potential working fluids. Stakeholders must monitor state-level building code adoptions in California, New York, and Washington that preempt federal timelines for zero-emission-ready construction.
Market Dynamics
The US Department of Energy's amended NAECA efficiency standards are compressing replacement cycles and accelerating fuel-switching decisions across single-family housing stock, reshaping how manufacturers configure product portfolios and distribution capacity.
Growth Catalysts
- Electrification mandates:California's Title 24 building code and New York's Local Law 154 prohibit fossil-fuel heating in new construction, forcing developers toward heat pump water heaters. Municipal adoption spreads to Washington, Massachusetts, and Colorado jurisdictions.
- Single-family retrofits:The Inflation Reduction Act's 30% federal tax credit subsidizes heat pump water heater installations, concentrating demand in Sun Belt states where all-electric construction already dominates. Homeowners replace functional gas units ahead of failure.
- Refrigerant transition:EPA's AIM Act phase-down of high-GWP hydrofluorocarbons is driving R-454B and R-290 adoption in heat pump compressor circuits, creating upgrade pull-through from equipment obsolescence.
Market Restraints
- Heat pump cold-climate performance:Coefficient of performance degrades below 40°F ambient temperatures, limiting electrification viability in northern US states and Canadian prairie provinces without hybrid configurations.
- Electrical service upgrades:Residential panels below 200-amp capacity require costly electrician work to support heat pump water heater loads, creating friction in 1960s-1980s housing stock concentrated in Midwest and Northeast markets.
- Natural gas infrastructure lock-in:Municipal gas distribution networks in Texas, Ohio, and Pennsylvania create sunk-cost barriers to fuel switching, with tankless gas units retaining installed base through lower first-cost positioning.
Strategic Opportunities
- Multi-family electrification lag:Apartment and condominium properties trail single-family adoption by 4-7 years, creating whitespace for packaged heat pump systems with centralized distribution architectures in Texas and Florida metro corridors.
- Propane-to-heat-pump conversion:Rural installations beyond municipal gas grids in Appalachian and Rocky Mountain regions face volatile fuel pricing, opening retrofit pathways where solar-plus-storage integration reduces operating cost exposure.
- Smart grid integration:Utility demand-response programs in California, New York, and Ontario compensate homeowners for water heater load curtailment during peak events, creating recurring revenue attachments for connected equipment.
Industry Challenges
- HVAC-electrical trade coordination:Heat pump water heater installation requires competency across refrigeration, plumbing, and electrical disciplines, with contractor licensing silos creating project delays and callback risk in fragmented service markets.
- Inventory SKU proliferation:Regional refrigerant variants, voltage configurations, and venting adaptations multiply stocking requirements, straining distributor working capital and complicating last-mile fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Water Heater Market |
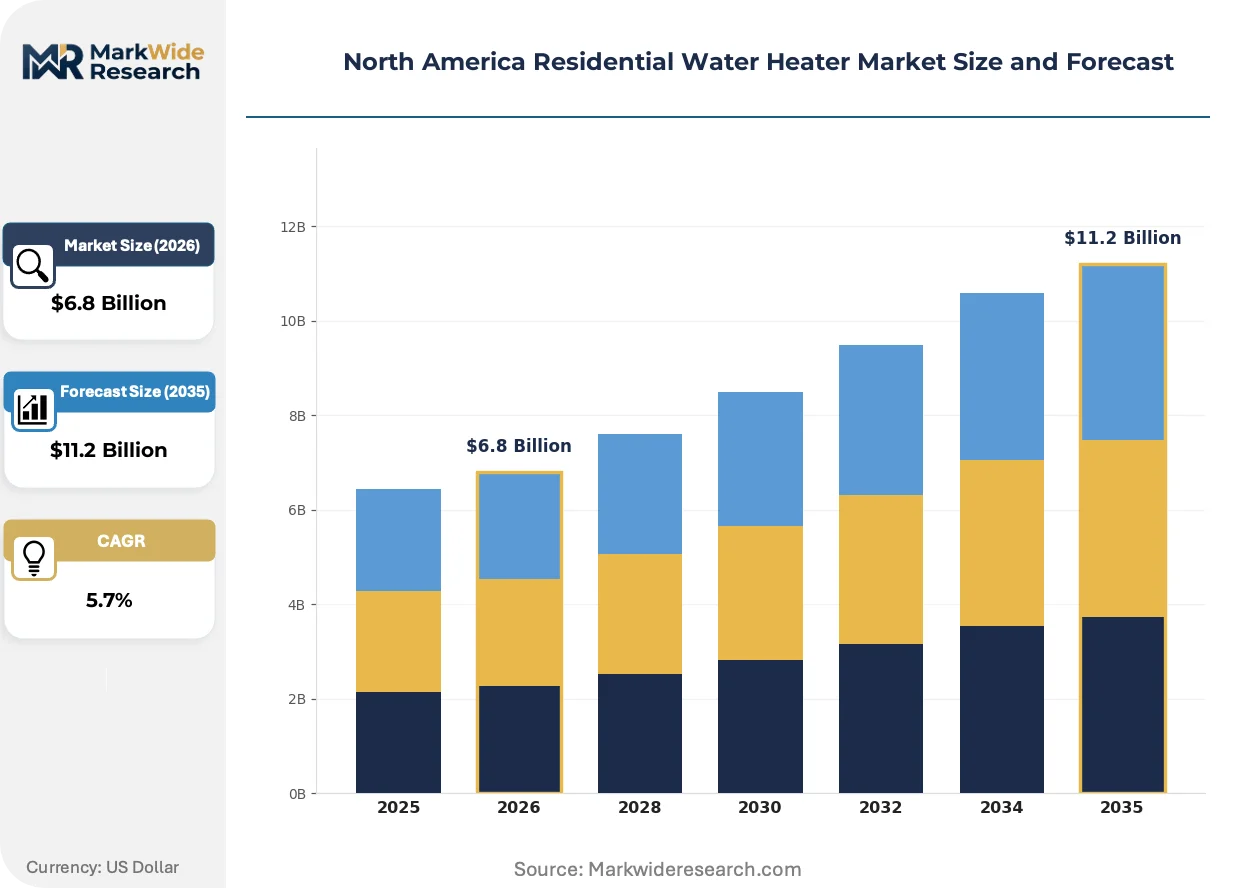
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage, Heat Pump, Solar Fuel Type: Electric, Natural Gas, Propane, Biomass Installation Type: Indoor, Outdoor, Modular, Centralized Capacity: 30 Gallon, 40 Gallon, 50 Gallon, 80 Gallon |
| Companies Covered | Bosch, Navien, A.O. Smith, GE Appliances, Ariston Thermo, Rheem, Rinnai, Noritz America, Bradford White, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Water Heater Market Emerging Trajectories
Product architecture is bifurcating between electrification-forward heat pump platforms and advanced combustion systems, with control intelligence and grid connectivity emerging as the decisive differentiators rather than thermal efficiency alone.
Heat pump water heaters are displacing conventional electric resistance units in new construction and retrofit applications alike. Single-family builders in California, Washington, and New York now specify heat pump platforms as standard, compressing the addressable market for legacy tank designs. The technology is displacing incumbent equipment faster in states with concurrent gas bans and incentive stacking.
The EPA's AIM Act refrigerant phase-down rules are forcing compressor redesigns around lower-GWP working fluids before 2027 compliance deadlines. Manufacturers face dual certification burdens for R-454B and R-290 variants across US and Canadian regulatory regimes. Heat pump product lines absorb the most engineering resources, delaying next-generation gas-fired condensing platform releases.
Utility-sponsored installation programs are consolidating contractor relationships and bypassing traditional wholesale channels. Homeowners in Arizona, Nevada, and Colorado increasingly purchase through utility marketplaces with instant rebate fulfillment rather than retail or independent plumber referrals. This channel compression concentrates volume with approved installer networks and erodes distributor margin capture in high-growth metro markets.
North America Residential Water Heater Market Segmentation
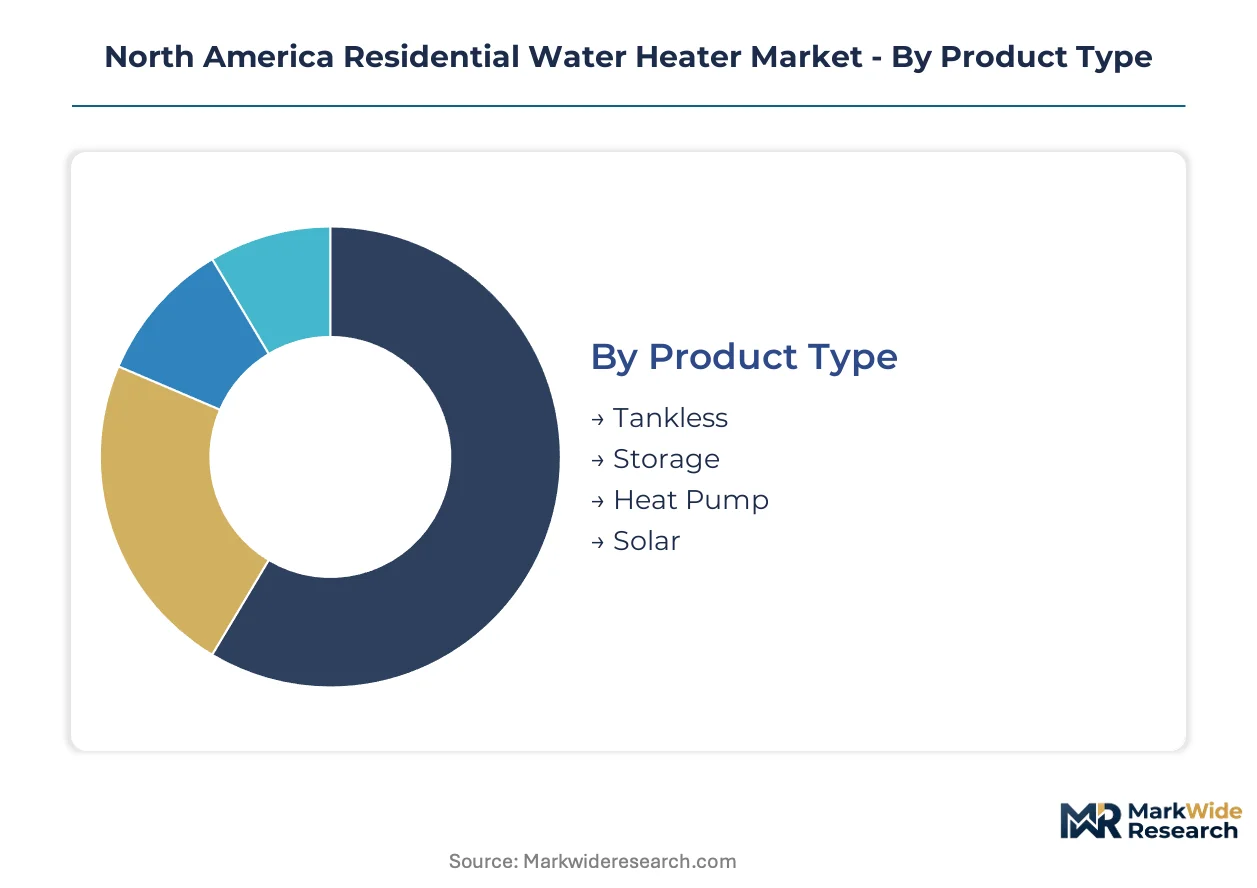
Segmentation in the North America residential water heater market reveals how regulatory pressure and housing stock characteristics split demand across incompatible technical specifications. Each dimension—product architecture, fuel source, installation constraints, and thermal capacity—creates distinct competitive arenas with divergent margin profiles and replacement cadences.
Product Type:
Geographic spread varies sharply across product architectures, with heat pump units concentrated in electrification-forward US states while tankless gas systems dominate Texas and Canadian prairie markets.
- Heat Pump:Hybrid compressor systems extract ambient thermal energy to heat stored water, achieving operational efficiencies above 300% under moderate ambient conditions. California, Washington, and New York builders now specify these as baseline equipment, with federal IRA tax credits accelerating Sun Belt retrofits ahead of equipment failure.
- Tankless:On-demand combustion or electric resistance systems eliminate standby thermal losses through instantaneous heating coils or burners. Texas, Ohio, and Pennsylvania homeowners favor natural gas variants where distribution infrastructure creates sunk-cost retention, while electric models gain traction in Pacific Northwest jurisdictions with low grid carbon intensity.
- Storage:Conventional tank-based systems maintain heated water reserves in glass-lined or stainless steel vessels. These units retain installed base in Midwest replacement cycles where electrical service upgrades pose barrier costs.
- Solar:Roof-mounted thermal collectors with storage integration harness solar radiation for water heating. Southwestern US installations in Arizona and Nevada exploit high insolation hours, though upfront capital requirements limit penetration to custom construction segments.
Storage tank configurations hold the largest share; momentum sits with heat pump platforms.
Fuel Type:
Cost tier stratification separates premium electrification pathways from economy combustion alternatives, with propane occupying volatile middle ground in rural markets beyond municipal infrastructure.
- Natural Gas:Fossil fuel combustion through sealed burner assemblies delivers rapid recovery rates and lower operating costs per therm than electric resistance. Northern US states and Canadian provinces retain this fuel type where heat pump coefficient of performance degrades below 40°F ambient temperatures.
- Electric:Resistance element or heat pump compressor systems draw grid power for thermal generation. Pacific Coast states and Colorado municipalities favor this pathway under building code electrification mandates, though panel capacity constraints create friction in 1960s-1980s housing stock.
- Propane:Liquefied petroleum gas combustion serves rural Appalachian and Rocky Mountain installations beyond natural gas distribution networks. Volatile commodity pricing drives conversion interest toward heat pump alternatives where solar-plus-storage integration can offset operating cost exposure.
- Biomass:Wood pellet or chip combustion systems leverage renewable fuel feedstocks for thermal generation. Northeastern US rural markets with established pellet supply chains employ these units in off-grid or sustainability-focused construction.
Natural gas retains dominant position; electric systems are climbing the fastest under regulatory compression.
Installation Type:
Application context determines margin structure, with indoor replacement scenarios commanding premiums for venting complexity while outdoor and modular configurations serve new construction efficiency.
- Indoor:Basement, utility closet, or garage placement requires atmospheric or power-vented exhaust management and condensate drainage. Space-constrained replacement scenarios in existing single-family homes generate margin premiums for contractors navigating clearance and combustion air requirements.
- Outdoor:Exterior wall-mounted or ground-pad installations eliminate venting complexity and free interior square footage. Sun Belt new construction favors this configuration for production efficiency, though freeze protection adds cost in northern climates.
- Modular:Pre-plumbed skid or rack systems enable rapid site assembly for multi-family or commercial-adjacent residential applications. Texas and Florida metro corridor developers specify these for centralized mechanical room efficiency in garden-style apartment construction.
- Centralized:Single large-capacity unit or banked array serving multiple dwelling units through recirculation loops. Condominium and townhouse properties employ this architecture to reduce per-unit mechanical footprint and maintenance liability.
Indoor systems command highest average selling prices; modular configurations show steepest expansion trajectory in multi-family pipeline.
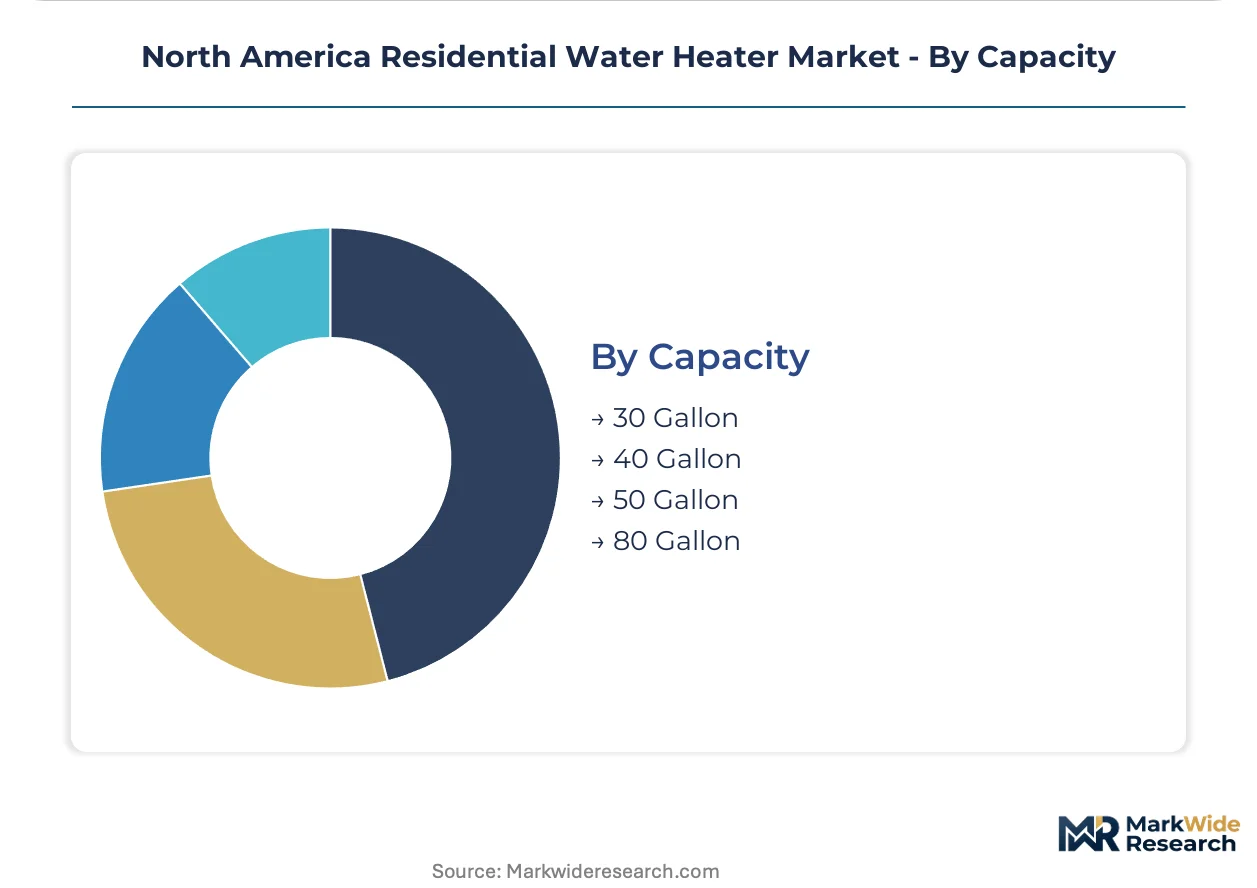
Capacity:
Customer type and housing unit size drive capacity selection, with single-family detached homes clustering at mid-range volumes while multi-family and large-footprint properties demand maximum thermal reserves.
- 50 Gallon:Mid-capacity vessels balance first-hour rating against physical footprint for three-to-four-person households. This specification dominates replacement demand in US Sun Belt states where standard tract home construction established baseline expectations.
- 40 Gallon:Compact tanks serve smaller households, secondary dwellings, and utility-constrained retrofits. Canadian provinces and northern US markets with lower incoming water temperatures sometimes pair this capacity with faster recovery burners.
- 80 Gallon:Large-volume storage meets peak demand in multi-bathroom homes and households with high-flow fixtures. Heat pump water heaters often specify this capacity to compensate for slower recovery rates versus combustion alternatives.
- 30 Gallon:Entry-level tanks occupy tight mechanical spaces in older housing stock and serve as point-of-use boosters. Limited first-hour rating restricts primary application to studio apartments and remote accessory dwelling units.
50-gallon units hold the largest share; 80-gallon specifications are gaining share fastest under heat pump adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US natural gas pipeline network and cross-border electrical interconnects with Canada shape regional demand patterns for water heating infrastructure across North America.
United States
Sun Belt states drive electrification retrofits as homeowners replace functional gas units ahead of failure. The Inflation Reduction Act's federal tax credits subsidize heat pump installations in Arizona, Nevada, and Colorado. Texas maintains natural gas dominance through municipal distribution infrastructure and tankless combustion preferences in Dallas-Fort Worth and Houston corridors.
Canada
Prairie provinces retain fossil fuel heating due to heat pump performance degradation below 40°F. Natural Resources Canada's EnerGuide labeling program shapes cross-border product certification requirements for manufacturers. Ontario and Quebec concentrate demand in Greater Toronto and Montreal where building code updates lag US electrification timelines.
Mexico
Natural gas distribution networks in Monterrey and Mexico City support tankless combustion installations for middle-class housing stock. Federal energy efficiency standards under CONUEE create compliance pathways for imported equipment. Baja California and Chihuahua border states absorb US product configurations through maquiladora supply chain spillover.
North America Residential Water Heater Market Vendor Landscape
Concentration sits with diversified appliance conglomerates and captive distribution specialists rather than pure-play water heater manufacturers. The vendor base separates into three strategic tiers: full-line HVAC-water heating conglomerates with captive wholesale channels, combustion specialists leveraging exclusive professional installer relationships, and Asian-origin tankless platform providers. Competitive moves center on refrigerant transition engineering for heat pump compressor circuits and utility-sponsored marketplace channel compression that bypasses traditional distribution.
Among diversified conglomerates, Rheem and A.O. Smith exemplify scale-driven archetypes with integrated manufacturing and distribution footprints. Bradford White occupies a specialist position through professional-installer exclusivity that locks out retail DIY access. Navien represents the Asian-origin tankless vector with condensing platform specialization. These three anchors demonstrate how competitive positioning fragments across channel strategy, installer relationships, and thermal technology focus rather than converging on uniform product specifications.
| Leading Market Players |
|---|
| Bosch |
| Navien |
| A.O. Smith |
| GE Appliances |
| Ariston Thermo |
| Rheem |
| Rinnai |
| Noritz America |
| Bradford White |
| Others |
Supply Flow & Price Mechanics
R-454B refrigerant substitution for legacy hydrofluorocarbons redraws procurement geography toward compressor manufacturers with early EPA AIM Act certification, simultaneously compressing margins on heat pump platforms and inflating replacement premiums for stranded R-410A inventory.
Pricing Analysis
Volume-discount tiering structures separate national account pricing for production builders from retail list prices serving replacement contractors. Price differentiation hinges on ENERGY STAR certification tier and after-sales service bundling through authorized dealer networks. Cost compression in standard-efficiency gas storage units is intensifying because Mexican maquiladora output expands cross-border supply. Price-sensitive multi-family developers negotiate lowest per-unit costs while single-family homeowners absorbing IRA tax credits show reduced sensitivity to upfront premiums.
Supply Chain Analysis
Inbound logistics costs from Asian compressor manufacturing through Los Angeles and Long Beach port complexes fluctuate with container availability and chassis shortages. Glass-lined steel tank production concentrates in Mexico, Tennessee, and Arkansas while electronic control modules source from Taiwan and South Korea. Single-source vulnerability sits with specialized heat pump compressor suppliers facing EPA refrigerant transition deadlines. Distribution runs through captive wholesale plumbing channels and utility-sponsored marketplace programs that displace traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as electrification mandates splinter demand across incompatible regional specifications and contractor competency requirements.
For Market Incumbents: Fortify captive distribution relationships against utility marketplace channel compression by embedding inventory financing for contractor partners. Deepen backward integration into heat pump compressor assembly to secure R-454B supply allocations before 2027 compliance deadlines. Defensive positioning must counter Asian-origin tankless specialists expanding condensing platform portfolios. For New Entrants and Emerging Players: Anchor in multi-family electrification lag across Texas and Florida metro corridors where centralized heat pump systems remain underpenetrated. Target packaged mechanical room solutions for garden-style apartment construction as the most penetrable white space. Pursue direct utility partnership routes that bypass established wholesale plumbing channels. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors component specialists with refrigerant-compliant heat pump engineering capabilities. Long-term viability over the next decade rests on positioning ahead of building code electrification waves spreading beyond early-adopter states. Acquisition targets should demonstrate compressor circuit redesign competency and utility program approval status. The signal to watch is state-level adoption of California-style gas prohibition timelines as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Engineering | EPA AIM Act compliance deadlines force R-454B and R-290 compressor redesigns before manufacturing cutoff dates. |
| Utility Marketplace Integration | Direct rebate fulfillment through Arizona, Nevada, and Colorado utility channels bypasses wholesale distributor capture. |
| Professional Installer Exclusivity | Bradford White's locked retail access model builds contractor loyalty and defends margin against price-transparent channels. |
| Hybrid System Development | Cold-climate heat pump configurations with electric resistance backup address performance degradation below 40°F ambient. |
| Multi-Family Packaged Systems | Centralized mechanical room architectures reduce per-unit footprint for Texas and Florida apartment construction pipelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of DOE appliance standards filings, EPA refrigerant phase-down rulemakings, and provincial EnerGuide databases. Primary interviews captured perspectives from wholesale plumbing distributor executives, HVAC contractor business owners, utility demand-side management officers, and municipal building code officials across US Sun Belt states and Canadian provinces. Secondary validation drew from Natural Resources Canada technical bulletins, California Title 24 compliance documentation, and SEC 10-K disclosures from publicly traded water heating manufacturers. Bottom-up installation volume estimates triangulated against top-down housing stock replacement cycle projections.
Segmentation dimensions modeled span product architecture, fuel source, installation type, and thermal capacity across the projection horizon. The analytical framework incorporates housing vintage distribution, electrical service upgrade cost curves, and state-level incentive program stacking effects. CAGRs derive from replacement cycle compression under NAECA efficiency standards and electrification mandate adoption trajectories. Forecast inputs include heat pump coefficient-of-performance degradation curves and natural gas infrastructure expansion plans from utility integrated resource filings.
Underlying assumptions cover moderate climate policy continuity, stable copper and steel commodity inputs, and contractor labor availability, with deviation risk concentrated in accelerated federal refrigerant phase-down schedules or electrical grid reliability constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Advanced Building Materials Market