
 US Commercial Paving Slabs Market | 2026-2036
US Commercial Paving Slabs Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Paving Slabs Market Intelligence
A shift toward municipality projects and high-aesthetic commercial buildings is rebalancing the end-user mix away from conventional industrial facilities and basic parking lots. Hanover Architectural Products specializes in architectural-grade pavers for these high-value applications. Belgard leverages its extensive distribution network to serve large-scale municipal contracts across multiple states. Unilock Ltd. differentiates through its proprietary manufacturing technologies that offer unique textures and enhanced durability for premium commercial spaces.
Commercial paving slabs are precast units, primarily of concrete or stone, engineered for exterior hardscaping in non-residential environments. They are manufactured to specific compressive strength and slip-resistance ratings to ensure safety and longevity in high-traffic zones. Within the product mix, interlocking pavers are gaining share over traditional concrete slabs due to superior design versatility. New construction installations, particularly for municipality projects and commercial buildings, constitute the primary demand source for these materials.
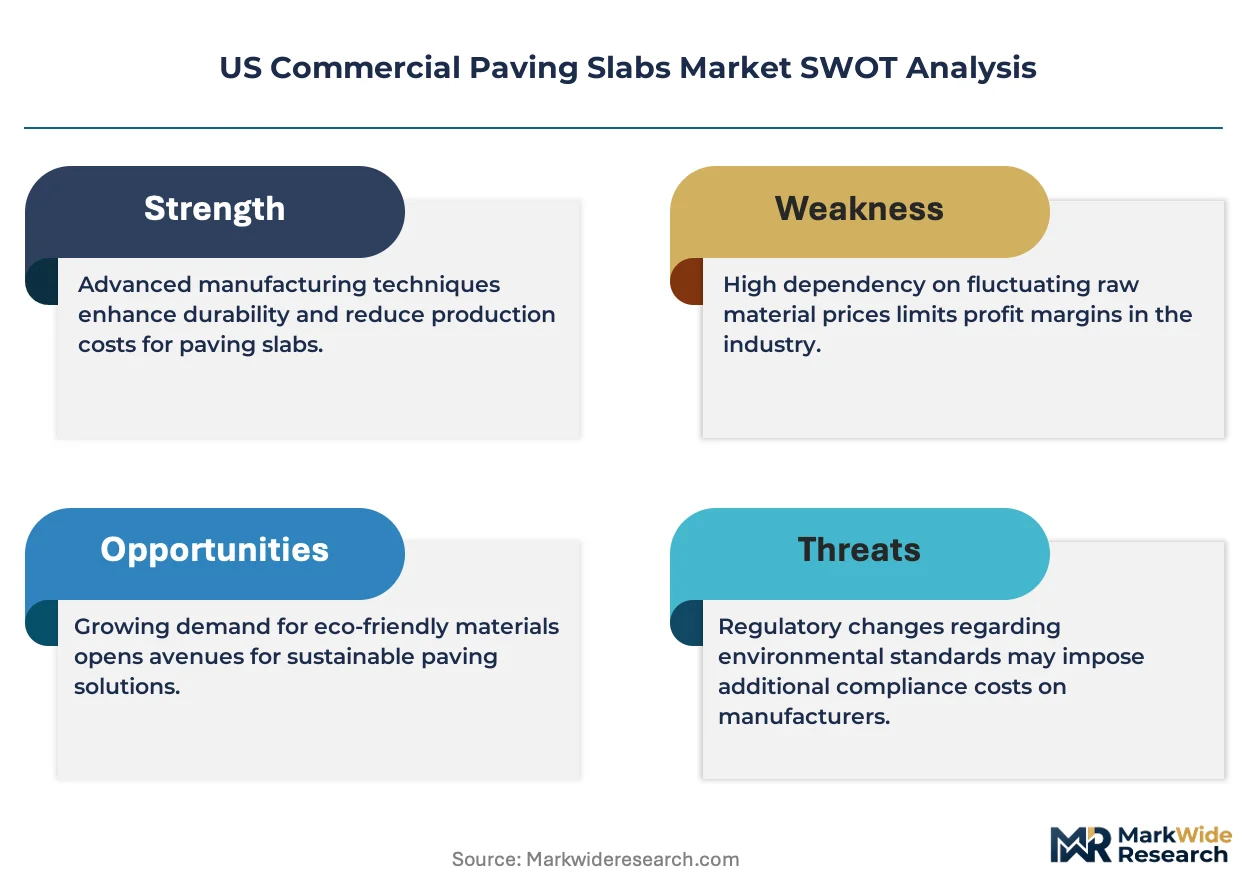
Product specifications are influenced by US federal regulations, with the Americans with Disabilities Act (ADA) setting standards for surface texture and accessibility. EPA stormwater management rules also shape demand, encouraging permeable paver systems in new developments. Navigating these compliance requirements is critical for market access. Future competitive positioning will be determined by a supplier's ability to innovate in sustainable materials and water-permeable designs.
Market Dynamics
The convergence of stringent environmental regulations and a demand shift towards high-amenity public spaces represents the central force shaping the US commercial paving slab market. EPA stormwater management rules, in particular, are compelling a fundamental redesign of exterior hardscapes.
Growth Catalysts
- Permeable Paver Mandates:Environmental Protection Agency (EPA) stormwater regulations incentivize or require the use of permeable surfaces in new commercial and municipal projects to manage runoff, directly spurring demand for interlocking permeable paver systems.
- Infrastructure Investment:Public sector spending on revitalizing urban cores, public plazas, and pedestrian-only zones, especially in fast-growing metropolitan areas in Texas and Florida, creates consistent demand for durable and aesthetically pleasing paving slabs.
- Architectural Specification:A design trend in commercial real estate favors the creation of high-value, experiential outdoor spaces, leading architects to specify premium, architectural-grade pavers over traditional concrete or asphalt for improved aesthetics.
Market Restraints
- Higher Initial Installation Cost:The total installed cost for advanced paver systems, particularly permeable ones requiring specialized sub-base preparation, is significantly higher than for conventional materials like asphalt or poured concrete, acting as a deterrent for budget-sensitive projects.
- Threat from Poured Concrete:Stamped and decorative poured-in-place concrete offers a lower-cost alternative that can mimic the look of pavers, presenting a persistent substitution threat, especially for large-scale projects like parking lots where cost is a primary factor.
- Maintenance Complexity:Permeable paver systems require periodic specialized maintenance, such as vacuum sweeping, to prevent the joints from clogging with sediment and losing their infiltration capacity, a long-term operational burden for property owners.
Strategic Opportunities
- Sustainable Material Innovation:Developing pavers with high percentages of recycled content, such as recycled concrete aggregate or post-consumer glass, offers a path to differentiation by appealing to LEED certification goals and corporate sustainability mandates.
- Retrofit Applications:A substantial opportunity exists in retrofitting existing, non-compliant parking lots and large paved surfaces with permeable paver systems, particularly as municipalities tighten local stormwater management ordinances.
- Digital Design and Sales Tools:Creating sophisticated visualization software and online specification tools allows manufacturers to engage directly with architects and designers, influencing project specifications at an early stage and streamlining the design-to-procurement process.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of installers certified by bodies like the Interlocking Concrete Pavement Institute (ICPI) creates installation bottlenecks and quality control issues, particularly for more complex permeable and pedestal-set paver systems.
- Compliance Fragmentation:Manufacturers and contractors must navigate a complex and fragmented web of building codes and stormwater regulations that vary significantly between states, counties, and even individual municipalities, increasing compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Paving Slabs Market |
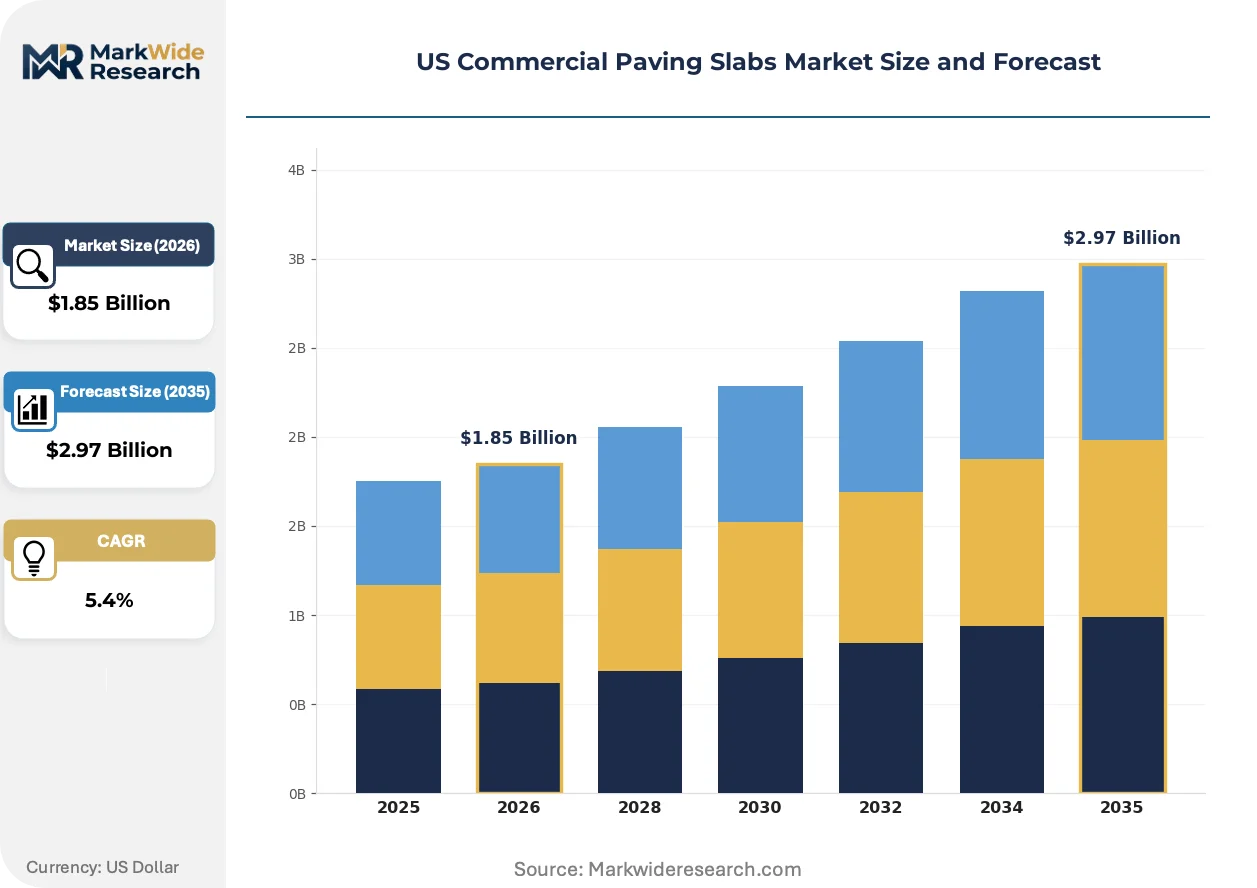
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Slabs, Asphalt Slabs, Interlocking Pavers, Stone Slabs Installation Type: New Construction, Renovation, Repair, Maintenance End User: Commercial Buildings, Parking Lots, Municipality Projects, Industrial Facilities Thickness: Thin, Standard, Thick, Heavy-Duty |
| Companies Covered | Pavestone Company, Cambridge Pavingstones, Hanover Architectural Products, Artistic Paver Manufacturing Inc., Tile Tech Pavers, Unilock Ltd., Techo-Bloc Inc., Oldcastle Architectural Products, Belgard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Paving Slabs Market Strategic Shifts & Innovations
Product development is increasingly focused on addressing environmental performance and aesthetic versatility. Innovations in materials science and manufacturing processes are enabling pavers to serve dual functions as both structural surfaces and integral components of sustainable site design, particularly for water management.
Advanced permeable paver technology allows stormwater to infiltrate the ground directly beneath the paved surface. Municipalities and commercial developers are the primary adopters, driven by a need to comply with local and federal water quality regulations. This technology is rewriting historical approaches to site drainage, reducing or eliminating the need for expensive retention ponds and conventional storm sewer infrastructure.
The Americans with Disabilities Act (ADA) continues to shape product design and surface characteristics. The Act mandates specific requirements for slip resistance, surface texture, and allowable gaps between pavers to ensure accessibility for all users. This regulatory pressure affects the entire product mix, forcing manufacturers to engineer and test products to meet these non-negotiable performance standards in all commercial applications.
Specification criteria for commercial projects are evolving beyond simple load-bearing capacity and cost. Architects and landscape designers now wield significant influence, prioritizing factors like color, texture, scale, and unique patterns to create signature outdoor environments. This shift is most visible in high-profile corporate campus, hospitality, and mixed-use retail developments where the hardscape is a central element of the brand experience.
US Commercial Paving Slabs Market Segmentation
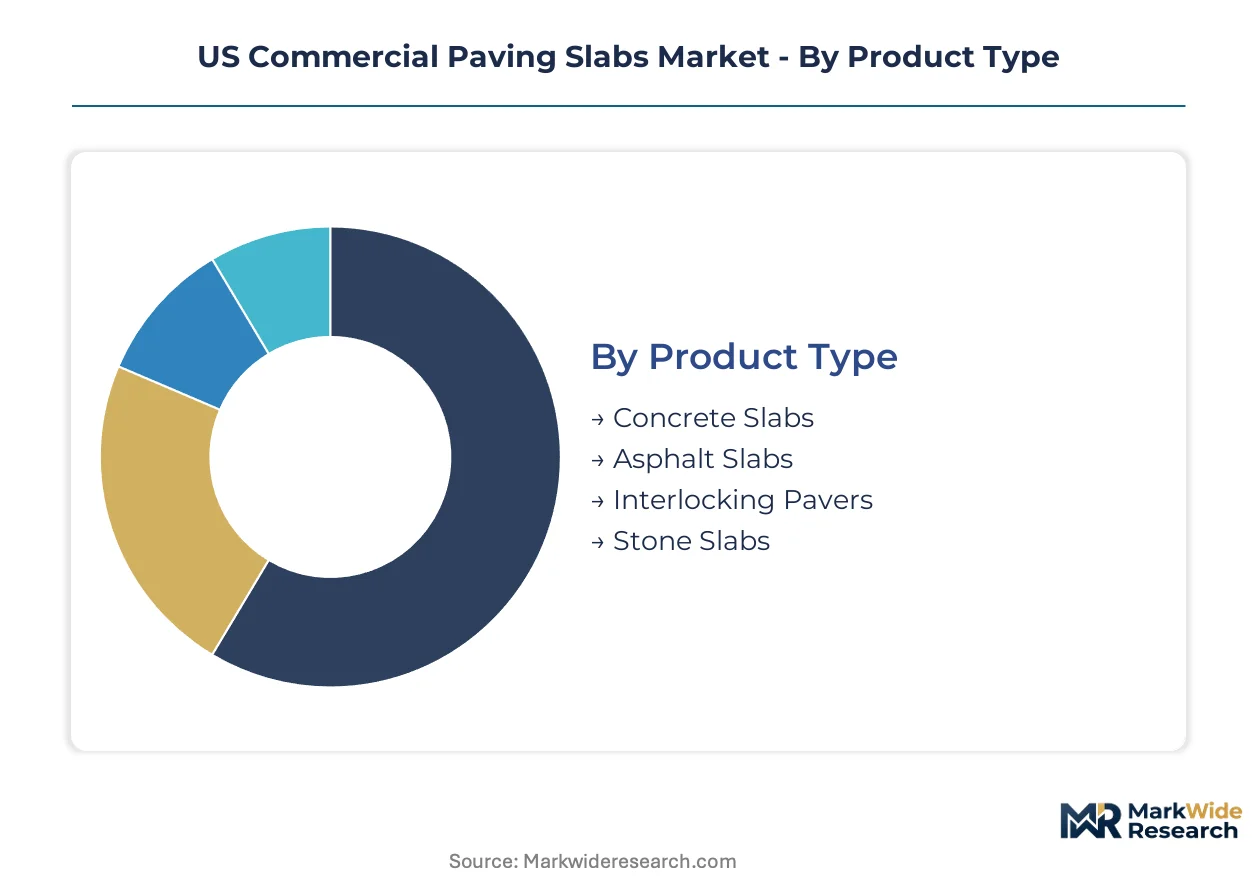
The US commercial paving slabs market exhibits distinct segments driven by material innovation, installation requirements, and end-user demands. Understanding these classifications reveals specific investment priorities and evolving design preferences across the commercial construction landscape. Each segment addresses unique functional and aesthetic criteria for diverse hardscaping projects.
Product Type:
The capital intensity of commercial paving slab projects often dictates material selection, with specialized products requiring higher upfront investment in manufacturing and installation techniques.
- Interlocking Pavers:These precast units feature integrated spacer bars for precise installation, allowing for superior design versatility and often enabling permeable surface applications. Demand concentrates in rapidly expanding metropolitan areas within Texas and Florida, driven by municipal stormwater regulations.
- Stone Slabs:Cut from natural stone, these premium products offer high aesthetic value and exceptional durability for architectural-grade applications. Commercial buildings and high-amenity public spaces specify stone slabs for their unique textures and enhanced visual appeal.
- Concrete Slabs:Standard precast concrete units provide a cost-effective and robust solution for various commercial hardscaping needs.
- Asphalt Slabs:These composite materials offer flexibility and ease of repair, primarily used in less aesthetic-sensitive commercial applications.
Concrete Slabs absorb the bulk of installed capacity; Interlocking Pavers are expanding most quickly.
Installation Type:
Commercial paving slab applications vary significantly based on project scope and existing infrastructure, influencing material choice and construction methodologies.
- New Construction:This segment involves installing paving slabs on previously undeveloped sites, representing the primary demand source for commercial hardscaping materials. Municipality projects and new commercial building developments drive volume for these installations.
- Renovation:Projects in this category involve upgrading or replacing existing paved surfaces to improve aesthetics, functionality, or regulatory compliance. Retrofitting existing parking lots with permeable paver systems represents a substantial opportunity in the United States.
- Repair:This segment addresses localized damage or wear on existing paved surfaces, requiring material compatibility and efficient intervention.
- Maintenance:Routine upkeep and preventative measures fall into this category, ensuring the longevity and performance of commercial paving installations.
Demand for New Construction remains foundational, while Renovation projects show significant momentum.
End User:
The customer type for commercial paving slabs dictates product specifications, with public and private sector clients prioritizing different aspects like durability, aesthetics, and regulatory compliance.
- Municipality Projects:Public sector investments in urban cores, public plazas, and pedestrian zones require durable, ADA-compliant, and often permeable paving solutions. These projects are particularly prominent in fast-growing US metropolitan areas.
- Commercial Buildings:High-aesthetic commercial real estate developments, including corporate campuses and mixed-use retail, specify premium pavers for experiential outdoor spaces. Architects and landscape designers influence these material selections for brand experience.
- Parking Lots:Large-scale vehicular areas prioritize cost-effectiveness and high compressive strength, often utilizing more traditional concrete or asphalt options.
- Industrial Facilities:These sites demand heavy-duty, high-load-bearing paving solutions for operational efficiency and safety in demanding environments.
Municipality Projects represent a stable revenue stream, and Commercial Buildings are attracting new investment.
Thickness:
The cost tier of commercial paving slabs is often correlated with their thickness, reflecting material volume and engineering for specific load-bearing requirements.
- Heavy-Duty:Engineered for extreme load-bearing and high-traffic industrial or commercial applications, these thick slabs command premium pricing due to enhanced material content and strength. They ensure longevity in demanding environments.
- Thick:These pavers offer superior durability and are suitable for general commercial applications with moderate to heavy vehicular or pedestrian traffic. Their robust construction supports long-term performance.
- Standard:This thickness serves a broad range of commercial applications, balancing cost-effectiveness with adequate load-bearing capacity.
- Thin:Primarily used for decorative overlays or pedestrian-only zones, these lighter slabs offer aesthetic versatility with lower structural requirements.
High-performance Heavy-Duty solutions command premium pricing, whereas Standard options serve the value segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US commercial paving slabs market concentrates its demand in areas experiencing significant economic expansion and public infrastructure investment. Federal incentives for sustainable development, like those encouraging green infrastructure, often drive localized market growth. This strategic focus on high-growth zones ensures efficient resource allocation for manufacturers and installers.
Texas
New commercial and public infrastructure development drives substantial demand for paving slabs in Texas. The EPA stormwater regulations encourage permeable paver adoption across new projects. Major metropolitan areas like Dallas-Fort Worth and Houston are seeing consistent investment in public spaces and commercial facilities.
Florida
Florida's rapidly expanding metropolitan areas generate strong demand for commercial paving slabs. State-level environmental protection initiatives complement federal EPA guidelines, promoting permeable solutions. Cities such as Miami and Orlando are experiencing significant growth in commercial buildings and municipal projects.
California
Strict environmental regulations, including comprehensive stormwater management policies, shape product specifications in California. The Americans with Disabilities Act (ADA) also influences paver design for accessibility. The San Francisco Bay Area and Los Angeles continue to invest heavily in high-aesthetic commercial and public hardscapes.
Northeast Corridor
Urban revitalization projects and dense pedestrian zones characterize demand within the Northeast Corridor, encompassing states like New York and Massachusetts. Compliance with ADA standards for slip resistance and surface texture is paramount for public safety. Major cities like New York City and Boston are upgrading existing infrastructure with durable paving solutions.
US Commercial Paving Slabs Market Key Industry Players
Top-tier vendors anchor the premium segment, while a fragmented base of regional specialists and general concrete manufacturers competes in the value segment. The market structure exhibits a tiered approach, with product sophistication and distribution reach differentiating players. Strategic archetypes include architectural specialists, large-scale municipal suppliers, and technology innovators. Capacity expansion and strategic partnerships represent dominant competitive moves.
Specialists in architectural-grade pavers, like Hanover Architectural Products, cater to high-value commercial buildings and public spaces. Belgard leverages its extensive distribution network to serve large-scale municipal contracts across multiple states, offering a broad product portfolio. Unilock Ltd. differentiates through proprietary manufacturing technologies that offer unique textures and enhanced durability for premium commercial spaces.
| Leading Market Players |
|---|
| Pavestone Company |
| Cambridge Pavingstones |
| Hanover Architectural Products |
| Artistic Paver Manufacturing Inc. |
| Tile Tech Pavers |
| Unilock Ltd. |
| Techo-Bloc Inc. |
| Oldcastle Architectural Products |
| Belgard |
| Others |
Cost & Logistics Intelligence
EPA stormwater regulations drive demand for permeable paver systems, compelling manufacturers to invest in specialized production capabilities. This investment influences pricing structures across the US commercial paving slabs market.
Pricing Analysis
Short lead times for specialized paver systems often command a premium, while standard concrete slabs in bulk may see discounts for spot inventory. Pricing for commercial paving slabs typically follows a project-based model, reflecting material quality, customization, and installation complexity. Upward pricing pressure stems from stringent US regulatory compliance for ADA and EPA stormwater management. Commercial buildings and high-amenity municipality projects exhibit lower price sensitivity compared to parking lots and industrial facilities.
Supply Chain Analysis
Reverse logistics for commercial paving slabs primarily involve waste concrete and stone recycling, which can be reprocessed into aggregates for new materials. Supply concentration for precast units often aligns with regional demand, with manufacturing facilities in states like Texas, Florida, and California serving local markets. Raw material dependencies include cement and various aggregates. Skilled labor scarcity for complex installations presents a structural supply chain risk. Distribution runs through a mix of direct sales to large projects and extensive dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US commercial paving slabs market is entering a vertical-integration race, where players are pursuing control over specialized installation services. This strategy enhances project execution and ensures product performance compliance.
For Market Incumbents:Cement market share by acquiring regional installation contractors to mitigate skilled labor scarcity and ensure quality control. Incumbents must invest in R&D for sustainable materials and advanced manufacturing technologies to counter the threat from lower-cost poured concrete alternatives. Pursue ICPI certification for installation teams to differentiate service quality. This protects against compliance fragmentation across jurisdictions.
For New Entrants and Emerging Players:Digital design and visualization software represents a technology-first wedge for new entrants to engage architects early in the specification process. Target renovation projects, especially retrofitting existing parking lots with permeable paver systems, which is a highly penetrable segment. Offer integrated design-build solutions for these complex installations. Partnering with sustainability consultants provides a strong go-to-market angle.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers with a long-term outlook, given the sustained demand from infrastructure investment and environmental regulations over the next 5 to 10 years. Focus on vertically integrated specialists offering advanced permeable paver technology or comprehensive installation services. Increased enforcement of EPA stormwater regulations across new metropolitan areas is a key signal to watch. This indicates accelerating market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Developing pavers with recycled content appeals to LEED certification goals and corporate sustainability mandates. |
| Capacity Expansion | Increasing production of permeable pavers meets rising demand driven by EPA stormwater regulations. |
| Strategic Partnership | Collaborating with architectural firms influences project specifications at early design stages. |
| Product Launch | Introducing new aesthetic designs and unique textures captures market share in high-value commercial buildings. |
| Acquisition of Specialist Firm | Acquiring installation contractors addresses skilled labor scarcity and ensures quality control for complex projects. |
Research Approach
EPA reports, ADA guidelines, and Interlocking Concrete Pavement Institute (ICPI) publications formed the secondary backbone of this study. Primary research involved in-depth interviews with architects, landscape designers, municipal project managers, and paving contractors. This approach ensured robust bottom-up and top-down triangulation. Analysis combined these insights with data from construction industry journals and state building codes.
A bottom-up analytical framework, validated by top-down market sizing, was applied across the analysis window. Segmentation dimensions modeled included product type, installation type, end user, thickness, and regional demand. Compound annual growth rates were derived from historical data and projected market drivers. Key forecast inputs included US infrastructure spending trends and new commercial construction starts.
Several conditions sit outside the modeled scope, including residential paving slabs and granular material pricing fluctuations. Forecasts reflect assumptions regarding economic stability and consistent regulatory enforcement. Practitioners should monitor new federal infrastructure bills and shifts in state-level environmental mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Poland Architectural Coatings Market
Building Materials
Steel Slag Market
Building Materials
Natural Stone Slab Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Steel Products Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Drywall Joint Tape Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Gravity Retaining Wall Market
Building Materials
China Cement Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Shotcrete Market
Building Materials
Qatar Facade Market
Building Materials
Glass Facade Market
Building Materials
Plaster Accelerator Market