
 Block Paving Market | 2026-2036
Block Paving Market Size, Share, and Industry Trends Forecast 2026-2036
Block Paving Market Analysis
Multi-source procurement among municipal hardscape contractors is rebalancing toward vertically integrated paver manufacturers with captive aggregate supplies. BRIXCO Construction Group leverages its in-house concrete batching capacity to secure specification-grade contracts across Midwestern state DOT programs. Rose Paving anchors its market position through specialized airport and commercial parking installations. KNL Industries differentiates via permeable pavement R&D partnerships with civil engineering firms.
Block paving consists of precast concrete, fired clay, or cut natural stone units laid in interlocking, mortared, or dry-laid patterns to create load-bearing vehicular and pedestrian surfaces, typically manufactured to compressive strengths between 50 MPa and 80 MPa for heavy-duty applications. Concrete pavers dominate volume in commercial and industrial applications where standardized dimensions and rapid installation reduce project timelines. Permeable installations represent the fastest-growing installation method segment as regulatory mandates for sustainable urban drainage systems expand across jurisdictions. Clay products sustain premium positioning in residential landscaping where colorfastness and aesthetic longevity command higher specification rates.
EPA stormwater management guidelines and state-level MS4 permits in the United States, alongside EU Green Deal surface water directives enforced by national environmental regulators in Germany and France, are mandating minimum permeability thresholds for new impervious surfaces. ASTM C936 and EN 1338 product standards govern dimensional tolerances and freeze-thaw durability, effectively filtering non-compliant imports from specification-driven projects. Stakeholders must monitor evolving Low Impact Development mandates that will progressively disqualify traditional impervious installations from public procurement eligibility.
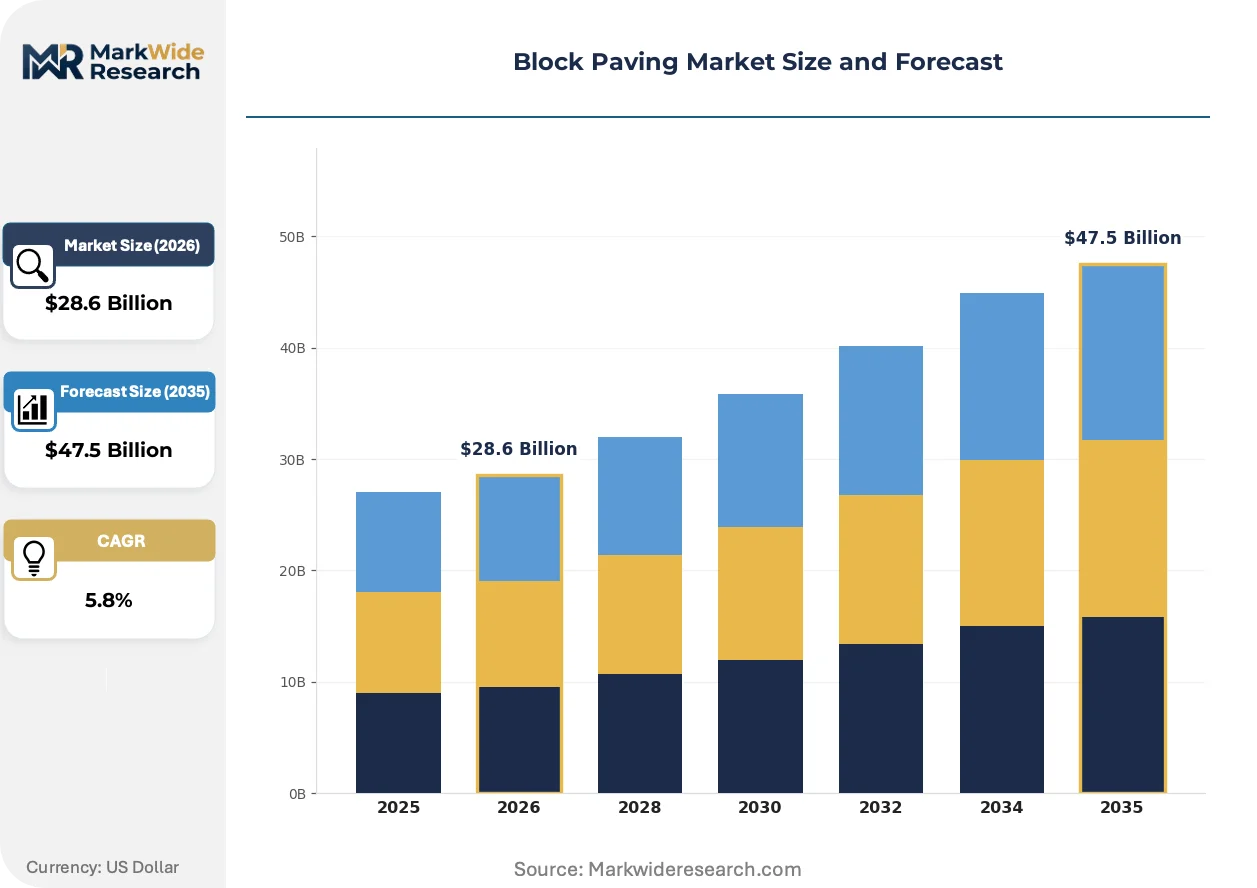
Market Dynamics
Municipal stormwater mandates across Germany, the United Kingdom, and France are structurally redirecting procurement specifications toward permeable installations, compressing demand timelines for traditional impervious systems and rewarding manufacturers with captive aggregate and in-house batching capabilities.
Growth Catalysts
- EU Green Deal surface water directives:National environmental regulators in Germany and France now enforce minimum permeability thresholds for new hardscape surfaces, disqualifying conventional impervious installations from public tender eligibility.
- Urban renewal corridors:Western European retrofit requirements now outpace greenfield development, concentrating demand in dense metropolitan zones with aging drainage infrastructure.
- Precast concrete batching automation:Standardized paver dimensions and rapid installation protocols compress project timelines for commercial and industrial clients, accelerating specification-grade contract capture.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production exposes concrete paver margins to input cost swings, squeezing mid-tier manufacturers without captive kiln operations.
- Freeze-thaw certification barriers:ASTM C936 and EN 1338 dimensional tolerance standards filter non-compliant imports from specification-driven projects, limiting supplier pool expansion.
- Clay product sourcing concentration:Premium residential segment dependence on specific shale deposits creates geographic supply vulnerability for colorfast fired clay units.
Strategic Opportunities
- Permeable-airport crossover applications:Specialized airfield pavement contractors are adapting permeable interlock systems for apron drainage, opening specification pathways beyond traditional road and parking markets.
- Low Impact Development mandate expansion:MS4 permit tightening across US state environmental agencies will progressively disqualify traditional impervious installations from federal infrastructure funding eligibility.
- Civil engineering R&D partnerships:Collaborative permeability testing protocols with structural design firms create first-mover specification lock-in for novel void-structured paver geometries.
Industry Challenges
- Geotechnical installation certification:Permeable sub-base engineering requires specialized civil competency that general hardscape contractors often lack, creating quality variance and warranty exposure.
- Legacy drainage integration:Retrofit projects must interface with existing combined sewer systems, complicating hydraulic modeling and raising remediation cost uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Block Paving Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Clay, Permeable, Natural Stone Installation Method: Interlocking, Standard, Mortared, Dry Laid Application: Residential, Commercial, Industrial, Landscaping Design Style: Traditional, Contemporary, Rustic, Patterned |
| Companies Covered | Hatch Asphalt, BRIXCO Construction Group, Rose Paving, Associated Paving Contractors, KNL Industries, Ruston Paving Co., Alpha Paving Industries, Stasi Brothers Asphalt Corp., All County Paving, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Block Paving Market Emerging Trajectories
Permeable pavement technology is actively restructuring competitive advantage around hydraulic performance certification rather than compressive strength alone, compressing the value of legacy manufacturing assets while rewarding R&D-intensive specialists.
Recycled aggregate concrete pavers are expanding into heavy-duty municipal road applications as state DOT programs relax virgin material specifications. German transport authorities now specify crushed concrete content thresholds for non-structural wearing courses. This technology is expanding into specification regimes previously reserved for quarried granite sets, compressing the premium positioning of natural stone alternatives.
The EU Green Deal's tightening surface water runoff directives are mandating real-time permeability monitoring for new hardscape installations. French environmental regulators now require post-construction infiltration rate verification. Commercial parking developers in the Île-de-France region are responding by specifying open-graded sub-base designs with embedded sensor arrays.
Specification-grade procurement now demands outcome-based drainage performance guarantees rather than product-centric compliance. Municipal hardscape contractors in the United Kingdom are bundling maintenance liability into multi-year service agreements. This reconfiguration is most visible in Thames Valley urban renewal corridors where retrofit SUDS installations dominate capital allocation.
Block Paving Market Segmentation
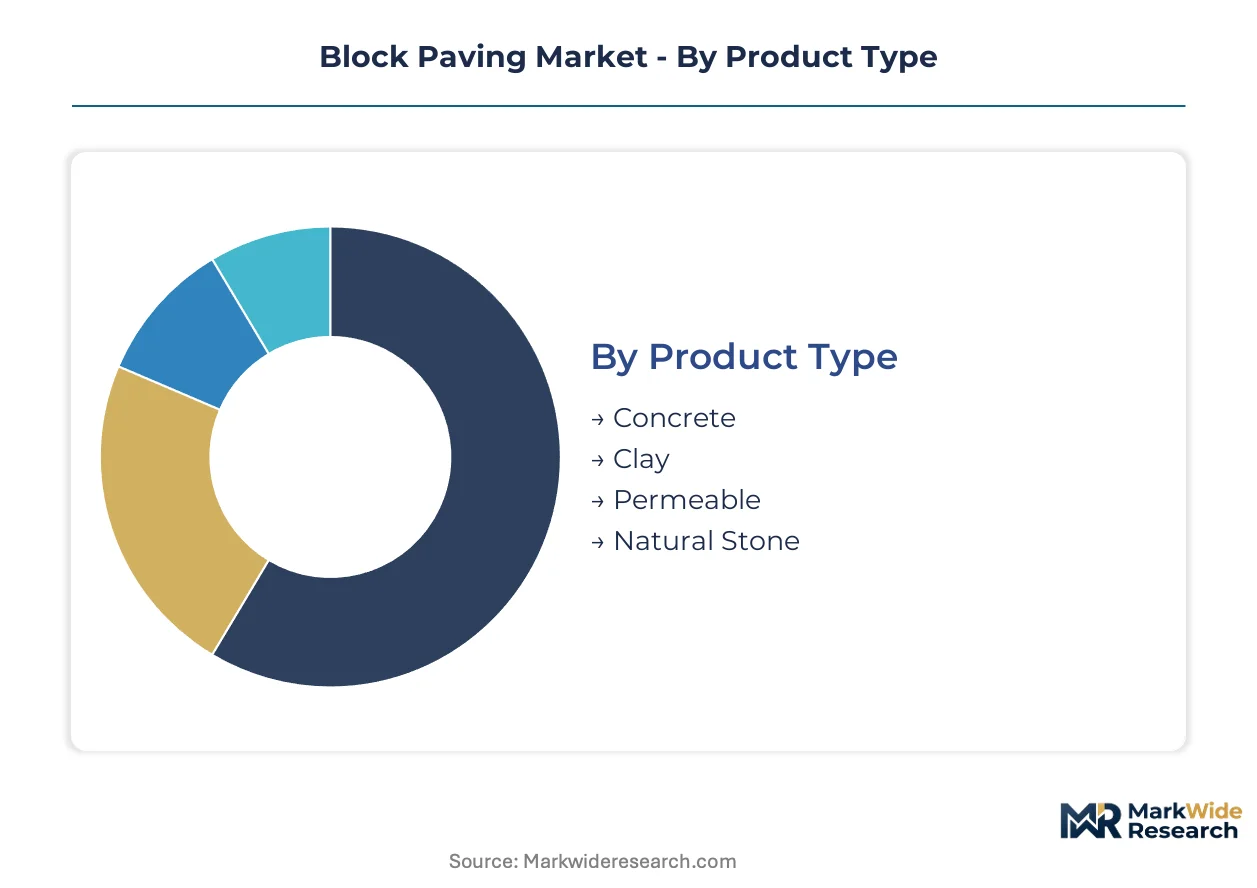
Segmentation in block paving reveals how specification requirements fragment procurement across load-bearing demands, drainage mandates, and aesthetic positioning. Manufacturers configure production lines around these divides, with captive aggregate supplies and batching automation determining which tiers they can serve profitably.
Product Type:
Supply concentration favors producers with in-house concrete batching and captive aggregate quarries, compressing margins for merchants dependent on spot-market cement purchases.
- Concrete:Precast units manufactured to 50-80 MPa compressive strength dominate commercial and industrial specifications where standardized dimensions accelerate installation timelines. German state DOT programs and UK municipal contractors specify concrete for heavy-duty vehicular surfaces.
- Permeable:Void-structured pavers with open-graded sub-base designs satisfy EU Green Deal surface water runoff mandates in France and Germany. French environmental regulators now require post-construction infiltration rate verification, embedding this segment into public tender eligibility.
- Clay:Fired clay units command premium positioning in residential landscaping where colorfastness and aesthetic longevity justify higher specification rates.
- Natural Stone:Cut granite and sandstone sets retain niche specification for heritage restoration and high-end architectural hardscapes.
Today's leader: Concrete. Tomorrow's challenger: Permeable.
Installation Method:
Cost tier differentiation separates specification-grade municipal contracts from residential merchant trade, with labor skill intensity determining contractor margin capture.
- Interlocking:Dry-laid precision-fit units without mortar enable rapid installation and future lift-and-relay maintenance, dominating commercial parking and airport apron applications.
- Standard:Conventional bedding on compacted sand or mortar screed serves volume residential driveways and pedestrian walkways.
- Mortared:Rigid bedding with cementitious joints provides structural continuity for heavy industrial loading and permeable-airport crossover trials.
- Dry Laid:Flexible installation without binding agents permits drainage and thermal expansion, specified for permeable SUDS retrofits in Thames Valley urban renewal corridors.
Interlocking commands the premium tier. Dry Laid is gaining share fastest in stormwater retrofit markets.
Application:
Volume concentration in Western European urban renewal corridors favors retrofit-specialist contractors over greenfield developers, reshaping project pipeline composition.
- Commercial:Multi-year service agreements bundling maintenance liability now dominate UK municipal procurement, particularly in parking and transport interchange hardscapes.
- Industrial:Heavy-duty loading specifications drive 80 MPa concrete paver demand from logistics hubs and distribution centers.
- Residential:Clay and natural stone aesthetics sustain premium merchant trade positioning despite concrete volume dominance elsewhere.
- Landscaping:Public realm and private garden installations prioritize visual integration over structural performance.
Commercial leads specification value. Industrial offers the steepest expansion trajectory under logistics infrastructure investment cycles.
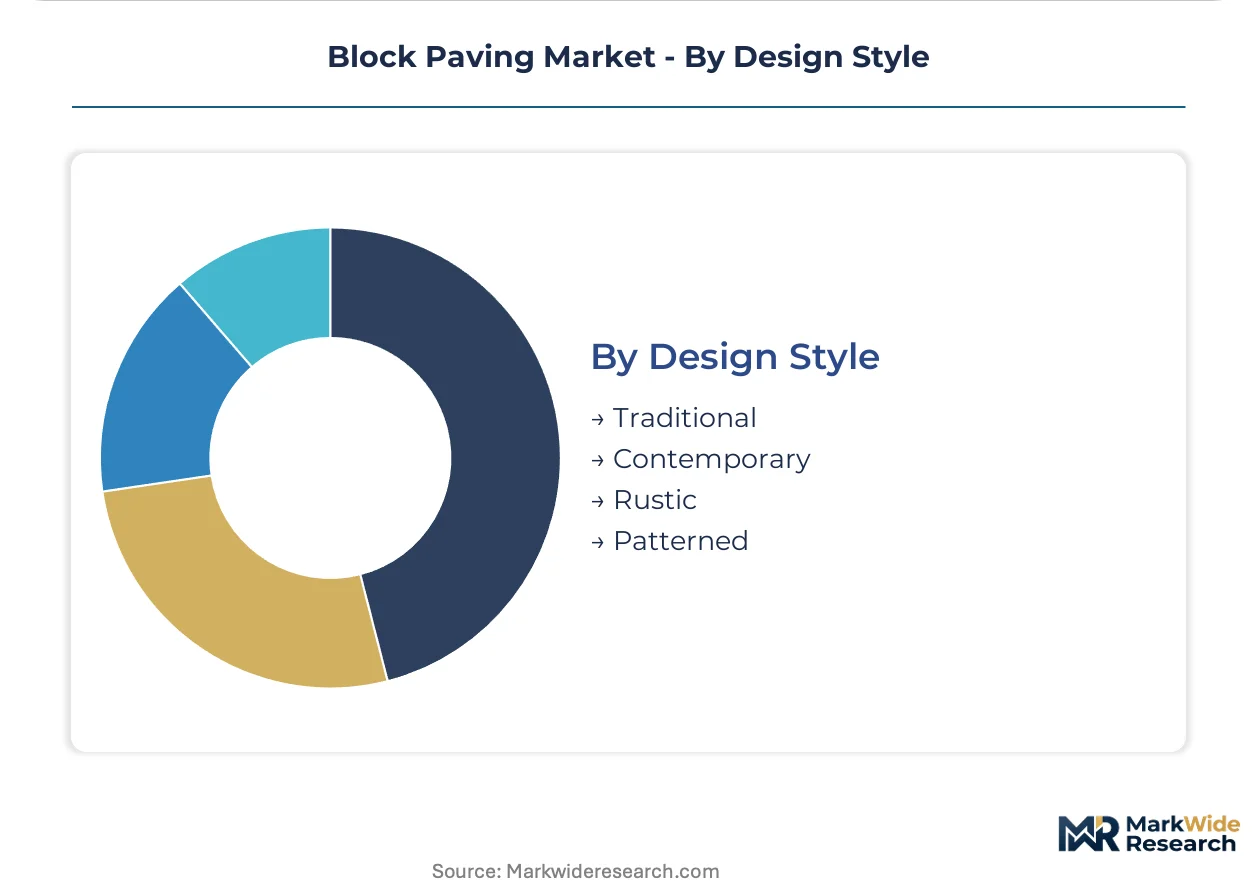
Design Style:
Customer type fragmentation splits procurement between heritage conservation officers specifying traditional materials and commercial developers pursuing contemporary visual differentiation.
- Contemporary:Clean lines and uniform color palettes align with commercial parking and airport apron specifications where visual coherence supports brand identity.
- Traditional:Herringbone and basketweave patterns specified for conservation area compliance and heritage streetscape restoration.
- Rustic:Tumbled edges and variegated coloring serve residential landscaping seeking aged aesthetic without weathering delays.
- Patterned:Custom geometric layouts enable wayfinding and zoning in pedestrian precincts and plaza designs.
Contemporary dominates commercial specification. Traditional holds defensive position in regulated heritage markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with lower compliance costs for permeability certification, while specification-grade demand concentrates in high-mandate Western European markets where stormwater directives tighten fastest.
Germany
Federal transport authorities specify crushed concrete content thresholds for municipal wearing courses, redirecting procurement toward domestic recyclers. The EU Green Deal's surface water runoff directives, enforced by national environmental regulators, mandate minimum permeability for new hardscape surfaces. Urban renewal corridors in the Rhine-Ruhr metropolitan region concentrate retrofit SUDS installations as aging combined sewer systems face capacity constraints.
United Kingdom
Thames Valley municipal contractors bundle multi-year maintenance liability into service agreements, transforming procurement from product-centric to outcome-based models. Environment Agency MS4 permit tightening progressively disqualifies impervious installations from public tender eligibility. Birmingham and Manchester metropolitan zones drive demand for interlocking dry-laid systems in transport interchange hardscapes.
France
Île-de-France commercial developers specify open-graded sub-base designs with embedded sensor arrays to satisfy post-construction infiltration verification requirements. French environmental regulators under EU Green Deal mandates now require real-time permeability monitoring for new installations. Lyon and Marseille urban renewal clusters concentrate retrofit demand where legacy drainage infrastructure requires hydraulic modeling integration.
United States
Midwestern state DOT programs specify 80 MPa compressive strength concrete pavers for heavy-duty vehicular surfaces, anchoring demand for high-performance precast units. EPA stormwater management guidelines and state-level MS4 permits mandate permeability thresholds for federal infrastructure funding eligibility. Chicago and Detroit logistics hubs drive industrial segment demand from distribution center loading specifications.
Canada
Ontario municipal procurement prioritizes freeze-thaw durability certification under CSA A231.2 standards, filtering non-compliant imports from specification-driven contracts. Provincial environmental regulators adopt Low Impact Development mandates aligned with US MS4 permit structures. Toronto and Vancouver metropolitan areas concentrate commercial parking retrofit demand as stormwater utility fees escalate for impervious surface coverage.
Block Paving Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue permeable-airport crossover applications and sensor-embedded sub-base systems. The vendor base stratifies across three archetypes: vertically integrated manufacturers with captive aggregate supplies, specialized airfield and commercial parking contractors, and R&D-intensive permeability specialists. Consolidation pressure favors backward integration into aggregate quarries and in-house concrete batching capacity. Dominant competitive moves include civil engineering partnerships for specification lock-in and multi-year service agreements bundling maintenance liability.
Within the vertically integrated tier, BRIXCO Construction Group and Rose Paving exemplify archetypes leveraging in-house production capabilities to secure specification-grade contracts. KNL Industries occupies a position representing R&D-intensive specialists pursuing permeability partnerships with structural design firms. These three anchors illustrate how competitive positioning fragments between scale-driven batching automation and innovation-driven hydraulic performance certification.
| Leading Market Players |
|---|
| Hatch Asphalt |
| BRIXCO Construction Group |
| Rose Paving |
| Associated Paving Contractors |
| KNL Industries |
| Ruston Paving Co. |
| Alpha Paving Industries |
| Stasi Brothers Asphalt Corp. |
| All County Paving |
| Others |
Supply Flow & Price Mechanics
Permeable paver manufacturing automation simultaneously compresses unit economics and concentrates supply among producers with captive aggregate quarries, as German federal transport authorities specify crushed concrete content thresholds that reward domestic recyclers with in-house batching capacity.
Pricing Analysis
Distributor margins on specification-grade concrete pavers range from 12 to 18 percent, with project-based contract pricing dominating municipal procurement while spot-market merchant trade serves residential segments. Price differentiation rests on freeze-thaw certification tier and captive kiln ownership, with ASTM C936-compliant units commanding premium positioning over uncertified imports. Cost compression in mid-tier concrete products is intensifying because Portland cement price volatility squeezes manufacturers without backward integration into clinker production. Municipal hardscape contractors exhibit the lowest price sensitivity due to multi-year service agreement bundling, whereas residential landscaping buyers prioritize economy-tier clay alternatives.
Supply Chain Analysis
Domestic-content mandates in German state DOT programs and UK Environment Agency procurement specifications are redirecting sourcing toward captive aggregate quarries in Germany, the United Kingdom, and France. Raw material dependencies center on Portland cement clinker, crushed concrete aggregate, and colorfast shale deposits for fired clay units. Single-source vulnerability concentrates in premium clay product sourcing where specific shale deposits create geographic supply risk. Distribution runs through specialized hardscape distributors serving municipal contractors, with direct-to-airfield-contractor channels capturing specification-grade commercial parking and apron installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The block paving market represents a late-cycle quality story as stormwater retrofit mandates in Western European urban renewal corridors concentrate procurement among contractors with permeability certification and maintenance liability bundling capabilities.
For Market Incumbents: Extend specification-grade contract capture by deepening civil engineering R&D partnerships for novel void-structured paver geometries, while consolidating backward integration into captive aggregate quarries to defend margins against Portland cement price volatility. Prioritize multi-year service agreements in Thames Valley and Rhine-Ruhr metropolitan zones where retrofit SUDS installations dominate capital allocation. For New Entrants and Emerging Players: The price-point gap between premium permeable installations and economy-tier standard pavers creates entry space for mid-tier producers specializing in recycled aggregate concrete for heavy-duty municipal wearing courses. Target German state DOT programs relaxing virgin material specifications, with go-to-market positioning anchored in crushed concrete content compliance and rapid-installation protocol certification. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated regional pavers because stormwater mandate fragmentation creates scale advantages in specification-grade procurement. The long-term viability window favors producers with in-house batching automation and permeability testing partnerships. Monitor EPA MS4 permit tightening across US state environmental agencies as the inflection signal for federal infrastructure funding eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aggregate Quarries | Captive supply of crushed concrete secures German DOT specification compliance against import competition. |
| Permeability R&D Partnerships | Collaborative testing with structural design firms creates first-mover specification lock-in for SUDS retrofits. |
| Multi-Year Service Agreement Bundling | UK municipal contractors transform procurement from product-centric to outcome-based drainage performance guarantees. |
| Recycled Aggregate Scale-Up | Crushed concrete content thresholds in German transport authority specifications open heavy-duty road applications. |
| Sensor-Embedded Sub-Base Systems | French post-construction infiltration verification mandates drive specification for open-graded designs with monitoring arrays. |
Methodological Framework
Coverage spans Germany, the United Kingdom, France, the United States, and Canada, with primary inputs from each market combining interviews with municipal hardscape contractors, civil engineering firm technical directors, state DOT specification officers, aggregate quarry operations managers, and commercial parking developers. Secondary validation drew from EPA stormwater management guidelines, EU Green Deal surface water directive filings, ASTM C936 and EN 1338 certification databases, and customs trade data on precast concrete imports. Bottom-up project pipeline analysis triangulated with top-down construction spending forecasts.
Rate-of-change decomposition across the analysis window modeled volume and value progression through product type segmentation, installation method differentiation, application load-bearing requirements, and regional regulatory mandate intensity. CAGRs were derived from regression analysis against municipal capital allocation patterns and logistics infrastructure investment cycles. Forecast inputs included state-level MS4 permit adoption timelines and EU member state transposition schedules for surface water runoff directives.
Caveats apply where Portland cement price volatility, freeze-thaw certification barrier adjustments, or geotechnical installation competency shortages could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Metal Cladding Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Roofing and Insulation Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
Construction Coatings Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Engineered Stone Market
Building Materials
US Cement Tiles Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market