
 South Africa White Cement Market | 2026-2036
South Africa White Cement Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa White Cement Market Intelligence
Maintenance contracts for decorative concrete resurfacing is pivoting how suppliers monetize white cement beyond initial material sales. PPC Ltd leverages its integrated quarry-to-distribution network to sustain supply reliability across South Africa's interior. Sephaku Cement differentiates through dedicated white cement production lines rather than gray-to-white switching capacity. LafargeHolcim South Africa dominates coastal logistics corridors, controlling port-adjacent bulk handling infrastructure.
White cement is a specialty hydraulic binder manufactured from raw materials with low iron and manganese content, yielding a product with reflectance values exceeding 80 percent on the L scale and superior decorative finish compatibility. Its primary commercial purpose centers on architectural concrete, terrazzo, precast cladding, and pigmented mortar systems where color consistency and surface brightness determine specification acceptance. Bagged white cement captures the premium margin pool in architectural finishes, while bulk delivery anchors volume flows into commercial infrastructure projects with continuous pour schedules. Ready-mix integration remains nascent but represents the fastest-growing channel as batching plants seek to reduce on-site labor variability.
South Africa's National Regulator for Compulsory Specifications (NRCS) administers SABS EN 197 and SANS 50197 compliance, forcing importers and domestic producers to maintain certified clinker sourcing and fineness testing protocols. The country's carbon tax framework, administered by the National Treasury, pressures energy-intensive kiln operations to accelerate alternative fuel substitution or absorb escalating production cost penalties. Stakeholders must monitor how pending amendments to building energy efficiency regulations reshape material specifications for thermally reflective exterior finishes.
Market Dynamics
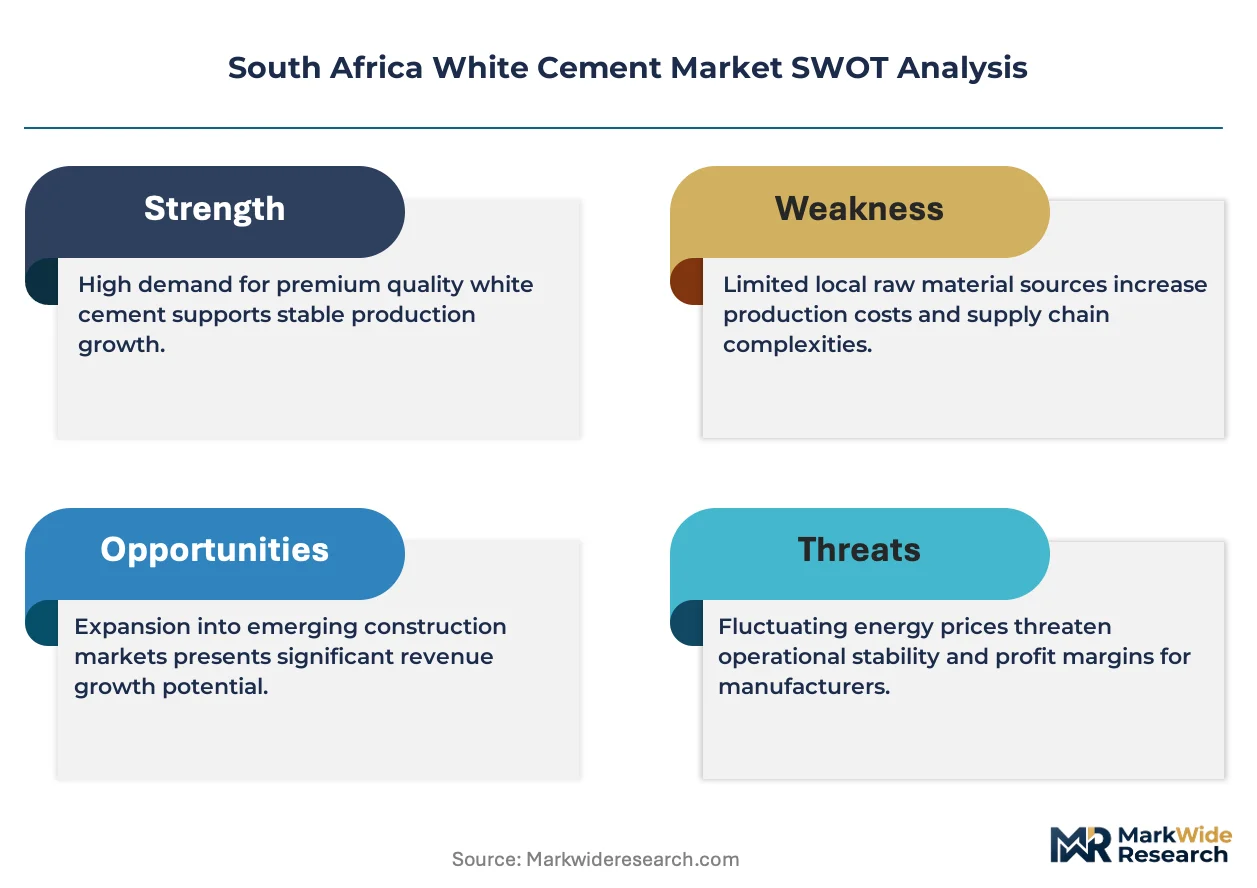
The National Treasury's carbon tax framework is compressing margins across South Africa's kiln operations while simultaneously accelerating alternative fuel substitution investments that reshape competitive cost structures.
Growth Catalysts
- Gauteng Infrastructure Concentration:Johannesburg and Pretoria anchor the bulk of premium commercial and residential construction, creating sustained pull for architectural-grade white cement in terrazzo and precast cladding applications.
- SABS EN 197 Compliance Mandate:The National Regulator for Compulsory Specifications enforces certified clinker sourcing and fineness testing protocols that filter out marginal suppliers and consolidate procurement toward certified domestic producers.
- Ready-Mix Channel Expansion:Batching plants are integrating white cement into continuous pour schedules to reduce on-site labor variability, opening volume flows beyond traditional bagged distribution.
Market Restraints
- Energy Cost Volatility:Kiln operations face escalating electricity and fuel input costs under the carbon tax framework, compressing margins for producers lacking alternative fuel infrastructure.
- Import Dependency for Specialty Additives:Pigment and performance additive supply concentrates in European and Asian export corridors, exposing domestic blenders to currency and shipping cost fluctuations.
- Limestone Quality Scarcity:Low-iron limestone suitable for white cement clinker production concentrates in limited quarry zones, constraining brownfield capacity expansion.
Strategic Opportunities
- Western Cape Coastal Logistics:Port-adjacent bulk handling infrastructure at Durban and Cape Town harbors enables export positioning into Sub-Saharan African markets with underdeveloped domestic production.
- Thermally Reflective Exterior Mandates:Pending amendments to building energy efficiency regulations are reshaping specifications for high-albedo architectural finishes in commercial facades.
- Decorative Concrete Resurfacing Services:Maintenance contract models monetize white cement beyond initial material sales through recurring revenue streams in commercial property refurbishment cycles.
Industry Challenges
- Kiln Operator Skill Shortage:Alternative fuel co-processing and clinker quality control for low-iron output require specialized combustion engineering expertise that remains scarce in the domestic labor pool.
- Certification Timeline Compression:SABS testing protocols for new product formulations extend go-to-market cycles, delaying response to specification shifts in fast-moving architectural trends.
- Legacy Gray-to-White Switching Complexity:Plants with dual-purpose capacity face contamination risk management and cleaning downtime costs that erode batch economics for small-volume white cement orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa White Cement Market |
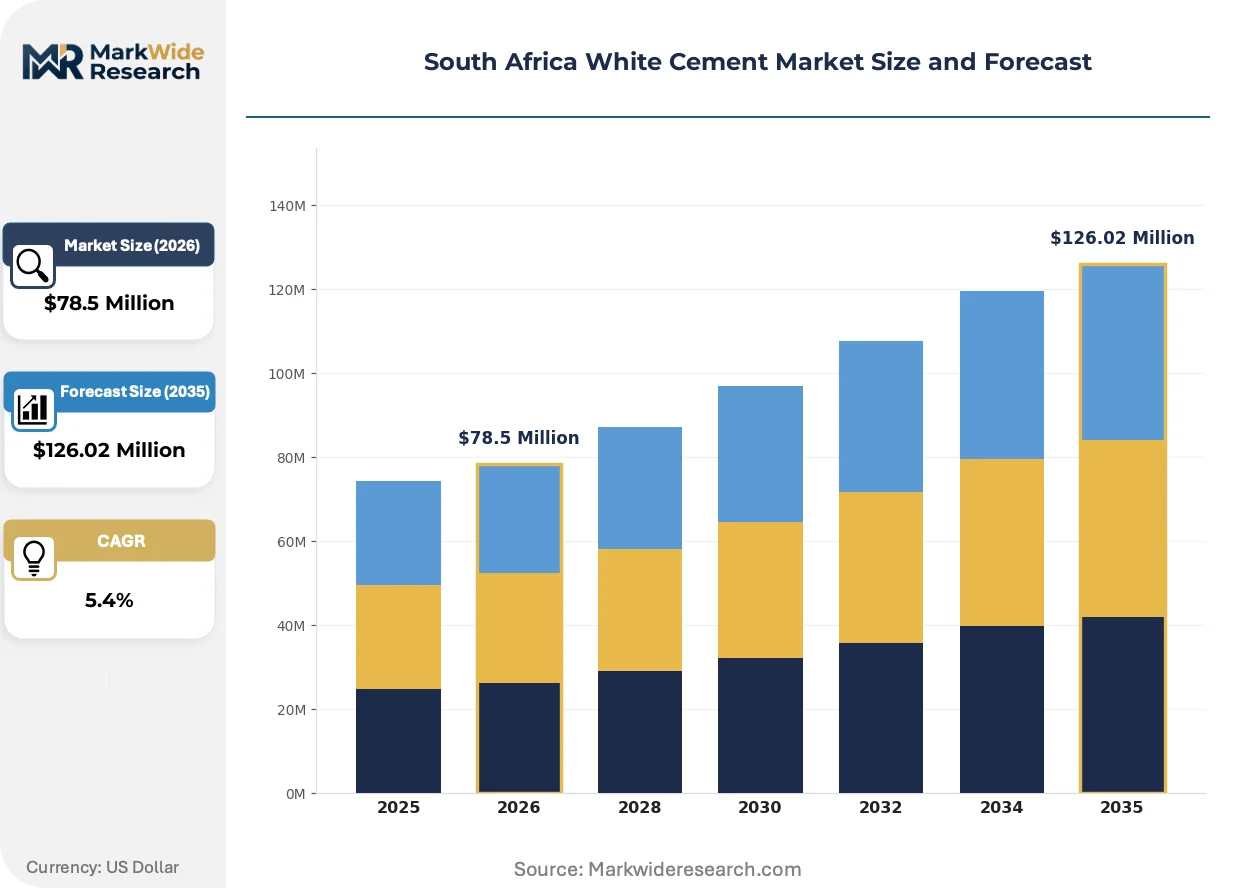
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $126.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bagged, Bulk, Pre-mixed, Ready-mix End Use Industry: Residential Construction, Commercial Infrastructure, Industrial Projects, Architectural Finishes Distribution Channel: Direct Sales, Retail Outlets, Distributors, Online Platforms Packaging Type: Paper Bags, Plastic Bags, Steel Drums, Containers |
| Companies Covered | Afrimat, Cemex South Africa, PPC Ltd, SOTACIB, Çimsa, Sephaku Cement, LafargeHolcim South Africa, Cementir Holding, Dangote Cement South Africa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa White Cement Market Strategic Shifts & Innovations
Production technology and procurement patterns are converging to compress delivery cycles and expand specification flexibility for architectural-grade binders across South Africa's construction corridors.
Calcined clay and limestone calcined clay cement (LC3) formulations are modularizing white cement production by enabling lower-clinker recipes that maintain brightness thresholds while reducing carbon intensity. Major infrastructure contractors in Gauteng are piloting these blends for precast cladding applications. The technology is modularizing batch plant operations by allowing on-site adjustment of reflectance and strength parameters without dedicated white cement silo infrastructure.
The National Treasury's carbon tax amendments are forcing kiln operators to document alternative fuel substitution rates or absorb escalating production penalties. Industrial consequence includes accelerated investment in biomass and waste-derived fuel handling systems at coastal and inland production facilities. Ready-mix producers in Durban and Port Elizabeth are responding by demanding certified low-carbon white cement documentation for green building rating submissions.
Specification-driven procurement is consolidating buyer power among tier-one developers who mandate SABS-certified supply chain documentation for entire project portfolios. Traditional merchant distributors are losing share to direct manufacturer relationships with national construction groups. This concentration is most visible in Johannesburg's premium residential tower segment, where developers bundle white cement procurement across multiple project phases to secure volume pricing and priority allocation during supply tightness.
South Africa White Cement Market Segmentation
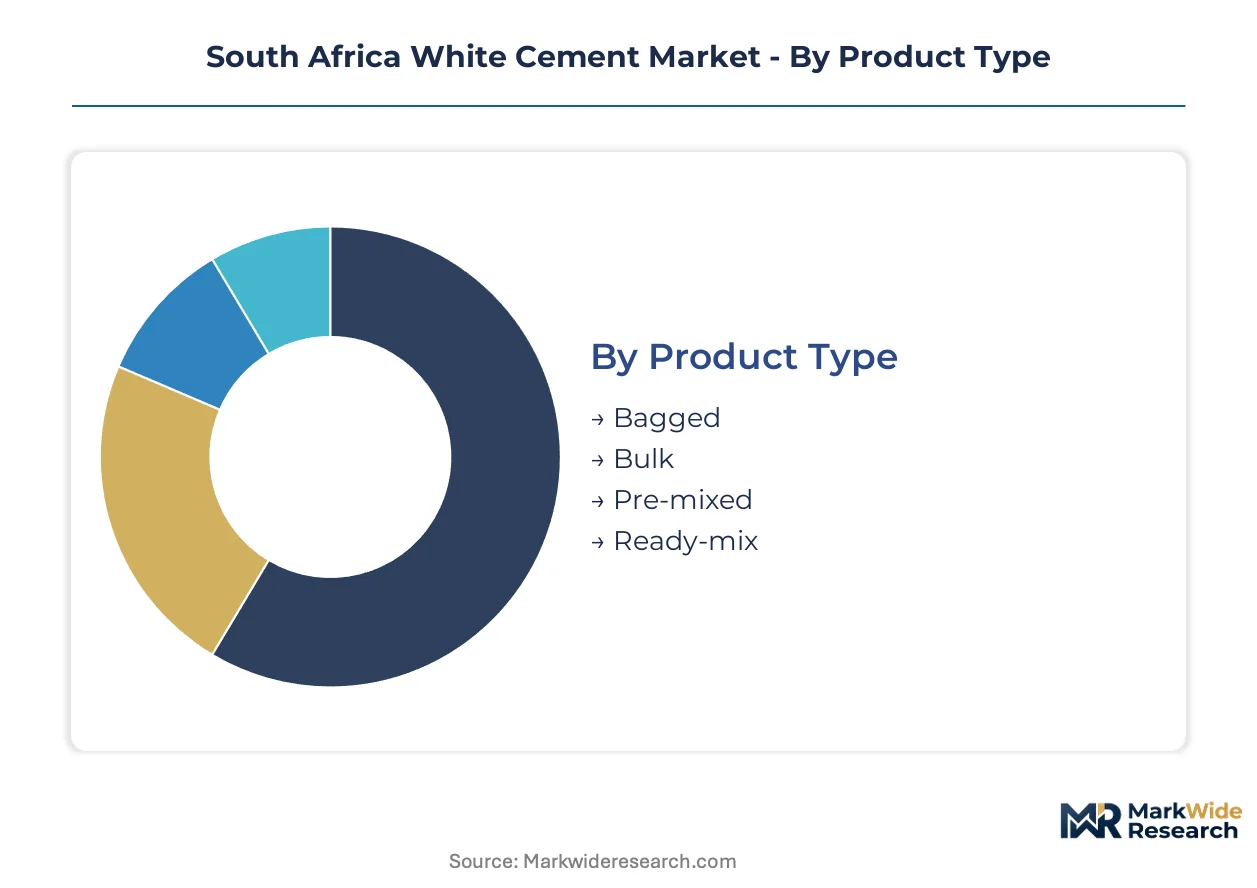
White cement segmentation in South Africa reflects divergent procurement logics between project-scale infrastructure and precision-driven architectural applications. Specification requirements, logistics economics, and batch-size flexibility determine how buyers navigate product categories and channel structures.
Product Type:
Standardization dominates bulk and ready-mix formats, while bagged and pre-mixed variants occupy the customization end of the spectrum with specification-tuned formulations.
- Bagged:50kg sacks deliver the highest margin capture through architectural-grade brightness certification and controlled moisture protection. Demand concentrates in Gauteng's premium residential tower segment where developers specify SABS-certified supply for terrazzo and pigmented mortar applications facing strict color consistency requirements.
- Bulk:Pneumatic tanker delivery anchors continuous pour schedules for commercial infrastructure with volume pricing and priority allocation during supply tightness. The format sacrifices specification flexibility for cost efficiency in large-scale precast cladding and structural concrete.
- Pre-mixed:Factory-blended formulations with integrated pigments and performance additives reduce on-site labor variability for decorative concrete resurfacing contracts.
- Ready-mix:Batching plant integration represents the steepest expansion trajectory as contractors seek to eliminate silo contamination risks and compress delivery cycles.
Leading the category by volume: Bulk. Expanding most quickly: Ready-mix.
End Use Industry:
Application maturity separates established construction verticals from emerging specification-driven segments reshaping procurement criteria.
- Residential Construction:High-end developments in Johannesburg and Pretoria drive specification for thermally reflective exterior finishes under pending building energy efficiency amendments. The segment demands certified low-carbon documentation for green building ratings.
- Commercial Infrastructure:Office towers and retail complexes anchor bulk volume flows with continuous pour schedules and multi-phase procurement bundling.
- Industrial Projects:Manufacturing facilities and logistics parks require standard gray-to-white switching capacity for aesthetic accent elements.
- Architectural Finishes:Terrazzo, precast cladding, and decorative concrete command premium pricing through reflectance values exceeding 80 percent on the L scale.
Architectural finishes capture the highest margin pool. Commercial infrastructure moves the largest tonnage.
Distribution Channel:
Channel selection tracks buyer scale and specification complexity, with direct relationships displacing traditional merchant intermediaries among tier-one developers.
- Direct Sales:National construction groups bypass distributors to secure volume pricing and priority allocation through manufacturer relationships spanning multiple project phases.
- Retail Outlets:Independent merchants serve small-scale contractors and renovation specialists with bagged product and technical advisory support.
- Distributors:Regional wholesalers maintain coastal and inland inventory positions for mid-tier developers lacking direct manufacturer access.
- Online Platforms:Digital procurement channels remain nascent but are gaining traction among specification engineers researching certified product documentation.
Direct sales dominate premium project procurement. Online platforms are gaining share fastest among technical specification researchers.
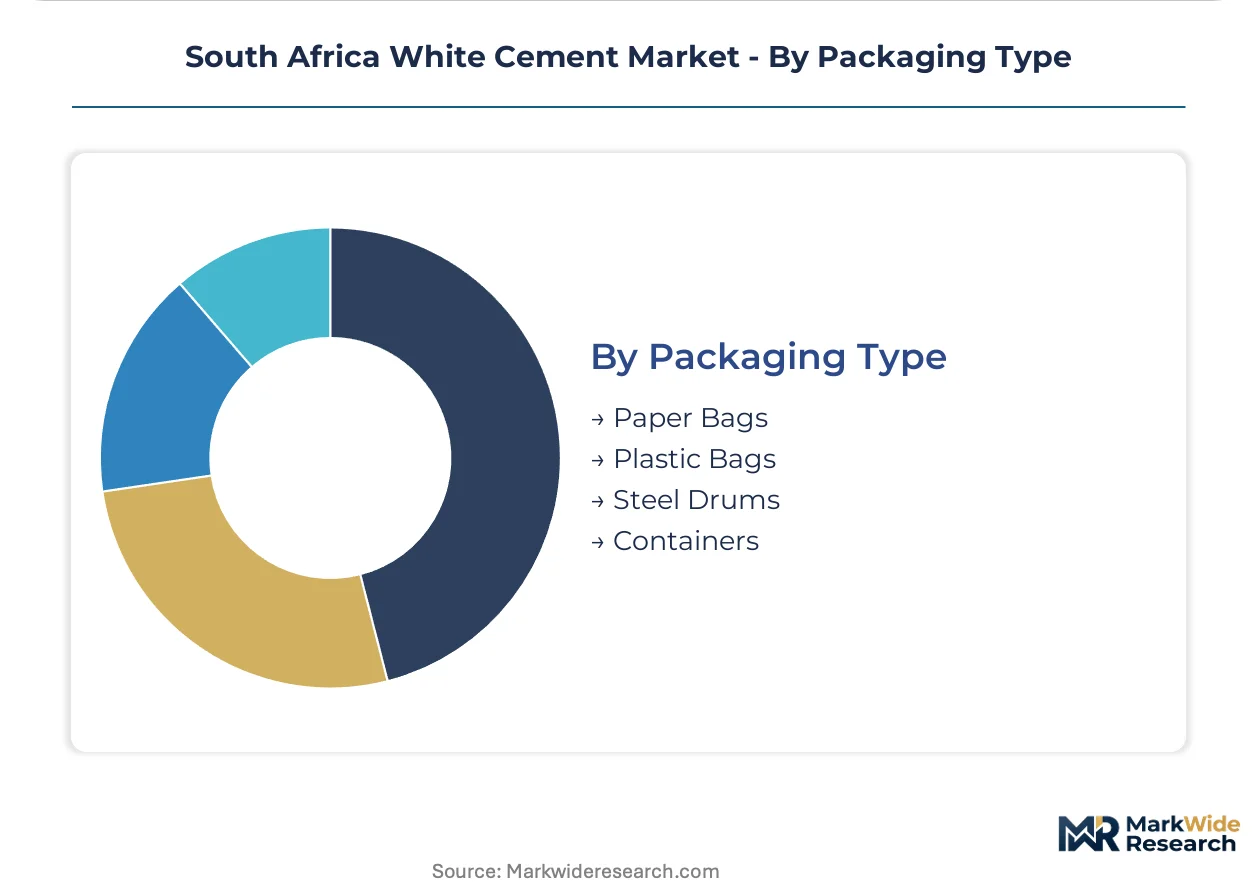
Packaging Type:
Material selection balances moisture protection, handling economics, and sustainability positioning across the value chain.
- Paper Bags:Multi-layer kraft construction with polyethylene barriers remains the standard for 50kg architectural-grade shipments requiring breathability and moisture resistance.
- Plastic Bags:Polypropylene woven sacks offer superior tear resistance for rough handling environments and humid coastal logistics corridors.
- Steel Drums:Sealed metal containers protect specialty pre-mixed formulations with integrated pigments during extended storage.
- Containers:Flexible intermediate bulk containers and tanker-based systems serve ready-mix and bulk delivery formats with reduced packaging waste.
Paper bags lead by shipment volume. Container-based delivery is climbing the fastest as batching plants seek packaging waste reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
White cement production concentrates in coastal and inland kiln clusters, while consumption pulls disproportionately toward Gauteng's commercial corridor. Domestic clinker capacity struggles to match specification-grade demand, forcing selective import flows through Durban and Cape Town harbors.
Gauteng Province
Johannesburg and Pretoria generate the bulk of architectural-grade white cement consumption through premium residential towers and commercial facades. The National Regulator for Compulsory Specifications enforces SABS EN 197 compliance that filters procurement toward certified domestic producers. Midrand and Sandton host specification engineering clusters where developers bundle multi-phase procurement across entire project portfolios.
KwaZulu-Natal
Durban anchors port-adjacent bulk handling infrastructure that enables both import reception and export positioning into Sub-Saharan markets. The provincial transport department prioritizes thermally reflective exterior finishes in public building retrofits under pending energy efficiency mandates. Pinetown and Richards Bay concentrate blending and distribution facilities serving coastal construction corridors.
Western Cape
Cape Town's high-end residential developments drive specification for pigmented mortar and terrazzo applications requiring L-scale reflectance above 80 percent. The city's carbon tax exposure pressures developers to document low-carbon material sourcing for green building ratings. Stellenbosch and Paarl anchor precast cladding manufacturing clusters supplying architectural finish contractors.
Eastern Cape
Port Elizabeth and East London combine automotive manufacturing aesthetics with emerging commercial construction demand for white cement accent elements. The provincial housing department pilots decorative concrete resurfacing in maintenance contracts for public infrastructure. Coega Industrial Development Zone attracts batching plant investment seeking reduced logistics costs for continuous pour schedules.
South Africa White Cement Market Key Industry Players
Top-tier vendors anchor integrated quarry-to-distribution networks, while mid-tier specialists compete on dedicated production lines and specification flexibility. The market structure splits between coastal logistics controllers and inland production specialists. Three archetypes dominate: integrated building materials conglomerates with captive limestone reserves, cement specialists operating dedicated white production facilities, and import-dependent distributors serving niche architectural segments. Competitive moves concentrate on alternative fuel substitution investments and direct sales relationships with tier-one developers.
Among South Africa-based producers, PPC Ltd and Sephaku Cement exemplify the dedicated-production archetype, while LafargeHolcim South Africa occupies a position within the integrated coastal logistics tier. Afrimat represents the construction materials diversification model, leveraging aggregate and readymix synergies. Cemex South Africa and Dangote Cement South Africa sit within import-supplemented domestic supply strategies. Çimsa, Cementir Holding, and SOTACIB anchor the international specialist tier serving specification-grade demand through selective export positioning.
| Leading Market Players |
|---|
| Afrimat |
| Cemex South Africa |
| PPC Ltd |
| SOTACIB |
| Çimsa |
| Sephaku Cement |
| LafargeHolcim South Africa |
| Cementir Holding |
| Dangote Cement South Africa |
| Others |
Cost & Logistics Intelligence
Tier-one developer procurement bundling across Gauteng's premium residential towers forces supply prioritization toward direct manufacturer relationships, compressing distributor margins and elevating volume-based pricing leverage for certified domestic producers.
Pricing Analysis
Margin tightening in bagged architectural-grade product reflects SABS EN 197 certification costs and low-iron limestone scarcity. Three-tier pricing structure across certified premium, standard construction, and gray-switching economy levels separates specification-grade brightness from commodity alternatives. Cost compression intensifies as carbon tax penalties escalate kiln operating expenses. Small-scale contractors exhibit highest price sensitivity, while national construction groups absorb premiums for priority allocation guarantees.
Supply Chain Analysis
Single-source vulnerability sits with European and Asian pigment suppliers for performance additives. Domestic clinker production draws from limited low-iron limestone quarries in Limpopo and Mpumalanga, supplemented by selective imports through Durban and Cape Town harbors. Currency fluctuation exposure runs through specialty additive procurement channels. Distribution runs through coastal bulk handling infrastructure controlled by integrated producers, with inland pneumatic tanker networks serving continuous pour schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SABS compliance mandates and carbon tax escalation are forcing marginal gray-to-white switching capacity offline, consolidating viable supply among dedicated production specialists with certified clinker sourcing.
For Market Incumbents: To counter ready-mix channel displacement of traditional bagged distribution, deepen direct relationships with national construction groups through multi-phase procurement bundling and accelerate alternative fuel co-processing investments to defend margin position against carbon tax penalties. For New Entrants and Emerging Players: Pending amendments to building energy efficiency regulations in South Africa open a window for thermally reflective exterior finish specialists to establish specification engineering relationships with Midrand and Sandton developer clusters before incumbent certification timelines compress. For Investors and Strategic Acquirers: The window for entry favors coastal logistics controllers with port-adjacent bulk handling infrastructure and captive limestone reserves. Long-term viability hinges on positioning for Sub-Saharan export corridors. Monitor SABS testing protocol amendments as the signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Co-processing Investment | Carbon tax compliance at PPC Ltd and Sephaku Cement facilities reduces penalty exposure while securing operational continuity. |
| Direct Manufacturer Relationship Expansion | Bypassing merchant distributors captures tier-one developer procurement bundling across Johannesburg premium tower portfolios. |
| Coastal Bulk Handling Infrastructure Control | Durban and Cape Town port positioning enables Sub-Saharan export flows into underdeveloped domestic production markets. |
| LC3 Formulation Modularization | Calcined clay integration at Gauteng batching plants reduces clinker dependency while maintaining L-scale brightness thresholds. |
| Decorative Concrete Resurfacing Service Launch | Maintenance contract models monetize white cement beyond initial material sales through recurring commercial property refurbishment revenue. |
Research Approach
Independent corroboration across kiln operations executives, ready-mix procurement leads, specification engineers at Midrand developer clusters, and SABS certification officers underwrites the qualitative findings. Secondary validation drew from National Treasury carbon tax framework documentation, NRCS compulsory specifications registers, customs import records for clinker and pigment flows, and SEC filings of listed building materials conglomerates. Bottom-up demand modeling across Gauteng, KwaZulu-Natal, Western Cape, and Eastern Cape construction corridors triangulated against top-down production capacity assessments.
Rate-of-change decomposition across the analysis window separated volume growth from price trajectory and mix shift effects. Segmentation dimensions modeled include product format (bagged, bulk, pre-mixed, ready-mix), end-use vertical (residential, commercial, industrial, architectural finishes), and distribution channel structure (direct sales, retail, distributor, online). CAGRs derived from logistic curve fitting against historical construction spend correlations and clinker capacity utilization rates. Industry-specific inputs incorporated alternative fuel substitution timelines and SABS certification pipeline backlogs.
The model assumes a particular technology adoption path for LC3 formulations; alternative pathways for calcined clay integration would alter the outlook. Deviation in National Treasury carbon tax amendment severity or NRCS testing protocol timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete Admixtures Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
East Africa Wall Putty Market
Building Materials
Qatar Cement Market
Building Materials
Global Pozzolan Market
Building Materials
Solar Control Window Film Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Rubbing Bricks Market
Building Materials
Basalt Rock Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
India Concealed Cistern Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Foam Bricks Market
Building Materials
France Architectural Coatings Market
Building Materials
Construction Stone Market