
 Asia-Pacific Building and Construction Sheets Market | 2026-2036
Asia-Pacific Building and Construction Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Building and Construction Sheets Market Outlook
Modular roofing kits is decoupling traditional bulk sheet purchasing across Asia-Pacific construction sites, letting buyers mix polycarbonate skylight modules with steel purlin systems rather than committing to single-source bundles. Fletcher Building leverages its Australasian manufacturing footprint to supply standardized modular panels across diverse climate zones. Hindalco Ind Ltd anchors aluminum-sheet output to India's expanding metro rail and airport terminal projects. Mitsubishi Chemical specializes in optical-grade polycarbonate diffusion layers that differentiate its offering from commodity extruders.
Asia-Pacific building and construction sheets comprise flat or profiled planar materials—typically 0.4 mm to 12 mm in thickness, manufactured through extrusion, rolling, or pressing processes—engineered for weather protection, structural enclosure, and thermal insulation in built environments. Steel sheets dominate volume flows across infrastructure projects given their load-bearing capacity and fire resistance, while polycarbonate sheets capture premium margin pools in commercial building daylighting applications where UV stabilization and impact resistance specifications tighten. Fiber cement boards compete aggressively in residential properties across tropical humidity zones where termite resistance and moisture dimensional stability determine specification.
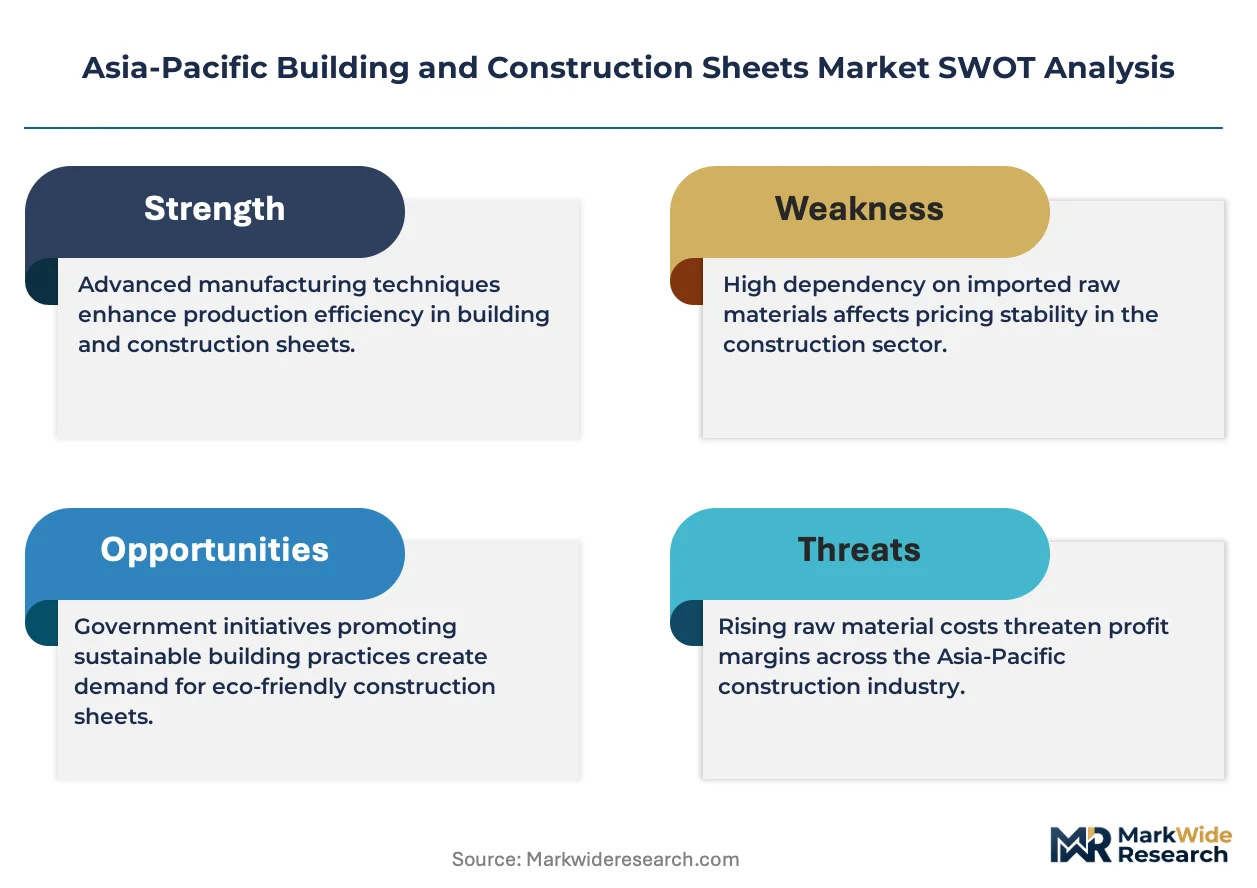
India's BIS mandates IS 277 for galvanized steel sheets and IS 14862 for fiber reinforced cement flat sheets, forcing reformulation of legacy products to access government contractor procurement channels. China's GB/T 12754 color-coated steel sheet standard and green building rating systems under MEE dual carbon goals redirect specification toward lower-emission coating chemistries and recycled content thresholds. Australia's NCC energy efficiency provisions for building envelopes tighten U-value requirements that favor insulated composite panel systems over single-skin metal roofing. Stakeholders must monitor diverging national compliance calendars and pre-certify sheet systems against the strictest applicable standard in their target project pipeline.
Market Dynamics
Modular roofing kits are fragmenting traditional bulk sheet procurement across Asia-Pacific construction sites, compelling manufacturers to reconfigure product portfolios around mix-and-match component systems rather than bundled offerings. This structural shift forces sheet suppliers to develop interoperable fastening and sealing technologies while ceding margin capture to specialized purlin and frame system providers.
Growth Catalysts
- India's PLI scheme for specialty steel:Production-linked incentives for coated steel products redirect domestic mill capacity toward construction-grade output, expanding local supply for infrastructure cladding applications.
- Metro rail terminal construction:Aluminum composite panel demand concentrates in station roof and facade systems across Southeast Asian urban transit networks, pulling sheet consumption into transportation-adjacent building categories.
- China's dual carbon goals:MEE enforcement of lower-emission coating chemistries accelerates specification of waterborne and powder-coated metal sheets in green building certification pathways.
Market Restraints
- Galvanized steel input cost volatility:Zinc price swings transmit directly to roofing sheet pricing, compressing fabricator margins and triggering project payment renegotiations.
- Polycarbonate resin supply concentration:Bisphenol A and phosgene feedstock dependence on Northeast Asian chemical complexes creates single-source vulnerability for optical-grade sheet producers.
- Fiber cement dimensional stability limits:High-humidity tropical climates constrain product warranties and accelerate replacement cycles versus metal alternatives.
Strategic Opportunities
- Vietnam's industrial corridor expansion:Northern manufacturing zones around Hai Phong and Bac Ninh generate concentrated demand for insulated sandwich panel systems in factory construction.
- Photovoltaic-integrated roofing:Building-integrated solar modules converge with standing-seam metal substrates, creating dual-function sheet categories for commercial warehouse developers.
- Australia's NCC Section J energy provisions:U-value performance mandates favor insulated composite panels over single-skin metal roofing in envelope specifications.
Industry Challenges
- BIS certification timeline compression:India's mandatory IS 277 and IS 14862 testing protocols extend product launch cycles by 4-6 months for imported sheet systems.
- Skilled installer scarcity:Modular kit assembly requires trained crews proficient in both polycarbonate thermal expansion management and steel purlin alignment, constraining rollout velocity.
- Legacy warehouse inventory incompatibility:Existing stock of non-interoperable fastening hardware blocks rapid adoption of new modular systems without full material write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Building and Construction Sheets Market |
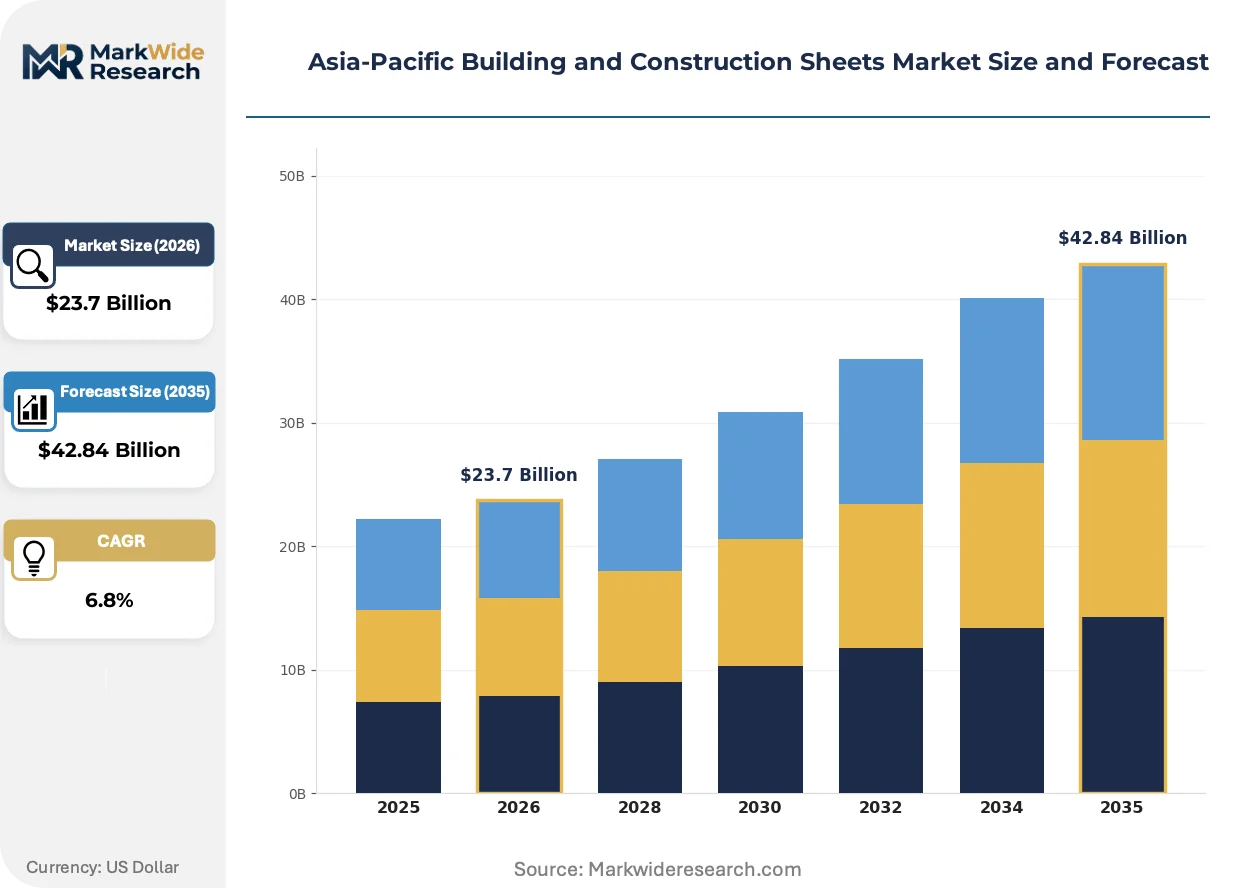
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate Sheets, Plywood, Steel Sheets, Fiber Cement Boards Application: Commercial Buildings, Residential Properties, Industrial Facilities, Infrastructure Projects Material Type: Plastic, Metal, Wood, Composites End User: Contractors, Architects, Builders, Developers |
| Companies Covered | Fletcher Building Limited, Mitsubishi Chemical, Hindalco Ind Ltd, Asia Poly Industrial Sdn Bhd, Raychung Acrylic, Shen Chuen Acrylic, Kansal Colour Roofings India Pvt. Ltd, Exodus Ispat Pvt. Ltd, Bansal Roofing Products Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Building and Construction Sheets Market Strategic Shifts
Material convergence and regulatory tightening are compressing traditional product category boundaries across Asia-Pacific building envelope markets. Sheet manufacturers now compete on system integration capability rather than standalone material performance.
Multiwall polycarbonate diffusion technology is absorbing daylighting specification share from conventional glass in commercial atrium and skylight applications. Australian and Japanese commercial developers specify 16mm and 20mm cellular structures for thermal performance compliance. This absorption is compressing commodity extruder margins while rewarding optical-grade specialists with premium positioning.
China's GB/T 12754 color-coated steel standard revisions under MEE jurisdiction are phasing out solvent-borne coating systems. Domestic mills reformulate primer and topcoat chemistries to meet volatile organic compound thresholds. Southeast Asian import-dependent markets face compliance documentation burdens that favor certified Chinese suppliers over regional traders.
Buyers in India's western industrial states now unbundle roofing procurement into separate purlin, sheet, and insulation contracts. Large commercial developers direct-source structural components through metal fabrication channels while retaining sheet specification authority. This disintermediation is visible across Gujarat and Maharashtra warehouse construction, where traditional roofing system integrators lose package-deal control.
Asia-Pacific Building and Construction Sheets Market Segmentation
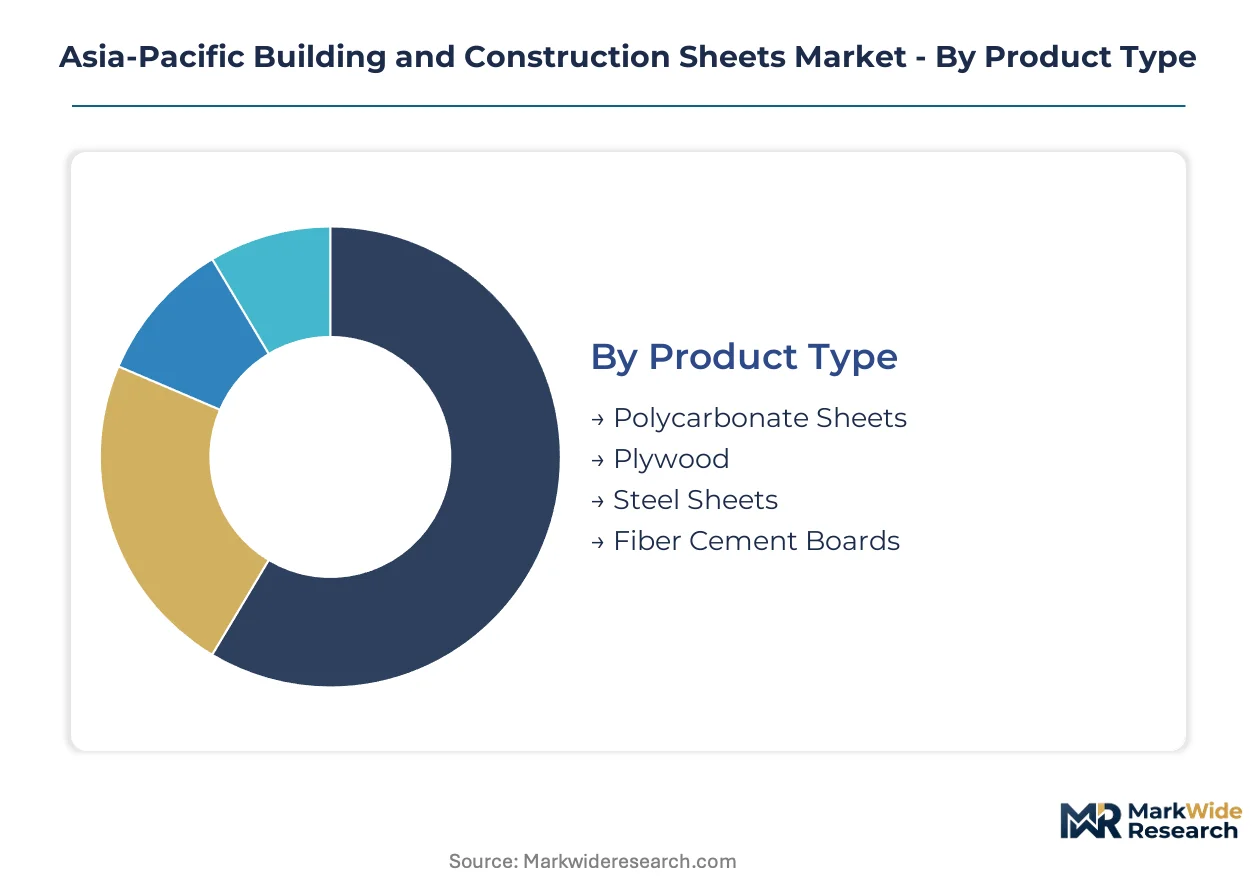
Segmentation in Asia-Pacific building and construction sheets reveals divergent margin structures across material categories. Steel and fiber cement compete on installed cost per square meter, while polycarbonate commands specification premiums through optical performance guarantees.
Product Type:
Steel sheets dominate volume flows across infrastructure tenders, while polycarbonate captures daylighting premiums in commercial atrium specifications.
- Polycarbonate Sheets:Multiwall cellular structures ranging 4mm to 40mm thickness deliver UV-stabilized light transmission for skylight and facade applications. Australian and Japanese commercial developers specify 16mm and 20mm configurations for thermal compliance, absorbing share from conventional glass in atrium construction.
- Steel Sheets:Galvanized and color-coated cold-rolled products from 0.4mm to 2.0mm thickness provide structural roofing and cladding across industrial and infrastructure projects. India's PLI scheme for specialty steel redirects domestic mill capacity toward construction-grade coated output, expanding local supply for government contractor procurement channels.
- Plywood:Structural and non-structural grades serve formwork and temporary enclosure applications across residential construction in Southeast Asian markets.
- Fiber Cement Boards:Cellulose-reinforced calcium silicate compositions compete in tropical humidity zones where termite resistance determines residential specification.
Today's leader: Steel Sheets. Tomorrow's challenger: Polycarbonate Sheets.
Application:
Commercial building envelopes generate the steepest expansion trajectory as developers unbundle roofing procurement across India's western industrial states.
- Commercial Buildings:Office towers, retail complexes, and hospitality structures specify composite panel systems and polycarbonate daylighting modules. Metro rail terminal construction across Southeast Asian urban networks concentrates aluminum composite panel demand in station roof and facade systems.
- Industrial Facilities:Factory construction in Vietnam's northern manufacturing zones around Hai Phong and Bac Ninh generates concentrated demand for insulated sandwich panel systems with standing-seam metal substrates.
- Residential Properties:Single-family and multi-unit housing drives fiber cement board consumption across tropical markets where moisture dimensional stability constrains product warranties.
- Infrastructure Projects:Airports, bridges, and transportation corridors specify load-bearing steel sheet systems with fire resistance certifications under BIS IS 277 and China's GB/T 12754 standards.
Commercial Buildings command current specification authority. Industrial Facilities are climbing the fastest as manufacturing corridor development accelerates.
Material Type:
Metal and plastic categories are converging through photovoltaic-integrated roofing modules that merge standing-seam substrates with building-integrated solar functionality.
- Metal:Steel, aluminum, and coated ferrous alloys provide structural enclosure with recycled content thresholds increasingly specified under China's MEE dual carbon enforcement.
- Plastic:Polycarbonate and PVC formulations capture daylighting and temporary enclosure applications where impact resistance and thermal expansion management determine installer qualification requirements.
- Wood:Plywood and engineered timber products serve formwork and aesthetic interior cladding in markets with established sustainable forestry certification chains.
- Composites:Fiber-reinforced polymer and aluminum composite panel systems integrate insulation layers for Australia's NCC Section J energy compliance.
Metal retains volume dominance. Composites are gaining share fastest through regulatory pressure on envelope thermal performance.
End User:
Procurement authority is fragmenting as large developers direct-source structural components while retaining sheet specification control.
- Developers:Commercial and industrial project sponsors unbundle roofing contracts across Gujarat and Maharashtra warehouse construction, separating purlin, sheet, and insulation procurement into distinct vendor relationships.
- Contractors:Installation firms face skilled crew scarcity for modular kit assembly requiring proficiency in both polycarbonate thermal expansion management and steel purlin alignment.
- Architects:Design professionals specify optical-grade polycarbonate diffusion layers and insulated composite panels to meet green building certification pathways and energy efficiency mandates.
- Builders:Residential construction firms select fiber cement and plywood products based on termite resistance and moisture stability in tropical climate zones.
Developers hold current procurement control. Architects are expanding influence fastest through green building specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel sheet manufacturing scaled first in Japan's post-war industrialization, then migrated to South Korea and China as coastal mill complexes achieved economies of scale in cold-rolling and coating operations. Today's Asia-Pacific market distributes capacity across multiple national regulatory jurisdictions with diverging compliance calendars.
China
MEE enforcement of GB/T 12754 color-coated steel standards is phasing solvent-borne coating systems from domestic mill output. Dual carbon goals redirect specification toward waterborne and powder-coated metal sheets with recycled content thresholds. Yangtze River Delta fabricators around Shanghai supply Southeast Asian import markets with certified low-emission products.
India
BIS mandates IS 277 for galvanized steel and IS 14862 for fiber cement sheets, extending product launch cycles for imported systems. The PLI scheme for specialty steel redirects domestic mill capacity toward construction-grade coated output. Gujarat and Maharashtra warehouse developers unbundle roofing procurement into separate purlin, sheet, and insulation contracts.
Vietnam
Northern manufacturing zones around Hai Phong and Bac Ninh generate concentrated demand for insulated sandwich panel systems in factory construction. The country's national construction regulator tightens fire resistance documentation for imported steel sheet systems. Industrial corridor expansion pulls specification authority toward direct developer sourcing rather than traditional system integrators.
Australia
NCC Section J energy efficiency provisions tighten U-value requirements that favor insulated composite panel systems over single-skin metal roofing. The national building code regulator enforces envelope performance mandates that redirect commercial specification. Melbourne and Sydney commercial developers specify 16mm and 20mm multiwall polycarbonate for atrium daylighting compliance.
Japan
METI industrial standards for optical-grade polycarbonate diffusion layers differentiate premium positioning from commodity extruders. Kanto region commercial developers absorb specification share from conventional glass in skylight applications. Tokyo-based chemical specialists supply 16mm cellular structures to Australian and Southeast Asian green building certification pathways.
Asia-Pacific Building and Construction Sheets Market Competitive Environment
Premium-margin players sit above commodity-margin players across optical performance and thermal compliance dimensions, with polycarbonate specialists capturing daylighting premiums while steel fabricators compete on installed cost per square meter. The vendor base spans Australasian building materials conglomerates, Japanese chemical specialists, and Indian aluminum and steel producers. Three archetypes dominate: integrated building materials suppliers with regional manufacturing footprints, chemical specialists with optical-grade extrusion capabilities, and domestic metals producers anchored to government infrastructure procurement. Competitive moves concentrate on modular system interoperability partnerships and pre-certification against multiple national standards.
Within the integrated materials tier, Fletcher Building Limited represents the Australasian archetype with standardized panel supply across diverse climate zones. Among chemical specialists, Mitsubishi Chemical occupies a position exemplifying optical-grade polycarbonate differentiation. On the domestic metals vector, Hindalco Ind Ltd anchors aluminum-sheet output to India's expanding metro rail and airport terminal projects. These three companies illustrate the geographic and technological segmentation governing competitive positioning across national procurement channels.
| Leading Market Players |
|---|
| Fletcher Building Limited |
| Mitsubishi Chemical |
| Hindalco Ind Ltd |
| Asia Poly Industrial Sdn Bhd |
| Raychung Acrylic |
| Shen Chuen Acrylic |
| Kansal Colour Roofings India Pvt. Ltd |
| Exodus Ispat Pvt. Ltd |
| Bansal Roofing Products Ltd |
| Others |
Value Chain & Pricing Dynamics
India's BIS certification mandates for IS 277 galvanized steel and IS 14862 fiber cement sheets are forcing imported systems through extended testing protocols, compelling regional mills to absorb compliance costs into contract pricing while ceding margin to domestic certified suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Asia-Pacific sheet procurement, with optical-grade polycarbonate diffusion layers commanding certification premiums against commodity extruder output. Price differentiation rests on BIS/GB compliance tier and thermal performance specification, with India's PLI-scheme domestic mills gaining leverage over import-dependent traders. Cost compression in standard-grade steel roofing intensifies because zinc input volatility transmits directly to fabricator margins. Government contractors exhibit highest price sensitivity due to tender-based procurement, while Australian commercial developers prioritize NCC Section J thermal compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Northeast Asian chemical complexes for bisphenol A and phosgene feedstocks that optical-grade polycarbonate producers require. Manufacturing gravity centers on China, India, and Vietnam, with Yangtze River Delta mills supplying Southeast Asian import markets and Gujarat-based steel fabricators serving domestic infrastructure tenders. Raw material dependencies span zinc ingots for galvanization, cellulose pulp for fiber cement, and aluminum coil for composite panel systems. Tariff exposure on Chinese color-coated steel imports into Vietnam constrains procurement flexibility. Distribution runs through direct developer sourcing channels across India's western industrial states, displacing traditional roofing system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific building and construction sheets function as a stable compounder anchored to infrastructure-led urbanization across Southeast Asian manufacturing corridors and India's metro rail expansion.
For Market Incumbents: Lock in modular system interoperability partnerships with purlin and frame specialists before procurement fragmentation accelerates. Invest in pre-certification against India's BIS timelines and Australia's NCC energy provisions to defend specification authority. Backward integration into coating chemistries mitigates MEE dual carbon compliance costs. For New Entrants and Emerging Players: Regional traders with GB/T 12754 documentation access can capture share in Vietnam's northern industrial zones around Hai Phong and Bac Ninh where factory construction concentrates demand. Target photovoltaic-integrated roofing modules for commercial warehouse developers seeking dual-function sheet categories. Partner with skilled installer training networks to overcome modular kit assembly scarcity. For Investors and Strategic Acquirers: Asymmetric upside sits with optical-grade polycarbonate specialists possessing METI-compliant diffusion layer capabilities. Five-to-ten year viability favors chemical specialists over commodity steel fabricators given regulatory tightening on coating emissions. Watch for BIS certification timeline compression as inflection signal favoring domestic Indian producers.| Strategic Initiative | Industry Significance |
|---|---|
| Modular System Interoperability Partnership | Enables mix-and-match procurement unbundling that Gujarat and Maharashtra developers now demand. |
| BIS Pre-Certification Investment | Compresses product launch cycles for imported systems competing in Indian government contractor channels. |
| Backward Integration into Coating Chemistries | Captures margin from waterborne and powder-coated metal sheet transitions under MEE enforcement. |
| Photovoltaic-Integrated Roofing Development | Converges standing-seam substrates with building-integrated solar for commercial warehouse specifications. |
| Optical-Grade Extrusion Capacity Expansion | Absorbs daylighting specification share from conventional glass in Australian and Japanese atrium projects. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at regional steel mills, procurement leads at Indian commercial developers, distribution channel partners across Southeast Asia, and technical R&D directors at polycarbonate extrusion facilities with secondary validation through customs and trade data, BIS certification registries, China's GB standards documentation, and SEC filings from listed building materials conglomerates. Bottom-up project pipeline assessments and top-down macro construction forecasts were triangulated for convergence.
Segment-weighting across material type, application, and end-user procurement authority shaped the analytical framework over the projection horizon. Modeled dimensions included steel versus polycarbonate versus fiber cement product categories, commercial versus industrial versus residential application splits, and developer-led versus contractor-led procurement patterns. CAGRs were derived from installed base growth, replacement cycle dynamics, and regulatory-driven specification shifts. Industry-specific inputs incorporated India's PLI scheme capacity additions and Australia's NCC Section J adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to zinc price volatility, BIS certification timeline changes, and MEE dual carbon enforcement intensity. Forecasts reflect documented assumptions on infrastructure spending trajectories and green building certification adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
North America Cement Market
Building Materials
Global Pozzolan Market
Building Materials
East Africa Cement Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Iron and Steel Slag Market
Building Materials
Italy Facade Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
West Africa Cement Market
Building Materials
France Architectural Coatings Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Cladding Market
Building Materials
Sanded Grout Market