
 East Africa Cement Market | 2026-2036
East Africa Cement Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Cement Market Intelligence
Skilled kiln operator shortages across the region is redrawing competitive boundaries for producers scaling clinker capacity. Dangote Cement leverages its integrated quarry-to-dispatch model to control raw material security across multiple East African markets. Bamburi Cement Limited anchors its position through coastal logistics dominance serving Kenyan and neighboring export demand. East African Portland Cement PLC competes on heritage brand recognition and institutional procurement relationships built over decades.
East Africa cement comprises hydraulic binding materials manufactured through calcination of limestone, clay, and corrective materials at approximately 1450°C, followed by grinding with gypsum to achieve specified fineness and compressive strength ratings. Ordinary Portland cement dominates volume flows for standard concrete applications, though blended cement variants are gaining specification share as durability requirements for coastal and sulfate-exposed infrastructure tighten. Infrastructure Development applications command the largest demand block, while Residential Construction segments show the steepest growth trajectory as mortgage finance penetration deepens in urban Kenya and Ethiopia.
Kenya's National Construction Authority enforces KS EAS 18 cement standards alongside EAC harmonization protocols, while Ethiopia's Ethiopian Conformity Assessment Enterprise certifies GB-equivalent product grades for federal projects. These frameworks elevate compliance costs for smaller mills but protect structural integrity in seismic and heavy-load applications. Stakeholders must weigh clinker import dependency against the capital intensity of domestic kiln investments as regional electricity reliability and carbon border considerations evolve.
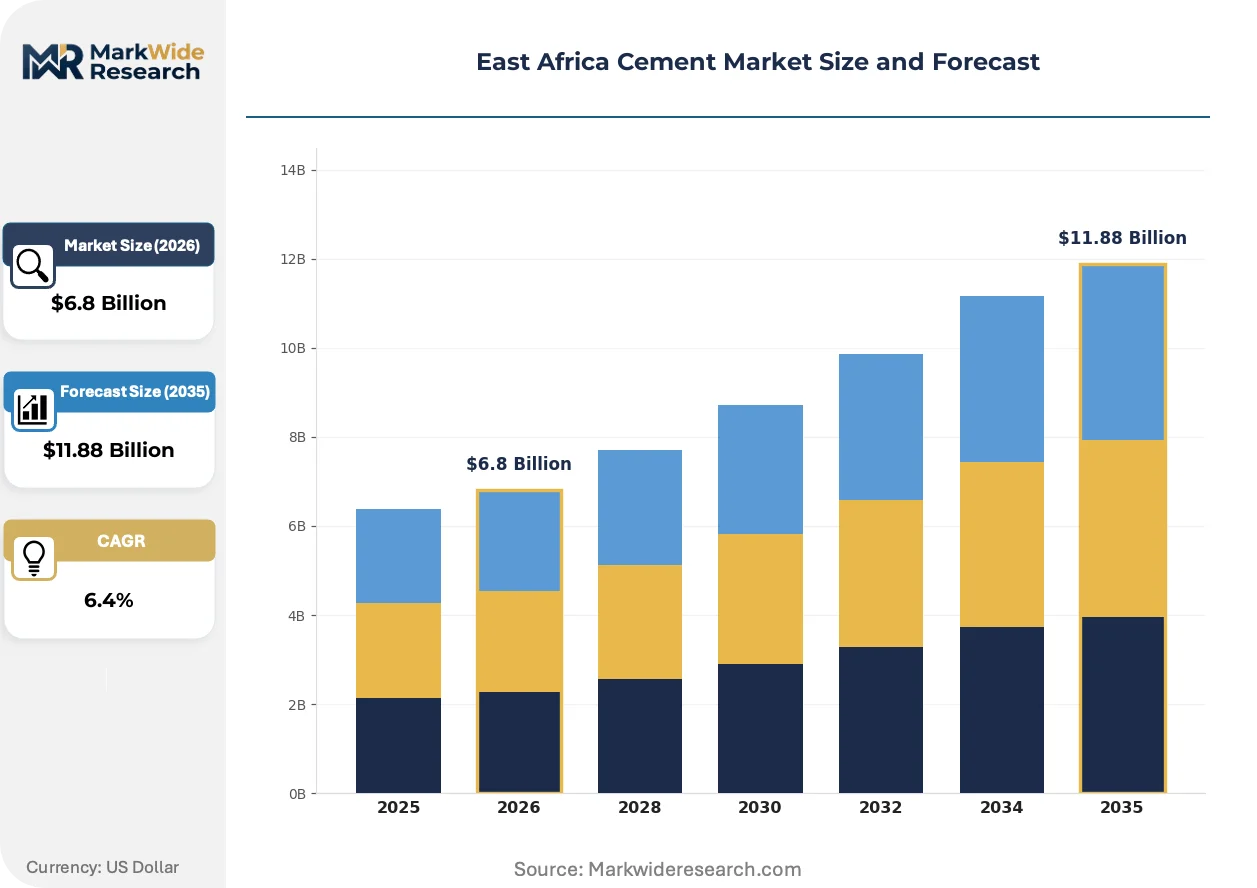
Market Dynamics
Government mega-infrastructure pipelines across Ethiopia, Kenya, and Tanzania are absorbing unprecedented cement volumes while clinker import dependency strains working capital cycles for domestic mills.
Growth Catalysts
- Ethiopian dam construction:Federal hydroelectric and industrial zone projects are pulling multi-million-tonne annual cement offtake through state-backed procurement channels.
- EAC harmonized standards:The East African Community's unified cement quality protocols are streamlining cross-border trade and raising entry barriers for substandard imports.
- Geothermal-powered kilns:Kenyan producers leveraging Rift Valley geothermal fields are securing baseload energy at stabilized tariffs versus grid-dependent competitors.
Market Restraints
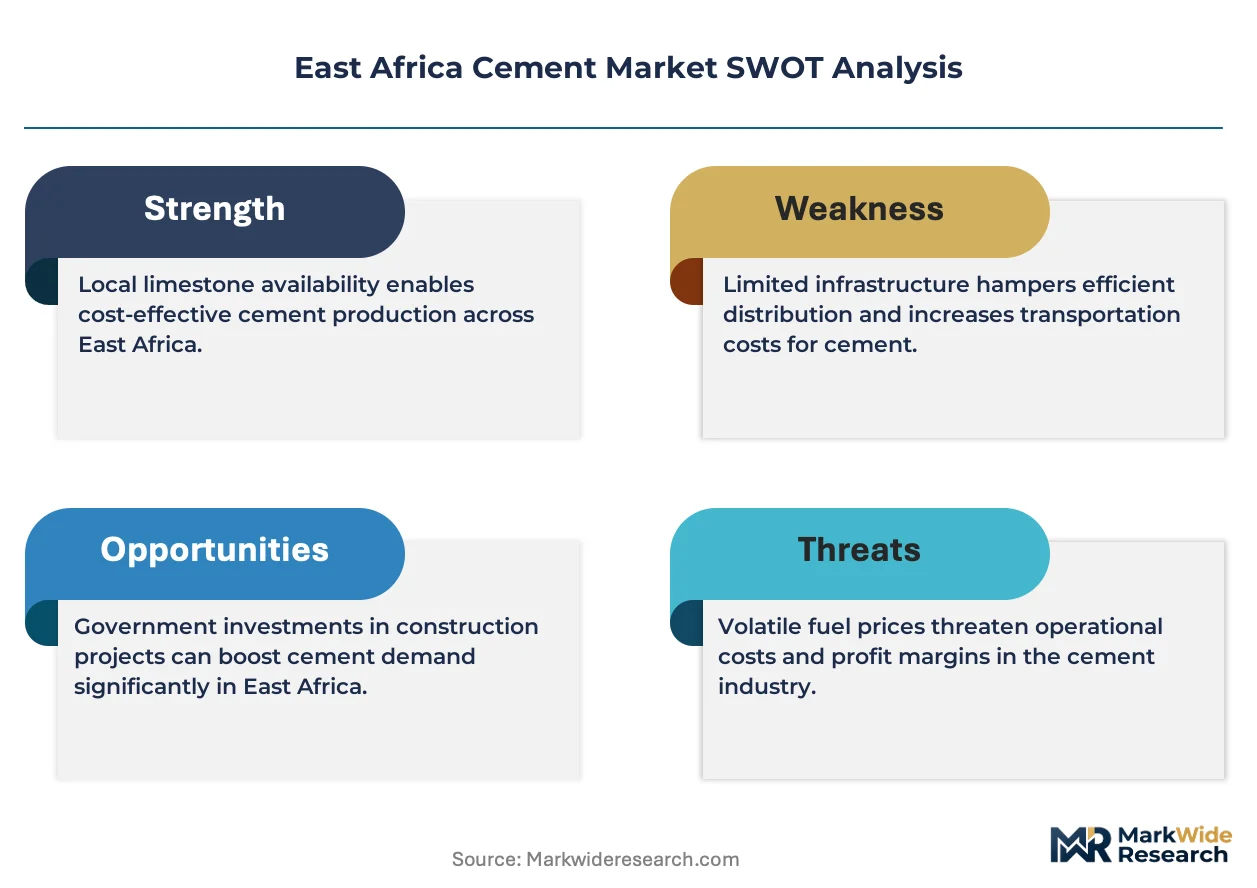
- Petcoke import concentration:Over 70% of East African clinker producers rely on Gulf-origin petroleum coke, exposing margins to Red Sea shipping disruptions and dollar-denominated volatility.
- Ethiopian forex rationing:The National Bank of Ethiopia's priority import licensing system delays spare parts procurement for FLSmidth and KHD Humboldt equipment.
- Limestone transport bottlenecks:Poorly surfaced haul roads between Mombasa and Nairobi raise delivered clinker costs versus coastal integrated plants.
Strategic Opportunities
- Tanzania's Lake Zone corridor:Underpenetrated demand in Mwanza and Bukoba offers first-mover advantages for grinding plants sourcing clinker from Tanga.
- Blended cement mandates:Kenyan building codes specifying 30% pozzolanic content create pull for local fly ash and volcanic pozzolana processing infrastructure.
- Digital dispatch platforms:Mobile-based logistics coordination is compressing truck turnaround times at Dar es Salaam and Mombasa terminals.
Industry Challenges
- Kiln operator certification:The East African Portland Cement PLC training pipeline produces fewer than 50 qualified rotary kiln specialists annually against regional expansion needs.
- Legacy ERP integration:Ethiopian state-owned mills running 1990s-era process control systems face multi-year migration timelines to ISO 27001-compliant architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Cement Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland, Blended Cement, Sulfate-Resistant, White Cement Application: Residential Construction, Commercial Projects, Infrastructure Development, Industrial Applications End User: Contractors, Government Projects, Real Estate Developers, DIY Homeowners Distribution Channel: Wholesale, Retail, Direct Supply, Online Sales |
| Companies Covered | Dangote Cement, Bamburi Cement Limited, East African Portland Cement PLC, ARM Cement PLC, Mombasa Cement Limited, Savannah Cement, Derba Midroc Cement, Mugher Cement, Messebo Cement, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Cement Market Strategic Shifts & Innovations
Alternative fuel substitution and digital quality assurance are compressing cost structures while EAC regulatory convergence rewrites competitive entry conditions across the region.
Calcined clay activation technology is supplanting traditional clinker content in blended cement formulations. Kenyan precast concrete producers are adopting LC3 (limestone calcined clay cement) at pilot scale for marine exposure applications. This substitution pathway is compressing per-tonne CO2 intensity while maintaining early-strength performance benchmarks specified under KS EAS 18.
Kenya's National Construction Authority revised enforcement protocols for KS EAS 18-1:2014 cement standards in 2023, mandating third-party laboratory verification for all federal project deliveries. Industrial consequence includes accelerated consolidation among testing laboratories and elevated compliance documentation burdens for smaller grinding operations. Kenyan residential developers are now specifying certified-origin cement in mortgage-financed construction, shifting procurement toward integrated producers with captive laboratory capacity.
Builder procurement patterns are fragmenting toward project-specific bulk contracts rather than annual framework agreements. Kenyan real estate developers and Ethiopian state contractors are negotiating shipment-lot pricing tied to immediate construction schedules, displacing the traditional 12-month offtake commitments that secured kiln utilization rates. This compression is most visible in Nairobi's mid-rise residential segment, where just-in-time concrete batching plants now hold 48-hour inventory versus the prior two-week stockholding norm.
East Africa Cement Market Segmentation
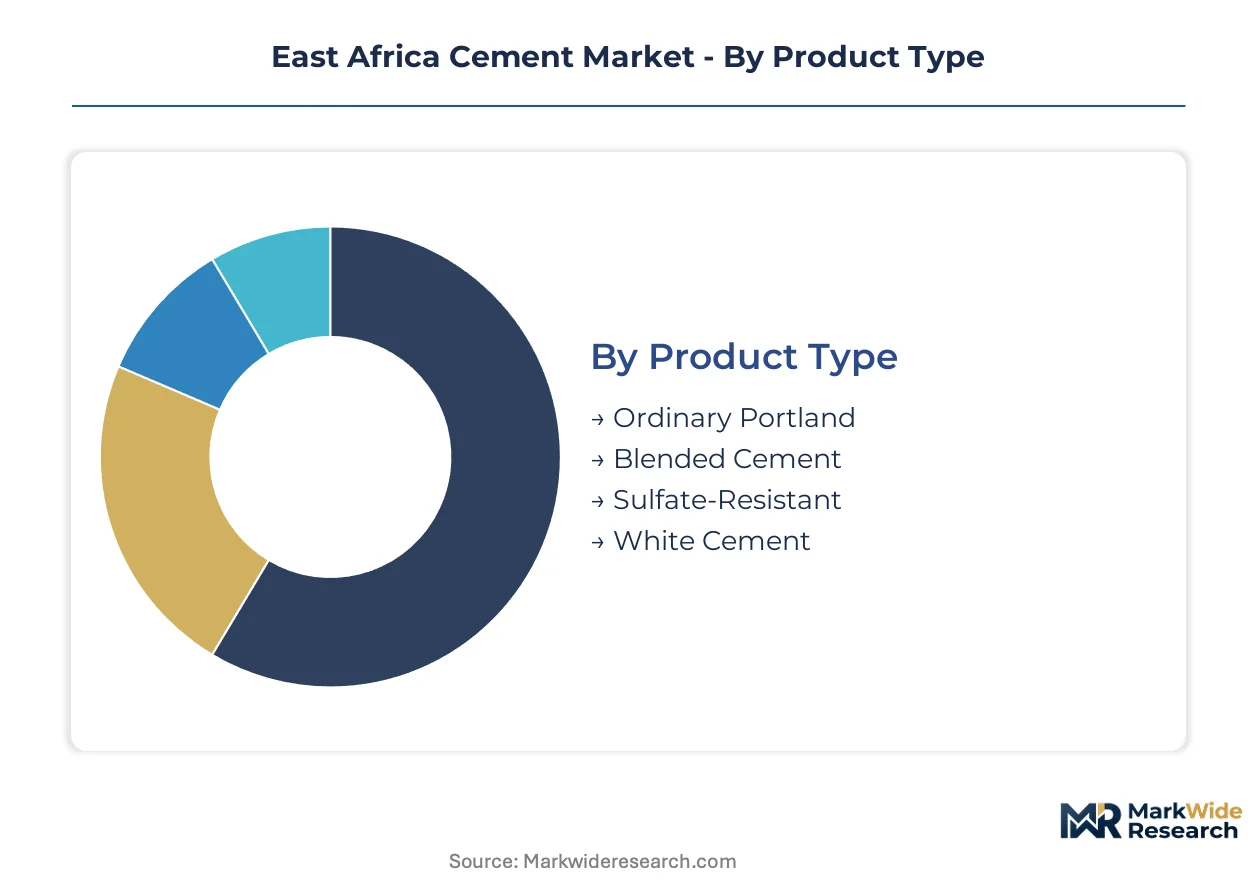
Cement flows through East African markets along distinct product-application-channel pathways that determine margin capture and working capital intensity. Understanding how Ordinary Portland cement diverges from specialty grades across procurement channels exposes where producers can defend pricing power versus where volume throughput dominates.
Product Type:
Distributor and direct-supply channels carry different product mixes, with bulk infrastructure procurement favoring standardized grades while retail networks stock higher-margin specialty formulations.
- Ordinary Portland:Composed of 95% clinker and 5% gypsum, this grade achieves compressive strength ratings per KS EAS 18 specifications. Demand concentrates in Ethiopian federal dam construction and Kenyan roadbuilding, where procurement runs through state-backed direct-supply contracts with price-indexed adjustments.
- Blended Cement:Incorporates 30-50% pozzolanic materials such as fly ash or volcanic tuff, reducing per-tonne CO2 intensity while meeting durability requirements. Kenyan coastal developers specify these grades for marine exposure applications, pulling volume through contractor-facilitated wholesale channels that aggregate multi-project demand.
- Sulfate-Resistant:Low C3A content below 5% protects against groundwater sulfate attack in foundation work.
- White Cement:Low-iron clinker formulations command premium positioning in decorative precast and architectural finishes.
Ordinary Portland dominates installed base. Blended cement is where expansion concentrates.
Application:
Cost tier stratification separates high-volume, price-competitive foundation work from specification-sensitive structural elements where certification premiums apply.
- Infrastructure Development:Mega-dam, highway, and rail projects absorb multi-million-tonne annual offtake through centralized procurement. Ethiopian federal contractors specify GB-equivalent grades with mandatory Ethiopian Conformity Assessment Enterprise certification, compressing eligible supplier pools.
- Residential Construction:Mid-rise apartment and single-family housing drives fastest volume expansion as mortgage finance penetration deepens in Nairobi and Addis Ababa. Kenyan developers favor 32.5R strength grades for cost-optimized slab and wall applications.
- Commercial Projects:Office and retail construction specifies higher early-strength cements to accelerate formwork cycling.
- Industrial Applications:Manufacturing plant foundations and silo construction require specialized sulfate-resistant formulations.
Infrastructure commands procurement scale. Residential construction is climbing the fastest.
End User:
Customer type determines payment terms, with government projects extending 90-180 day cycles against cash-before-delivery retail patterns.
- Government Projects:Federal and state-backed infrastructure pipelines in Ethiopia, Kenya, and Tanzania absorb rising volumes through priority licensing channels. Procurement runs through centralized tender systems with bonded performance guarantees and extended payment horizons that strain working capital for non-integrated mills.
- Contractors:Mid-tier construction firms aggregate demand across multiple sites, negotiating shipment-lot pricing tied to immediate pour schedules rather than annual frameworks.
- Real Estate Developers:Nairobi and Dar es Salaam residential specialists specify certified-origin cement for mortgage-financed construction.
- DIY Homeowners:Small-batch retail purchases concentrate in peri-urban hardware networks.
Government projects anchor volume commitments. Contractors are gaining share fastest.
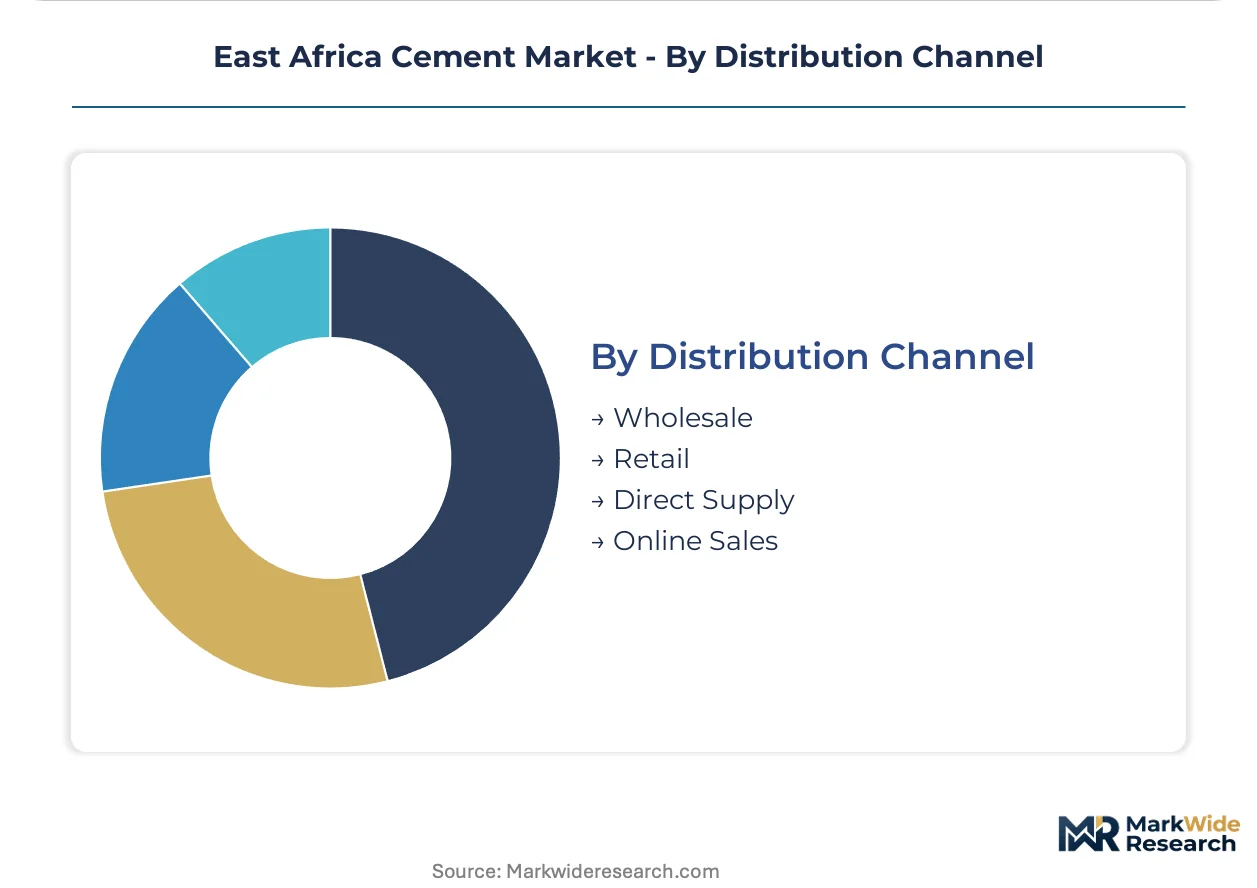
Distribution Channel:
Geographic reach and margin structure diverge sharply between coastal integrated plants with captive logistics and inland grinding operations dependent on third-party haulage.
- Direct Supply:Integrated producers dispatch bulk cement directly to major project sites via dedicated fleets, bypassing distributor markups. Dangote Cement leverages this channel across multiple East African markets to secure raw material security through quarry-to-dispatch control.
- Wholesale:Regional distributors aggregate demand from smaller contractors and retail outlets, holding 2-4 week inventory positions. Poorly surfaced haul roads between Mombasa and Nairobi raise delivered costs for inland grinding plants versus coastal competitors.
- Retail:Hardware stores and construction material yards serve fragmented DIY and small-contractor demand.
- Online Sales:Mobile-based logistics platforms are compressing truck turnaround times at Dar es Salaam and Mombasa terminals.
Direct supply captures institutional margin. Wholesale is where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Bank of Ethiopia anchors regulatory gravity across East Africa's cement corridor, with currency controls and import licensing reshaping procurement economics for producers spanning Kenya, Tanzania, and Ethiopia.
Ethiopia
Federal dam construction and industrial zone pipelines absorb multi-million-tonne annual cement offtake through state-backed procurement channels. The Ethiopian Conformity Assessment Enterprise certifies GB-equivalent product grades for federal projects, compressing eligible supplier pools. Addis Ababa and the Omo River basin host concentrated demand clusters where Derba Midroc and Mugher Cement serve mega-infrastructure schedules.
Kenya
Mortgage finance penetration in Nairobi and Mombasa drives residential construction expansion with 32.5R strength grade specifications. Kenya's National Construction Authority enforces KS EAS 18 cement standards alongside EAC harmonization protocols, elevating compliance costs for smaller mills. The Rift Valley geothermal fields enable baseload kiln energy for producers near Naivasha and Nakuru.
Tanzania
Dar es Salaam port infrastructure and Lake Zone corridor development create dual demand anchors for coastal and inland grinding operations. The Tanzania Bureau of Standards implements EAC unified protocols for cross-border cement trade. Mwanza and Bukoba present underpenetrated demand nodes where Tanga-sourced clinker could support first-mover grinding plant economics.
Uganda
Kampala-centered construction activity pulls cement through Kenyan and Tanzanian supply corridors due to limited domestic clinker capacity. The Uganda National Bureau of Standards adopted EAC cement quality harmonization in 2022, tightening import specification enforcement. Tororo and Hima host the primary domestic production clusters serving northern transport corridors.
Rwanda
Kigali's urban densification and regional trade hub positioning generate cement demand met largely through Tanzanian and Ugandan import channels. The Rwanda Standards Board enforces EAC technical regulations for construction materials. Bugesera and the Northern Province concentrate infrastructure investment where blended cement specifications gain traction for durability-exposed applications.
East Africa Cement Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across East Africa's cement sector. Integrated producers with captive quarry operations and coastal logistics control raw material security and dispatch economics, while inland grinding mills compete on working capital velocity and regional distribution density. Three archetypes dominate: multinational integrated platforms with multi-country footprints, state-affiliated heritage producers with institutional procurement relationships, and mid-scale domestic specialists with geographic niche concentration. Competitive dynamics center on clinker import dependency management and kiln operator certification pipelines versus grinding capacity expansion in underpenetrated corridors.
Within the multinational integrated tier, Dangote Cement and Bamburi Cement Limited exemplify divergent strategic anchors. Dangote Cement represents quarry-to-dispatch vertical control across multiple East African markets, leveraging Nigerian parent-company capital deployment for integrated capacity. Bamburi Cement Limited occupies coastal logistics dominance positioning, serving Kenyan demand and neighboring export corridors through Mombasa terminal infrastructure. East African Portland Cement PLC sits within the state-heritage archetype, competing on decades-built institutional procurement relationships and brand recognition in formal construction channels.
| Leading Market Players |
|---|
| Dangote Cement |
| Bamburi Cement Limited |
| East African Portland Cement PLC |
| ARM Cement PLC |
| Mombasa Cement Limited |
| Savannah Cement |
| Derba Midroc Cement |
| Mugher Cement |
| Messebo Cement |
| Others |
Cost & Logistics Intelligence
KS EAS 18 certification requirements gate both supply qualification and price differentiation across Kenyan and Ethiopian procurement channels, compressing eligible supplier pools while enabling certified-origin premiums in mortgage-financed construction segments.
Pricing Analysis
Coastal integrated plants in Mombasa and Tanga command delivered cost advantages of fifteen to twenty percent over inland grinding operations serving Nairobi and Addis Ababa. Three-tier pricing structure across premium certified-origin, standard grade, and economy bulk segments reflects certification level and volume scale differentiation. Price erosion runs through the economy tier as clinker import dependency strains working capital for non-integrated mills. Government contractors show least price sensitivity due to bonded performance guarantees, while mid-tier residential developers in Nairobi's peri-urban corridors drive hardest bargain negotiations.
Supply Chain Analysis
Red Sea petcoke transit underwrites fuel security for over seventy percent of regional clinker capacity, exposing margins to shipping disruption and dollar-denominated volatility. Manufacturing concentrates in Ethiopia, Kenya, and Tanzania, with Uganda and Rwanda drawing from cross-border supply corridors. Raw material dependencies rest on Gulf-origin petroleum coke, Egyptian clinker imports, and Rift Valley limestone deposits. Single-source fuel vulnerability represents the dominant structural risk. Distribution runs through direct-supply dedicated fleets for mega-projects, wholesale distributor networks for mid-tier contractors, and mobile-platform coordinated retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified rotary kiln operator production of fewer than fifty specialists annually against regional expansion needs frames East African cement as a capability-scarcity market where certification pipeline control and captive technical talent development separate viable long-term positions from working capital-constrained grinding operations.
For Market Incumbents: Consolidate around geothermal-powered kiln assets in Kenya's Rift Valley and coastal logistics infrastructure at Mombasa to defend margin position against clinker import-dependent challengers. Prioritize backward integration into limestone quarry control and captive laboratory certification capacity to meet KS EAS 18 third-party verification mandates. Accelerate kiln operator training pipeline partnerships with Ethiopian technical institutes to preempt capability scarcity bottlenecks. For New Entrants and Emerging Players: Lead with grinding plant positioning in Tanzania's Lake Zone corridor, where Mwanza and Bukoba demand clusters remain underpenetrated relative to coastal supply capacity. Target contractor-facilitated wholesale channel entry with shipment-lot pricing flexibility rather than annual framework commitments. Emphasize LC3 calcined clay blended cement formulations to differentiate on CO2 intensity credentials for EAC harmonized standards compliance. For Investors and Strategic Acquirers: EAC regulatory convergence on unified cement quality protocols reshapes the acquisition landscape toward integrated producers with captive laboratory and certification infrastructure. Five-to-ten year viability favors quarry-to-dispatch vertical control over grinding-only asset exposure to clinker import volatility. Target acquisition archetype: mid-scale coastal integrated platforms with Rift Valley geothermal energy access. Signal to monitor: National Bank of Ethiopia forex rationing severity for spare parts procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | Captive raw material security insulates margin from transport cost inflation on Mombasa-Nairobi haul corridors. |
| Geothermal Kiln Energy Transition | Rift Valley baseload power access stabilizes energy tariffs versus grid-dependent competitors in Naivasha. |
| LC3 Blended Cement Scale-Up | Calcined clay activation technology compresses CO2 intensity while maintaining KS EAS 18 early-strength benchmarks. |
| Kiln Operator Certification Pipeline | East African Portland Cement PLC training partnerships address regional shortage of qualified rotary kiln specialists. |
| Mobile Platform Logistics Integration | Digital dispatch coordination compresses truck turnaround times at Dar es Salaam and Mombasa bulk terminals. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EAC trade harmonization protocols, Ethiopian Conformity Assessment Enterprise certification records, and Kenyan National Construction Authority enforcement bulletins. Primary interviews engaged plant operations directors, procurement leads at federal infrastructure contractors, distributor network managers, and geothermal energy supply specialists. Secondary validation drew from customs clinker import data, EAC standards harmonization documentation, and cement industry association capacity reports. Bottom-up volume modeling triangulated against top-down infrastructure pipeline absorption estimates.
Segmentation dimensions modeled span product type across Ordinary Portland, blended, and specialty grades; application across infrastructure, residential, commercial, and industrial end-uses; and distribution channel structure across direct supply, wholesale, retail, and digital-coordinated logistics. CAGRs derived from regression analysis of historical capacity utilization against announced project pipelines, with adjustments for forex rationing impacts on equipment procurement timelines. Industry-specific forecast inputs incorporated Rift Valley geothermal field expansion schedules and EAC cross-border tariff harmonization implementation trajectories.
Forecasts assume regulatory continuity in Kenyan KS EAS 18 enforcement, Ethiopian federal procurement priority licensing, and EAC unified cement standards adoption; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as National Bank of Ethiopia forex availability and Red Sea shipping security conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cement Tiles Market
Building Materials
Brick Adhesive Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Construction Coatings Market
Building Materials
Qatar Facade Market
Building Materials
Cladding Market
Building Materials
US Cement Tiles Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Italy Architectural Coatings Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Fly Ash Bricks Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Concrete Admixtures Market
Building Materials
Europe Fireproof Cladding Market