
 Poland Architectural Coatings Market | 2026-2036
Poland Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Architectural Coatings Market Analytics
Poland is reconfiguring its architectural coatings production footprint with new water-based capacity coming online in Lower Silesia. AkzoNobel N.V. leverages its global color technology platform to dominate premium decorative segments in Polish urban centers. Sniezka SA anchors domestic supply through its extensive distribution network reaching secondary cities and rural contractors. PPG Industries Inc. competes on industrial protective coatings for infrastructure and manufacturing facilities.
Architectural coatings encompass formulated film-building materials applied to building substrates for decoration, protection, or functional performance, typically comprising binders, pigments, extenders, solvents or water carriers, and additives that cure to form adherent, durable surface layers. Emulsion paints lead Polish residential consumption due to low odor profiles and compliance with indoor air quality protocols, while high-performance coatings represent the fastest-expanding technology segment as commercial clients specify extended lifecycle protection. Water-based systems occupy the dominant share of new formulation development, though solvent-based products retain niche positions in exterior wood preservation and metal priming where moisture resistance thresholds exceed standard acrylic performance.
Poland's State Sanitary Inspection enforces EU REACH and national VOC emission standards that redirect manufacturer portfolios toward low-solvent and zero-VOC waterborne platforms. The Polish Committee for Standardization harmonizes product certification with EN 13300 paint classification and CE marking requirements that condition market access for imported and domestically produced coatings. Stakeholders must monitor how Poland's transposition of the EU Green Deal renovation targets reshapes specification criteria across public procurement and private construction finance channels.
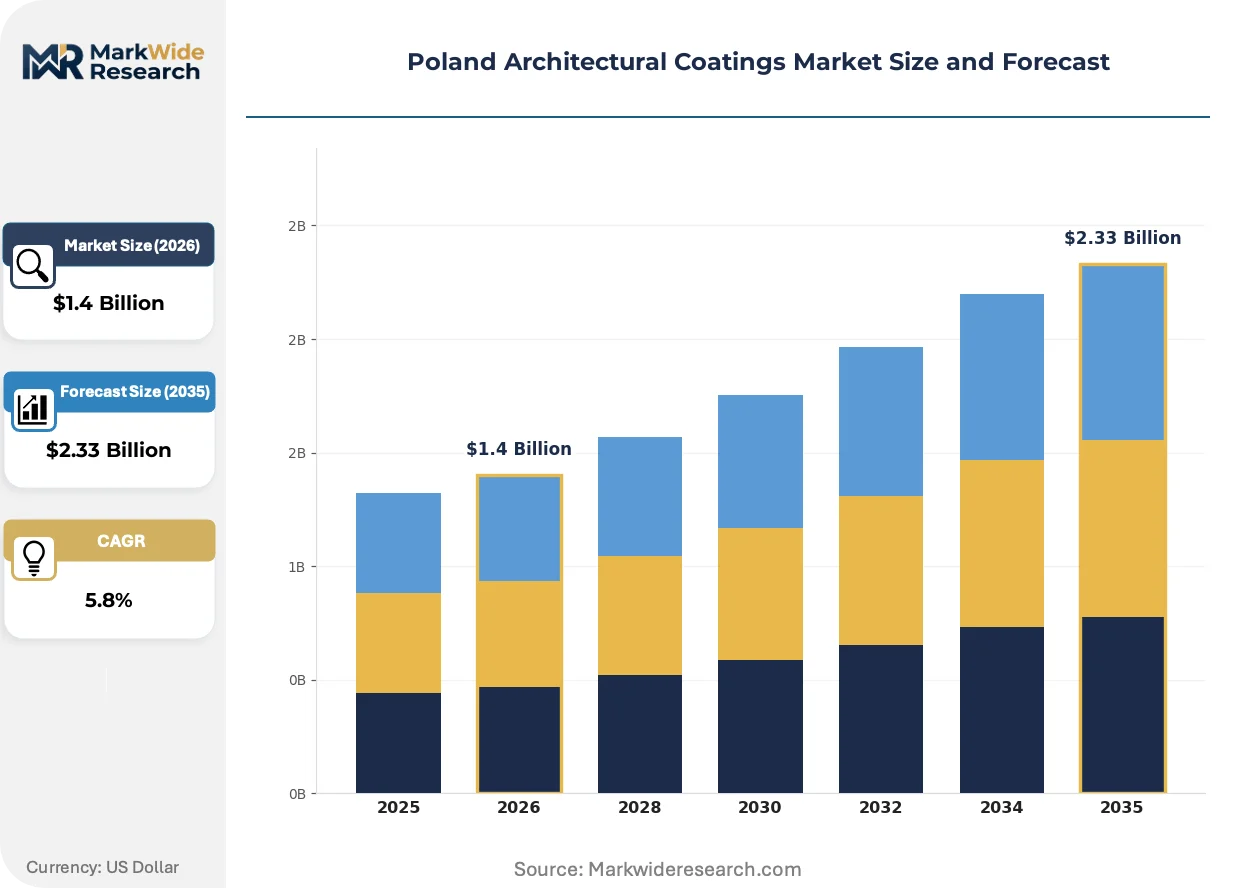
Market Dynamics
Poland's architectural coatings sector is compressing around water-based formulation transitions as the State Sanitary Inspection enforces EU-derived VOC ceilings that disqualify legacy solvent systems from metropolitan construction tenders.
Growth Catalysts
- EU Green Deal renovation targets:Poland's transposition of building energy efficiency mandates into national procurement rules is redirecting public infrastructure budgets toward certified low-emission coating systems.
- Warsaw-Kraków corridor concentration:Overlapping commercial development and heritage restoration pipelines in this urban axis are sustaining premium emulsion demand from institutional buyers.
- Waterborne technology maturation:Acrylic-urethane hybrid platforms now match solvent-based durability thresholds for exterior metal priming, expanding specification scope for Polish industrial contractors.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin stability for domestic formulators dependent on Chinese and Ukrainian mineral concentrate imports.
- Lower Silesia capacity concentration:New water-based production gravity in this single region creates geographic supply vulnerability for northern and eastern Polish distribution networks.
- REACH registration friction:ECHA compliance timelines for novel bio-based binders delay product launch cycles by 18-24 months versus conventional acrylic registrations.
Strategic Opportunities
- Podlaskie and Warmia-Mazury underpenetration:Secondary city renovation rates in Poland's northeast corridor lag national averages by 40%, presenting white-space demand for Sniezka SA's rural distribution infrastructure.
- Photocatalytic air-purifying coatings:Titanium dioxide-functionalized exterior emulsions are penetrating Kraków municipal building specifications as smog-mitigation infrastructure.
- Digital color-matching kiosks:Retail channel innovation is compressing contractor specification cycles by embedding spectrophotometric tools directly in builder-merchant storefronts across Poznań and Łódź.
Industry Challenges
- Formulation chemist scarcity:Polish technical universities produce insufficient polymer science graduates to staff R&D expansion at new Lower Silesia water-based facilities.
- CE marking timeline compression:Polish Committee for Standardization harmonization delays with EN 13300 revisions are extending product certification cycles for imported coating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Architectural Coatings Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Paints, Enamel Paints, Primers, Sealers End User: Residential Buildings, Commercial Structures, Industrial Facilities, Infrastructure Projects Technology: Water-Based, Solvent-Based, Powder Coatings, High-Performance Coatings Application: Interior, Exterior, Decorative, Protective |
| Companies Covered | AkzoNobel N.V., PPG Industries Inc., Sniezka SA, Jotun, BASF SE, Sherwin-Williams Company, Beckers Group, Brillux GmbH & Co. KG, CIN S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Architectural Coatings Market Evolving Landscape
Formulation virtualization is collapsing physical testing cycles as digital twin platforms simulate coating performance under Polish climatic stress conditions before laboratory validation.
Self-healing microcapsule technology is virtualizing maintenance cost structures for Polish infrastructure owners. Bridge and tunnel operators in the Warsaw metropolitan zone are specifying these systems to compress lifecycle repainting intervals. The technology is virtualizing traditional protective coating procurement models by shifting specifications toward performance-guarantee contracts rather than material-volume tenders.
REACH Annex XVII expansion on microplastic additives is forcing reformulation of textured exterior finishes across Polish decorative portfolios. Manufacturers are accelerating bio-based extender substitution programs to preempt 2027 enforcement windows. Heritage restoration contractors in Kraków's historic core face acute compliance pressure given the aesthetic fidelity requirements of conservation-grade specifications.
Specification authority is migrating from general contractors to facility management operators in Polish commercial real estate. Long-term service agreements now bundle coating application with predictive maintenance monitoring, displacing traditional lump-sum construction procurement. This shift concentrates most visibly in Warsaw office tower retrofits where institutional landlords prioritize operational expenditure predictability over capital cost minimization.
Poland Architectural Coatings Market Segmentation
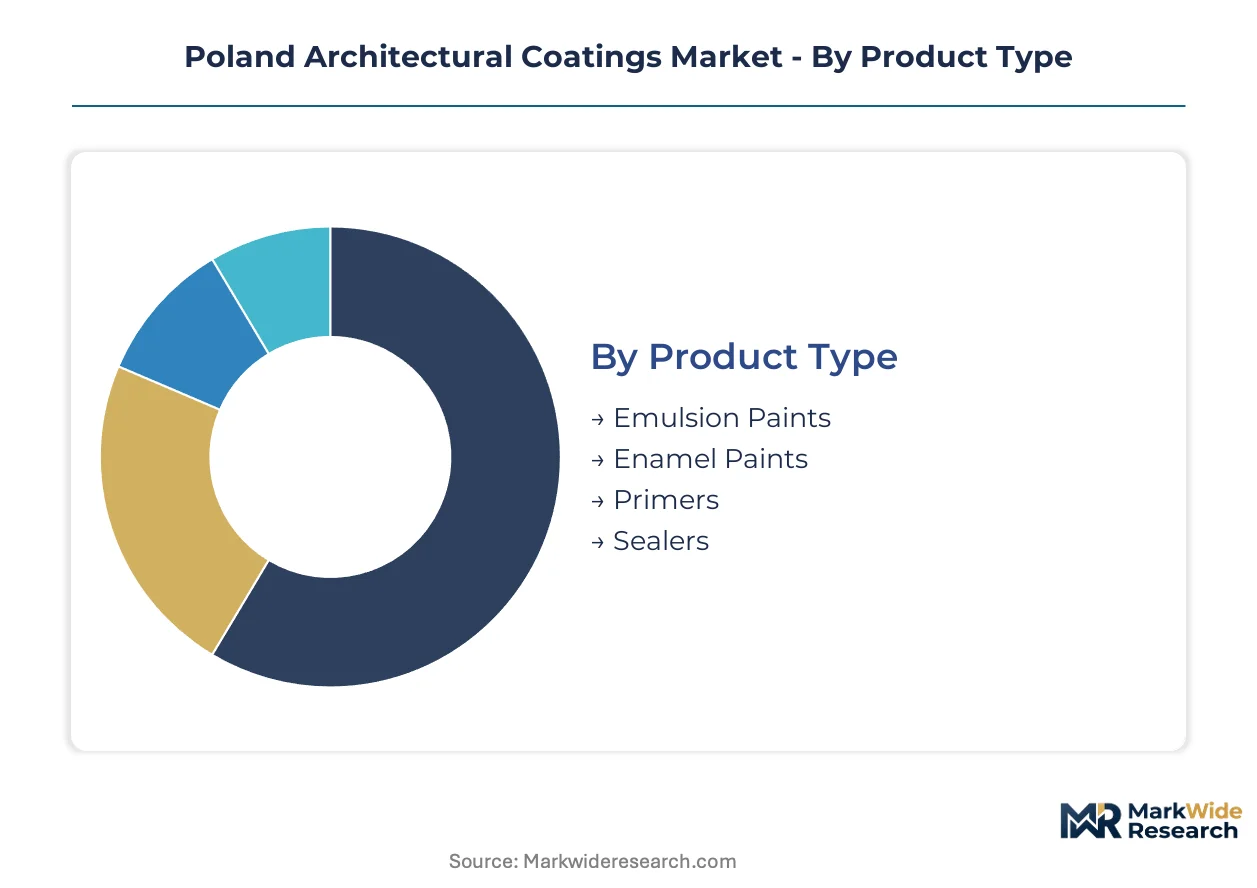
Architectural coatings in Poland fragment across formulation chemistry, end-use intensity, and performance specifications. Each dimension carries distinct regulatory footprints and margin structures that reshape competitive positioning across Warsaw-Kraków corridor projects versus secondary city distribution.
Product Type:
Mature alkyd systems coexist with emerging hybrid platforms as Polish formulators navigate REACH Annex XVII compliance timelines.
- Emulsion Paints:Acrylic and vinyl-acrylic copolymer dispersions in water carrier systems dominate Polish residential renovation. Warsaw metropolitan contractors specify these for low-odor interior applications where State Sanitary Inspection VOC limits apply.
- Enamel Paints:Thermosetting alkyd and polyurethane resin systems cure to hard, glossy films. Heritage restoration contractors in Kraków's historic core specify these for decorative woodwork requiring aesthetic fidelity alongside durability.
- Primers:Substrate-specific adhesion promoters including zinc phosphate metal primers and acrylic masonry sealers.
- Sealers:Penetrating and film-forming variants for concrete moisture management and substrate consolidation.
Emulsion paints retain volume leadership; high-performance enamel formulations hold the steepest expansion curve in conservation-grade specifications.
End User:
Customer type stratification separates price-sensitive rural renovation from performance-specified institutional procurement.
- Residential Buildings:Single-family and multi-unit housing renovation drives emulsion paint volume across Polish metropolitan and secondary markets. Podlaskie and Warmia-Mazury underpenetration creates white-space demand for distribution infrastructure.
- Commercial Structures:Office towers, retail centers, and hospitality facilities specify extended-lifecycle coatings. Warsaw office retrofits increasingly bundle application with facility management service agreements.
- Industrial Facilities:Manufacturing plants and warehouses demand chemical-resistant protective systems.
- Infrastructure Projects:Bridge, tunnel, and transportation coatings require certified durability under Polish climatic stress conditions.
Residential buildings retain volume leadership; commercial structures hold the steepest expansion curve as procurement shifts toward operational expenditure bundling.
Technology:
Formulation chemistry divides along environmental compliance maturity and performance threshold requirements.
- Water-Based:Acrylic, polyurethane, and hybrid dispersions carry the dominant share of new capacity investment in Lower Silesia. Polish Committee for Standardization EN 13300 harmonization favors these systems in public procurement.
- Solvent-Based:Alkyd and epoxy systems in organic solvent carriers retain niche positions in exterior wood preservation and metal priming where moisture resistance exceeds standard acrylic performance.
- Powder Coatings:Thermosetting resin systems applied as dry powder for industrial metal finishing.
- High-Performance Coatings:Fluoropolymer, polysiloxane, and ceramic-enhanced systems for extreme durability specifications.
Water-based technology retains volume leadership; high-performance coatings hold the steepest expansion curve in infrastructure and commercial asset protection.
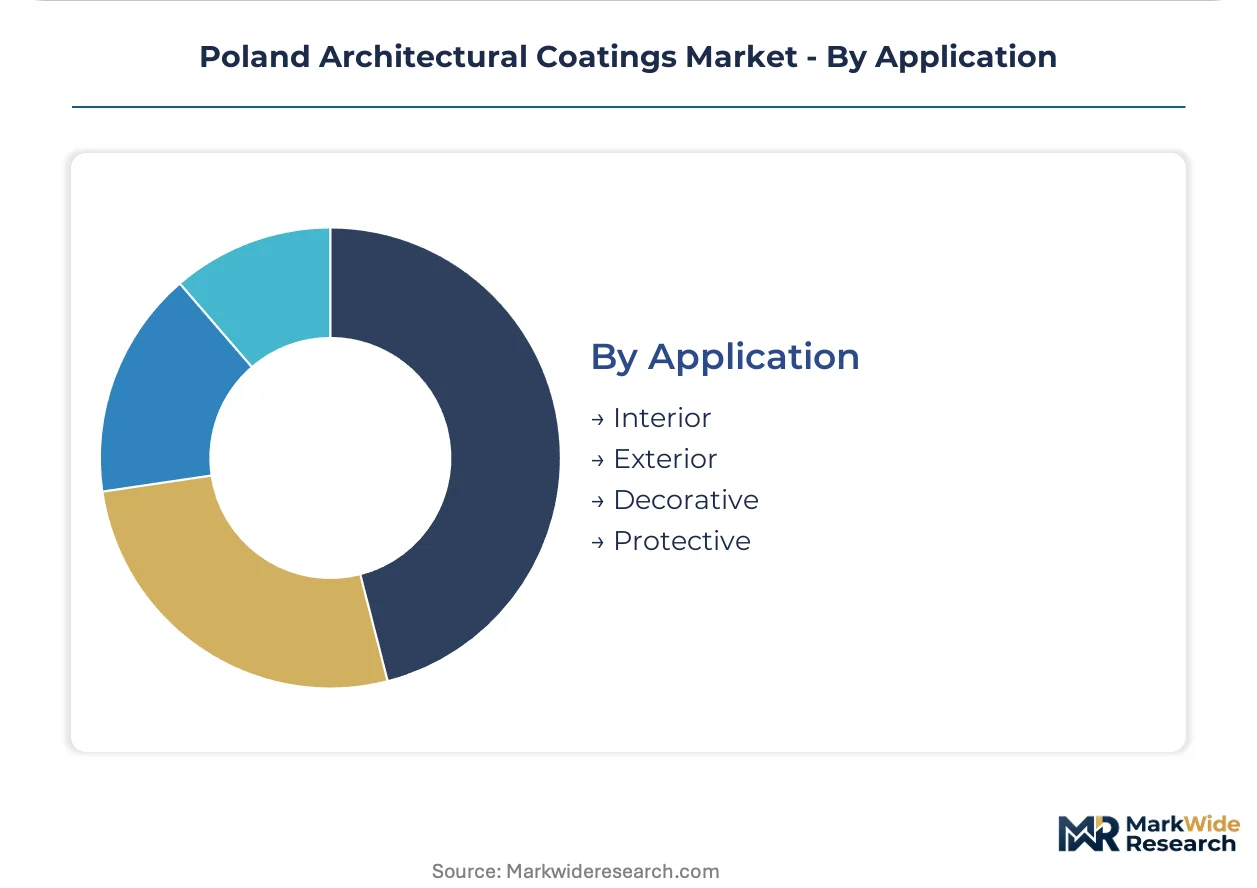
Application:
Use environment separates aesthetic-driven interior specifications from weathering-resistant exterior performance.
- Interior:Wall and ceiling coatings emphasizing low-odor emission and washability. Polish residential consumers prioritize indoor air quality compliance in metropolitan renovation projects.
- Exterior:Facade, trim, and roof coatings resisting UV degradation and thermal cycling. Photocatalytic titanium dioxide-functionalized emulsions are penetrating Kraków municipal specifications for smog mitigation.
- Decorative:Color and texture-focused finishes including textured exterior renders subject to microplastic additive reformulation pressure.
- Protective:Anti-corrosion, chemical-resistant, and abrasion-resistant functional coatings.
Interior applications retain volume leadership; exterior protective systems hold the steepest expansion curve as building envelope performance standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New water-based capacity deployment in Lower Silesia concentrates Polish supply-side investment, while distribution networks stretch toward underpenetrated northeastern voivodeships. Metropolitan renovation intensity in Warsaw and Kraków anchors premium demand, with regulatory enforcement tightening VOC ceilings nationwide.
Lower Silesia
Industrial waterborne formulation capacity clusters around Wrocław and the Legnica-Głogów copper basin. Poland's State Sanitary Inspection enforces EU-derived emission limits that disqualify legacy solvent systems from public tenders. New production facilities here supply the Warsaw-Kraków corridor while creating geographic vulnerability for northern distribution networks.
Masovia
Warsaw metropolitan renovation drives premium interior emulsion consumption from institutional and residential buyers. The Polish Committee for Standardization harmonizes EN 13300 paint classification with CE marking requirements that condition market access. Commercial office retrofits in the capital increasingly bundle coating application with long-term facility management agreements.
Lesser Poland
Kraków's heritage restoration pipeline sustains demand for conservation-grade enamel systems in the historic core. Municipal procurement now specifies photocatalytic titanium dioxide-functionalized exterior emulsions for smog mitigation infrastructure. The city's conservation authorities balance aesthetic fidelity requirements against REACH Annex XVII microplastic additive deadlines.
Podlaskie and Warmia-Mazury
Secondary city renovation rates in Poland's northeast corridor lag national averages by substantial margins, creating white-space demand for distribution infrastructure. Rural contractors here remain price-sensitive, favoring standard-grade emulsion systems over premium formulations. Sniezka SA's extensive rural network targets this underpenetrated zone for volume expansion.
Pomerania
Gdańsk and the Tri-City area concentrate maritime-influenced protective coating demand for port infrastructure and shipyard maintenance. Coastal climatic stress conditions accelerate exterior coating degradation cycles, compressing repainting intervals. Industrial facilities here specify chemical-resistant systems that exceed standard acrylic performance thresholds.
Poland Architectural Coatings Market Competitive Landscape
Global majors and domestic specialists split the Polish architectural coatings market into distinct competitive tiers. Multinational chemical conglomerates leverage color technology platforms and industrial protective expertise, while regional formulators anchor distribution reach into secondary cities and rural contractor networks. Two strategic archetypes dominate: technology leaders competing on formulation innovation and certification compliance, and distribution-heavy domestic players competing on geographic coverage and price accessibility. Capacity expansion in Lower Silesia and digital retail channel innovation represent the dominant competitive vectors reshaping market structure.
Among global coating specialists, AkzoNobel N.V. and PPG Industries Inc. exemplify the technology-leader archetype through their positioning on premium decorative and industrial protective segments respectively. Sniezka SA anchors the domestic distribution-heavy tier, representing Polish-owned supply reaching into underpenetrated rural markets where international players maintain limited presence. These three companies illustrate the competitive fault line between global formulation expertise and localized distribution density that defines Polish market structure.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries Inc. |
| Sniezka SA |
| Jotun |
| BASF SE |
| Sherwin-Williams Company |
| Beckers Group |
| Brillux GmbH & Co. KG |
| CIN S.A. |
| Others |
Value Network & Pricing Analysis
The Warsaw-Gdańsk rail corridor's freight cost dynamics amplify pricing power for Lower Silesia-based formulators while compressing margins for distributors serving Poland's northeastern voivodeships. This logistics asymmetry feeds into a three-tier pricing structure across premium, standard, and economy levels that separates metropolitan specification buyers from rural renovation contractors.
Pricing Analysis
EU REACH dictates the pricing tier structure across Polish architectural coatings, separating CE-marked premium formulations from uncertified economy imports. Price differentiation rests on certification grade and volume scale, with institutional procurement bundling application services commanding premium positioning. Cost compression in the standard tier is intensifying because titanium dioxide feedstock volatility feeds through pigment-intensive formulations. Rural contractors in Podlaskie and Warmia-Mazury exhibit the highest price sensitivity, while Warsaw facility management operators prioritize lifecycle cost predictability over unit pricing.
Supply Chain Analysis
Extended payment terms from Chinese titanium dioxide suppliers and supply-chain finance facilities at major Polish distributors anchor working capital structures across the value chain. Geographic supply concentration centers on China for pigment feedstocks, Germany for specialty additives, and domestic Lower Silesia for water-based formulation capacity. Raw material dependencies include titanium dioxide concentrates, acrylic resin dispersions, and bio-based extender alternatives. Single-source vulnerability runs through Ukrainian mineral concentrate disruptions. Distribution runs through builder-merchant networks reaching secondary cities and direct contractor relationships in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's architectural coatings sector is approaching a platform-economics inflection as digital color-matching infrastructure and predictive maintenance bundling reshape contractor specification authority. Interoperability between spectrophotometric retail tools and facility management software stacks is consolidating procurement influence around data-integrated service providers.
For Market Incumbents: Insulate premium positioning by embedding color technology platforms with predictive coating lifecycle analytics for Warsaw commercial real estate operators. Accelerate backward integration into water-based resin production to offset titanium dioxide cost volatility. Defensive patent filings around photocatalytic exterior formulations will preempt competitive entry in Kraków municipal smog-mitigation specifications.
For New Entrants and Emerging Players: Establish a beachhead in Podlaskie and Warmia-Mazury distribution infrastructure where Sniezka SA's network coverage creates service gaps for rural contractors. Target white-space demand in heritage restoration enamel systems where conservation-grade certification barriers filter out commodity competitors. A go-to-market angle bundling digital color matching with contractor financing programs will compress specification cycles against established distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates divesting non-core decorative coatings assets amid portfolio rebalancing toward industrial specialties. Long-term viability in Polish architectural coatings hinges on water-based technology transition completion and regulatory compliance infrastructure depth. The signal to watch is EN 13300 harmonization timeline compression at the Polish Committee for Standardization, which will accelerate certification cost burdens for subscale formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New water-based formulation plants in Lower Silesia supply Warsaw-Kraków corridor demand growth. |
| Backward Integration | In-house acrylic resin production reduces exposure to Chinese petrochemical feedstock volatility. |
| Green Manufacturing Transition | Zero-VOC platform investments align with State Sanitary Inspection enforcement trajectories. |
| Long-term Supply Agreement | Titanium dioxide offtake contracts with alternative suppliers mitigate Ukrainian concentrate disruption. |
| Joint Venture | Digital color-matching kiosk partnerships with Poznań and Łódź builder-merchants compress specification cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Polish Committee for Standardization certification registers, and EU ECHA regulatory filings. Primary interviews engaged formulation chemists at Lower Silesia production facilities, procurement directors at Warsaw commercial real estate operators, distribution managers at regional builder-merchant networks, and conservation contractors in Kraków's historic core. Secondary validation drew from Polish Central Statistical Office construction output indices, EU Green Deal implementation tracking, and EN 13300 paint classification documentation. Bottom-up volume estimates triangulate against top-down construction expenditure allocations.
Forecast inputs incorporate formulation technology adoption curves, regulatory compliance timeline assumptions, and regional renovation intensity differentials across the projection horizon. Segmentation dimensions modeled include formulation chemistry, end-use building type, technology platform, and application environment. CAGRs derive from regression analysis linking construction output trajectories to coatings intensity ratios. Industry-specific forecast inputs include EU Green Deal renovation target transposition rates and REACH Annex XVII microplastic additive phase-out schedules.
Sensitivities concentrate around titanium dioxide supply disruption scenarios, EN 13300 harmonization delays, and EU Green Deal funding allocation shifts. Forecasts reflect documented assumptions regarding technology transition pacing and regulatory enforcement intensity. Macroeconomic construction cycle deviation, regulatory timeline compression, or breakthrough bio-based binder commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Sprayed Concrete Market
Building Materials
East Africa Cement Market
Building Materials
North America Architectural Coatings Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Natural Stone Slab Market
Building Materials
Cribbing Blocks Market
Building Materials
Fly Ash Bricks Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Pozzolana Cement Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Block Paving Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Foam Bricks Market
Building Materials
Germany Aluminum Door and Window Market