
 Grinding Discs Market | 2026-2036
Grinding Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Grinding Discs Market Analytics
Modular disc-and-hub configurations is realigning procurement patterns across metalworking and construction channels. Robert Bosch GmbH leverages its power-tool ecosystem to sustain bundled accessory sales. Carborundum Universal Limited anchors South Asian supply through integrated abrasive manufacturing. 3M Company differentiates via ceramic grain technology leadership in high-precision applications.
Grinding discs are consumable abrasive tools comprising bonded or coated mineral grains on rigid fiber-glass or plastic backing plates, engineered for material removal through rotational friction at speeds typically exceeding 10,000 RPM. Their primary industrial purpose spans weld seam conditioning, surface preparation, and precision dimensioning across ferrous and non-ferrous substrates. Bonded abrasives dominate volume due to entrenched metalworking demand, while diamond segments capture premium margin pools in stone and composite machining. Ceramic material formulations represent the fastest-expanding category as heat-resistant grains extend disc life in high-pressure automotive grinding.
OSHA enforces permissible exposure limits on respirable crystalline silica, compelling manufacturers to reformulate bonded abrasives and improve dust suppression. REACH regulates synthetic abrasive mineral classification and disposal pathways across European supply chains. EPA air quality standards shape domestic production facility compliance investments. Stakeholders must monitor evolving MEE emissions protocols in China and assess backward integration into ceramic grain supply as a strategic hedge against raw material cost volatility.
Market Dynamics
OSHA silica exposure limits and REACH abrasive material restrictions are forcing bonded abrasive reformulations across metalworking supply chains. Manufacturers face simultaneous pressure to suppress respirable dust while maintaining stock removal rates in high-RPM applications.
Growth Catalysts
- EV powertrain precision grinding:Automotive OEMs are expanding cylindrical grinding operations for electric motor shafts and battery housing surfaces. Ceramic grain discs extend tool life in these heat-intensive applications.
- REACH synthetic mineral classification:European manufacturers accelerating compliant bonded abrasive development capture preferential placement in aerospace supply chains serving Germany and France.
- Germany industrial tool clusters:Concentrated demand from automotive and aerospace tier suppliers drives specification tightening for precision surface finish capabilities.
Market Restraints
- Fused alumina price volatility:Energy-intensive smelting operations in China expose abrasive grain costs to electricity tariff fluctuations and carbon border adjustment uncertainties.
- Silica exposure compliance costs:OSHA permissible exposure limits mandate capital-intensive dust collection retrofits and respiratory protection programs at fabrication facilities.
- Diamond segment substitution in stone:Superabrasive tools capture premium margin pools in granite and engineered stone machining where speed outweighs consumable cost.
Strategic Opportunities
- India domestic manufacturing incentives:PLI scheme support for capital goods production creates localized abrasive supply advantages for construction and metalworking channels.
- Modular disc-and-hub systems:Separable backing plate designs reduce per-use material costs and open aftermarket attachment revenue streams.
- MEE emissions protocols in China:Tightening air quality standards at production facilities favor integrated manufacturers with captive ceramic grain synthesis capabilities.
Industry Challenges
- Ceramic grain synthesis expertise scarcity:Sol-gel and seeded-gel manufacturing know-how concentrates at limited technical centers, constraining quality scale-up.
- Multi-jurisdiction certification timelines:Simultaneous OSHA silica compliance, REACH substance registration, and BIS quality marking create product launch delays.
- Legacy equipment RPM incompatibility:Older angle grinders lack thermal management for ceramic grain operating windows, fragmenting specification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grinding Discs Market |
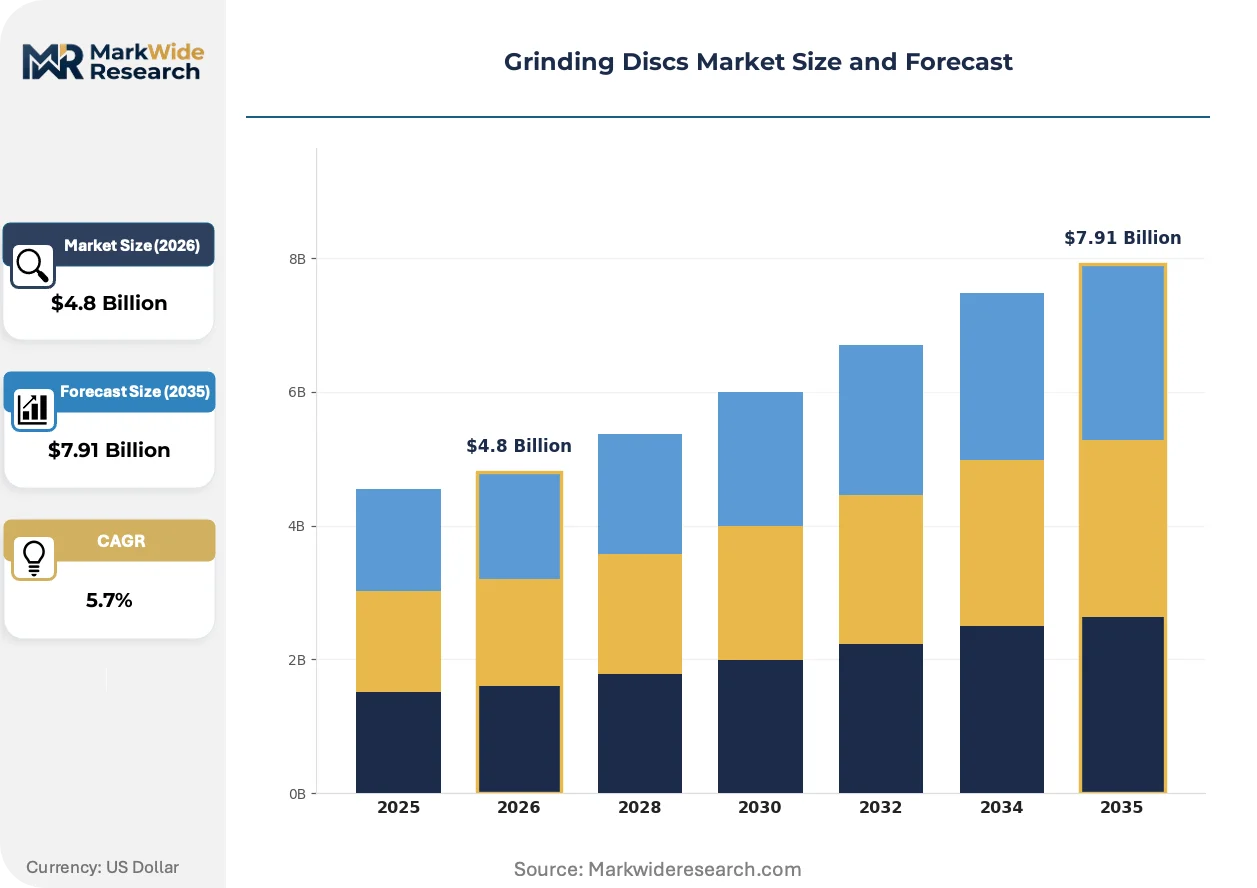
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
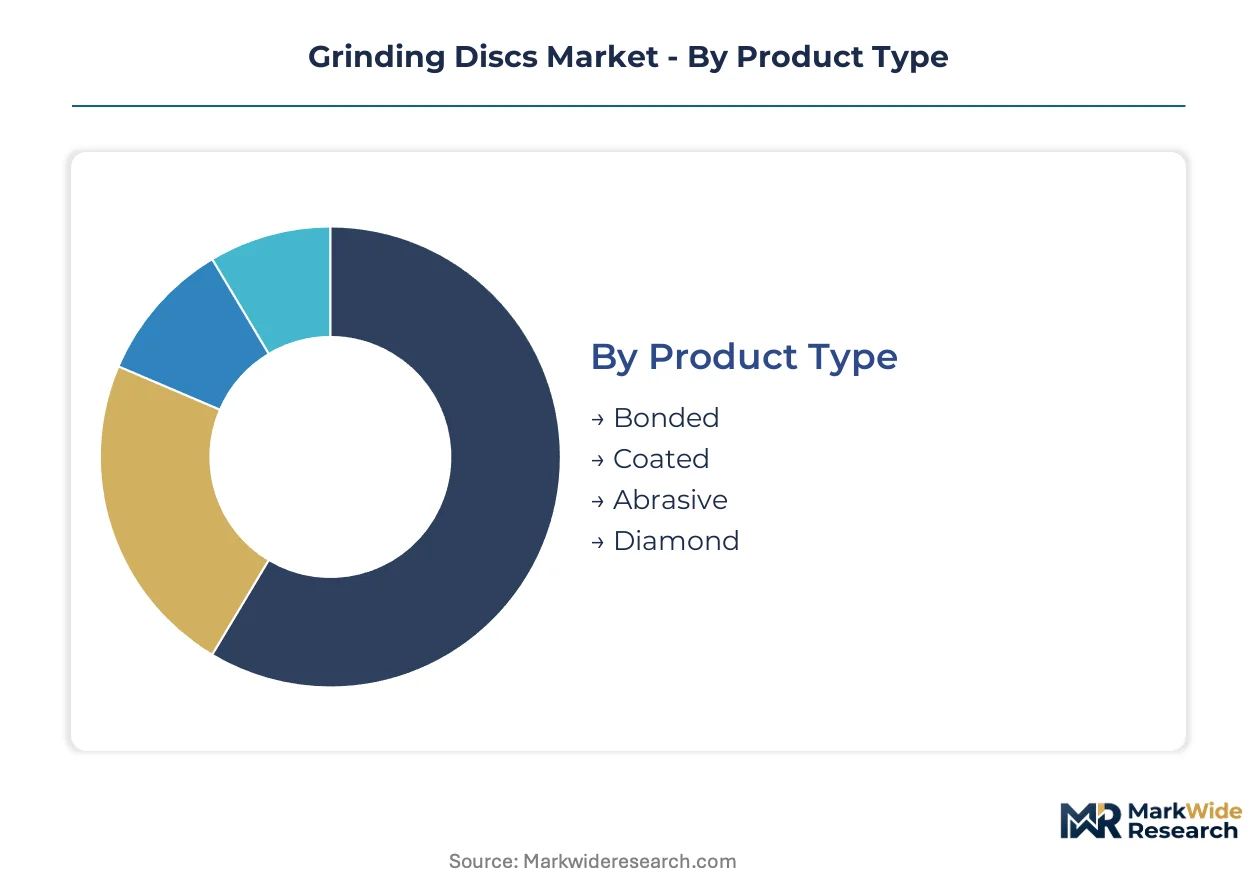
| Segmentation | Product Type: Bonded, Coated, Abrasive, Diamond Material: Aluminum Oxide, Silicon Carbide, Zirconia, Ceramic Application: Metalworking, Construction, Automotive, Woodworking End User: Manufacturers, Contractors, DIY Enthusiasts, Retailers |
| Companies Covered | Robert Bosch GmbH, Carborundum Universal Limited, 3M Company, Weiler Abrasives Group, Pferd Inc., Tyrolit Group, NORITAKE CO., LIMITED, Flexovit USA Inc., Compagnie de Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grinding Discs Market Evolving Landscape
Ceramic abrasive formulations and modular hub architectures are compressing traditional bonded abrasive lifecycles. Regulatory pressure on respirable silica is simultaneously accelerating dust-suppressed product development and reshaping procurement specifications across industrial metalworking.
Ceramic grain technology is modularizing precision grinding workflows across automotive powertrain machining. Seeded-gel aluminum oxide structures withstand higher interface temperatures than fused alumina alternatives. Tier-one suppliers in Germany and Japan specify these formulations for EV motor shaft finishing where dimensional tolerance requirements have tightened. The technology is modularizing process steps by combining roughing and finishing operations into single-pass sequences.
REACH synthetic abrasive mineral reclassification is redirecting formulation strategies across European supply chains. ECHA substance evaluation protocols now scrutinize bauxite-derived processing residues and synthetic mineral disposal pathways. Manufacturers serving French and German aerospace clusters are accelerating water-based bonding agent development to preempt downstream waste classification restrictions. Stone and composite machining segments face the steepest compliance cost escalations due to higher abrasive consumption intensity.
Specification-driven procurement consolidation is compressing supplier bases in North American metalworking distribution. Large fabrication contractors now mandate OSHA-compliant silica suppression documentation as a qualification threshold, disqualifying generic import offerings. Industrial distributors respond by bundling certified abrasive systems with respiratory protection equipment and dust extraction rentals. This pattern concentrates most visibly in California and Texas construction markets where silica enforcement has intensified through state-plan OSHA offices.
Grinding Discs Market Segmentation
Grinding disc procurement patterns diverge sharply between standalone consumable replacement and integrated power-tool ecosystem sales. Specification requirements vary by integration depth, with embedded system sales demanding tighter dimensional tolerances and certified dust suppression documentation.
Product Type:
Standalone consumable discs dominate replacement channels, while bonded abrasives embedded in OEM power-tool bundles command premium placement through specification lock-in.
- Bonded:Resin- or vitrified-bonded mineral grains on rigid fiberglass backing plates withstand rotational stresses exceeding 12,000 RPM in metalworking applications. Demand concentrates in German automotive supply chains where EV powertrain grinding requires heat-resistant formulations.
- Coated:Abrasive grains electrostatically deposited on flexible paper or cloth backings enable contour following in surface preparation workflows. California and Texas fabrication contractors specify OSHA-compliant silica-suppressed variants as qualification thresholds.
- Abrasive:Loose grain configurations serve specialized lapping and polishing operations requiring precise material removal control.
- Diamond:Metal-bonded synthetic diamond segments capture premium margin pools in granite and engineered stone machining where cutting speed outweighs consumable cost.
Bonded discs lead volumes today; diamond segments are gaining share fastest in stone and composite applications.
Material:
Raw material cost tiers stratify procurement patterns, with fused mineral formulations serving price-sensitive construction channels and engineered ceramics capturing precision metalworking premiums.
- Aluminum Oxide:Brown and white fused alumina variants provide general-purpose stock removal across ferrous substrates. Chinese electricity tariff fluctuations expose this segment to raw material cost volatility through energy-intensive smelting operations.
- Ceramic:Seeded-gel aluminum oxide structures withstand interface temperatures 40% higher than fused alternatives, enabling single-pass roughing and finishing in EV motor shaft applications. Tier-one suppliers in Germany and Japan specify these formulations exclusively.
- Silicon Carbide:Sharp, friable grains excel in non-ferrous and stone grinding where minimal heat generation preserves workpiece integrity.
- Zirconia:Self-sharpening grain structures extend disc life in high-pressure weld seam conditioning across heavy fabrication.
Aluminum oxide leads volumes today; ceramic formulations are expanding most quickly in automotive powertrain machining.
Application:
End-use intensity and specification stringency create divergent margin profiles, with automotive and aerospace applications demanding certified performance documentation.
- Metalworking:Weld seam conditioning and precision dimensioning across ferrous and non-ferrous substrates consume the highest abrasive volumes. OSHA silica enforcement is reshaping procurement toward dust-suppressed bonded systems.
- Automotive:Cylindrical grinding of electric motor shafts and battery housing surfaces requires ceramic grain discs for heat-intensive operations. German OEMs are tightening dimensional tolerance specifications faster than other geographies.
- Construction:Surface preparation and concrete grinding applications prioritize cost efficiency over precision, though California state-plan OSHA offices are accelerating compliance documentation requirements.
- Woodworking:Coated abrasive discs dominate material removal in furniture and millwork production where finish quality drives specification.
Metalworking leads volumes today; automotive applications show the steepest expansion trajectory from EV powertrain investment.
End User:
Procurement authority and technical sophistication determine specification influence, with large manufacturers dictating bonded abrasive formulations while contractor channels respond to distributor bundling strategies.
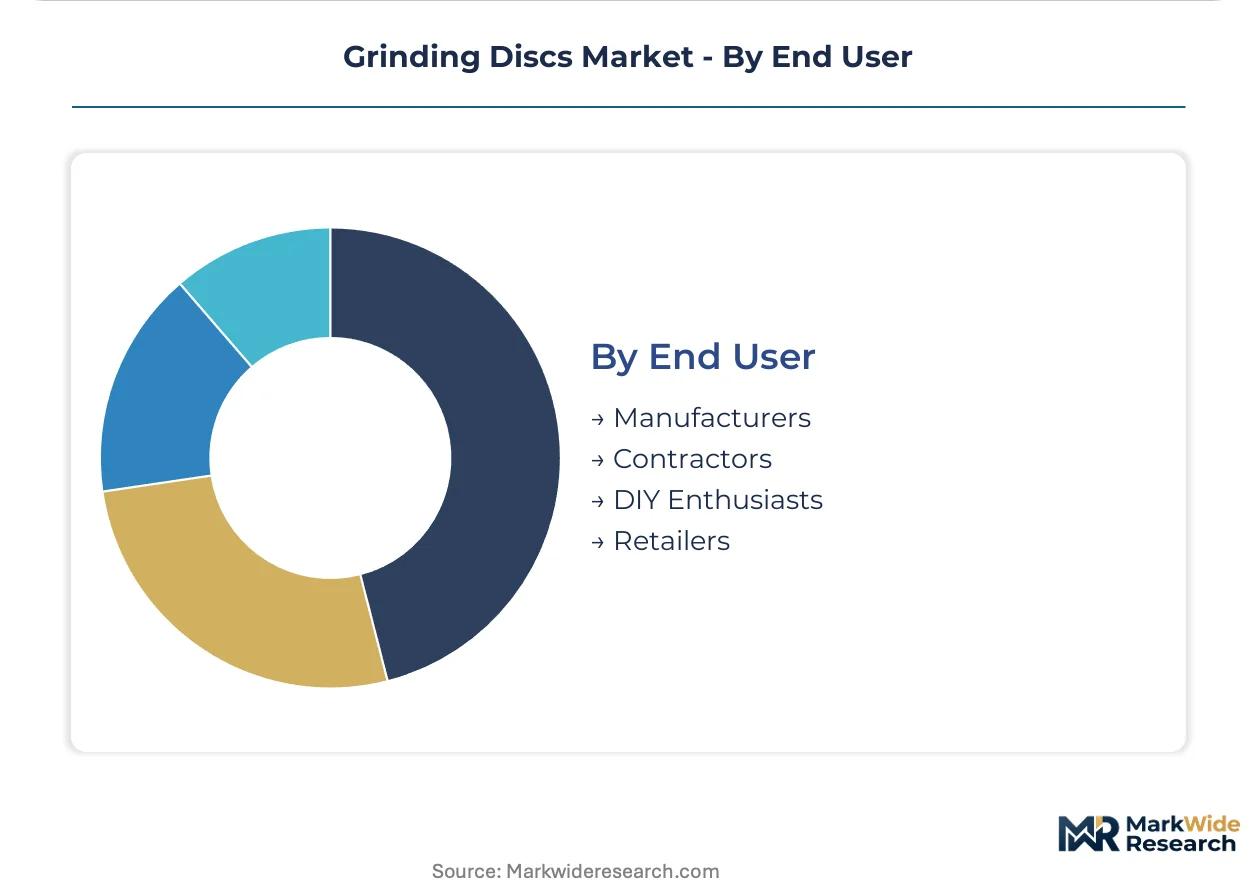
- Manufacturers:Tier-one automotive and aerospace producers specify ceramic grain formulations and mandate REACH-compliant material documentation. German industrial tool clusters concentrate this demand.
- Contractors:Large fabrication operations in California and Texas now require OSHA-compliant silica suppression documentation as a qualification threshold, disqualifying generic import offerings.
- DIY Enthusiasts:Price-sensitive replacement purchases through retail channels favor standard aluminum oxide formulations without premium dust suppression features.
- Retailers:Industrial distributors bundle certified abrasive systems with respiratory protection equipment and dust extraction rentals to capture specification-driven consolidation.
Manufacturers lead volumes today; contractor procurement is concentrating fastest around compliance-bundled offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision abrasive manufacturing in the post-war industrial reconstruction, establishing technical standards that persist across European metalworking supply chains today.
United States
California and Texas fabrication contractors now mandate OSHA-compliant silica suppression documentation as a procurement threshold. EPA air quality standards shape capital allocation decisions at domestic production facilities. Industrial distributors in Houston and Los Angeles bundle certified abrasive systems with respiratory protection equipment.
Germany
Automotive OEMs in Stuttgart and Munich specify ceramic grain discs for EV powertrain grinding operations. REACH synthetic mineral classification accelerates compliant bonded abrasive development. The industrial tool clusters of Bavaria and Baden-Württemberg concentrate aerospace tier-supplier demand.
China
Energy-intensive fused alumina smelting operations expose abrasive grain costs to electricity tariff fluctuations. MEE emissions protocols tighten air quality standards at production facilities. Yangtze River Delta manufacturing hubs favor integrated producers with captive ceramic grain synthesis capabilities.
India
PLI scheme support for capital goods production creates localized abrasive supply advantages. BIS quality marking requirements create product launch timelines alongside international certifications. Maharashtra and Gujarat industrial corridors concentrate construction and metalworking channel demand.
Japan
Tier-one suppliers in Nagoya and Osaka specify seeded-gel aluminum oxide formulations exclusively for precision applications. METI industrial policy supports advanced material manufacturing capabilities. Kanto region automotive supply chains drive specification tightening for dimensional tolerance requirements.
Grinding Discs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification documentation. The vendor base stratifies into three tiers: multinational diversified industrials with power-tool ecosystems, specialized abrasive manufacturers with captive grain synthesis, and regional fabricators serving price-sensitive construction channels. Dominant competitive moves include backward integration into ceramic grain supply and bundling strategies that combine consumables with dust extraction equipment.
Within the diversified industrial tier, Robert Bosch GmbH and 3M Company represent archetypes of ecosystem-anchored distribution. Carborundum Universal Limited exemplifies the regional specialist model with integrated manufacturing presence. These three entities occupy distinct competitive positions without overlapping core strategic vectors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Carborundum Universal Limited |
| 3M Company |
| Weiler Abrasives Group |
| Pferd Inc. |
| Tyrolit Group |
| NORITAKE CO., LIMITED |
| Flexovit USA Inc. |
| Compagnie de Saint-Gobain S.A. |
| Others |
Value Network & Pricing Analysis
OSHA silica exposure mandates gate qualified supply and premium-tier pricing access by disqualifying generic import offerings lacking dust suppression documentation. Large fabrication contractors now bundle certified abrasive systems with respiratory protection equipment, compressing procurement toward compliant suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ceramic grain formulations for automotive powertrain grinding from fused alumina construction variants. Price differentiation rests on REACH certification grade and volume scale. Cost compression in standard aluminum oxide tiers intensifies because Chinese electricity tariff fluctuations expose energy-intensive smelting operations. DIY enthusiasts through retail channels exhibit highest price sensitivity; German automotive OEMs show least.
Supply Chain Analysis
Regional distribution centers in Houston and Los Angeles operate hub-and-spoke patterns bundling certified abrasives with dust extraction rentals. Manufacturing concentrates in China, Germany, and India. Raw material inputs draw from bauxite-derived fused alumina, seeded-gel ceramic grains, and synthetic diamond feedstock. Single-source vulnerability runs through Yangtze River Delta ceramic grain synthesis capabilities. Distribution runs through industrial distributors serving California and Texas construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grinding discs market functions as a stable compounder. EV powertrain precision grinding requirements across automotive OEMs drive steady consumable replacement demand.
For Market Incumbents: To counter ceramic grain synthesis expertise scarcity, deepen backward integration into sol-gel manufacturing capabilities and expand captive supply of heat-resistant formulations. Capacity addition in Maharashtra and Gujarat industrial corridors captures PLI scheme incentives while BIS quality marking investments preempt multi-jurisdiction certification delays. For New Entrants and Emerging Players: Ceramic abrasive technology-first wedges open white-space in modular disc-and-hub aftermarket attachment revenue streams. India's construction and metalworking channels present most penetrable geography given domestic manufacturing incentives. Go-to-market through industrial distributor bundling partnerships with respiratory protection equipment. For Investors and Strategic Acquirers: Roll-up economics work for regional abrasive fabricators because specification-driven procurement consolidation compresses supplier bases around OSHA-compliant documentation. Five-to-ten year viability hinges on REACH-compliant material capabilities. Watch MEE emissions protocol tightening in China as inflection indicator favoring integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grain Supply | Captive sol-gel synthesis hedges against Chinese electricity tariff volatility and raw material cost swings. |
| Modular Disc-and-Hub System Development | Separable backing plate designs reduce per-use material costs and open aftermarket attachment revenue at Bosch and 3M. |
| REACH-Compliant Bonded Abrasive Reformulation | Water-based bonding agents preempt ECHA waste classification restrictions in French and German aerospace supply chains. |
| Dust Suppression Certification Investment | OSHA-compliant documentation qualifies suppliers for California and Texas fabrication contractor procurement thresholds. |
| India PLI-Aligned Capacity Expansion | Maharashtra and Gujarat localized production captures capital goods incentives serving construction and metalworking channels. |
Research Methodology
Bottom-up automotive and metalworking end-use modeling reconciled against top-down abrasive grain supply tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and industrial distributor category managers combine with secondary validation from SEC 10-K filings, customs and trade data, and OSHA enforcement records. Triangulation across these sources grounds volume and value estimates.
Input-output matrix framing maps raw material cost tiers to end-use intensity segments across the projection horizon. Modeled dimensions include product type, material formulation, application intensity, and end-user procurement authority. CAGRs derive from segment-level growth rate reconciliation against macro industrial production indices. Ceramic grain adoption curves and EV powertrain investment trajectories inform automotive segment projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OSHA silica enforcement intensity and REACH substance reclassification timing. Forecasts reflect documented assumptions around regulatory compliance cost pass-through and ceramic grain technology diffusion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gear Hobbing Cutter Market
Tools
Flooring Tools Market
Tools
Belt File Sander Market
Tools
Caulking Gun Market
Tools
Global Flange Fasteners Market
Tools
Digital Levels Market
Tools
Squeegee Market
Tools
Global Cordless Power Tools Market
Tools
Woodworking Circular Saw Blades Market
Tools
Leather Cutting Machine Market
Tools
Portable Rolling Toolbox Market
Tools
Powder Compacting Pressers Market
Tools
Digital Laser Levels Market
Tools
Paint Spray Guns Market
Tools
Foam Engraving Machines Market
Tools
Cutting Equipment Market