
 Blended Cement Market | 2026-2036
Blended Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Blended Cement Market Analysis
Fly ash is shifting from waste-stream liability to primary binder feedstock, cutting clinker ratios below 50% in many formulations. Heidelberg Materials leverages captive power-plant partnerships to secure consistent fly ash quality across European operations. UltraTech Cement anchors its cost position through backward integration into slag grinding infrastructure at steel mill gates. Ambuja Cements differentiates via coastal logistics networks that import granulated blast furnace slag to western Indian markets.
Blended cement combines Portland clinker with supplementary cementitious materials such as fly ash, slag, or calcined clay to reduce carbon intensity while meeting compressive strength specifications. The product achieves equivalent 28-day performance to pure Portland grades at lower embodied carbon, serving as the default specification for green building certifications and public infrastructure tenders. Ground granulated blast furnace slag blends command premium positioning in marine and sulfate-exposure applications where durability requirements exceed standard thresholds. Infrastructure application volumes outpace residential deployment as national development banks tie loan disbursements to low-carbon material specifications.
The EPA enforces coal combustion residuals rules that classify fly ash handling standards, while India's BIS mandates IS 455 and IS 1489 blended cement grades for all public works contracts. The EU Green Deal's carbon border adjustment mechanism will penalize high-clinker imports, redirecting procurement toward slag-rich formulations from domestic kilns. Stakeholders must monitor regulatory divergence between carbon-accounting methodologies as procurement rules harden across jurisdictions.
Market Dynamics
Clinker substitution mandates are compressing the feedstock base for cement producers, forcing rapid reconfiguration of kiln operations and procurement networks around supplementary cementitious materials.
Growth Catalysts
- India's BIS mandate:IS 455 and IS 1489 blended grades are compulsory for all public infrastructure contracts, locking in procurement volumes for domestic producers.
- EU Green Deal carbon border adjustment:The mechanism penalizes high-clinker imports, redirecting demand toward slag-rich domestic formulations.
- Marine infrastructure durability specifications:Ground granulated blast furnace slag blends command premium positioning in sulfate-exposure applications where performance thresholds exceed standard grades.
Market Restraints
- Fly ash supply concentration:Quality material concentrates around captive power-plant partnerships, leaving independent producers exposed to inconsistent feedstock access.
- Slag grinding capex intensity:Steel mill gate infrastructure requires substantial capital deployment, concentrating processing capacity among integrated operators.
- Limestone calcined clay technical ceiling:LC3 formulations face compressive strength validation gaps in high-performance structural applications, limiting specification reach.
Strategic Opportunities
- Vietnam infrastructure pipeline:Mekong Delta megaprojects absorb rising blended cement volumes as development banks tie disbursements to low-carbon material specifications.
- Calcined clay technology convergence:Flash calcination combined with advanced grinding circuits enables clinker factors below 40% without strength penalties.
- Digital procurement platforms:B2B marketplaces for supplementary cementitious materials are disintermediating traditional trader networks in European supply chains.
Industry Challenges
- SCM quality assurance skill gap:Laboratory capacity for fly ash reactivity testing and slag glass content verification lags behind formulation complexity.
- Multi-standard certification timelines:Producers seeking EN 197-1 plus IS 1489 plus ASTM C595 approvals face 18-24 month validation cycles per product variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blended Cement Market |
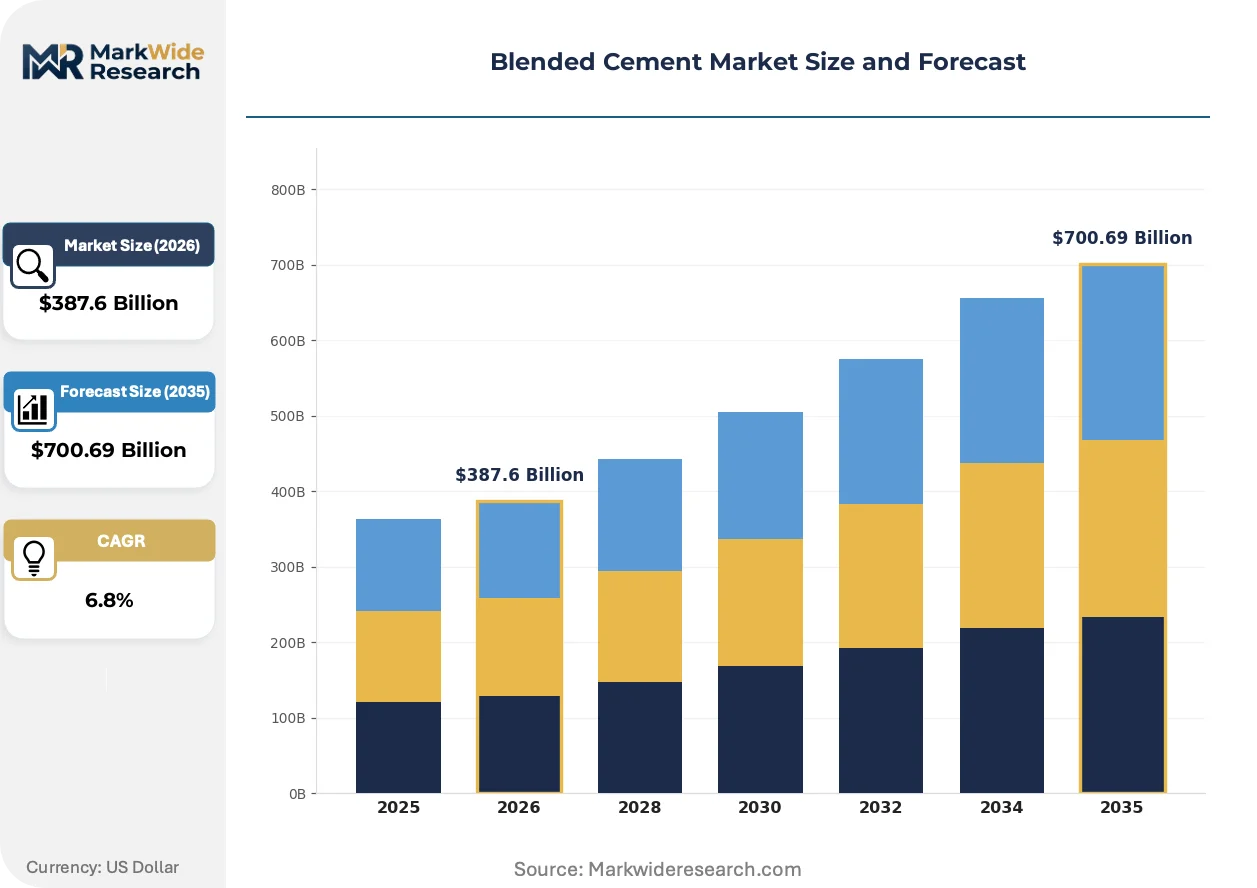
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Composite, Pozzolanic, Ground Granulated Blast Furnace Slag, Fly Ash Application: Residential, Commercial, Infrastructure, Industrial Form: Powder, Granulated, Pelleted, Liquid End User: Contractors, Builders, Government, Real Estate Developers |
| Companies Covered | Holcim, Anhui Conch Cement, Heidelberg Materials, Cemex, UltraTech Cement, Ambuja Cements, JSW Cement, Dalmia Bharat, CRH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blended Cement Market Emerging Trajectories
Electrification of process heat and algorithmic batch optimization are converging to compress embodied carbon per ton while maintaining specification compliance across divergent regional standards.
Calcined clay activation technology is electrifying kiln operations previously dependent on fossil combustion. Major European producers deploy flash calciners powered by renewable electricity to process kaolinitic clays at 800°C. The shift eliminates direct process emissions from clay calcination while enabling clinker substitution rates above 50% in Portland limestone calcined clay cement.
REACH authorization timelines for chromium VI reduction are tightening formulation windows across EU member states. The restriction pushes producers toward alternative activators and modified gypsum sources. Slag-rich blends gain relative advantage as their inherent chemistry requires lower chromate reduction treatment.
Buyers now specify embodied carbon per cubic meter of concrete rather than cement type alone. Contractors in Nordic markets source blended cements by verified Environmental Product Declaration ratings, bypassing traditional grade-based procurement. The shift rewards producers with integrated SCM supply chains and penalizes high-clinker imports regardless of upfront pricing.
Blended Cement Market Segmentation
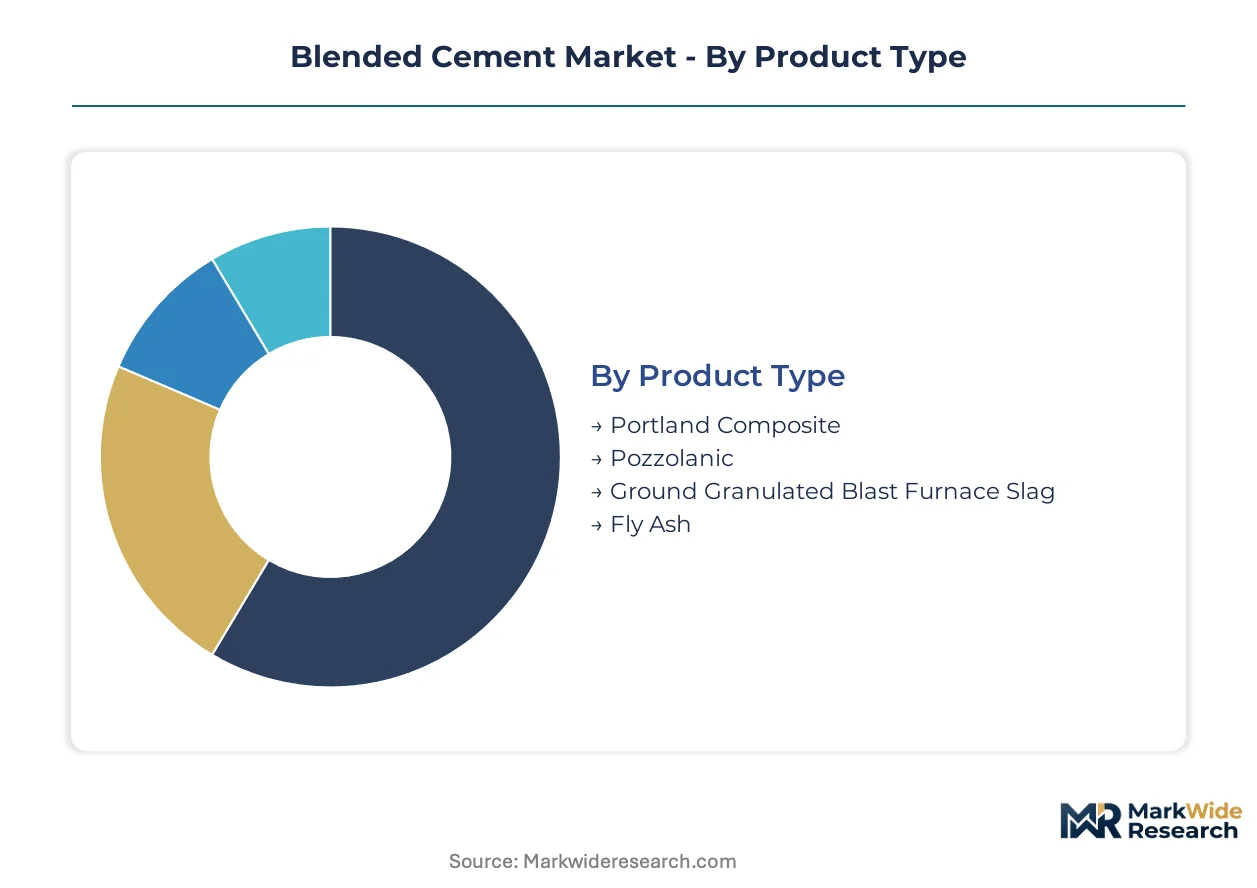
Blended cement specifications diverge sharply across product chemistry, application load requirements, and procurement channel. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning among integrated producers.
Product Type:
The customization-vs-standardization spectrum runs from commodity-grade fly ash blends to specification-intensive slag formulations requiring certified glass content.
- Portland Composite:Combines Portland clinker with multiple supplementary cementitious materials in controlled ratios. Demand concentrates in German and French infrastructure tenders where EN 197-1 CEM II and CEM III specifications mandate provenance documentation.
- Ground Granulated Blast Furnace Slag:High-alumina vitreous material ground to 4000-5000 cm²/g Blaine fineness. Marine infrastructure projects in the Netherlands and Belgium specify this grade exclusively for sulfate-exposure environments where durability thresholds exceed standard Portland performance.
- Pozzolanic:Volcanic-origin or artificial siliceous materials reacting with calcium hydroxide. Italian and Greek producers leverage domestic pozzolan deposits.
- Fly Ash:Coal combustion residue classified by LOI and fineness. Indian power-plant partnerships dominate quality supply.
Most installed capacity flows through Portland Composite. Expansion is steepest in Ground Granulated Blast Furnace Slag.
Application:
Volume concentration tracks public procurement scale, with infrastructure absorbing bulk deliveries under sovereign tender rules.
- Infrastructure:Megaprojects specify low-clinker blends tied to development bank disbursement conditions. Vietnam's Mekong Delta flood-control structures and Indonesia's Trans-Java toll road mandate blended grades.
- Residential:Individual housing construction favors cost-optimized pozzolanic blends. Indian affordable housing schemes drive bulk procurement.
- Commercial:High-rise and retail specifications prioritize consistent setting times.
- Industrial:Manufacturing facility floors and containment structures demand abrasion-resistant formulations.
Public infrastructure commands the dominant volume share. Residential applications are gaining share fastest as housing agency specifications harden.
Form:
Processing intensity separates bulk powder commodity from value-added granulated and pelleted formats.
- Powder:Standard milled product distributed in bulk tankers or bagged. European ready-mix concrete plants absorb volumes through pneumatic discharge systems.
- Granulated:Rapid-cooled slag particles requiring subsequent grinding. Steel mill gate operations in Germany and Poland control supply.
- Pelleted:Pre-agglomerated form reducing dust emission during handling. Coastal import terminals favor this format.
- Liquid:Slurry suspensions for specialized injection applications. Tunneling contractors in Switzerland specify liquid blast furnace slag.
Powder form dominates installed grinding capacity. Pelleted formats are climbing the fastest as dust-control regulations tighten.
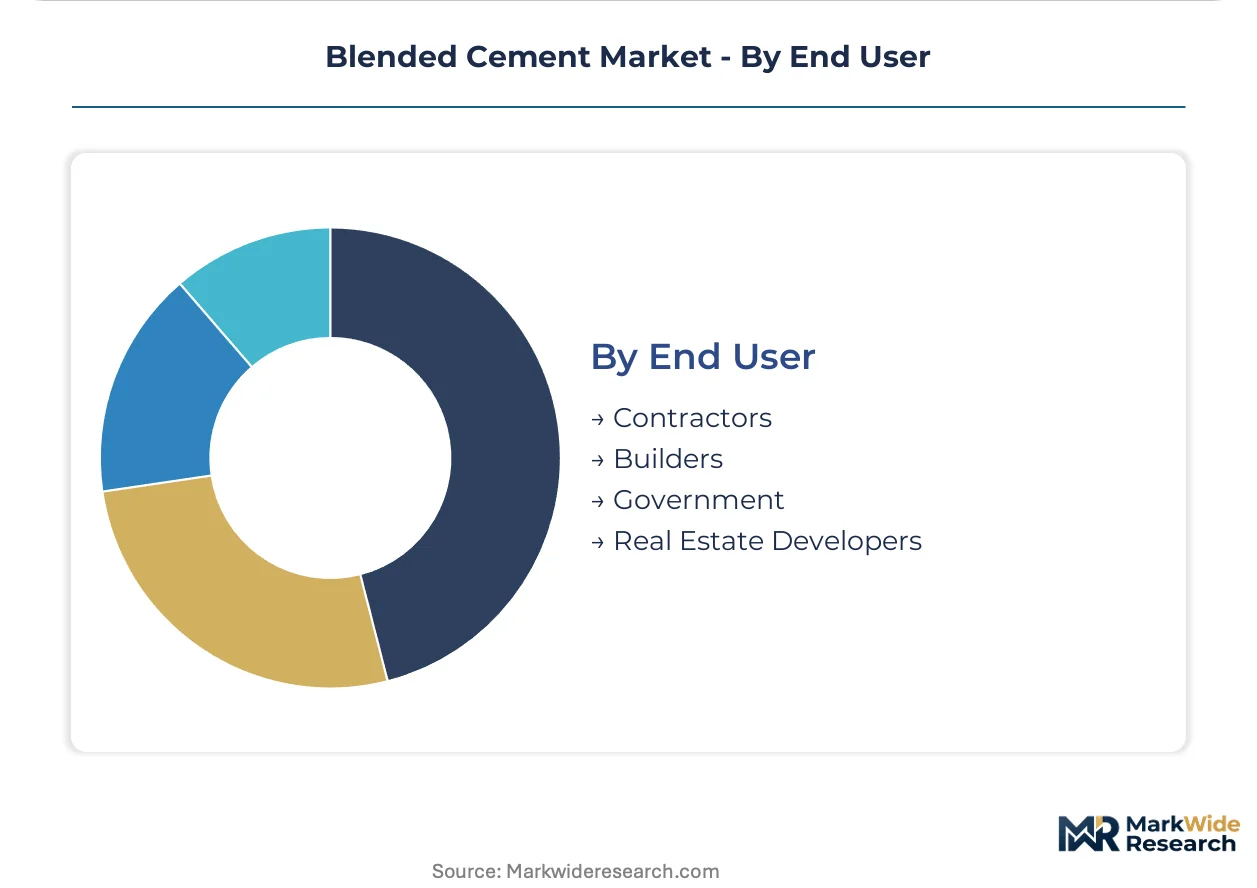
End User:
Procurement sophistication varies from specification-agnostic small builders to carbon-accounting government agencies.
- Government:Public works departments mandate IS 455 and IS 1489 grades in India, EN 197-1 in France and Germany. Tender documents embed Environmental Product Declaration thresholds.
- Contractors:Large construction firms source through annual framework agreements. Nordic contractors verify embodied carbon per cubic meter of concrete.
- Builders:Small and mid-scale residential developers prioritize price over certification.
- Real Estate Developers:Green building certification seekers specify low-clinker blends for LEED and BREEAM compliance.
Government procurement channels concentrate the largest contract volumes. Real estate developers are expanding most quickly as green building mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European blended cement capacity, with slag grinding infrastructure concentrated at steel mill gates. India's Bureau of Indian Standards mandates IS 455 and IS 1489 grades for all public works contracts. Vietnam's Mekong Delta flood-control megaprojects absorb rising volumes as development banks tie disbursements to low-carbon material specifications.
India
Government housing schemes and highway corridors drive bulk procurement of fly ash blends. The Bureau of Indian Standards mandates IS 455 and IS 1489 grades for all public infrastructure contracts. Gujarat's cement belt concentrates slag grinding capacity at steel mill gates near Hazira.
Germany
Marine infrastructure projects in the North Sea specify high-slag formulations for sulfate exposure. The EU Green Deal's carbon border adjustment mechanism penalizes high-clinker imports. The Rhine-Ruhr corridor hosts integrated slag processing at Duisburg steel complexes.
Vietnam
Mekong Delta flood-control structures and Trans-Asia highway segments absorb rising blended volumes. Development banks tie loan disbursements to low-carbon material specifications. Ho Chi Minh City contractors source through framework agreements tied to embodied carbon thresholds.
United States
Coastal infrastructure resilience programs specify slag-rich blends for marine exposure. The EPA enforces coal combustion residuals rules governing fly ash handling standards. Texas and Florida DOTs mandate supplementary cementitious materials in bridge and highway specifications.
Netherlands
North Sea port expansions and coastal defense projects command premium slag formulations. Rotterdam's import terminals handle granulated blast furnace slag from German steel mills. The Port of Rotterdam Authority specifies low-clinker blends for quay wall construction.
Blended Cement Market Vendor Landscape
Capacity expansion dominates the current landscape as producers retrofit kilns for clinker substitution above 50%. The market structures around three tiers: integrated multinationals with captive SCM supply, domestic champions with steel mill partnerships, and regional specialists focused on single formulations. Strategic archetypes include slag-grinding integrators, fly ash aggregators through power-plant contracts, and calcined clay technology licensors. M&A activity concentrates on slag grinding assets and coastal import terminals.
Among European-based multinationals, Heidelberg Materials exemplifies the integrated archetype through captive power-plant partnerships. UltraTech Cement anchors the domestic champion tier with backward integration into steel mill gate operations. Ambuja Cements represents coastal logistics specialists importing granulated blast furnace slag to western Indian markets.
| Leading Market Players |
|---|
| Holcim |
| Anhui Conch Cement |
| Heidelberg Materials |
| Cemex |
| UltraTech Cement |
| Ambuja Cements |
| JSW Cement |
| Dalmia Bharat |
| CRH |
| Others |
Supply Flow & Price Mechanics
India's BIS mandate for IS 455 and IS 1489 grades in public infrastructure contracts forces domestic producers to secure captive fly ash and slag supply, compressing procurement costs for integrated operators while exposing non-integrated competitors to feedstock volatility and margin erosion.
Pricing Analysis
Input-cost pass-through from clinker substitution drives a contract-based long-term offtake pricing model. Price differentiation hinges on certification grade (BIS/EN 197-1/ASTM C595 tier) and volume scale, with government tenders commanding lowest unit costs. Cost compression in standard-grade blends is intensifying because slag grinding capex concentrates processing capacity among steel mill partners. Small residential builders exhibit highest price sensitivity; marine infrastructure contractors prioritize durability performance over upfront cost.
Supply Chain Analysis
Reverse-logistics flows for granulated blast furnace slag reshape procurement geography as steel mills reclaim material for cement grinding partnerships. Supply concentrates in India, Germany, and Vietnam, with raw material dependencies on coal fly ash, blast furnace slag, and calcined clay. Single-source vulnerability runs through captive power-plant fly ash partnerships. Distribution runs through bulk tanker networks to ready-mix concrete plants and coastal import terminals handling pelleted slag.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with India's BIS mandate and the EU Green Deal's carbon border adjustment mechanism locking in procurement volumes for compliant producers.
For Market Incumbents: Deploy slag grinding capacity additions at steel mill gates in Gujarat and the Rhine-Ruhr corridor to defend against calcined clay technology licensors. Secure captive fly ash partnerships before independent power producers divert material to alternative binders. Cement producers without backward integration face structural margin pressure from feedstock access asymmetry. For New Entrants and Emerging Players: Coastal logistics specialists importing granulated blast furnace slag to western Indian markets represent the most penetrable buyer archetype. Target Vietnam's Mekong Delta flood-control contractors through framework agreements tied to embodied carbon thresholds. Establish digital procurement platforms for supplementary cementitious materials to disintermediate European trader networks. For Investors and Strategic Acquirers: Asymmetric upside sits with slag grinding assets and coastal import terminals as clinker substitution mandates harden across jurisdictions. Five-to-ten year viability favors operators with integrated SCM supply chains and multi-standard certification capacity. Monitor BIS enforcement intensity and EU carbon border adjustment implementation pace as inflection indicators for procurement rule divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slag Grinding | Steel mill gate operations in Hazira and Duisburg secure feedstock access under BIS and EU Green Deal rules. |
| Captive Fly Ash Partnerships | Power-plant contracts lock in quality supply for IS 455 and IS 1489 grade production in India's cement belt. |
| Multi-Standard Certification Investment | EN 197-1 plus IS 1489 plus ASTM C595 approvals enable cross-border tender participation for infrastructure megaprojects. |
| Coastal Import Terminal Expansion | Rotterdam and western Indian terminals handle granulated blast furnace slag for sulfate-exposure marine applications. |
| Calcined Clay Technology Licensing | Flash calcination systems enable clinker factors below 40% for producers seeking premium green building certification positioning. |
Methodological Framework
Coverage spans India, Germany, Vietnam, the Netherlands, and the United States, with primary inputs from each market combining interviews with cement plant operations managers, public works procurement officers, steel mill slag sales directors, and ready-mix concrete technical specialists. Secondary validation draws from BIS grade specifications, EU Green Deal regulatory texts, EPA coal combustion residuals rules, customs trade data for granulated slag imports, and cement producer SEC filings. Bottom-up volume estimates from grinding capacity utilization triangulate against top-down infrastructure disbursement projections.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions modeled include product chemistry (Portland Composite, Ground Granulated Blast Furnace Slag, Pozzolanic, Fly Ash), application load requirements (Infrastructure, Residential, Commercial, Industrial), and procurement channel sophistication (Government, Contractor, Builder, Real Estate Developer). CAGRs derive from trend extrapolation of clinker substitution rates and regulatory mandate implementation timelines, with industry-specific inputs from development bank disbursement conditions and green building certification adoption curves.
Inputs from regulatory filings and producer disclosures were available through the study window; gaps in real-time slag grinding capacity utilization data introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented clinker substitution trajectories and carbon border adjustment implementation assumptions. Practitioners should monitor BIS enforcement actions, EU carbon border adjustment mechanism rollout pace, and flash calcination technology cost curves for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Dry Mix Mortar Market
Building Materials
Concrete and Cement Market
Building Materials
Masonry Cement Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Glass Facade Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
India Concealed Cistern Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Fly Ash Bricks Market
Building Materials
Construction Materials Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
Cribbing Blocks Market
Building Materials
US Facade Market
Building Materials
Indonesia Architectural Coatings Market