
 Rotary Trommel Market | 2026-2036
Rotary Trommel Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Trommel Market Analytics
Equipment leasing and project finance for mobile trommel fleets is rewriting competitive access for mid-sized contractors. McLanahan Corporation leverages its foundry-to-field vertical integration to control drum fabrication quality. Doppstadt anchors German engineering credibility in compost and biomass screening. Vermeer competes through its dealer network density across North American construction corridors.
A rotary trommel is a cylindrical screening drum mounted on a slight incline, rotated by a drive mechanism at speeds typically between 10 and 25 RPM, with perforated or woven mesh panels that classify materials by particle size as feedstock cascades through the drum. Its primary industrial purpose is to separate bulk solids into uniform fractions for downstream processing in mining, recycling, and aggregate operations. Mobile trommel configurations command premium positioning due to contractor demand for rapid site relocation without crane-assisted assembly. Waste management end users represent the fastest-growing installation base as landfill diversion targets intensify across OECD jurisdictions. Permanent installations in sand classification applications form a mature, replacement-driven revenue pool with predictable maintenance cycles.
EPA emission standards for diesel-powered mobile equipment shape engine retrofit requirements across US recycling yards. EU F-Gas Regulation and REACH compliance on hydraulic fluids constrain component sourcing for European OEMs including Pronar and Eggersmann GmbH. ISO 21873 mobile machinery safety standards govern guarding and emergency stop protocols for export-bound units. Stakeholders must monitor how battery-electric drivetrain certification timelines intersect with contractor fleet renewal decisions.
Market Dynamics
EU Green Deal circular-economy mandates are forcing waste management operators across Germany and France to accelerate mobile trommel fleet replacements, while steel alloy drum innovations from Nordic suppliers compress equipment lifecycle costs in abrasive sorting environments.
Growth Catalysts
- EU F-Gas Regulation:Hydraulic fluid compliance requirements under REACH are driving replacement demand for legacy trommel fleets in European recycling yards.
- Australian iron ore screening corridors:Bulk mineral processors are expanding trommel installations to handle higher throughputs amid infrastructure project pipelines.
- Steel alloy drum fabrication:Nordic metallurgical advances are extending drum wear life in high-abrasion aggregate applications, reducing downtime costs.
Market Restraints
- High-grade steel input volatility:Specialty alloy plate prices fluctuate with scrap metal arbitrage between European and Asian foundries.
- German engineering supply concentration:Premium drum fabrication capacity clusters with a narrow base of Bavarian and Rhineland metalworking specialists.
- Stationary trommel substitution:Vibrating screen systems capture share in permanent sand classification installations with lower capital intensity.
Strategic Opportunities
- Brazilian aggregate processing hubs:Infrastructure investment cycles in São Paulo and Minas Gerais states are opening contractor equipment procurement windows.
- Battery-electric drivetrain convergence:Integration of solid-state battery packs with regenerative braking systems is enabling diesel-free mobile trommel operation at quarry sites.
- Equipment leasing channel innovation:Project finance structures are democratizing mobile fleet access for mid-sized waste management contractors previously locked out of ownership.
Industry Challenges
- ISO 21873 certification timelines:Mobile machinery safety compliance for export-bound units creates order-to-delivery gaps that strain contractor project scheduling.
- Mechatronics skill scarcity:Maintenance technicians capable of servicing integrated drum-drive-electronics systems command wage premiums that inflate operator opex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Trommel Market |
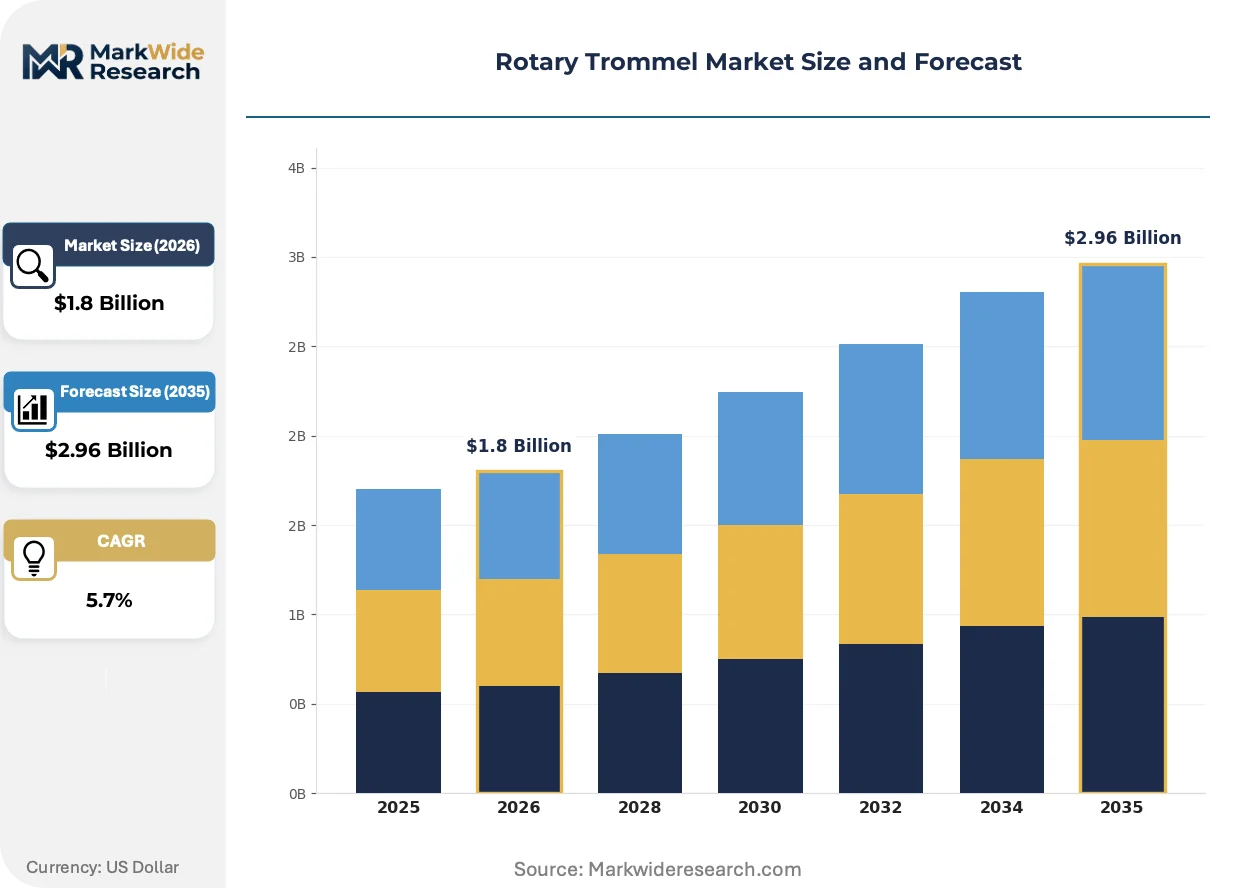
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Trommel, Mobile Trommel, Heavy-Duty Trommel, Mini Trommel End User: Mining, Construction, Recycling, Waste Management Installation Type: Permanent, Portable, Semi-Permanent, Fully Assembled Application: Soil Screening, Material Sorting, Aggregate Processing, Sand Classification |
| Companies Covered | McLanahan Corporation, Doppstadt, McCloskey International, Pronar, EDGE Innovate, Terex Corporation, Eggersmann GmbH, Filson Filter, Vermeer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Trommel Market Evolving Landscape
Rotary trommel engineering is pivoting toward modularity and emissions compliance as regulatory pressure intersects with contractor demands for operational flexibility across dispersed job sites.
Woven wire mesh panel systems is migrating from traditional fixed-peg mounting toward quick-release clamp mechanisms that permit 15-minute screen changeouts. Australian bulk mineral processors are piloting these configurations at Pilbara iron ore operations. The shift is compressing maintenance windows and enabling multi-fraction classification campaigns without crane-assisted drum access.
EPA emission standards for diesel-powered mobile equipment are mandating engine retrofit kits or full powertrain replacements across US recycling yard fleets. Equipment owners in California and Texas are front-loading capital expenditure to avoid operational shutdown risks. The regulation is accelerating interest in battery-electric alternatives among contractors with multi-site municipal contracts.
Mid-sized waste management contractors are consolidating procurement decisions through regional equipment cooperatives that negotiate fleet-scale leasing terms. Traditional dealer networks in North American construction corridors face disintermediation pressure from direct manufacturer finance arms. The pattern is most visible in compost and biomass screening segments where project tenures favor short-term equipment access over ownership.
Rotary Trommel Market Segmentation
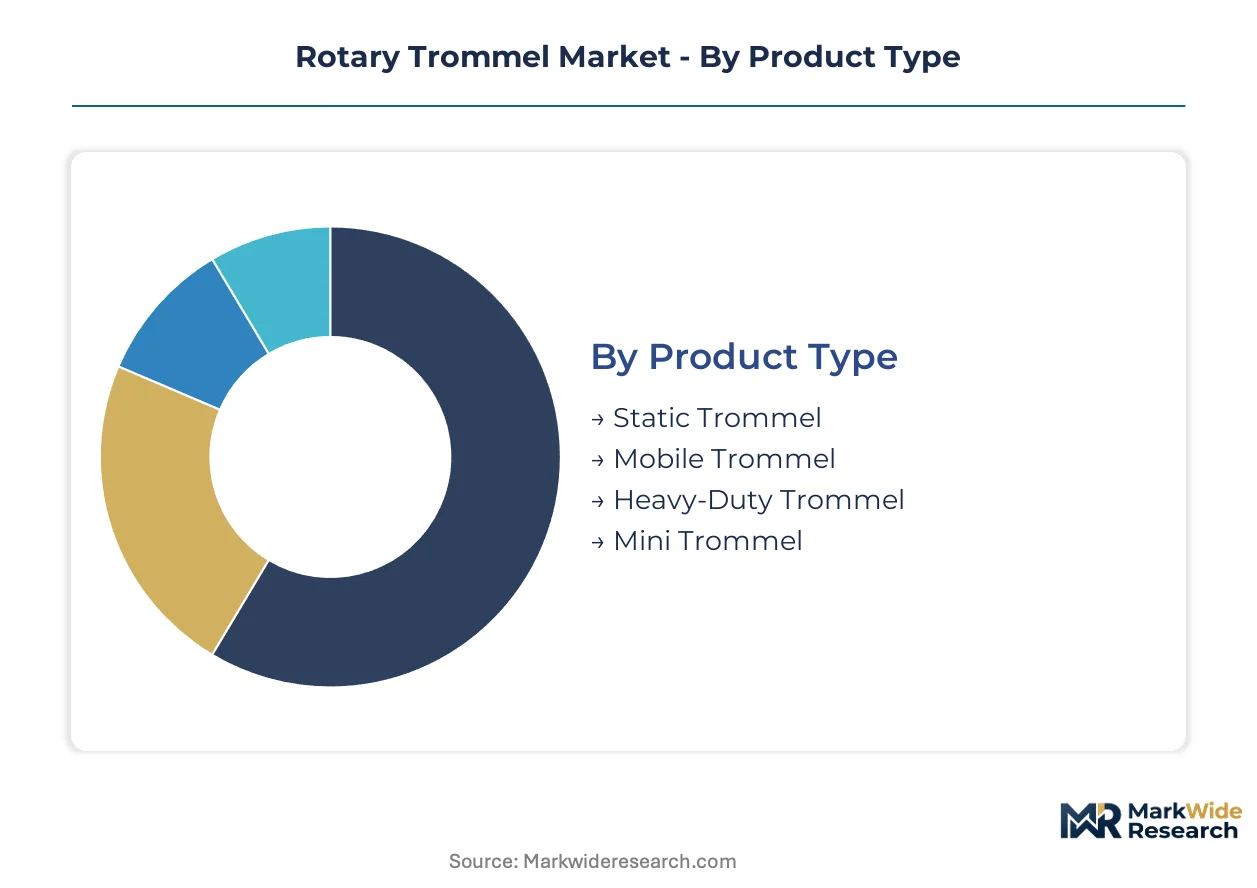
Rotary trommel segmentation reveals how equipment specifications align with distinct operational constraints across mining corridors, recycling yards, and aggregate processing sites. Procurement patterns diverge sharply between contractors prioritizing site mobility and permanent installations serving high-volume mineral classification.
Product Type:
Use-case spectrum spans from fixed-base mineral processing to rapid-deployment waste screening across dispersed municipal contracts.
- Mobile Trommel:Self-propelled or trailer-mounted units with integrated diesel or battery-electric powertrains enable same-day relocation between construction debris sites and composting facilities. Demand concentrates with German and French waste management operators executing EU Green Deal landfill diversion mandates, where fleet flexibility determines contract win rates.
- Static Trommel:Foundation-anchored installations with higher throughput capacity serve Australian iron ore screening corridors and Brazilian aggregate hubs. Pilbara bulk mineral processors favor these configurations for continuous 24-hour operation with minimal maintenance windows.
- Heavy-Duty Trommel:Reinforced drum assemblies with abrasion-resistant steel alloy construction target high-wear environments including demolition concrete recycling and foundry sand reclamation.
- Mini Trommel:Compact skid-mounted or wheeled units under 2.5 meters drum diameter address landscaping contractors and small-scale compost producers with limited capital budgets.
The dominant share belongs to Static Trommel configurations in mining applications, while Mobile Trommel demand is closing the gap fastest among European waste management fleets.
End User:
Customer procurement authority varies from centralized mining house engineering departments to fragmented municipal contractor networks.
- Waste Management:Landfill diversion targets across OECD jurisdictions are accelerating fleet replacement cycles for compost, biomass, and construction debris screening. Operators in Germany and France are scaling mobile deployments fastest under circular-economy procurement mandates.
- Mining:Bulk mineral processors in Australian iron ore corridors and Brazilian aggregate hubs specify heavy-duty static configurations with 50+ ton per hour throughput ratings.
- Recycling:C&D debris and electronic waste processors demand quick-change screen panels to handle variable feedstock compositions across single-shift campaigns.
- Construction:Road building and infrastructure contractors favor portable units for on-site aggregate reprocessing to reduce haulage costs and virgin material procurement.
Mining retains the largest installed base by value, though Waste Management exhibits the steepest expansion trajectory as landfill diversion regulations tighten.
Installation Type:
Deployment architecture determines capital commitment timelines and residual equipment mobility value.
- Permanent:Concrete-anchored installations with fixed electrical infrastructure dominate sand classification facilities and high-volume aggregate processing plants where 15+ year operational horizons justify foundation investment.
- Portable:Modular skid-mounted or trailer-based configurations without permanent foundations serve contractors with multi-site project portfolios. Brazilian infrastructure investment cycles in São Paulo and Minas Gerais states are opening procurement windows for this category.
- Semi-Permanent:Bolt-down installations with rapid disassembly capability bridge the gap between long-term site commitments and eventual relocation needs.
- Fully Assembled:Factory-integrated units delivered ready for immediate commissioning reduce field assembly risk for remote mining site deployments.
Permanent installations command the greatest cumulative revenue share, yet Portable configurations are gaining share fastest as contractor leasing channels democratize fleet access.
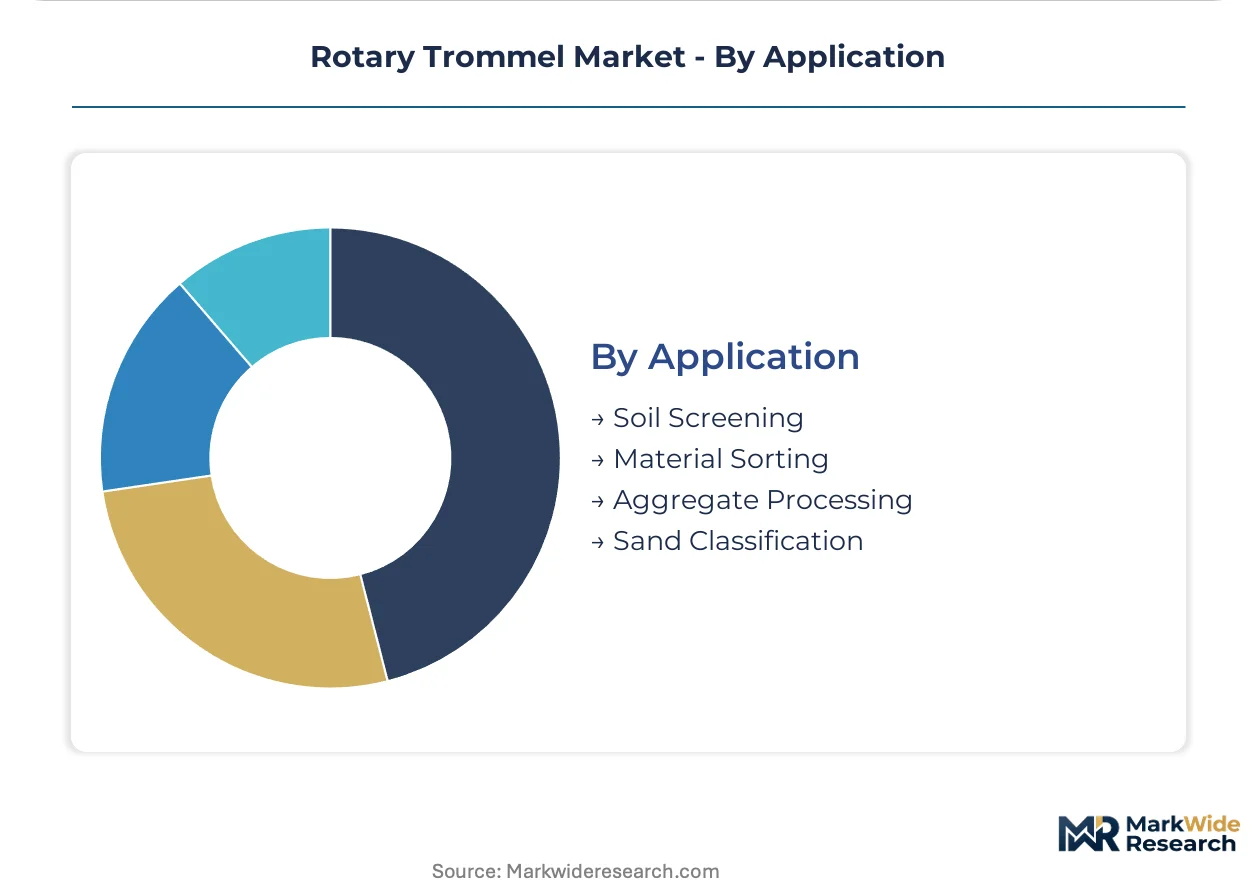
Application:
Process requirements dictate drum aperture specifications, rotational speed profiles, and downstream material handling integration.
- Aggregate Processing:Multi-fraction classification of crushed stone, gravel, and sand for concrete and asphalt production. Australian and Brazilian infrastructure pipelines are sustaining replacement demand for high-capacity static configurations.
- Soil Screening:Topsoil and compost remediation for landscaping and agricultural amendment markets. EPA emission standards for diesel-powered mobile equipment are shaping engine retrofit requirements across US recycling yards serving this segment.
- Material Sorting:Mixed C&D debris and municipal solid waste separation into combustible, recyclable, and residual streams. Quick-release clamp mechanisms for 15-minute screen changeouts are migrating from pilot programs to standard specifications.
- Sand Classification:Foundry sand reclamation and frac sand processing demand precise particle size distribution control with minimal fines carryover.
Aggregate Processing anchors the revenue base, while Material Sorting applications are climbing the fastest as circular-economy mandates expand feedstock diversion targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in rotary trommel equipment tilt toward surplus positions for German and Australian fabricators, while Brazilian and Indian markets absorb inbound mobile units to serve infrastructure buildouts. Currency volatility and steel alloy input costs are reshaping cross-border procurement timelines for mid-sized contractors.
Germany
Waste management operators in Bavaria and North Rhine-Westphalia are replacing legacy diesel fleets with EU Green Deal-compliant mobile configurations. REACH hydraulic fluid mandates from ECHA are disqualifying older trommel models from municipal tender participation. Engineering clusters around Düsseldorf and Munich anchor drum fabrication capacity for abrasive-sorting applications.
Australia
Pilbara iron ore processors are expanding static trommel installations to handle elevated throughputs from infrastructure project pipelines. EPA emission standards shape diesel retrofit requirements for mobile units operating across Queensland recycling corridors. Perth-based engineering houses supply heavy-duty configurations to bulk mineral classification sites in Western Australia.
United States
Construction debris recyclers in Texas and California are front-loading capital expenditure to avoid EPA mobile equipment shutdown risks. Equipment leasing cooperatives in the Midwest are consolidating procurement decisions for compost and biomass screening fleets. Dealer network density across North American construction corridors determines contractor equipment access.
Brazil
Infrastructure investment cycles in São Paulo and Minas Gerais states are opening procurement windows for portable trommel configurations. ANVISA compliance requirements on hydraulic component imports constrain sourcing flexibility for regional contractors. Aggregate processing hubs around Belo Horizonte are scaling screening capacity for concrete and asphalt production.
France
Landfill diversion targets under EU circular-economy mandates are accelerating mobile trommel deployments by waste management operators in Île-de-France. EU F-Gas Regulation constraints on component sourcing are compressing order-to-delivery timelines for equipment refreshes. Industrial clusters in Auvergne-Rhône-Alpes specialize in quick-release screen panel systems for multi-fraction classification.
Rotary Trommel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in drum fabrication and drive mechanism supply. Market structure tilts toward consolidation among full-line manufacturers with captive foundry capacity, while niche fabricators compete on rapid customization cycles. Strategic archetypes separate vertically integrated engineering houses from modular assembly specialists and regional lease-finance operators. Dominant competitive moves include backward integration into steel alloy drum production and geographic expansion through distributor acquisition.
Within the integrated-system tier, McLanahan Corporation exemplifies the foundry-to-field archetype with upstream control over drum fabrication quality. Among German engineering specialists, Doppstadt occupies a position anchored in compost and biomass screening credibility. Vermeer represents the dealer-network-density model across North American construction corridors, sitting within the mobile equipment distribution archetype.
| Leading Market Players |
|---|
| McLanahan Corporation |
| Doppstadt |
| McCloskey International |
| Pronar |
| EDGE Innovate |
| Terex Corporation |
| Eggersmann GmbH |
| Filson Filter |
| Vermeer |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation compliance costs on hydraulic component sourcing compress margins for European OEMs while simultaneously widening price spreads between certified and non-certified equipment tiers. This regulatory chokepoint forces buyers to absorb premium positioning for REACH-compliant configurations or accept operational exclusion from municipal tenders.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle ISO 21873 certification, extended wear warranties, and quick-release screen panel systems; standard configurations compete on throughput ratings; economy units target mini-trommel landscaping contractors. Pricing pressure stems from high-grade steel alloy input volatility between European and Asian foundries. Waste management contractors exhibit highest price sensitivity due to municipal tender margin constraints, while Pilbara iron ore processors prioritize lifecycle cost over acquisition price.
Supply Chain Analysis
Extended payment terms from Bavarian and Rhineland metalworking specialists now stretch to 90-120 days, reflecting working capital pressure from scrap metal arbitrage volatility. Drum fabrication capacity concentrates in Germany, Australia, and Brazil. Raw material inputs draw from Nordic steel alloy suppliers, Chinese perforated mesh manufacturers, and Italian drive mechanism specialists. Single-source vulnerability sits with specialty abrasion-resistant plate mills in Scandinavia. Distribution runs through manufacturer-direct finance arms and regional equipment cooperatives that displace traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary trommel incumbents face substitution pressure from vibrating screen systems in permanent sand classification applications, requiring defensive positioning around mobility value and rapid screen changeout capabilities.
For Market Incumbents: Insulate core mining and waste management accounts by backward integration into steel alloy drum production and captive foundry capacity. Prioritize ISO 21873 certification investment to preempt regulatory disqualification. Defend against vibrating screen substitution by emphasizing same-day relocation value in municipal contracts.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian portable trommel procurement windows opened by São Paulo and Minas Gerais infrastructure cycles. Target mini-trommel landscaping contractors with skid-mounted units under 2.5 meter drum diameter. Lead with equipment leasing channel partnerships that bypass incumbent dealer network density.
For Investors and Strategic Acquirers: EU Green Deal landfill diversion mandates reshape the acquisition landscape toward mobile fleet operators with circular-economy contract portfolios. Long-term viability centers on battery-electric drivetrain readiness and quick-release screen panel IP. Watch battery-electric certification timeline convergence with contractor fleet renewal decisions as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Alloy Drum Production | Captive foundry capacity insulates McLanahan and Doppstadt from scrap metal arbitrage volatility. |
| Battery-Electric Drivetrain Certification Investment | EPA emission standards in California and Texas accelerate contractor interest in diesel-free mobile configurations. |
| Quick-Release Screen Panel System Development | Australian Pilbara iron ore processors pilot 15-minute changeout mechanisms for multi-fraction classification. |
| Equipment Leasing Channel Partnership | Mid-sized waste management cooperatives in the US Midwest consolidate procurement through direct manufacturer finance arms. |
| Geographic Expansion into Brazilian Aggregate Hubs | Belo Horizonte infrastructure investment cycles open procurement windows for portable trommel configurations. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across mining and waste management operations; and secondary validation through customs/trade data, SEC equipment manufacturer filings, and EU ECHA regulatory compliance databases. Bottom-up unit shipment estimates triangulated against top-down mineral processing capacity expansion announcements.
Forecast inputs considered mobile versus static configuration mix shifts, steel alloy price trajectory assumptions, and battery-electric drivetrain adoption curves across the projection horizon. Segmentation dimensions modeled include product type, end user industry, installation architecture, and application process requirements. CAGRs derived from regression analysis against infrastructure investment pipelines and landfill diversion regulatory timelines.
Stress conditions across steel input costs, EU F-Gas Regulation enforcement intensity, and Brazilian currency volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vertical Mill Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Trenchers Market