
 Draw Heat Setting Winder Market | 2026-2036
Draw Heat Setting Winder Market Size, Share, and Industry Trends Forecast 2026-2036
Draw Heat Setting Winder Market Foresight
Digital twin integration with real-time thermal profiling is rewriting how draw heat setting winders optimize yarn tenacity and elongation consistency. SSM Schärer Schweiter Mettler AG leverages its Swiss engineering heritage to sustain premium positioning in precision winding systems. Murata Machinery, Ltd. anchors Asian supply networks through extensive service infrastructure across key textile clusters. Oerlikon Textile GmbH competes on automation depth, offering end-to-end filament processing lines that reduce manual intervention.
A draw heat setting winder combines sequential drawing and heat-setting operations to stabilize synthetic yarn molecular structure, typically processing polyester and nylon at controlled temperatures between 180°C and 220°C to achieve dimensional stability for downstream weaving and knitting. The equipment serves textile manufacturers requiring consistent yarn shrinkage control for automotive upholstery, industrial belting, and technical apparel applications. Fully automatic systems now dominate capital procurement budgets as labor costs rise and throughput requirements tighten, while hybrid configurations gain traction among mid-scale producers seeking upgrade pathways without full line replacement. Thermal regulation technology represents the fastest-improving performance dimension, with advanced PID control systems narrowing temperature variance to within ±1.5°C.
EU REACH regulations and the F-Gas Directive constrain solvent-based heat-setting chemistries and refrigerant choices in European installations, pushing OEMs toward closed-loop thermal recovery architectures. China's GB standards for textile machinery safety and India's BIS certification requirements for imported industrial equipment create layered compliance obligations for multinational suppliers. Japan's METI energy efficiency benchmarks additionally shape product development priorities for premium segment entries. Stakeholders must monitor how carbon border adjustment mechanisms reshape total cost of ownership calculations across competing manufacturing geographies.
Market Dynamics
Digital twin technology is compressing commissioning cycles and forcing incumbent OEMs to restructure service revenue models around predictive thermal analytics rather than scheduled maintenance contracts.
Growth Catalysts
- EU F-Gas Directive phase-down:Mandated refrigerant transitions are accelerating replacement demand for closed-loop thermal recovery systems in European polyester processing plants.
- Vietnam textile corridor expansion:Ho Chi Minh City industrial zones are adding draw heat setting capacity to serve automotive upholstery export contracts.
- Real-time PID control advancement:Temperature variance reduction to ±1.5°C enables premium yarn grades for technical belting applications.
Market Restraints
- Specialized alloy supply concentration:Heat-resistant chamber components depend on German and Japanese specialty steel suppliers with extended lead times.
- REACH compliance cost escalation:ECHA registration requirements for heat-setting chemistry additives inflate total cost of ownership for European installations.
- Induction heating substitution:Emerging electromagnetic yarn stabilization methods threaten conventional conductive thermal systems in niche applications.
Strategic Opportunities
- India technical textile mandate:BIS certification pathways for industrial yarn equipment open procurement channels under the PLI scheme for man-made fibers.
- Digital twin convergence:Integration of physics-based simulation with live thermal profiling creates outcome-based service contracting models.
- Recycled PET feedstock expansion:Post-consumer bottle-to-yarn lines require modified heat-setting protocols for rPET molecular structure stabilization.
Industry Challenges
- Thermal systems engineering talent scarcity:Specialized expertise in combined mechanical winding and precision temperature control commands premium compensation in Southeast Asian manufacturing hubs.
- Legacy DCS integration complexity:Brownfield polyester plants face protocol mismatches between proprietary winder controls and existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Draw Heat Setting Winder Market |
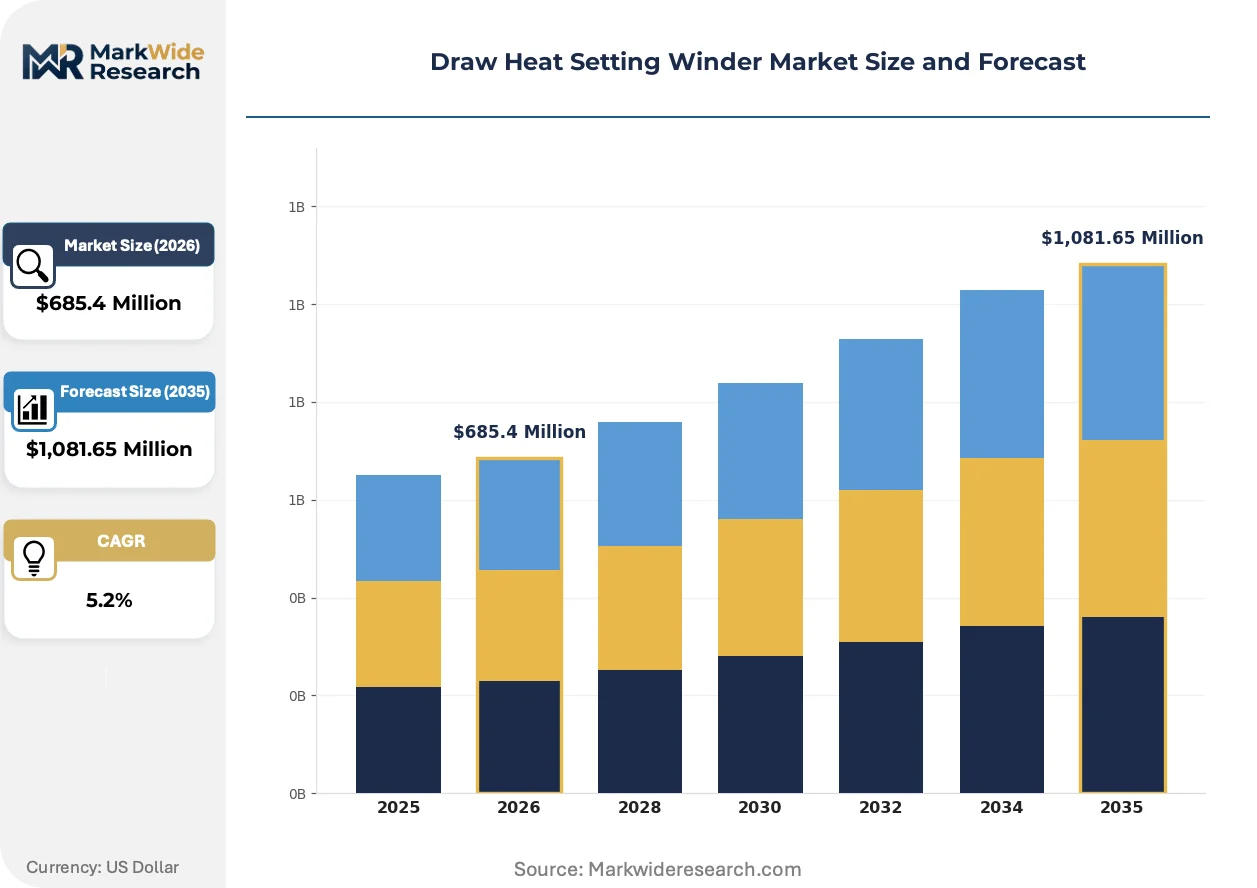
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Manual, Hybrid End User: Textile Industry, Automotive, Electronics, Aerospace Application: Yarn Processing, Fabric Treatment, Material Winding, Quality Control Technology: Thermal Regulation, Control Systems, Automation, Monitoring Solutions |
| Companies Covered | SSM Schärer Schweiter Mettler AG, Oerlikon Textile GmbH, Murata Machinery, Ltd., Savio Macchine Tessili S.p.A, TMT Machinery, Inc., Rieter Holding AG, Vandewiele NV, Superba S.p.A., Peass Industrial Engineers Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Draw Heat Setting Winder Market Shifts & Advancements
Equipment intelligence layers are separating hardware commoditization from software-defined performance optimization, rewriting how value migrates through the supply chain.
Physics-based digital twin software is virtualizing thermal chamber behavior ahead of physical commissioning. Automotive upholstery yarn producers in Germany and Japan are deploying these tools to compress qualification timelines for new polyester grades. Virtualization is virtualizing the traditional pilot-line validation step, collapsing months of iterative testing into simulation cycles.
REACH authorization requirements for persistent organic pollutants are restricting legacy heat-setting chemical formulations. ECHA sunset date pressures are forcing reformulation investments across European filament processors. Automotive technical textile suppliers face the tightest compliance windows, with some accelerating equipment replacement to avoid chemistry re-registration costs.
Buyer consolidation among synthetic yarn multinationals is concentrating procurement leverage. Tier-1 polyester producers are unbundling aftermarket service contracts from initial equipment purchases, forcing OEMs to compete separately on spare parts and technical support. This pattern is most pronounced in Vietnam's manufacturing corridor, where new plant builds attract competing service-only bids from European and Japanese suppliers.
Draw Heat Setting Winder Market Segmentation
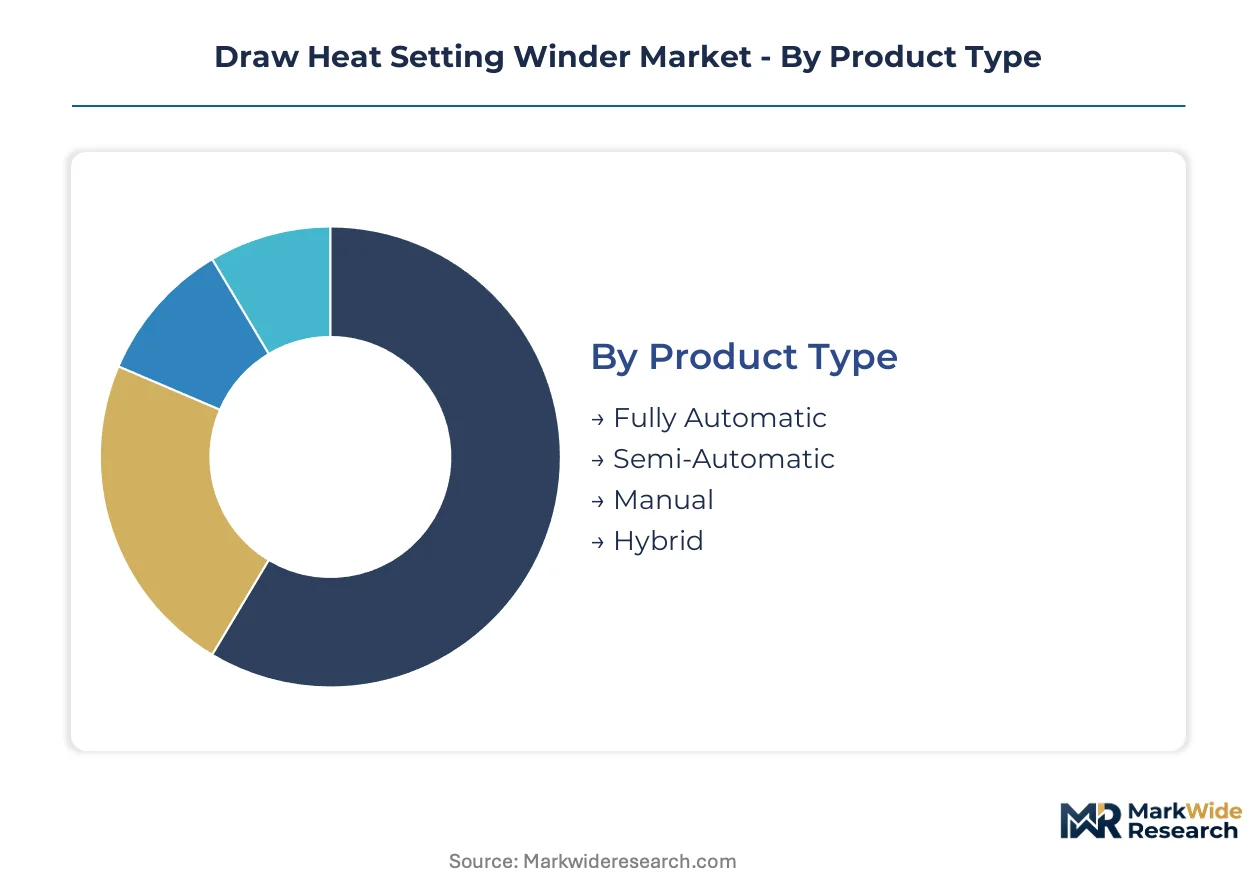
Draw heat setting winders serve divergent operational requirements across polyester industrial yarn production, automotive upholstery supply chains, and technical textile manufacturing. Segmentation reveals how equipment specifications align with thermal precision demands, throughput scale, and integration complexity in downstream processing environments.
Product Type:
Automation intensity defines capital allocation patterns across synthetic yarn processing facilities, with labor cost trajectories and quality consistency requirements driving procurement decisions.
- Fully Automatic:Systems integrate sequential drawing, heat-setting, and precision winding with minimal operator intervention. Vietnam's Ho Chi Minh City textile corridor favors these configurations for automotive upholstery export contracts where dimensional stability tolerances are tightest.
- Hybrid:Configurations combine automated thermal chambers with semi-automated winding heads, offering upgrade pathways for mid-scale producers. European polyester processors under ECHA registration pressures deploy hybrid systems to defer full capital replacement while meeting REACH compliance windows.
- Semi-Automatic:Equipment retains manual loading stations with automated thermal profiling, common in India's technical textile sector where BIS certification requirements favor phased automation adoption.
- Manual:Basic configurations serve specialty yarn producers requiring frequent grade changeovers and small batch flexibility.
The dominant share belongs to Fully Automatic systems, while Hybrid configurations are closing the gap fastest.
End User:
Downstream industry specifications determine thermal chamber design priorities and control system sophistication levels.
- Textile Industry:Synthetic yarn manufacturers processing polyester and nylon for weaving and knitting operations. Germany's automotive upholstery suppliers demand ±1.5°C temperature variance control for technical belting applications.
- Automotive:Tier-1 seating and interior trim suppliers requiring shrinkage-stable yarns for injection molding compatibility. Japan's METI energy efficiency benchmarks shape equipment selection for premium segment entries.
- Electronics:Producers of high-tenacity fibers for cable reinforcement and flexible circuit substrates.
- Aerospace:Manufacturers of aramid and carbon fiber precursors requiring ultra-precise molecular orientation control.
Textile Industry procurement maintains the largest installed base, though Automotive specifications are expanding most quickly.
Application:
Process stage integration determines whether equipment operates as standalone units or within continuous filament processing lines.
- Yarn Processing:Core application stabilizing drawn synthetic fibers through controlled thermal exposure. Post-consumer rPET feedstock expansion is modifying heat-setting protocols for recycled molecular structure stabilization.
- Fabric Treatment:Direct heat-setting of woven or knitted constructions for dimensional stability prior to garment manufacturing.
- Material Winding:Precision package formation for downstream warping and knitting operations.
- Quality Control:Inline tenacity and elongation monitoring with automatic defect rejection protocols.
Yarn Processing commands the principal revenue share, while Quality Control integration is gaining share fastest.
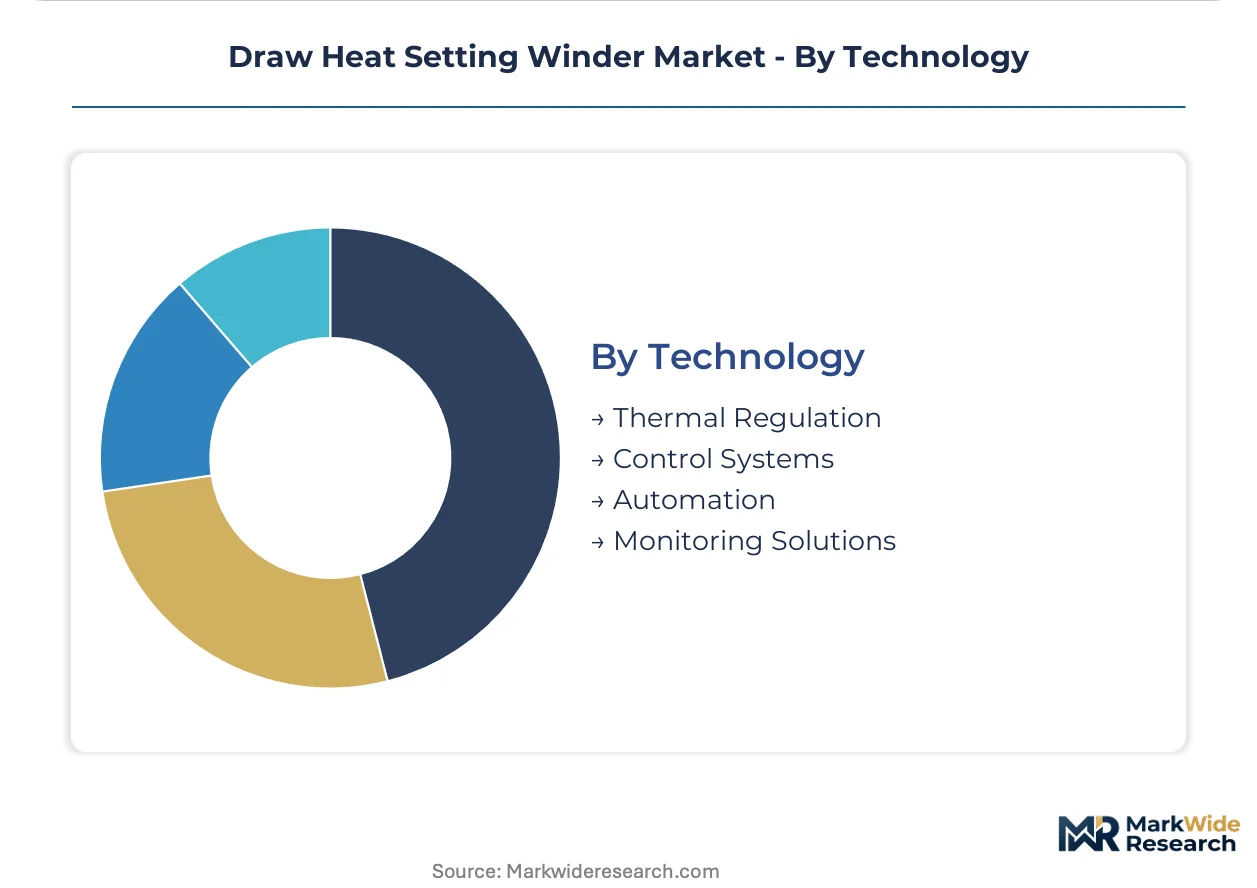
Technology:
Performance differentiation increasingly concentrates in software-defined thermal management rather than mechanical hardware.
- Thermal Regulation:Advanced PID control systems and closed-loop thermal recovery architectures responding to EU F-Gas Directive refrigerant phase-down mandates.
- Control Systems:Proprietary distributed control architectures facing integration complexity with legacy DCS installations in brownfield polyester plants.
- Automation:Robotic package handling and automatic doffing systems reducing labor dependency in Southeast Asian manufacturing hubs.
- Monitoring Solutions:Physics-based digital twin software virtualizing thermal chamber behavior ahead of physical commissioning.
Thermal Regulation retains the foundational technology position, while Monitoring Solutions adoption is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive upholstery buyers and synthetic yarn multinationals concentrate procurement leverage in manufacturing corridors where polyester industrial capacity is scaling fastest. Germany's technical textile suppliers and Vietnam's export-oriented processors anchor distinct demand archetypes. Regulatory fragmentation across REACH, BIS certification, and METI benchmarks reshapes equipment specification priorities by geography.
Germany
Automotive seating suppliers and technical belting manufacturers drive precision-grade equipment demand. ECHA's REACH authorization timelines for persistent organic pollutants force reformulation investments and accelerated equipment replacement cycles. Stuttgart and Mannheim industrial zones host Tier-1 upholstery yarn processors deploying closed-loop thermal recovery systems.
Vietnam
Polyester industrial yarn exporters serving Japanese and Korean automotive supply chains expand heat-setting capacity fastest. The country's national standards body aligns textile machinery safety protocols with ASEAN harmonization frameworks. Ho Chi Minh City manufacturing corridors attract competing service-only bids from European and Japanese OEMs for new plant builds.
China
Post-consumer rPET bottle-to-yarn lines require modified heat-setting protocols for recycled molecular structure stabilization. GB standards for textile machinery safety and MIIT energy efficiency mandates create layered compliance obligations for domestic and multinational suppliers. Zhejiang and Jiangsu province chemical fiber clusters dominate synthetic yarn output volume.
India
Technical textile producers under the PLI scheme for man-made fibers drive phased automation adoption. BIS certification requirements for imported industrial equipment open procurement channels for mid-scale hybrid system deployments. Gujarat and Tamil Nadu synthetic yarn belts concentrate draw heat setting winder installations for domestic weaving and export markets.
Japan
Premium-grade automotive upholstery yarn producers demand METI energy efficiency benchmark compliance for equipment selection. METI's industrial efficiency standards shape product development priorities for precision thermal control systems. Nagoya and Osaka manufacturing basins anchor high-tenacity fiber processing for domestic automotive and electronics applications.
Draw Heat Setting Winder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent value capture models. The vendor base separates into consolidated OEMs with end-to-end filament processing portfolios and precision-winding specialists with narrow technical depth. Three archetypes dominate: automation-integrated systems houses, thermal regulation technology specialists, and regional service infrastructure anchors. M&A activity concentrates on digital twin software capabilities, while geographic expansion targets Vietnam and India manufacturing corridors.
Among Swiss and German precision engineering houses, SSM Schärer Schweiter Mettler AG and Oerlikon Textile GmbH exemplify divergent strategic positions—one anchoring premium winding system heritage, the other representing automation-integrated line solutions. Murata Machinery, Ltd. occupies a position as the Asian service infrastructure anchor. These three illustrate how geographic origin and corporate structure shape competitive archetype representation without determining specific market outcomes.
| Leading Market Players |
|---|
| SSM Schärer Schweiter Mettler AG |
| Oerlikon Textile GmbH |
| Murata Machinery, Ltd. |
| Savio Macchine Tessili S.p.A |
| TMT Machinery, Inc. |
| Rieter Holding AG |
| Vandewiele NV |
| Superba S.p.A. |
| Peass Industrial Engineers Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Zhejiang and Jiangsu province chemical fiber clusters concentrate polyester industrial yarn capacity, granting Chinese OEM procurement teams outsized leverage in thermal chamber component negotiations. This geographic density compresses margins for European and Japanese precision engineering houses while amplifying pricing power for synthetic yarn multinationals consolidating their supplier bases.
Pricing Analysis
Cost-plus contracts with nickel alloy indexation dominate European installations, where heat-resistant chamber components from German and Japanese specialty steel suppliers command premium positioning. Pricing stratifies across fully automatic, hybrid, and semi-automatic tiers based on automation depth and REACH compliance bundling. Cost compression in mid-scale hybrid configurations is intensifying because Vietnamese textile corridor buyers unbundle aftermarket service contracts from initial equipment purchases. Tier-1 polyester producers exhibit lowest price sensitivity, while India's technical textile mid-scale adopters under PLI scheme constraints drive hardest bargain.
Supply Chain Analysis
Upstream specialty steel feedstock draws from Germany, Japan, and select Austrian metallurgical producers, with heat-resistant alloy supply concentrated among three dominant suppliers. Critical inputs span nickel-chromium heating elements, precision ceramic insulation, and proprietary PID control modules. Single-source vulnerability in induction-grade alloy supply creates exposure to export licensing delays. Distribution runs through OEM direct sales for fully automatic systems and regional machinery distributors for hybrid and semi-automatic tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin software interoperability is transforming this market toward platform economics, with physics-based thermal simulation creating winner-take-most dynamics among OEMs achieving API integration with automotive upholstery buyers' MES systems.
For Market Incumbents: Insulate premium positioning by deepening captive supply of precision thermal regulation components and accelerating digital twin SaaS revenue migration ahead of predictive analytics commoditization. SSM Schärer Schweiter Mettler AG's Swiss engineering heritage and Murata Machinery's Asian service density represent defensible moats against automation-integrated line competitors. For New Entrants and Emerging Players: Establish a beachhead in India's technical textile corridor by pursuing BIS certification pathways for hybrid draw heat setting winders under the PLI scheme for man-made fibers. Post-consumer rPET feedstock expansion creates white-space for modified heat-setting protocol specialists, with equipment-as-a-service models penetrating mid-scale processors seeking upgrade pathways without full capital commitment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal regulation software specialists over mechanical hardware commoditizers, as value migrates toward physics-based simulation and predictive maintenance algorithms. Acquisition target archetypes include digital twin software developers with automotive upholstery validation credentials and regional service infrastructure anchors in Vietnam's Ho Chi Minh City manufacturing corridor. Watch for carbon border adjustment mechanism implementation as inflection indicator reshaping total cost of ownership calculations across competing manufacturing geographies.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Software Acquisition | Physics-based thermal simulation compresses commissioning cycles for automotive upholstery qualification timelines. |
| Regional Service Infrastructure Buildout | Vietnam's Ho Chi Minh City corridor attracts competing aftermarket bids from European and Japanese OEMs. |
| Closed-Loop Thermal Recovery System Launch | EU F-Gas Directive refrigerant phase-down mandates accelerate replacement demand in European polyester plants. |
| Recycled PET Protocol Development | Post-consumer bottle-to-yarn lines require modified heat-setting for rPET molecular structure stabilization. |
| Backward Integration into Specialty Alloys | Heat-resistant chamber component supply concentration in Germany and Japan creates margin vulnerability. |
Research Methodology
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and technical textile R&D directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across synthetic yarn processing facilities with secondary validation from SEC filings of listed textile machinery manufacturers, ECHA REACH registration databases, and BIS certification records. Bottom-up equipment shipment analysis and top-down synthetic yarn capacity expansion tracking were triangulated against regional trade data.
Scenario-bracketing around EU F-Gas Directive implementation pace, Vietnam textile corridor investment cycles, and rPET feedstock adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation intensity, thermal regulation technology tier, end-use industry specification, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and greenfield capacity addition pipelines, with inputs from METI energy efficiency benchmark trajectories and India's PLI scheme disbursement schedules.
Stress conditions across specialty alloy supply disruptions, REACH authorization timeline accelerations, and induction heating substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and automotive upholstery contract migration patterns. Cross-checking against customs records for textile machinery imports and synthetic yarn producer capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Spray Washer Market
Construction Equipment
Jib Crane Market