
 Concrete Admixtures Market | 2026-2036
Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Admixtures Market Intelligence
Asset-light leasing models for chemical blending equipment is rewriting capital requirements for regional admixture suppliers. Sika AG leverages its global technical service network to sustain premium positioning across infrastructure tenders. BASF SE anchors its competitiveness through backward integration into polycarboxylate ether monomers. MBCC Group differentiates via specialized formulations for extreme-climate concreting in Middle Eastern and Nordic markets.
Concrete admixtures comprise chemical or mineral additives dosed at up to 5% by cement weight to modify rheology, setting time, or hardened properties such as compressive strength and permeability resistance. Their primary commercial purpose centers on enabling concrete placement under adverse conditions while reducing water-cement ratios and extending structural service life. Plasticizers and superplasticizers command the largest volume share as they address the dominant industry requirement for pumpable, flowable mixes in high-rise and complex-form construction. Air-entraining agents represent a concentrated margin pool due to specification-critical performance in freeze-thaw climates and their narrower qualified supplier base.
ASTM C494, EN 934, and REACH compliance collectively shape product registration costs and reformulation cycles across North American and European supply corridors. EPA effluent guidelines and OSHA crystalline silica standards further constrain manufacturing site economics and worker exposure protocols for dry powder handling. Stakeholders must monitor evolving low-carbon procurement mandates from infrastructure authorities, as embodied carbon thresholds will increasingly determine admissibility in public sector concrete specifications.
Market Dynamics
Embodied carbon thresholds in public infrastructure procurement are forcing wholesale reformulation of chemical admixtures toward low-clinker, high-supplementary-cementitious-material compatibility. This structural pressure is compressing traditional product lifecycles and redrawing competitive advantage around lifecycle assessment capabilities.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Infrastructure authorities in Germany, France, and the Netherlands now specify maximum CO2 per cubic meter of concrete, creating specification-driven demand for carbon-reducing admixtures.
- Urban transit megaprojects:Metro expansion in India, Vietnam, and Indonesia requires high-strength, pumpable concrete for deep foundation and tunnel lining applications.
- Precast manufacturing automation:Factory-controlled curing environments enable precise dosing of accelerators and retarders, expanding admixture penetration in modular construction.
Market Restraints
- Naphthalene sulfonate feedstock volatility:Crude oil derivative pricing swings compress margins for conventional superplasticizer producers without captive naphthalene supply.
- REACH registration cost concentration:Small and mid-sized European formulators face disproportionate compliance burdens relative to revenue, consolidating viable supplier bases.
- Limestone calcined clay cement substitution:LC3 blends reduce total admixture dosage requirements per cubic meter in emerging market housing applications.
Strategic Opportunities
- Carbon capture utilization in admixture chemistry:CO2-derived carbonate additives for accelerated carbonation curing represent uncommercialized white space in precast segments.
- Performance-based infrastructure procurement:Australia's shift toward durability-guarantee contracts rewards admixture suppliers with predictive service-life modeling capabilities.
- 3D concrete printing rheology:Specialized viscosity-modifying agents for layered extrusion construction open premium formulation channels in experimental building projects.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in polycarboxylate ether molecular architecture resides with a shrinking cohort of specialized practitioners approaching retirement.
- Multi-jurisdiction certification timelines:Simultaneous ASTM C494, EN 934, and BIS IS 9103 approvals extend product commercialization cycles by 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Admixtures Market |
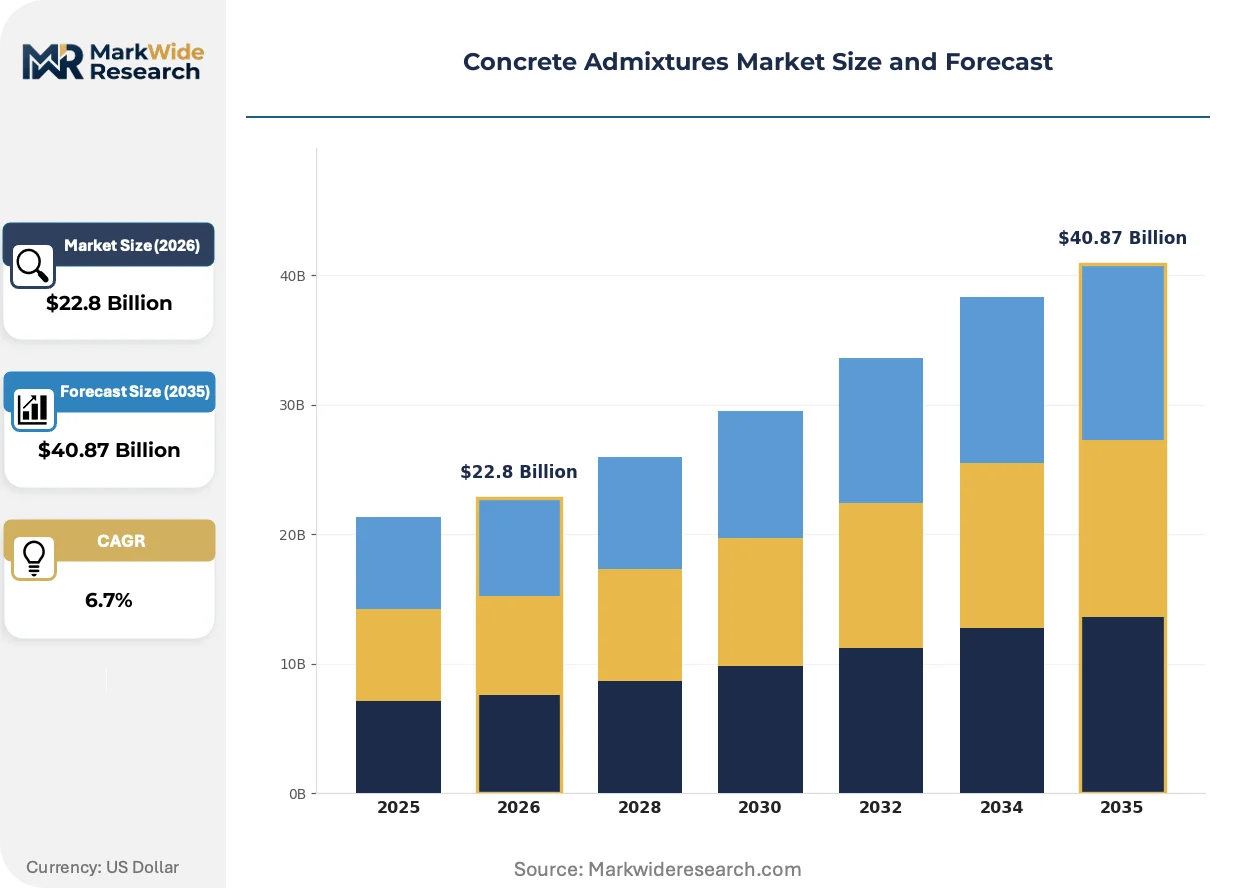
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Retarding Admixtures, Accelerating Admixtures, Air-Entraining Agents Technology: Nanotechnology, Superplasticizers, Micro-silica, Fiber Reinforcement Application: Commercial Construction, Residential Construction, Industrial Applications, Infrastructure Projects End User: Contractors, Builders, Architects, Construction Companies |
| Companies Covered | Sika AG, BASF SE, GCP Applied Technologies Inc., Fosroc, Inc., Mapei SpA, RPM International, Inc., CHYRSO SAS, MBCC Group, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Admixtures Market Strategic Shifts & Innovations
Active reformulation around decarbonization targets is collapsing traditional product category boundaries, with rheology modifiers, shrinkage reducers, and corrosion inhibitors converging into integrated performance systems. This convergence demands new technical service capabilities and redraws R&D investment priorities.
Biopolymer-based superplasticizers synthesized from agricultural lignin waste streams are collapsing the cost-performance tradeoff that historically favored petroleum-derived polycarboxylate ethers. Precast manufacturers in Scandinavia and the Netherlands are piloting these formulations at commercial scale. The structural consequence is compressing acceptable premium pricing for conventional synthetic chemistries.
REACH authorization requirements for crystalline silica in dry powder admixtures are forcing manufacturing site reconfigurations across European supply corridors. Wet-slurry delivery systems and liquid-only product portfolios are displacing traditional bagged formulations. Dry powder handling equipment investments now concentrate in Middle Eastern and Southeast Asian production facilities outside EU jurisdiction.
Buyers in high-rise residential construction are unbundling technical service from product supply, engaging independent concrete consultants for mix optimization rather than relying on admixture vendor field support. This disintermediation is most visible in China's tier-one cities, where developer procurement departments now specify performance parameters and source chemicals through distributor channels at arm's length from formulation expertise.
Concrete Admixtures Market Segmentation
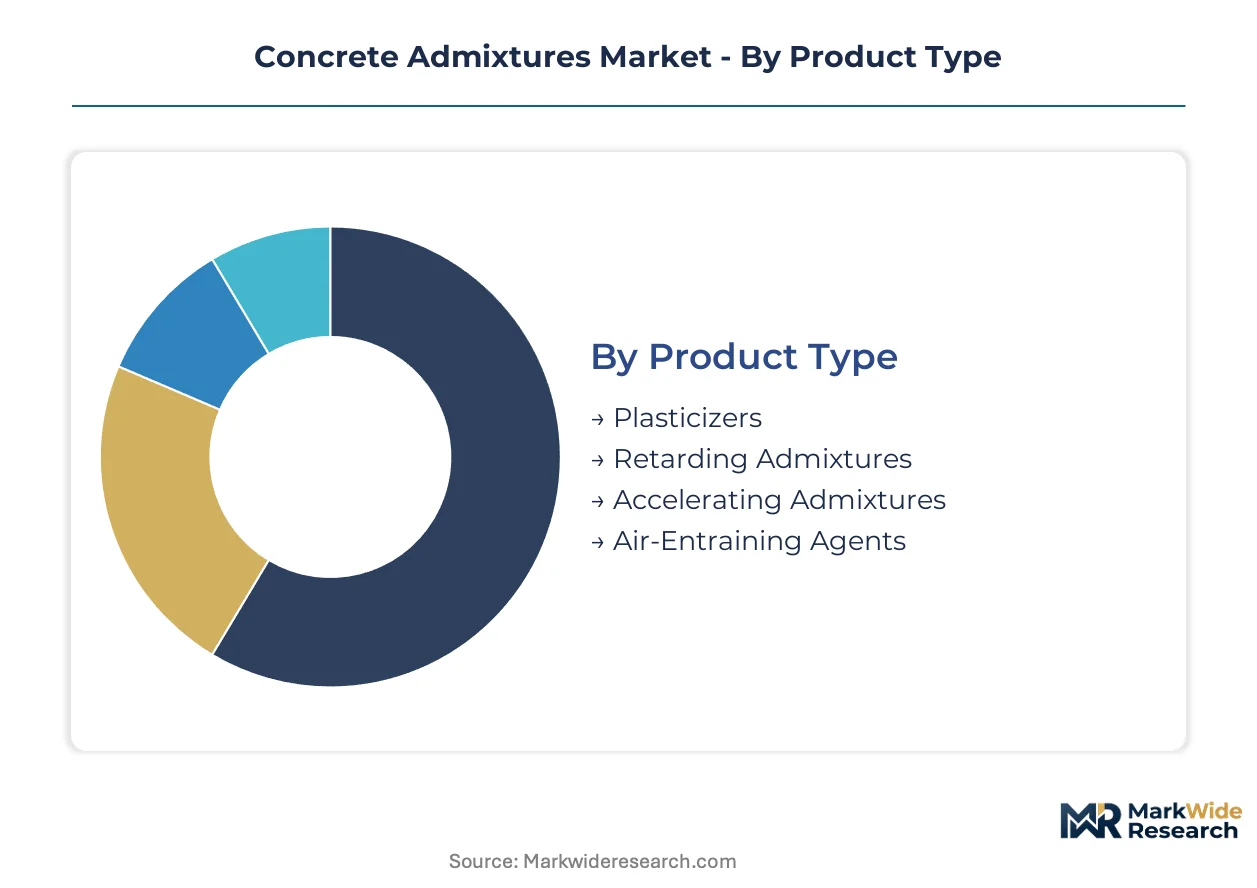
Segmentation in concrete admixtures reveals divergent margin profiles and specification intensity across chemical families, with procurement cycles stretching from spot-market plasticizer purchases to multi-year framework agreements for integrated performance systems. Understanding these structural divides enables suppliers to align R&D portfolios with the highest-velocity revenue pools.
Product Type:
Plasticizers turn over fastest through distributor channels serving ready-mix plants, while air-entraining agents move slowest due to narrow qualified supplier bases and specification lock-in for freeze-thaw durability.
- Plasticizers:Lignosulfonate and polycarboxylate ether formulations reduce water-cement ratios for pumpable, flowable mixes. Demand concentrates in India's urban transit megaprojects and Vietnam's high-rise residential towers, driven by specification requirements for high-strength concrete in deep foundation work.
- Air-Entraining Agents:Vinsol resin and synthetic surfactant formulations entrain microscopic air voids for freeze-thaw resistance. Procurement clusters in Germany, the Netherlands, and Nordic markets where EU Green Deal embodied carbon mandates intersect with harsh winter exposure requirements.
- Retarding Admixtures:Hydroxycarboxylic acid and lignosulfonate blends delay setting in hot-weather pours and long-haul transit.
- Accelerating Admixtures:Calcium chloride and non-chloride formulations speed early strength development for precast manufacturing and cold-weather construction.
Plasticizers anchors the volume base while air-entraining agents gains share at the steepest rate.
Technology:
Cost tiers separate commodity superplasticizers from premium nanotechnology platforms, with the latter commanding fivefold price multiples for specialized infrastructure applications.
- Superplasticizers:Polycarboxylate ether and naphthalene sulfonate chemistries dominate high-performance concrete specifications. India's metro expansion and Indonesia's toll road programs drive specification intensity, constrained by naphthalene feedstock volatility from crude oil derivative markets.
- Nanotechnology:Nano-silica and nano-titania dispersions enhance densification and self-cleaning surfaces. Adoption clusters in experimental 3D concrete printing projects across Australia's performance-based procurement environment and Dutch precast innovation hubs.
- Micro-silica:Condensed silica fume improves compressive strength and abrasion resistance in marine and industrial exposures.
- Fiber Reinforcement:Steel, synthetic, and glass macro-fibers control plastic and hardened shrinkage cracking.
Superplasticizers command the revenue concentration while nanotechnology expands most quickly in premium formulation channels.
Application:
Volume concentration follows public infrastructure procurement cycles, with commercial construction running shortest tender timelines and infrastructure projects stretching across multi-year political horizons.
- Infrastructure Projects:Bridge, tunnel, dam, and transit applications demand integrated admixture systems for extreme exposure conditions. Germany's Federal Transport Infrastructure Plan and India's National Infrastructure Pipeline anchor specification-driven demand for durability-guarantee formulations.
- Commercial Construction:High-rise offices and retail complexes prioritize pumpability and finish quality for architectural concrete. China's tier-one cities exhibit unbundling trends where developers source chemicals through distributor channels independent of vendor technical service.
- Residential Construction:Single-family and multi-family housing applications emphasize cost-efficient water reducers for slab and foundation work.
- Industrial Applications:Manufacturing floors, warehouses, and process facilities require abrasion-resistant and chemically resistant concrete systems.
Infrastructure Projects anchors the specification premium while Commercial Construction delivers the highest transaction velocity.
End User:
Customer type determines technical service intensity, with architects influencing specifications upstream and contractors executing procurement downstream with divergent margin capture.
- Construction Companies:Large integrated contractors and specialty concrete firms drive volume through centralized procurement and captive batching operations. Sika AG and BASF SE compete for framework agreements in Germany and France where EU Green Deal compliance requirements filter supplier qualification.
- Architects:Design professionals specify performance parameters for exposed architectural concrete and sustainable building certifications. Influence concentrates in Netherlands and Scandinavian markets where biopolymer-based superplasticizers gain specification traction.
- Contractors:General and specialty trade contractors execute spot-market purchases for project-specific requirements.
- Builders:Residential and small commercial developers prioritize cost-optimized formulations through distributor relationships.
Construction Companies anchors the volume base while Architects exerts expanding influence over premium specification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in concrete admixtures concentrate chemical blending capacity near limestone reserves and major construction corridors, with formulation expertise migrating toward markets with stringent embodied carbon regulations.
Germany
Federal Transport Infrastructure Plan tenders drive specification intensity for durability-guarantee admixtures in bridge and tunnel applications. EU Green Deal mandates through the Federal Ministry for Digital and Transport enforce maximum CO2 per cubic meter thresholds. Industrial clusters along the Rhine-Ruhr corridor anchor polycarboxylate ether production for export into Benelux markets.
India
National Infrastructure Pipeline metro expansions in Mumbai, Delhi, and Bengaluru require high-strength pumpable concrete for deep foundation work. BIS IS 9103 compliance timelines extend product registration cycles for international suppliers entering the market. Gujarat and Maharashtra host specialty chemical manufacturing zones serving affordable housing programs across western states.
United States
EPA effluent guidelines constrain dry powder manufacturing economics, accelerating wet-slurry delivery system adoption. Infrastructure Investment and Jobs Act disbursements prioritize low-carbon concrete specifications for federal bridge and highway rehabilitation. Texas and California concrete corridors concentrate ready-mix demand for plasticizer and superplasticizer formulations.
China
Tier-one city developers unbundle technical service from product supply, sourcing chemicals through distributor channels independent of vendor field support. GB standards and dual carbon goals under MEE oversight reshape formulation requirements for high-rise residential construction. Yangtze River Delta precast manufacturing hubs pilot automated dosing systems for accelerator and retarder integration.
Netherlands
Biopolymer-based superplasticizers synthesized from agricultural lignin waste streams gain specification traction among architects pursuing sustainable building certifications. REACH authorization requirements for crystalline silica force manufacturing site reconfigurations toward liquid-only portfolios. Rotterdam-Amsterdam logistics corridors facilitate wet-slurry distribution into German and Belgian construction markets.
Concrete Admixtures Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on feedstock and monomer supply. The vendor base organizes around three strata: multinational chemical conglomerates with backward integration into polycarboxylate ether monomers, regional formulators leasing asset-light blending equipment, and niche specialists targeting extreme-climate performance guarantees. Consolidation pressure concentrates among European mid-cap formulators facing disproportionate REACH registration burdens relative to revenue. Dominant competitive moves include captive supply chain integration and framework agreement positioning for infrastructure procurement cycles.
Among Swiss-German chemical conglomerates, Sika AG and BASF SE occupy positions as platform integrators leveraging global technical service networks. MBCC Group exemplifies the specialized-formulation archetype targeting climate-specific performance requirements. These three anchors illustrate how competitive advantage redistributes between scale-driven system provision and targeted expertise in specification-intensive segments.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| GCP Applied Technologies Inc. |
| Fosroc, Inc. |
| Mapei SpA |
| RPM International, Inc. |
| CHYRSO SAS |
| MBCC Group |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Polycarboxylate ether monomer production concentrates in Germany and China, anchoring margin capture for backward-integrated suppliers while forcing independent formulators into price-taker positions on commodity plasticizers. This upstream concentration funnels pricing power toward chemical conglomerates with captive monomer supply, compressing returns for asset-light regional blenders dependent on spot-market feedstock procurement.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade—REACH-compliant formulations command substantial premia over baseline ASTM C494 products—and volume scale, with megaproject offtakes securing double-digit discounts. Cost compression in conventional superplasticizers is intensifying because biopolymer alternatives from agricultural lignin waste streams are collapsing acceptable premium pricing for petroleum-derived chemistries. Ready-mix plants and small contractors exhibit acute price sensitivity, while infrastructure authorities with durability-guarantee specifications demonstrate minimal elasticity.
Supply Chain Analysis
Naphthalene sulfonate feedstock draws from crude oil derivative markets, tethering conventional superplasticizer economics to petrochemical volatility. Manufacturing concentrates in Germany, China, and India, with formulation expertise migrating toward EU jurisdictions with stringent embodied carbon regulations. Single-source vulnerability concentrates in polycarboxylate ether monomer supply, where three chemical conglomerates control capacity expansion timelines. Distribution runs through wet-slurry delivery systems displacing traditional bagged formulations, particularly across European supply corridors where REACH crystalline silica restrictions apply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Concrete admixtures sit in early-cycle expansion as embodied carbon mandates force wholesale reformulation across infrastructure procurement, accelerating penetration of low-clinker-compatible performance systems.
For Market Incumbents: Insulate specification lock-in by deepening technical service capabilities for lifecycle assessment modeling, while securing captive supply of polycarboxylate ether monomers to defend against biopolymer substitution threats. Prioritize framework agreement positioning for EU Green Deal-compliant infrastructure tenders in Germany and the Netherlands, where procurement authorities filter supplier qualification through CO2 per cubic meter thresholds. For New Entrants and Emerging Players: Asset-light leasing models for chemical blending equipment in Southeast Asia represent the most penetrable entry point, bypassing capital barriers that constrain regional formulators. Carbon capture utilization for accelerated carbonation curing in precast segments offers uncrowded white space, with pilot-scale validation through Dutch and Scandinavian manufacturing hubs providing credibility for specification pursuit. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European mid-cap formulators facing disproportionate REACH registration burdens relative to revenue. Long-term viability across a 5-10 year window favors targets with demonstrated low-clinker admixture compatibility and installed base in infrastructure procurement corridors. Watch for biopolymer superplasticizer specification traction among Netherlands architects as inflection signal for conventional chemistry displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomers | Captive polycarboxylate ether supply insulates margin compression from naphthalene feedstock volatility. |
| Biopolymer Formulation Development | Agricultural lignin-derived superplasticizers collapse cost-performance tradeoffs favoring petroleum chemistries. |
| Wet-Slurry Manufacturing Transition | Liquid-only portfolios circumvent REACH crystalline silica authorization requirements constraining dry powder handling. |
| Lifecycle Assessment Capability Buildout | Predictive service-life modeling secures positioning for Australia's durability-guarantee procurement contracts. |
| Asset-Light Regional Blending Expansion | Leased equipment models reduce capital requirements for Southeast Asia infrastructure megaproject participation. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with admixture formulators, infrastructure procurement officers, ready-mix plant managers, and technical service directors; and secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and BIS IS 9103 registration databases. Bottom-up volume modeling across product type, technology tier, application segment, and end-user category triangulated against top-down market sizing from construction expenditure flows and cement consumption patterns.
Forecast inputs considered polycarboxylate ether penetration rates, biopolymer substitution velocity, EU Green Deal implementation timelines, and infrastructure disbursement cycles across the analysis window. Segmentation dimensions modeled include chemical family, performance tier, project scale, and regional regulatory cluster. CAGRs derived from regression analysis of historical admixture intensity per cubic meter against projected concrete volumes, with scenario weighting for LC3 cement substitution effects and precast manufacturing automation adoption.
Practitioners should monitor feedstock price volatility, REACH authorization scope expansion, and biopolymer specification traction for early signals of forecast revision. Quarterly review of infrastructure procurement tender awards, embodied carbon threshold adjustments, and formulation chemist labor market tightness is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Construction Coatings Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Engineered Wood Product Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Bolt (Fastener) Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Plaster Accelerator Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Steel Sleepers Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Sanded Grout Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Low-E Construction Glass Market
Building Materials
Cellular Concrete Market